
 Direct-Skin Wearable Medical Devices Market | 2026-2036
Direct-Skin Wearable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Direct-Skin Wearable Medical Devices Market Analysis
Buyer concentration among hospital procurement departments is restructuring how direct-skin wearable vendors secure long-term contracts. Abbott Laboratories anchors its position through captive manufacturing of glucose-sensing filaments. Dexcom, Inc. differentiates via vertical control over transmitter assembly and algorithm development. Medtronic competes through integrated insulin delivery systems that pair skin-worn sensors with automated dosing hardware.
Direct-skin wearable medical devices attach directly to epidermal tissue via biocompatible adhesives, incorporating electrochemical or optical sensors that transcutaneously detect biomarkers such as glucose, lactate, or cortisol at sampling intervals under fifteen minutes. These systems serve chronic disease management by replacing intermittent fingerstick measurements with automated, continuous physiological surveillance. Monitoring Devices command the largest revenue pool due to recurring sensor replacement cycles, while Smart Patches represent the fastest-expanding category as micro-needle array designs reduce skin irritation and extend wear duration beyond fourteen days. Bluetooth-enabled units dominate connectivity architecture, though NFC is gaining share in clinical settings where paired smartphone ownership cannot be assumed.
The FDA breakthrough device program and EMA adaptive pathways both compress premarket review timelines for novel skin-interface biosensors, directly shaping competitive speed-to-market. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards form mandatory gatekeeping layers that filter out undercapitalized entrants lacking dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving CMS reimbursement decisions and equivalent national health technology assessment processes, as payment policy changes will determine which sensor modalities achieve profitable scale.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while demanding longer sensor wear times and integrated data platforms from direct-skin wearable suppliers.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare remote patient monitoring codes now cover continuous glucose monitoring for type 2 diabetes patients, expanding addressable populations beyond insulin-dependent users.
- Micro-needle Array Advancement:Solid-state microneedle designs reduce dermal irritation and enable lactate and cortisol sensing alongside glucose, opening multi-analyte diagnostic applications.
- United States Demand Concentration:American health systems lead adoption of Bluetooth-enabled continuous monitoring for post-surgical recovery and chronic heart failure management.
Market Restraints
- Filament Supply Concentration:Glucose-oxidase enzyme production concentrates among three specialty chemical suppliers, creating input vulnerability for sensor manufacturers.
- Biocompatibility Testing Burden:ISO 10993 cytotoxicity and sensitization studies require 18-24 month validation timelines that filter out undercapitalized entrants.
- Intermittent Fingerstick Substitution:Non-invasive optical glucose monitors under development threaten electrochemical sensor incumbents if clinical accuracy thresholds are achieved.
Strategic Opportunities
- Japan's Aging Demographics:METI funding for preventive health technologies creates procurement channels for fourteen-day wear patches in rural eldercare facilities.
- EMA Adaptive Pathways:Conditional approval mechanisms for breakthrough skin-interface biosensors accelerate European commercialization ahead of full PMA equivalents.
- Pharmacy Distribution Integration:CVS and Walgreens pilot direct-to-patient sensor fulfillment models that bypass traditional durable medical equipment channels.
Industry Challenges
- Algorithm Validation Talent Scarcity:Machine learning engineers with FDA software-as-medical-device experience command premium compensation that strains mid-tier vendor R&D budgets.
- Legacy EHR Integration Complexity:Epic and Cerner interoperability requirements force sensor vendors to maintain multiple API configurations, increasing technical debt.
- Cleanroom Manufacturing Capex:ISO 14644 Class 7 production facilities for adhesive lamination and sensor printing require capital commitments exceeding manufacturing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct-Skin Wearable Medical Devices Market |
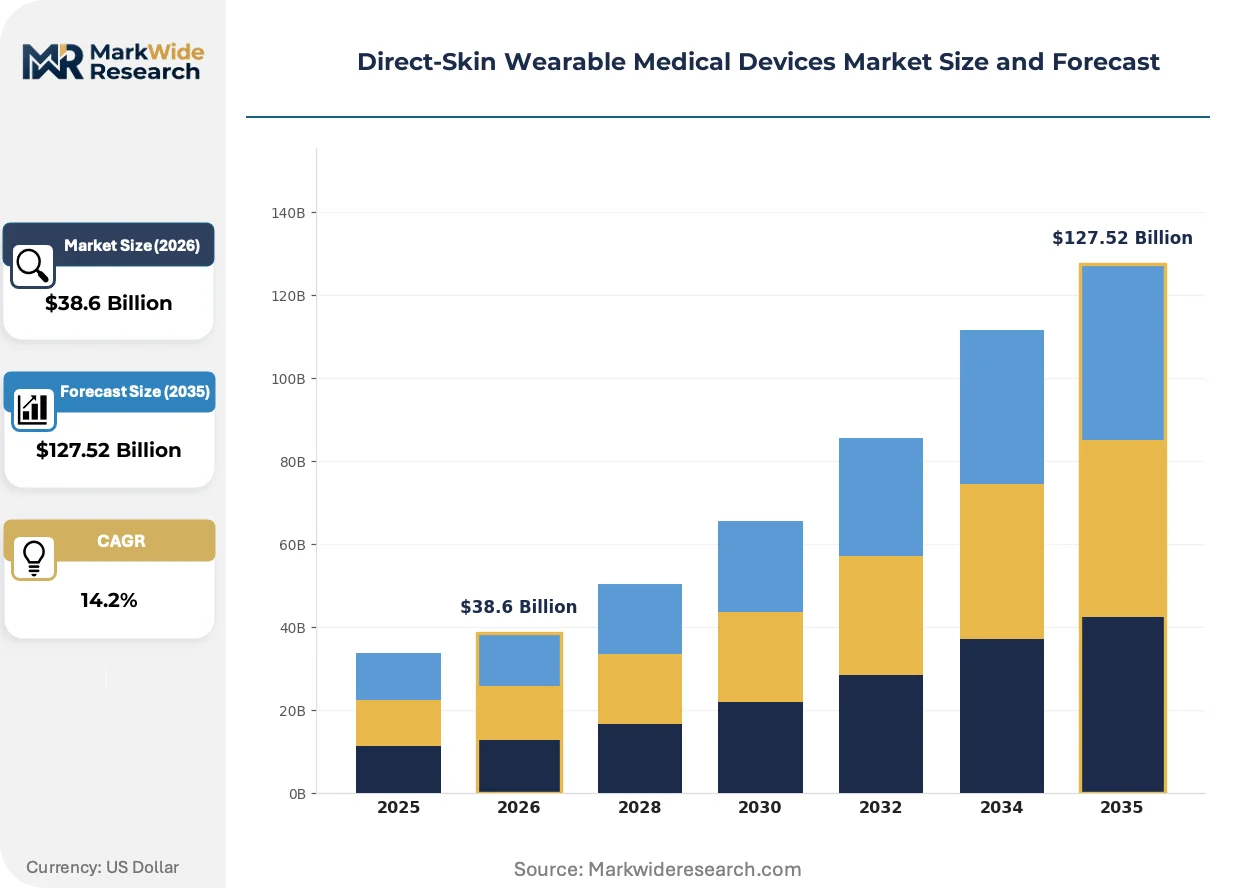
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Devices, Therapeutic Devices, Diagnostic Devices, Smart Patches Technology: Bluetooth, NFC, RFID, Ultrasonic End User: Healthcare Professionals, Patients, Researchers, Fitness Enthusiasts Application: Chronic Disease Management, Fitness Tracking, Health Monitoring, Postoperative Care |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Abbott Laboratories, Dexcom, Inc., Garmin Ltd., Koninklijke Philips N.V., Medtronic, OMRON Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct-Skin Wearable Medical Devices Market Emerging Trajectories
Convergence between materials science and digital health infrastructure is redefining performance benchmarks for epidermal monitoring systems.
Hybrid electrochemical-optical sensing architectures are unifying glucose and blood pressure measurement into single patch formats. Cardiology departments at Cleveland Clinic and Mayo Clinic pilot these dual-parameter systems for post-discharge monitoring. The convergence is compressing device count per patient and reducing skin adhesion failure rates from multiple overlapping wearables.
FDA breakthrough device designation pathways now process skin-adhesive biosensor submissions under compressed 180-day review targets. The FDA's Digital Health Center of Excellence issues pre-submission guidance that reduces regulatory uncertainty for algorithm-driven diagnostic outputs. Sensor vendors with predicate device clearance experience leverage this pathway to outpace de novo applicants by 12-18 months.
Hospital procurement departments now bundle sensor contracts with analytics platform subscriptions, displacing standalone device purchasing. Integrated delivery networks in Texas and California negotiate multi-year agreements that tie sensor pricing to patient outcome metrics. This model concentrates purchasing power among systems with sufficient scale to measure population-level clinical returns.
Direct-Skin Wearable Medical Devices Market Segmentation
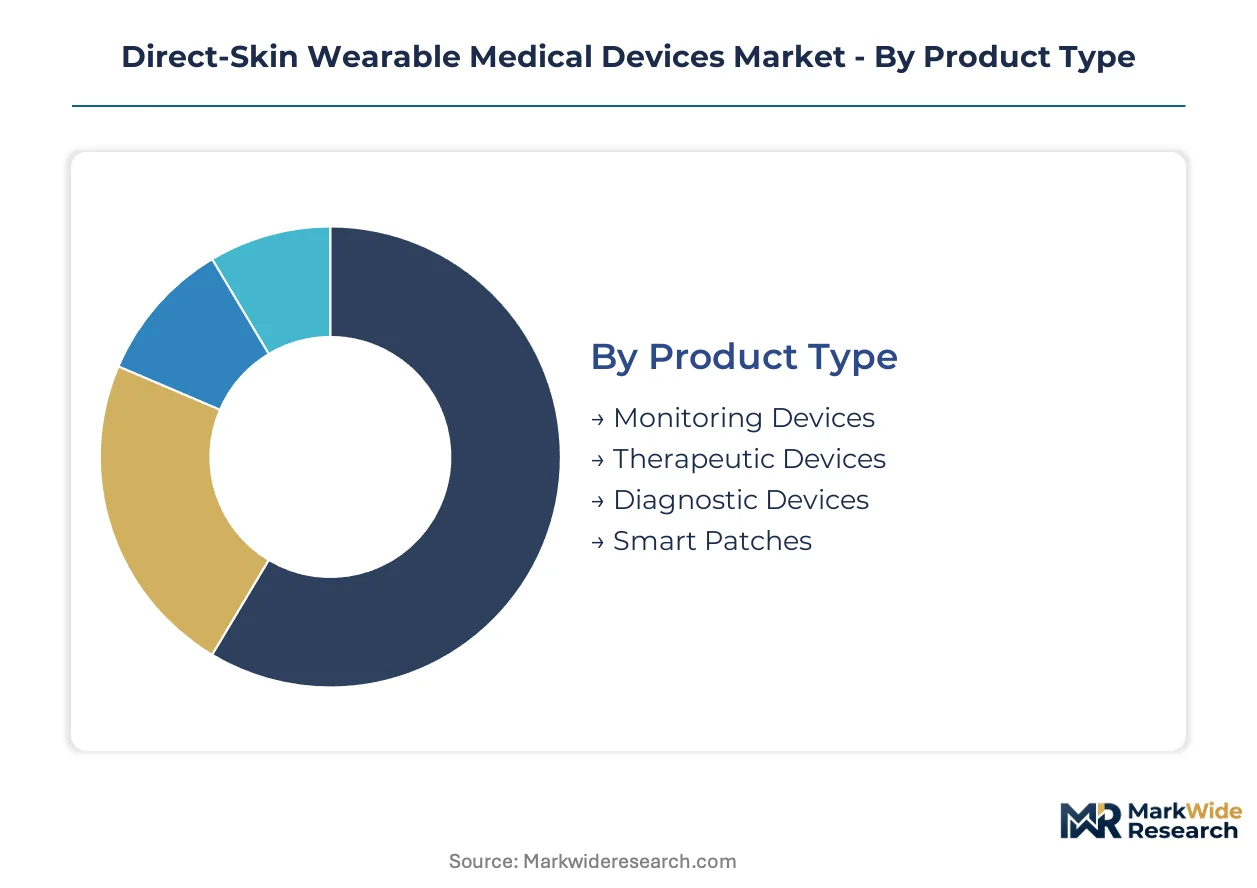
Direct-skin wearable medical devices fragment across four critical dimensions that determine regulatory pathway complexity, reimbursement eligibility, and manufacturing scale requirements. Product type classification dictates whether FDA 510(k) clearance or PMA submission applies, while technology choice shapes interoperability mandates and battery life specifications.
Product Type:
ISO 10993 biocompatibility testing intensity varies sharply across this category, with implantable-adjacent segments requiring extended cytotoxicity validation while surface-adherent formats face abbreviated pathways.
- Monitoring Devices:Electrochemical sensor assemblies with glucose-oxidase or lactate-responsive filaments that transcutaneously sample interstitial fluid at sub-fifteen-minute intervals. Hospital procurement departments in the United States concentrate purchasing power here, driven by Medicare remote patient monitoring reimbursement expansion for type 2 diabetes populations.
- Smart Patches:Solid-state micro-needle arrays that reduce dermal irritation and extend wear duration beyond fourteen days through biomimetic adhesive formulations. Japanese eldercare facilities under METI preventive health funding programs represent the fastest-expanding demand node for multi-analyte diagnostic formats.
- Therapeutic Devices:Transdermal drug delivery systems with iontophoretic or microneedle actuation mechanisms for hormone or vaccine administration.
- Diagnostic Devices:Single-use biosensor platforms for point-of-care infectious disease detection or cardiac biomarker quantification.
Leading the category by volume: Monitoring Devices. Growing fastest: Smart Patches.
Technology:
Connectivity architecture selection determines FCC certification requirements in the United States and CE-RED compliance obligations in Europe, with power consumption profiles directly constraining sensor form factor miniaturization.
- Bluetooth:Dominant radio protocol enabling continuous data streaming to paired smartphones or hospital gateway systems, with BLE 5.0 specifications supporting multi-year battery life in compact transmitter housings. American post-surgical recovery programs and chronic heart failure management protocols anchor demand concentration.
- NFC:Near-field communication for clinical settings where smartphone ownership cannot be assumed, requiring proximity activation but eliminating pairing complexity. European hospital systems adopting EMA adaptive pathway approvals favor this architecture for conditional deployment scenarios.
- RFID:Passive backscatter identification for inventory tracking and patient-matching workflows rather than continuous physiological streaming.
- Ultrasonic:Emerging acoustic transmission through tissue for implantable-adjacent sensing where electromagnetic interference must be eliminated.
Widest installed base: Bluetooth. Steepest expansion trajectory: NFC.
End User:
User category determines clinical evidence requirements, with professional-facing segments demanding randomized controlled trial data while direct-to-consumer formats navigate FTC advertising scrutiny.
- Healthcare Professionals:Hospital systems and physician practices requiring Epic or Cerner EHR interoperability, ISO 27001 data security compliance, and liability indemnification structures. Integrated delivery networks in Texas and California negotiate outcome-tied multi-year contracts.
- Patients:Direct-to-consumer channels through CVS and Walgreens pilot fulfillment models that bypass traditional durable medical equipment distribution, contingent on simplified onboarding interfaces.
- Researchers:Academic medical centers and contract research organizations requiring raw data export capabilities and protocol customization for clinical trial endpoints.
- Fitness Enthusiasts:Wellness-oriented consumers prioritizing aesthetic discretion and social sharing integration over clinical-grade accuracy validation.
Primary revenue source: Healthcare Professionals. Gaining share fastest: Patients.
Application:
Application segmentation aligns with reimbursement code availability and prescriber specialty concentration, determining sales force deployment and key opinion leader engagement strategies.
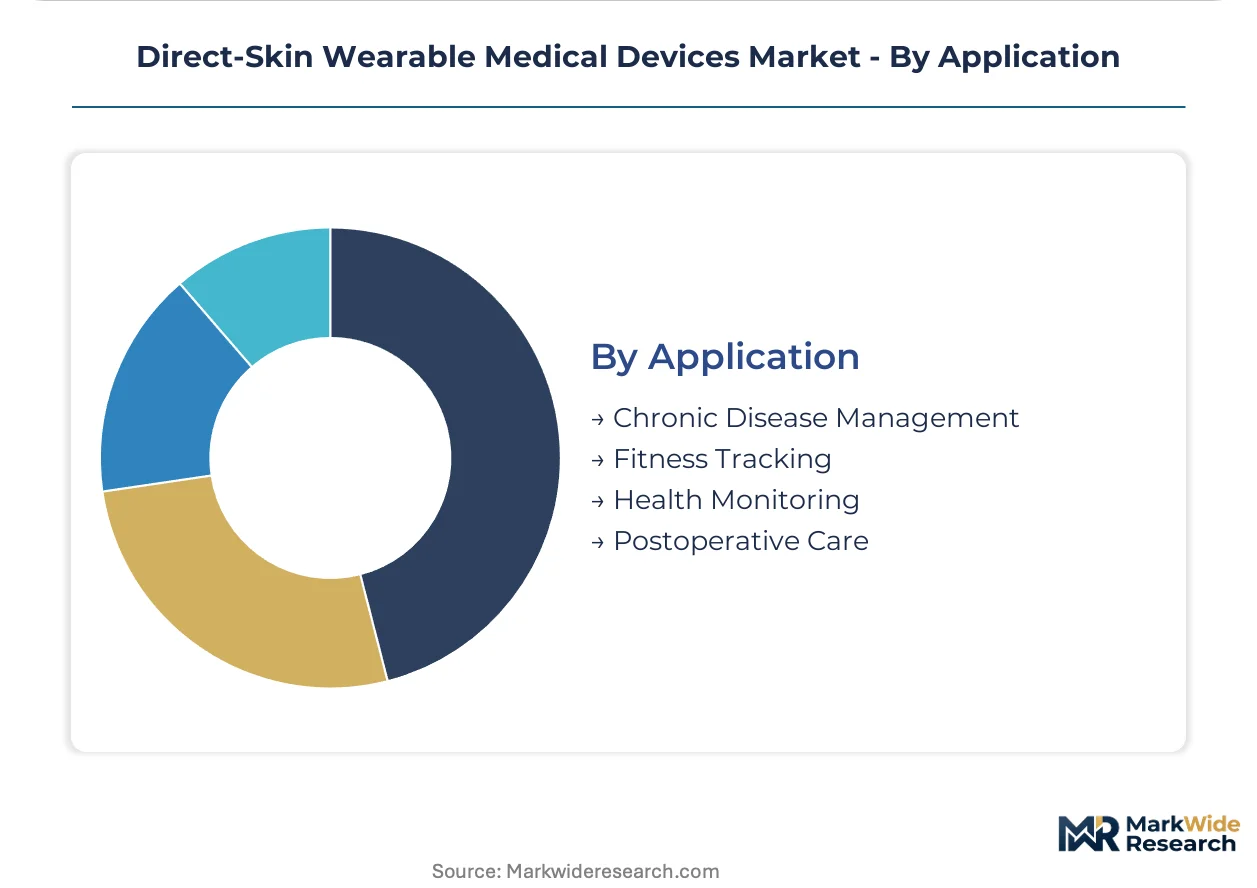
- Chronic Disease Management:Continuous glucose monitoring for diabetes, cardiac rhythm surveillance for arrhythmia patients, and respiratory tracking for COPD populations. CMS reimbursement code expansion for remote patient monitoring drives United States demand concentration.
- Postoperative Care:Wound healing monitoring, infection biomarker detection, and early mobility tracking for orthopedic and cardiac surgery recovery. Cleveland Clinic and Mayo Clinic pilot programs validate dual-parameter patch architectures.
- Fitness Tracking:Lactate threshold estimation, hydration status monitoring, and recovery metric quantification for athletic performance optimization.
- Health Monitoring:General wellness surveillance including sleep staging, stress hormone estimation, and circadian rhythm mapping without disease-specific diagnostic claims.
Dominant application by revenue: Chronic Disease Management. Expanding most quickly: Postoperative Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glucose-oxidase enzyme production concentrates in Germany, Japan, and the United States, anchoring regional manufacturing capabilities for electrochemical sensor filaments. These feedstock localities shape procurement patterns and regulatory alignment across major demand centers.
United States
Medicare remote patient monitoring reimbursement expansion drives hospital procurement consolidation around continuous glucose monitoring platforms. FDA breakthrough device designation pathways compress premarket review timelines for skin-adhesive biosensors. Texas and California integrated delivery networks negotiate multi-year outcome-tied contracts for sensor-analytics bundles.
Germany
EMA adaptive pathways accelerate European commercialization of novel skin-interface biosensors ahead of full PMA equivalents. ISO 10993 biocompatibility testing infrastructure concentrates in Baden-Württemberg and Bavaria medical technology clusters. Stuttgart-based specialty chemical suppliers dominate glucose-oxidase enzyme production for sensor manufacturers.
Japan
METI preventive health technology funding creates procurement channels for fourteen-day wear patches in rural eldercare facilities. PMDA streamlined review processes align with global harmonization initiatives for wearable medical devices. Kanto region medical device manufacturers lead solid-state micro-needle array development for multi-analyte sensing.
China
NMPA innovative medical device approval pathways reduce time-to-market for domestic skin-worn biosensor developers. Yangtze River Delta electronics manufacturing ecosystems support Bluetooth-enabled transmitter assembly at scale. Shanghai-based cleanroom facilities achieve ISO 14644 Class 7 certification for adhesive lamination operations.
Switzerland
Swissmedic expedited access pathways attract sensor developers seeking European market entry ahead of EMA centralized procedures. Basel pharmaceutical technology clusters facilitate partnerships between adhesive formulation specialists and diagnostic platform developers. Zurich-based precision manufacturing infrastructure supports miniaturized electrochemical sensor production.
Direct-Skin Wearable Medical Devices Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue algorithm-driven diagnostic differentiation and multi-analyte sensing architectures. Market structure consolidates around three strategic archetypes: diversified health technology conglomerates with captive sensor manufacturing, pure-play continuous monitoring specialists with vertical control over transmitter assembly, and integrated insulin delivery system providers pairing skin-worn sensors with automated dosing hardware. Dominant competitive moves include strategic partnerships with pharmacy distribution networks and backward integration into glucose-oxidase enzyme supply.
Within the diversified technology tier, Apple Inc. and Samsung Electronics Co., Ltd. exemplify consumer electronics originators extending wearable platforms into regulated health monitoring applications. Among dedicated medical device specialists, Abbott Laboratories, Dexcom, Inc., and Medtronic occupy positions defined by distinct supply chain configurations: captive filament manufacturing, vertical transmitter control, and integrated delivery systems respectively. These three anchors represent alternative strategic pathways for securing procurement relationships with consolidating hospital systems.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Abbott Laboratories |
| Dexcom, Inc. |
| Garmin Ltd. |
| Koninklijke Philips N.V. |
| Medtronic |
| OMRON Corporation |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation around multi-year sensor-analytics bundles is forcing vendors to absorb warranty and algorithm update costs previously unbundled, compressing margins and accelerating captive production investments in glucose-oxidase enzyme supply.
Pricing Analysis
Extended warranty coverage and predictive algorithm subscriptions now bundle into sensor pricing rather than standing as separate line items. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated devices from 510(k) equivalents and unbranded white-label alternatives. Pricing pressure stems from integrated delivery networks demanding outcome-tied discounts that tie sensor reimbursement to patient glucose time-in-range metrics. Pharmacy distribution channels exhibit highest price sensitivity as CVS and Walgreens fulfillment models compete on patient out-of-pocket costs, while hospital systems with dedicated biomedical engineering staff tolerate premium tiering for EHR-integrated platforms.
Supply Chain Analysis
ISO 10993 biocompatibility certification and FDA Quality System Regulation compliance create gating barriers that filter out contract manufacturers lacking dedicated regulatory affairs infrastructure. Glucose-oxidase enzyme production concentrates in Germany, Japan, and the United States, with Stuttgart-based specialty chemical suppliers and Kanto region fermentation facilities anchoring filament feedstock. Solid-state micro-needle arrays and biocompatible adhesive formulations draw from precision polymer suppliers in Switzerland and precision electronics manufacturers in the Yangtze River Delta. Single-source vulnerability concentrates in enzyme production, where three specialty chemical suppliers serve the entire electrochemical sensor industry. Distribution runs through durable medical equipment channels, pharmacy fulfillment pilots, and direct hospital procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation is accelerating market concentration as undercapitalized entrants lacking ISO 10993 testing infrastructure and predicate device clearance experience exit under margin pressure.
For Market Incumbents: Extend sensor wear duration beyond fourteen days through solid-state micro-needle advancement to defend against intermittent fingerstick substitution threats from optical glucose monitors. Deepen backward integration into glucose-oxidase enzyme production to secure input supply against specialty chemical supplier concentration. Lock in multi-year outcome-tied contracts with Texas and California integrated delivery networks before pharmacy distribution channels commoditize sensor fulfillment. For New Entrants and Emerging Players: Pharmacy distribution partners represent the most penetrable channel for bypassing hospital procurement consolidation, particularly in direct-to-consumer fulfillment models that simplify patient onboarding interfaces. Target Japanese rural eldercare facilities under METI preventive health funding programs, where fourteen-day wear multi-analyte patches face limited incumbent penetration. Pursue EMA adaptive pathway conditional approvals to accelerate European commercialization ahead of full PMA timelines. For Investors and Strategic Acquirers: The window for entry favors algorithm-driven diagnostic specialists with FDA software-as-medical-device experience and multi-analyte sensing architectures. Long-term viability hinges on acquisition targets possessing captive biocompatibility testing infrastructure and predicate device clearance pathways that compress regulatory timelines. Watch for CMS reimbursement code expansion for non-glucose biomarkers as the inflection signal for platform diversification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery networks in Texas and California consolidate vendor relationships around outcome-tied sensor-analytics bundles. |
| FDA Breakthrough Device Pathway | Compressed 180-day review targets accelerate clearance timelines for skin-adhesive biosensors with predicate device experience. |
| Backward Integration into Enzyme Supply | Captive glucose-oxidase production mitigates input vulnerability from three-supplier concentration in specialty chemical markets. |
| Software Companion Development | Epic and Cerner EHR interoperability requirements force maintenance of multiple API configurations, increasing technical debt for algorithm platforms. |
| Reimbursement Strategy | CMS remote patient monitoring code expansion for type 2 diabetes populations broadens addressable market beyond insulin-dependent users. |
Methodological Framework
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads combined with secondary validation from FDA 510(k) and PMA submissions, EMA adaptive pathway approvals, and ISO 10993 biocompatibility testing records. Bottom-up sensor shipment estimates triangulated against top-down Medicare remote patient monitoring claims data across the analysis window.
Rate-of-change decomposition separates volume expansion from price trajectory across product type, technology architecture, end user category, and application segmentation. CAGRs derived from logistic adoption curves fitted to historical glucose monitoring penetration patterns and projected forward across the modeling period. Forecast inputs incorporate METI preventive health funding allocations, EMA conditional approval timelines, and pharmacy distribution pilot expansion rates.
Caveats apply where FDA software-as-medical-device guidance revisions or CMS reimbursement code modifications could materially shift the outlook. Forecasts reflect assumptions regarding biocompatibility testing timeline stability and glucose-oxidase enzyme supply continuity. A model refresh is warranted upon material change in optical glucose monitor clinical accuracy thresholds or breakthrough device designation pathway processing speeds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Ligation Devices Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Endoprosthesis Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Global Mobile C-Arm Market
Medical Devices
Global Endotracheal Tubes Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Medical Connector Market
Medical Devices
Oxygen Generator Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Pelvic Muscle Probes Market