
 Cardiac Implants Market | 2026-2036
Cardiac Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Implants Market Analysis
Aftermarket service revenue is reconfiguring margin capture across the cardiac implant value chain. Medtronic leverages its field service network to sustain recurring revenue streams from device monitoring and remote follow-up. Abbott Laboratories anchors its position through vertical integration into lead extraction and battery replacement services. Boston Scientific Corporation differentiates by competing on electrophysiology lab partnership models that bundle capital equipment with implant volume commitments.
Cardiac implants encompass permanently or temporarily placed devices that mechanically support heart function, regulate rhythm, or restore vascular patency, typically manufactured from titanium alloys, platinum-iridium electrodes, or biocompatible polymers with hermetic sealing against body fluids. Their primary purpose is to reduce mortality and morbidity in patients with structural heart disease, conduction disorders, or coronary ischemia. Implantable cardioverter defibrillators and leadless pacemakers now command the fastest expansion within product type segments as electrophysiology shifts toward miniaturization and catheter-based delivery. Biomaterials and electronic devices represent the technology categories where margin pools concentrate, with active implant systems requiring sophisticated firmware and energy management architectures that sustain premium positioning.
FDA premarket approval and the EU Medical Device Regulation impose escalating clinical evidence burdens on novel active implantable devices, while ISO 14155 governs investigational study conduct across multiple jurisdictions. These frameworks extend development timelines but simultaneously erect barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor how FDA breakthrough device designation and EMA parallel scientific advice pathways reshape competitive entry dynamics for subcutaneous ICD and leadless pacing platforms.
Market Dynamics
Electrophysiology lab capacity expansion is compressing the gap between diagnostic catheterization and therapeutic implantation, forcing device manufacturers to bundle hardware with procedural training and remote monitoring infrastructure to secure hospital system commitments.
Growth Catalysts
- Leadless pacemaker miniaturization:Catheter-based delivery eliminates transvenous lead complications, expanding candidacy to patients with vascular access limitations previously excluded from conventional systems.
- EU Medical Device Regulation (MDR) clinical evidence pathways:Stricter post-market surveillance requirements favor manufacturers with established quality management systems and dedicated regulatory affairs infrastructure.
- Japan's aging demographic concentration:The country's super-aged population structure sustains procedural volume for implantable cardioverter defibrillators despite plateauing prevalence in younger cohorts elsewhere.
Market Restraints
- Platinum-iridium electrode supply concentration:Refining capacity for these critical electrode materials clusters in a handful of specialized metallurgical facilities, exposing manufacturers to input cost volatility and allocation risk.
- FDA premarket approval timeline extension:Novel active implantable devices face escalating clinical evidence burdens that stretch development cycles and compress competitive windows for breakthrough designations.
- Transcatheter valve replacement substitution:Structural heart interventions are displacing some rhythm management indications as cardiologists prioritize hemodynamic correction over electrical stabilization in overlapping patient populations.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled implantable devices are converging with cloud-based analytics platforms to create recurring revenue streams beyond the initial procedural episode.
- Germany's Diagnosis-Related Group refinement:Reimbursement recalibration for complex electrophysiology procedures is creating incentive alignment for hospitals to invest in advanced implant capabilities.
- Subcutaneous ICD penetration in the United States:Elimination of transvenous leads addresses lead extraction liability concerns, opening addressable market expansion in younger patients with long life expectancy.
Industry Challenges
- Electrophysiologist training pipeline constraints:Procedural complexity for lead extraction and device upgrade surgeries outpaces fellowship program output, creating regional access disparities.
- Legacy device interoperability:New-generation implants must maintain backward communication compatibility with existing home monitoring systems and clinic networks, constraining firmware architecture choices.
- Hermetic sealing certification timelines:Titanium alloy biocompatibility and laser-weld integrity testing for long-term implantation extends quality assurance cycles before commercial release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Implants Market |
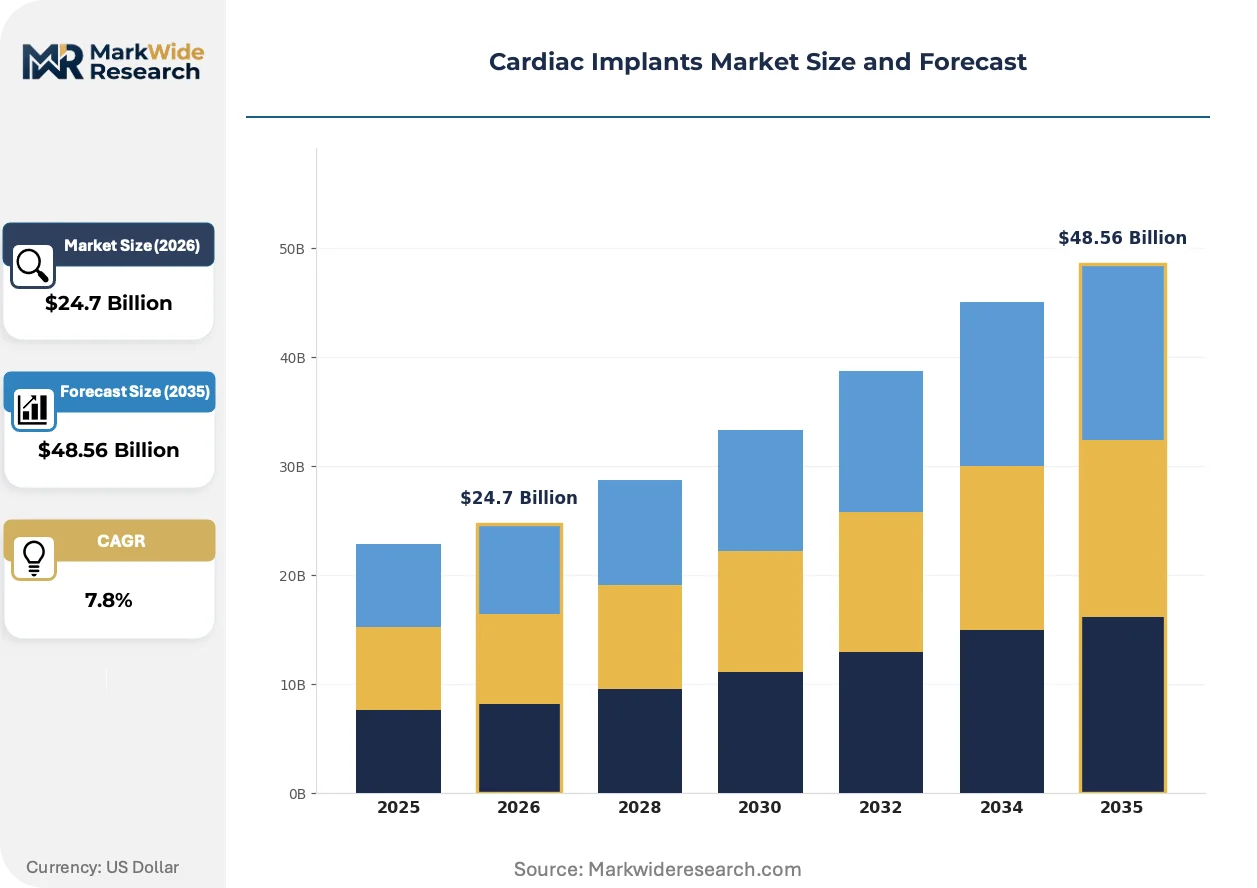
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $48.56 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Stents, Implantable Cardioverter Defibrillators, Catheters Technology: Biomaterials, Active Implants, Passive Implants, Electronic Devices End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Home Healthcare Application: Heart Failure, Arrhythmia Management, Coronary Artery Disease, Therapeutic Monitoring |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Edwards Lifesciences Corporation, BIOTRONIK, Philips, Stryker, Terumo Corporation, LivaNova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Implants Market Emerging Trajectories
Cardiac implant development is pivoting from hardware-centric differentiation toward ecosystem integration, where device firmware, remote connectivity, and predictive analytics form unified competitive moats rather than standalone product performance.
Leadless pacing technology is hybridizing conventional bradycardia management with atrial fibrillation burden monitoring through integrated accelerometer and thoracic impedance sensors. Major electrophysiology programs in the United States and Germany are adopting these dual-function systems to consolidate device inventory and simplify patient follow-up protocols. This convergence is compressing the traditional separation between rhythm monitoring and therapeutic pacing, enabling single-device strategies for comorbid patient populations.
The EU Medical Device Regulation's reinforced clinical evidence requirements are extending post-market surveillance obligations for active implantable devices across all member states. Manufacturers must now maintain systematic literature review processes and periodic safety update reports that parallel pharmaceutical vigilance standards. Subcutaneous ICD platforms face the steepest compliance burden given their novel sensing algorithms and limited long-term field data compared to transvenous alternatives.
Hospital procurement committees are consolidating vendor relationships through multi-year implant volume agreements that bundle capital equipment placement with device supply commitments. Electrophysiology lab directors in Japan and the United States are prioritizing suppliers offering integrated training pathways and 24/7 technical support over pure price competition. This behavioral shift favors manufacturers with field service density and dedicated clinical specialist teams capable of supporting complex extraction and upgrade procedures.
Cardiac Implants Market Segmentation
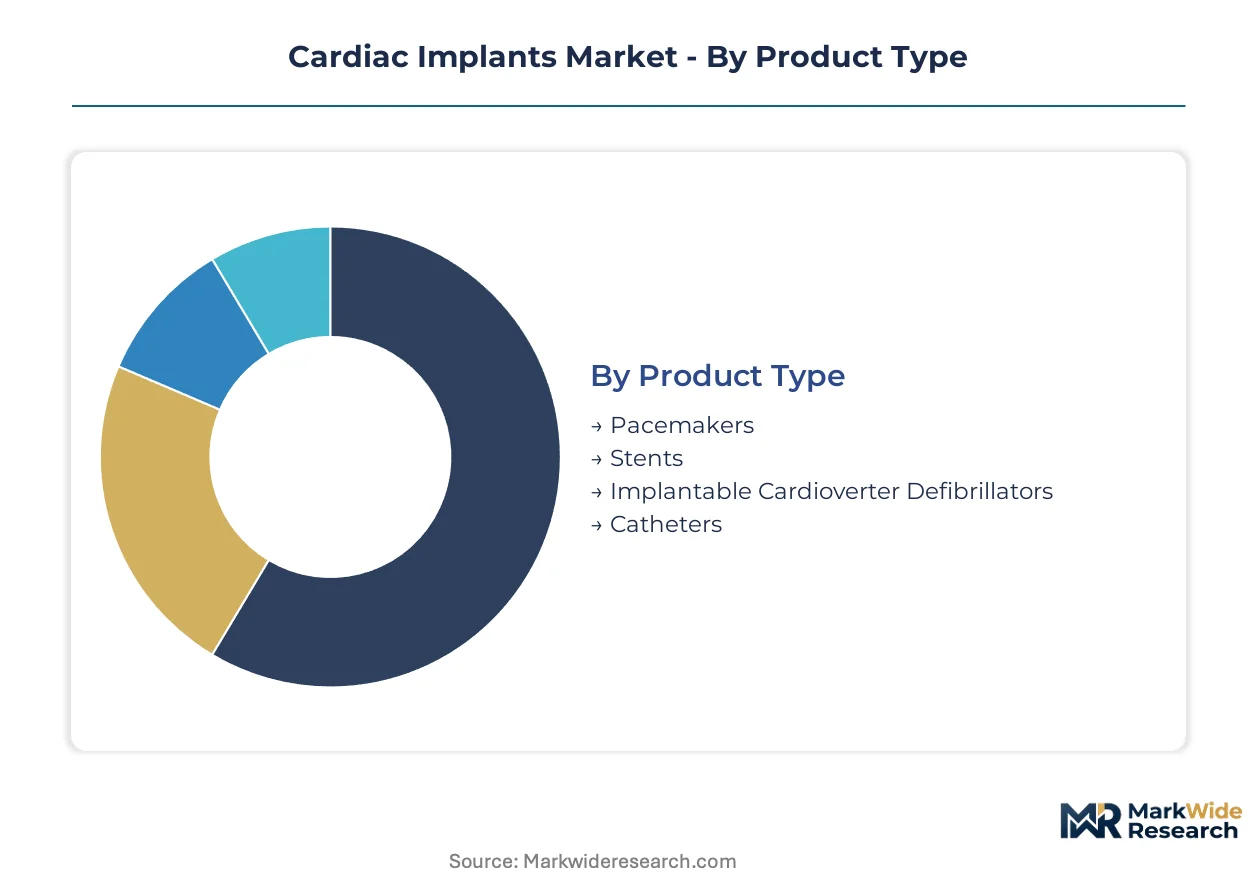
Cardiac implant manufacturers prioritize segments with compressed replacement cycles and recurring revenue potential. Understanding where procedural volume concentrates versus where technology premiums command margin differentiation shapes portfolio allocation and R&D prioritization across the value chain.
Product Type:
Replacement intervals vary dramatically across implant categories, with battery-dependent systems turning over faster than permanent structural devices.
- Implantable Cardioverter Defibrillators:Battery-powered systems with finite energy reserves require surgical replacement every 5-7 years, creating predictable procedural recurrence. United States electrophysiology labs generate the highest procedural density for these devices, driven by favorable reimbursement alignment for complex extraction and upgrade surgeries.
- Pacemakers:Leadless miniaturized variants are displacing conventional transvenous systems as catheter delivery eliminates lead-related complications. Germany's Diagnosis-Related Group recalibration is accelerating hospital investment in leadless capabilities, concentrating demand in tertiary referral centers with advanced electrophysiology infrastructure.
- Stents:Drug-eluting and bioresorbable platforms address coronary restenosis with permanent implantation profiles.
- Catheters:Diagnostic and ablation catheters support electrophysiology mapping and therapeutic delivery.
Stents anchor the volume base while implantable cardioverter defibrillators gain share at the steepest rate.
Technology:
Margin pools concentrate where firmware complexity and energy management architectures create defensible differentiation.
- Electronic Devices:Sophisticated sensing algorithms, wireless telemetry, and predictive analytics firmware sustain premium positioning. Active implant systems in Japan and the United States integrate Bluetooth connectivity with cloud-based remote monitoring platforms, generating recurring service revenue beyond initial implantation.
- Active Implants:Battery-powered therapeutic systems with hermetic sealing and biocompatible electrode interfaces command the highest per-unit margins. FDA premarket approval pathways and EU MDR clinical evidence requirements favor established manufacturers with dedicated regulatory affairs infrastructure.
- Biomaterials:Titanium alloys, platinum-iridium electrodes, and biocompatible polymers form the structural foundation.
- Passive Implants:Non-powered structural devices rely on mechanical design and surface engineering.
Biomaterials generate the highest absolute shipment volumes while electronic devices capture the most favorable margin expansion trajectory.
End User:
Procurement authority and technical support requirements segment the customer base across facility types.
- Hospitals:Integrated health systems with electrophysiology lab capacity dominate complex device implantation and extraction procedures. United States hospital procurement committees are consolidating vendor relationships through multi-year volume agreements bundling capital equipment with device supply commitments.
- Cardiology Clinics:Specialized outpatient facilities concentrate diagnostic workup and device follow-up monitoring. Germany's clinic-based electrophysiology programs are expanding leadless pacemaker candidacy assessment, filtering appropriate cases for tertiary referral.
- Ambulatory Surgical Centers:Lower-acuity settings are capturing select pacemaker implantation cases.
- Home Healthcare:Remote monitoring infrastructure and patient-facing technical support services.
Hospitals retain the procedural complexity tier while cardiology clinics expand their share of longitudinal patient management.
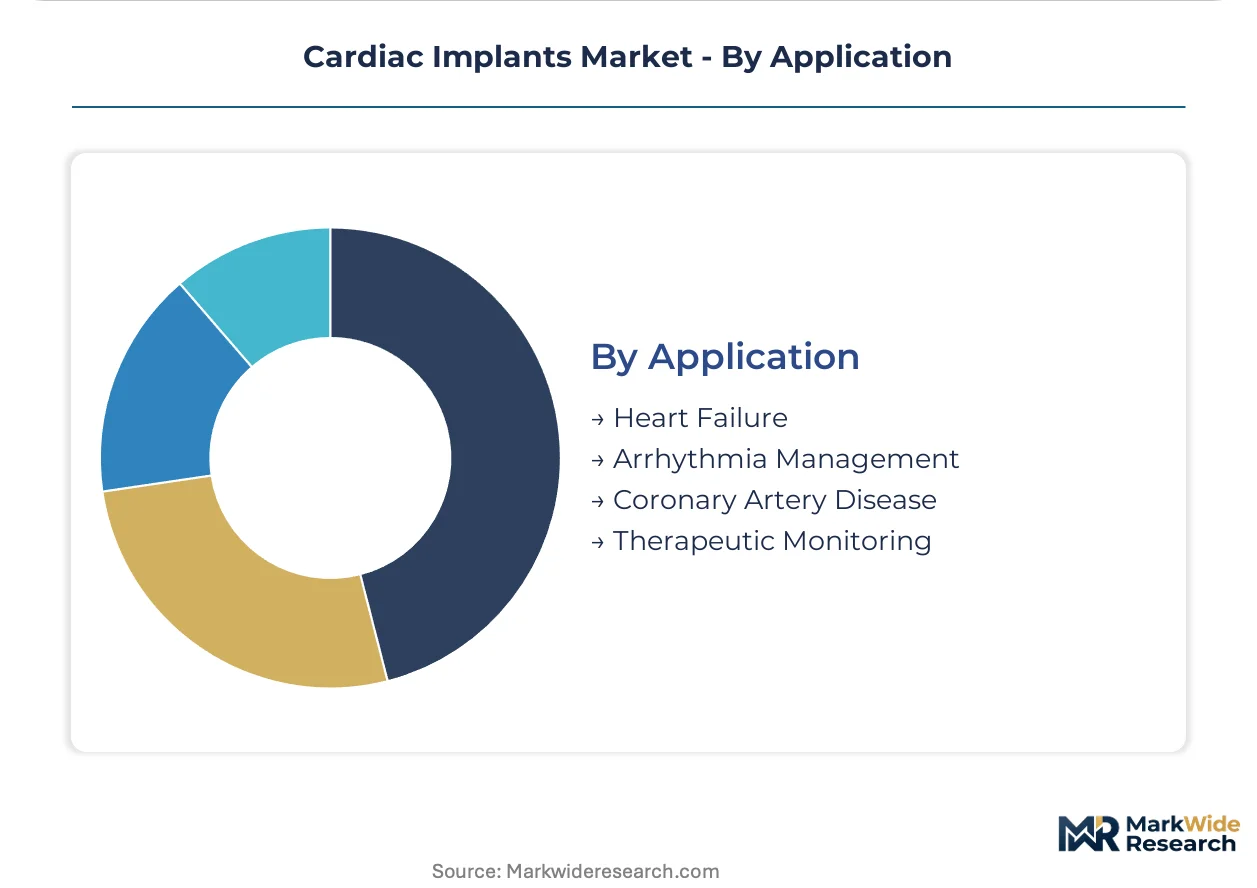
Application:
Clinical indication severity and intervention urgency shape device selection and reimbursement pathways.
- Arrhythmia Management:Bradycardia pacing and tachyarrhythmia termination represent the most technology-intensive application segment. Leadless pacemakers and subcutaneous ICDs are expanding candidacy to patients with vascular access limitations previously excluded from transvenous systems.
- Heart Failure:Cardiac resynchronization therapy and hemodynamic monitoring devices address structural dysfunction. Japan's super-aged demographic concentration sustains procedural volume for heart failure implants despite plateauing prevalence in younger cohorts elsewhere.
- Coronary Artery Disease:Revascularization stents and flow monitoring sensors address ischemic pathology.
- Therapeutic Monitoring:Integrated sensors within pacing and defibrillation platforms track disease progression.
Coronary artery disease represents the largest historical indication base while arrhythmia management climbs fastest on technology substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity for advanced cardiac implants, while healthcare systems in India and Brazil face acute budget constraints that compress margins on standard device categories.
United States
Hospital procurement committees bundle multi-year implant volume agreements with capital equipment placement, concentrating demand in integrated health systems with electrophysiology lab capacity. FDA premarket approval pathways impose escalating clinical evidence burdens that favor established manufacturers with dedicated regulatory affairs infrastructure. The Cleveland Clinic and Mayo Clinic anchor advanced extraction and upgrade surgery referral networks.
Germany
Tertiary referral centers with advanced electrophysiology infrastructure drive leadless pacemaker adoption as Diagnosis-Related Group recalibration creates incentive alignment for complex procedure investment. EU Medical Device Regulation post-market surveillance obligations parallel pharmaceutical vigilance standards. Berlin and Munich host concentration of electrophysiology fellowship programs that constrain regional access disparities.
Japan
Super-aged demographic structure sustains procedural volume for implantable cardioverter defibrillators despite plateauing prevalence in younger cohorts elsewhere. PMDA regulatory frameworks govern active implantable device approval with systematic literature review requirements. Tokyo and Osaka metropolitan areas concentrate electrophysiology lab density and device implantation capacity.
China
Domestic manufacturers capture volume in standard pacemaker categories while imported premium devices face reimbursement compression under centralized procurement. NMPA clinical trial requirements for novel active implants extend development timelines. Shanghai and Beijing anchor foreign manufacturer commercial operations and clinical specialist training infrastructure.
India
Private hospital chains in metropolitan centers drive demand for premium implantable devices while public sector procurement emphasizes cost containment on standard systems. CDSCO regulatory pathways for active implantable medical devices require local clinical data generation. Mumbai and Delhi-NCR concentrate cardiac electrophysiology fellowship training and complex device extraction capabilities.
Cardiac Implants Market Vendor Landscape
Diversified medical technology conglomerates and specialized cardiovascular device firms split the market between ecosystem integration strategies and focused therapeutic excellence. The vendor base concentrates around manufacturers with captive regulatory affairs infrastructure capable of navigating FDA and EU MDR clinical evidence pathways. Three archetypes dominate: full-spectrum electrophysiology platform providers, rhythm management specialists with remote monitoring integration, and structural heart interventionalists expanding into conduction system pacing. Competitive moves center on electrophysiology lab partnership bundling and backward integration into lead extraction service networks.
Within the diversified platform tier, Medtronic and Abbott Laboratories exemplify manufacturers leveraging field service density to secure hospital system commitments through integrated training pathways and 24/7 technical support. Boston Scientific Corporation occupies a position emphasizing electrophysiology lab partnership models that bundle capital equipment with implant volume agreements. These three entities anchor the competitive structure through distinct approaches to recurring revenue capture beyond initial procedural episodes.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| BIOTRONIK |
| Philips |
| Stryker |
| Terumo Corporation |
| LivaNova |
| Others |
Supply Flow & Price Mechanics
Undercapacity in platinum-iridium electrode refining drives input cost volatility that manufacturers pass through to hospital procurement committees, compressing margin buffers for standard-tier devices while sustaining premium positioning for systems with firmware differentiation.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture across implant portfolios. Three-tier pricing structure across premium, standard, and economy levels segments buyers by procedure complexity and remote monitoring requirements, with FDA breakthrough designation and EU MDR certification tiers commanding substantial brand premiums. Cost compression in standard pacemaker categories is intensifying because domestic manufacturers in China and India compete on procurement tenders. Public hospital systems in emerging markets exhibit the highest price sensitivity, while integrated US health systems prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for titanium alloy feedstock and electronic component assemblies. Manufacturing concentration in Germany, Japan, and Switzerland anchors high-reliability device production, with platinum-iridium electrodes, hermetic sealing ceramics, and lithium-silver oxide battery cells forming critical input dependencies. Single-source vulnerability in specialized metallurgical refining creates allocation risk during demand surges. Distribution runs through manufacturer-direct field service networks for complex implants, with GPO contracts and hospital procurement committees governing standard device flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote patient monitoring subscriptions and lead extraction service networks are expanding faster than hardware shipments, reframing cardiac implants as service-attach platforms rather than discrete device transactions.
For Market Incumbents: Pre-empt transcatheter valve substitution by accelerating conduction system pacing integration and securing electrophysiology lab exclusivity through capital equipment bundling. Consolidate lead extraction capabilities through backward integration into specialized service networks before regional training pipeline constraints create access bottlenecks. For New Entrants and Emerging Players: Pursue subcutaneous ICD white space in younger patient cohorts with long life expectancy, where lead extraction liability concerns disadvantage transvenous incumbents. Target ambulatory surgical centers for leadless pacemaker penetration, leveraging simplified catheter delivery to bypass tertiary hospital procurement consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with captive remote monitoring platforms and dedicated field service density. Long-term viability over a multi-year horizon favors acquisition targets with FDA breakthrough device designations and established EU MDR quality management systems. Watch FDA premarket approval timeline compression as an inflection signal for competitive entry dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year volume agreements with Cleveland Clinic and Mayo Clinic anchor referral network access. |
| Software Companion Development | Bluetooth-enabled remote monitoring platforms generate recurring revenue beyond initial implantation. |
| CE Marking Pathway | EU MDR systematic literature review capabilities erect barriers against under-resourced competitors. |
| Reimbursement Strategy | Germany's Diagnosis-Related Group recalibration creates incentive alignment for complex procedure investment. |
| FDA Submission | Breakthrough device designation accelerates premarket approval timelines for subcutaneous ICD platforms. |
Methodological Framework
A standing panel of electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored market sizing across the analysis window.
Scenario-bracketing around regulatory timeline variations and reimbursement recalibration events bounded the projection range. Segmentation modeling spanned product type, technology tier, end-user facility class, and clinical application indication. CAGRs derived from logistic diffusion curves fitted to procedural volume data and replacement cycle dynamics. Inputs included electrophysiology lab capacity expansion rates and fellowship program output constraints.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles and medical device tariff schedules would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway efficiency and reimbursement stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Infusion Pump Software Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Transport Chairs Market
Medical Devices
Power Smart Bed Market
Medical Devices
Massage Equipment Market
Medical Devices
Global Glucometer Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
EMG Biosensors Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
South Africa Anesthesia Devices Market