
 Appendage Management Market | 2026-2036
Appendage Management Market Size, Share, and Industry Trends Forecast 2026-2036
Appendage Management Market Analysis
The FDA's 510(k) clearance pathway for smart materials is consolidating the cost-of-entry calculus for appendage management innovators. Abbott Laboratories leverages its vascular closure expertise to anchor positions in cardiac appendage occlusion. Medtronic plc sustains R&D intensity across its atrial appendage closure portfolio. Boston Scientific Corporation dominates left atrial appendage device segments through specialized catheter-based delivery systems.
Appendage management encompasses prosthetic, orthotic, and supportive interventions engineered to restore or enhance limb function following amputation, trauma, or degenerative conditions. Smart materials with embedded sensor arrays enable real-time gait adjustment and pressure redistribution in lower-limb prosthetics. Prosthetics and orthotics command the largest revenue share as aging populations and diabetic complications sustain replacement demand. Robotics-enabled rehabilitation devices represent the fastest-expanding technology segment, with exoskeleton systems penetrating post-surgery recovery protocols in tertiary hospitals. Biomechanics applications in injury prevention are maturing, though margin pools concentrate in custom 3D-printed socket interfaces for high-activity users.
The FDA regulates appendage management devices under Class II and III designations, while ISO 13485 quality management standards govern manufacturing consistency across suppliers. The EU Medical Device Regulation (MDR) and CE marking requirements are reshaping market access timelines for European distribution. Stakeholders must monitor reimbursement coding evolution for smart prosthetics as payors weigh functional outcomes against device acquisition costs.
Market Dynamics
Hospital procurement committees now prioritize functional outcome metrics over device acquisition costs, compressing sales cycles for manufacturers lacking real-world performance data from rehabilitation networks.
Growth Catalysts
- EU MDR harmonization:CE marking consolidation under the Medical Device Regulation is streamlining cross-border distribution for German and French orthotics suppliers, reducing duplicate certification burdens.
- Diabetic limb salvage protocols:Advanced wound care centers in the United States are expanding orthotic intervention programs, creating pull-through demand for custom offloading devices.
- Carbon fiber composite substitution:Lighter, fatigue-resistant materials are displacing traditional thermoplastics in high-activity prosthetic sockets, enabling extended wear times for ambulatory users.
Market Restraints
- Silicone liner cost volatility:Petrochemical feedstock fluctuations are squeezing margins on suspension systems, forcing mid-tier manufacturers toward thermoplastic elastomer alternatives.
- Titanium supply concentration:Sponge processing capacity clusters in Japan and Kazakhstan, exposing prosthetic component fabricators to geopolitical supply interruptions.
- Biocompatibility testing duration:ISO 10993 cytotoxicity protocols add 14-18 months to smart material commercialization timelines, delaying sensor-embedded socket launches.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives are attracting contract manufacturers to establish orthotics fabrication hubs serving domestic and export markets.
- Home-based rehabilitation monitoring:Telehealth platforms are creating channel bypass opportunities for direct-to-patient prosthetic adjustment services, disintermediating traditional orthotic clinics.
- Convergence of additive manufacturing and AI-driven socket design:Generative topology optimization is compressing custom prosthetic turnaround from weeks to days in Australian tertiary hospitals.
Industry Challenges
- Prosthetist-orthotist certification scarcity:Accredited training program capacity in the United States lags replacement demand, extending patient wait times for custom device fitting.
- Legacy electronic health record integration:Smart prosthetic data streams require API development that most hospital IT departments have deprioritized against cybersecurity mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Appendage Management Market |
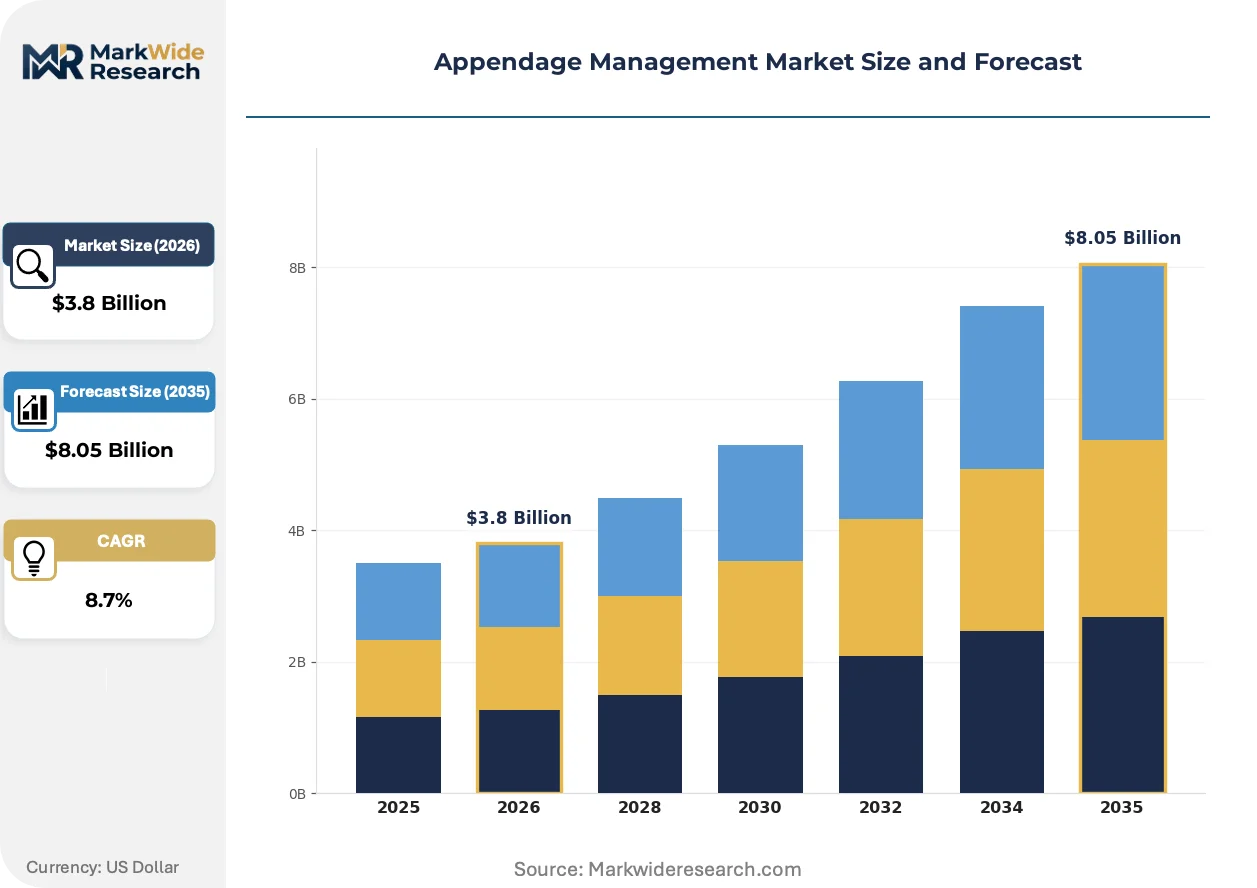
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetics, Orthotics, Supports, Rehabilitation Devices End User: Hospitals, Rehabilitation Centers, Home Care, Sports Clinics Technology: 3D Printing, Smart Materials, Robotics, Biomechanics Application: Post-Surgery Recovery, Injury Prevention, Enhanced Mobility, Pain Management |
| Companies Covered | Boston Scientific Corporation, Abbott Laboratories, Medtronic plc, AtriCure, Inc., Johnson & Johnson, Lifetech Scientific Co., Ltd, Occlutech International AB, SentreHEART, Inc., Cardia, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Appendage Management Market Emerging Trajectories
Sensor-embedded materials and generative design workflows are collapsing traditional boundaries between measurement, fabrication, and long-term device adjustment, forcing business model reinvention across the value chain.
Embedded piezoelectric sensor arrays in lower-limb prosthetics are expanding into real-time gait analysis applications. Veterans Affairs medical centers and private rehabilitation networks are deploying these systems for remote monitoring of amputee recovery trajectories. The technology is expanding into predictive maintenance contracts that replace transactional device sales with recurring revenue arrangements tied to functional outcomes.
The FDA's 510(k) clearance pathway for software-as-a-medical-device is tightening documentation requirements for algorithm-driven prosthetic adjustment tools. Manufacturers must now submit clinical validation data for machine learning models that modify socket fit recommendations. Cardiac appendage occlusion devices face parallel scrutiny, with the agency demanding longer-term thrombosis surveillance studies for novel implant geometries.
Hospital value analysis committees now require prosthetic suppliers to submit total cost-of-ownership models spanning device lifespan rather than upfront acquisition quotes. This behavioral shift favors vendors with durable component architectures and established refurbishment programs. The pattern is most visible in German statutory health insurance contracting, where diagnosis-related group bundling is compressing allowable reimbursement for replacement sockets.
Appendage Management Market Segmentation
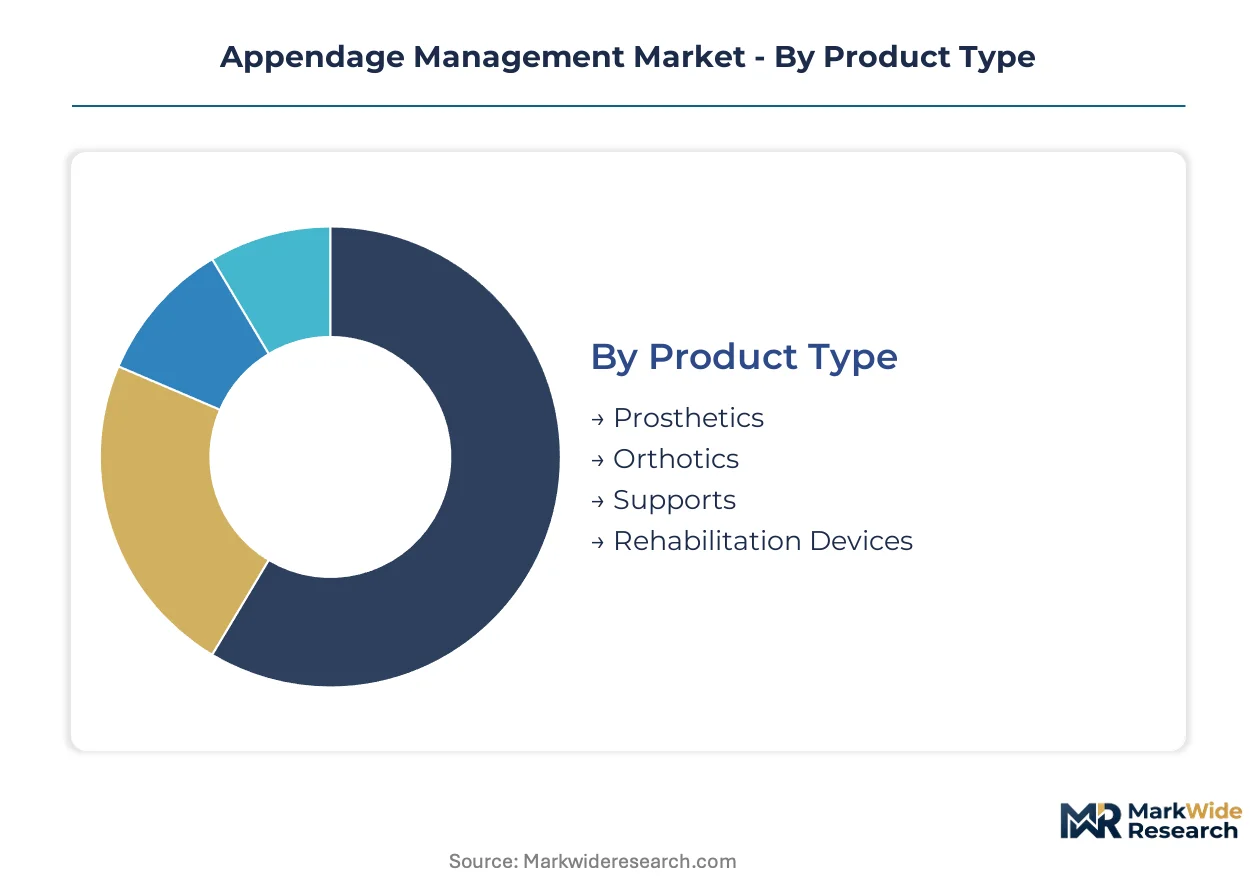
Appendage management device procurement follows distinct upgrade cycles across product categories, with replacement timelines varying from months for consumable liners to years for major prosthetic systems. Understanding these renewal patterns allows manufacturers to align inventory and service models with predictable demand waves.
Product Type:
Replacement cycles drive revenue predictability across this category, with socket systems requiring refitting every 18-36 months while component-level upgrades occur on shorter intervals.
- Prosthetics:Carbon fiber composite sockets and modular limb systems replace traditional thermoplastic assemblies in high-activity user segments. German rehabilitation networks and United States Veterans Affairs medical centers concentrate demand for microprocessor-controlled knee and ankle units, with reimbursement authorization tied to functional mobility assessments.
- Orthotics:Custom-molded ankle-foot orthoses and spinal bracing systems incorporate 3D-printed lattice structures for weight reduction. Diabetic foot clinics in the United States expand offloading orthotic programs, creating recurring demand for replacement inserts as wound healing progresses.
- Supports:Compression garments and joint stabilizers serve post-injury recovery protocols with shorter replacement cycles.
- Rehabilitation Devices:Continuous passive motion machines and resistance training systems target postsurgical joint recovery in hospital settings.
Volume placements concentrate in Prosthetics; the faster expansion belongs to Rehabilitation Devices.
End User:
Procurement authority and reimbursement pathways fragment demand across this category, with centralized purchasing dominating high-volume accounts while decentralized decision-making prevails in smaller settings.
- Hospitals:Value analysis committees in tertiary centers now mandate total cost-of-ownership documentation spanning device lifespan rather than upfront acquisition metrics. German statutory health insurance contracting and United States diagnosis-related group bundling compress allowable reimbursement for replacement sockets, favoring vendors with refurbishment programs.
- Rehabilitation Centers:Specialized fitting facilities in Germany and Australia deploy additive manufacturing for same-day socket production. These centers generate recurring revenue through adjustment services and component upgrades, with telehealth platforms now enabling remote monitoring of patient gait metrics.
- Home Care:Direct-to-patient delivery models bypass traditional orthotic clinic networks for established users with stable limb volume.
- Sports Clinics:Performance-focused facilities emphasize injury prevention and return-to-play protocols for athletic populations.
Revenue concentration sits with Hospitals; Sports Clinics are climbing the fastest as performance optimization demand spreads beyond traditional medical indications.
Technology:
Regulatory clearance timelines and manufacturing capital requirements create tiered competitive entry barriers across technology platforms.
- 3D Printing:Generative topology optimization compresses custom socket turnaround from weeks to days in Australian tertiary hospitals. Selective laser sintering of nylon-12 powders enables lattice structures that reduce component weight while maintaining structural integrity under cyclic loading.
- Smart Materials:Embedded piezoelectric sensor arrays enable real-time gait analysis and pressure redistribution in lower-limb prosthetics. FDA 510(k) clearance pathways for software-as-a-medical-device tighten documentation requirements for algorithm-driven adjustment tools, extending commercialization timelines.
- Robotics:Exoskeleton systems penetrate post-surgery recovery protocols, with powered hip and knee mechanisms assisting ambulation retraining.
- Biomechanics:Motion capture and force plate analysis inform custom device design for high-activity users and athletic applications.
Deployment scale favors 3D Printing; Smart Materials show the steepest expansion trajectory as predictive maintenance contracts replace transactional sales.
Application:
Clinical evidence requirements and reimbursement coding specificity determine addressable market size for each indication.
- Post-Surgery Recovery:Cardiac appendage occlusion devices and limb prosthetics both serve postsurgical populations, with the former addressing stroke prevention in atrial fibrillation patients. Abbott Laboratories and Boston Scientific Corporation anchor positions through specialized catheter-based delivery systems, while prosthetic manufacturers compete on socket fit and component durability.
- Injury Prevention:Custom orthotic interventions target diabetic foot ulcer prevention and sports-related overuse injuries. Advanced wound care centers in the United States expand screening protocols, creating pull-through demand for offloading devices before tissue breakdown occurs.
- Enhanced Mobility:Microprocessor-controlled prosthetic knees and powered exoskeletons restore functional independence for amputee and neurologically impaired populations.
- Pain Management:Spinal orthoses and compression systems address chronic musculoskeletal conditions through mechanical load redistribution.
Patient volume clusters in Post-Surgery Recovery; Injury Prevention is gaining share fastest as payors recognize cost avoidance from proactive intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production-Linked Incentive scheme for medical devices is attracting contract manufacturers to establish orthotics fabrication hubs serving domestic and export markets, concentrating investment in designated special economic zones with tax abatements and duty exemptions on imported capital equipment.
United States
Veterans Affairs medical centers and private rehabilitation networks deploy sensor-embedded prosthetics for remote monitoring of amputee recovery trajectories. FDA 510(k) clearance pathways for smart materials consolidate quality benchmarks while tightening documentation requirements for algorithm-driven adjustment tools. Pittsburgh and San Diego anchor prosthetic innovation clusters where tertiary hospitals partner with additive manufacturing specialists for same-day socket production.
Germany
Statutory health insurance contracting compresses allowable reimbursement for replacement sockets, favoring vendors with refurbishment programs and total cost-of-ownership documentation. EU Medical Device Regulation harmonization streamlines cross-border distribution for orthotics suppliers, reducing duplicate certification burdens. Bavarian rehabilitation center networks expand their orthotics and prosthetics capabilities through centralized procurement frameworks that prioritize functional outcome metrics.
Australia
Generative topology optimization compresses custom prosthetic turnaround from weeks to days in Sydney and Melbourne tertiary hospitals. TGA regulatory frameworks align with ISO 13485 quality management standards governing manufacturing consistency across suppliers. Queensland and New South Wales health systems pilot predictive maintenance contracts that replace transactional device sales with recurring revenue arrangements tied to functional outcomes.
Japan
PMDA oversight of Class II and III medical devices maintains rigorous biocompatibility testing protocols that extend commercialization timelines for smart material innovations. METI industrial policy supports carbon fiber composite substitution in prosthetic sockets through materials science research consortia. Osaka and Nagoya manufacturing clusters supply precision-machined titanium components to domestic and regional prosthetic fabricators.
India
CDSCO regulatory pathways for orthotic and prosthetic devices converge with BIS standards for medical device manufacturing quality. PLI scheme incentives reduce effective tax rates for manufacturers locating in designated medical device parks. Gujarat and Karnataka host emerging fabrication hubs where contract manufacturers serve export markets in Southeast Asia and the Middle East.
Appendage Management Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered competitive entry barriers created by regulatory clearance timelines and manufacturing capital requirements. The market structure concentrates around cardiovascular device multinationals with vascular closure expertise and dedicated orthotics fabricators with rehabilitation network relationships. Three archetypes dominate: diversified medical technology conglomerates leveraging cardiac catheterization platforms, specialized atrial appendage occlusion developers, and prosthetic-orthotic manufacturers with custom fabrication capabilities. Competitive moves center on strategic partnerships with rehabilitation networks and portfolio diversification into smart materials with embedded sensor arrays.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Abbott Laboratories anchor positions through specialized catheter-based delivery systems and vascular closure expertise respectively. Medtronic plc occupies a position within the cardiac rhythm and vascular portfolio tier, sustaining research and development intensity across atrial appendage closure segments. These three companies exemplify the convergence of cardiovascular intervention platforms with appendage management applications.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Abbott Laboratories |
| Medtronic plc |
| AtriCure, Inc. |
| Johnson & Johnson |
| Lifetech Scientific Co., Ltd |
| Occlutech International AB |
| SentreHEART, Inc. |
| Cardia, Inc. |
| Others |
Supply Flow & Price Mechanics
Titanium sponge price indices cascade through prosthetic component fabrication, compressing margins on modular limb systems while amplifying price premiums for carbon fiber composite sockets that bypass petrochemical feedstock volatility.
Pricing Analysis
Lead-time premiums dominate transaction economics, with same-day socket production commanding substantial markups over standard four-week fabrication cycles. Three-tier pricing structure across premium, standard, and economy levels separates microprocessor-controlled knee units from passive mechanical alternatives and basic body-powered devices. Price differentiation hinges on ISO 13485 certification tier and functional mobility assessment scores. Cost compression in mid-tier suspension systems intensifies as silicone liner petrochemical costs fluctuate. Rehabilitation centers exhibit lowest price sensitivity due to bundled reimbursement protocols, while individual home-care users face highest out-of-pocket exposure.
Supply Chain Analysis
Refurbishment flows from German statutory health insurance programs and United States Veterans Affairs networks create reverse-logistics revenue streams that subsidize new device pricing. Manufacturing concentration centers on Japan and Kazakhstan for titanium sponge processing, Germany for precision carbon fiber lamination, and China for electronic sensor module assembly. Component sourcing draws from Australian generative design software providers, Indian contract fabrication hubs under PLI incentives, and Swiss precision machining specialists. Single-source vulnerability concentrates in Japanese titanium sponge capacity. Distribution runs through hospital value analysis committees and rehabilitation center procurement frameworks rather than direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The appendage management sector has become a vertical-integration race, with control over smart material sensor arrays and socket fabrication workflows determining margin capture across the value chain.
For Market Incumbents: Lock in rehabilitation network partnerships through predictive maintenance contracts that replace transactional sales with recurring revenue tied to functional outcomes. Deepen backward integration into carbon fiber composite pre-preg manufacturing to offset titanium supply concentration risks. Pursue FDA 510(k) clearance for algorithm-driven socket adjustment tools ahead of documentation requirement tightening. Certification investment in ISO 13485 quality management systems creates defensive moats against mid-tier competitors lacking hospital procurement committee access. For New Entrants and Emerging Players: Telehealth platform partnerships offer the most penetrable route for direct-to-patient prosthetic adjustment services that bypass established orthotic clinic networks. Target home-care segments with stable limb volume where remote monitoring replaces in-person fitting visits. White-space opportunities concentrate in India's PLI-designated medical device parks for export-oriented contract fabrication. Sports clinic channels for performance optimization applications remain underdeveloped relative to traditional medical indications. For Investors and Strategic Acquirers: The window for entry favors specialized atrial appendage occlusion developers with catheter-based delivery expertise and prosthetic-orthotic manufacturers with custom 3D-printed socket capabilities. Long-term viability rests on convergence of additive manufacturing and AI-driven generative design workflows that compress turnaround times. Acquisition target archetypes include smart materials innovators with embedded sensor arrays and rehabilitation network operators with centralized procurement relationships. Monitor FDA software-as-a-medical-device clearance timelines and EU MDR harmonization progress as inflection indicators for regulatory-access valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures value analysis committee access and total cost-of-ownership contract structures. |
| CE Marking Pathway | Unlocks EU MDR-harmonized cross-border distribution for German and French suppliers. |
| Software Companion Development | Enables FDA 510(k) clearance for algorithm-driven prosthetic adjustment tools. |
| Backward Integration into Carbon Fiber | Reduces exposure to petrochemical feedstock volatility in socket manufacturing. |
| Reimbursement Strategy | Aligns diagnostic-related group bundling with predictive maintenance revenue models. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation, and hospital procurement contract filings, complemented by interviews with prosthetist-orthotists, rehabilitation center procurement directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from ISO 13485 audit records, CMS Medicare reimbursement data, and Indian PLI scheme beneficiary disclosures. Bottom-up demand modeling across product categories triangulated against top-down macroeconomic indicators.
Cross-referencing historical replacement cycle patterns with expert panel input on smart material commercialization timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass prosthetic-orthotic-rehabilitation device categories, end-user procurement authority structures, technology platform regulatory pathways, and application-specific reimbursement coding. CAGRs were derived from installed base growth rates and component upgrade frequency assumptions. Industry-specific forecast inputs included diabetic limb salvage protocol expansion trajectories and exoskeleton rehabilitation penetration curves.
The model holds under stable FDA Class II-III designation pathways and sustained German statutory health insurance reimbursement rates; deviation in titanium supply chain disruptions or EU MDR implementation delays would shift volume and value outputs. Practitioners should monitor silicone liner petrochemical cost indices and prosthetist-orthotist training program capacity for early signals of margin compression and service delivery bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Breast Localization System Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Diabetes Devices Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Global Nebuliser Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Surgical Display Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Low Vision Aids Market
Medical Devices
Global Pregnancy Detection Kits Market