
 Temporary Pacing Leads Market | 2026-2036
Temporary Pacing Leads Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Pacing Leads Market Analytics
Domestic catheter manufacturing in the United States is realigning around higher-reliability conductor assemblies for temporary pacing applications. Medtronic leverages its integrated supply chain to sustain cost advantages across bipolar and unipolar lead portfolios. Abbott Laboratories anchors its position through specialized transvenous delivery systems that dominate high-volume hospital purchasing. Boston Scientific Corporation competes on electrophysiology workflow integration, extending its reach into outpatient procedural settings.
Temporary pacing leads are thin, flexible conductors designed for short-term cardiac electrical stimulation, typically featuring platinum-iridium electrodes with polyurethane or silicone insulation and connecting to external pulse generators via standard DIN or IS-1 connectors. Their primary purpose is to maintain adequate heart rate during post-surgical recovery, acute myocardial infarction, or interventional electrophysiology procedures when permanent pacemaker implantation is unnecessary or contraindicated. Bipolar leads currently command the strongest margin pool due to reduced myocardial stimulation thresholds and improved sensing fidelity, while transvenous delivery mode dominates procedural volume owing to minimally invasive insertion techniques that shorten recovery times. Dual chamber leads represent the fastest-growing product configuration as electrophysiologists increasingly demand atrioventricular sequential pacing capabilities for hemodynamically compromised patients.
The US FDA regulates temporary pacing leads as Class II cardiovascular devices requiring substantial equivalence demonstrations and electrical safety testing under 21 CFR 870.1800, while the EU MDR imposes enhanced clinical evidence requirements and post-market surveillance obligations for active implantable accessories. ISO 14708-2 standards govern active implantable medical devices including pacing leads, specifying insulation integrity and conductor fatigue resistance criteria that manufacturers must validate. Stakeholders should monitor evolving FDA guidance on biocompatibility testing for novel polymer formulations and track EU notified body capacity constraints that could delay MDR conformity assessments for new lead designs.
Market Dynamics
Catheterization laboratory expansion across the United States is compressing procedure turnaround times, forcing manufacturers to redesign temporary pacing leads for faster deployment and reduced fluoroscopy exposure. Electrophysiology departments now demand leads that integrate seamlessly with existing mapping systems while maintaining electrical reliability under accelerated procedural protocols.
Growth Catalysts
- Hospital electrophysiology expansion:United States catheterization laboratory construction is accelerating procedural volumes for peri-procedural rhythm management, pulling demand for compatible temporary pacing systems.
- FDA Class II device guidance updates:Tighter electrical performance testing protocols under 21 CFR 870.1800 are filtering out lower-reliability competitors and elevating certified manufacturers.
- Platinum-iridium electrode adoption:Superior conductivity and corrosion resistance in these electrode materials are reducing myocardial stimulation thresholds and improving sensing fidelity in acute care settings.
Market Restraints
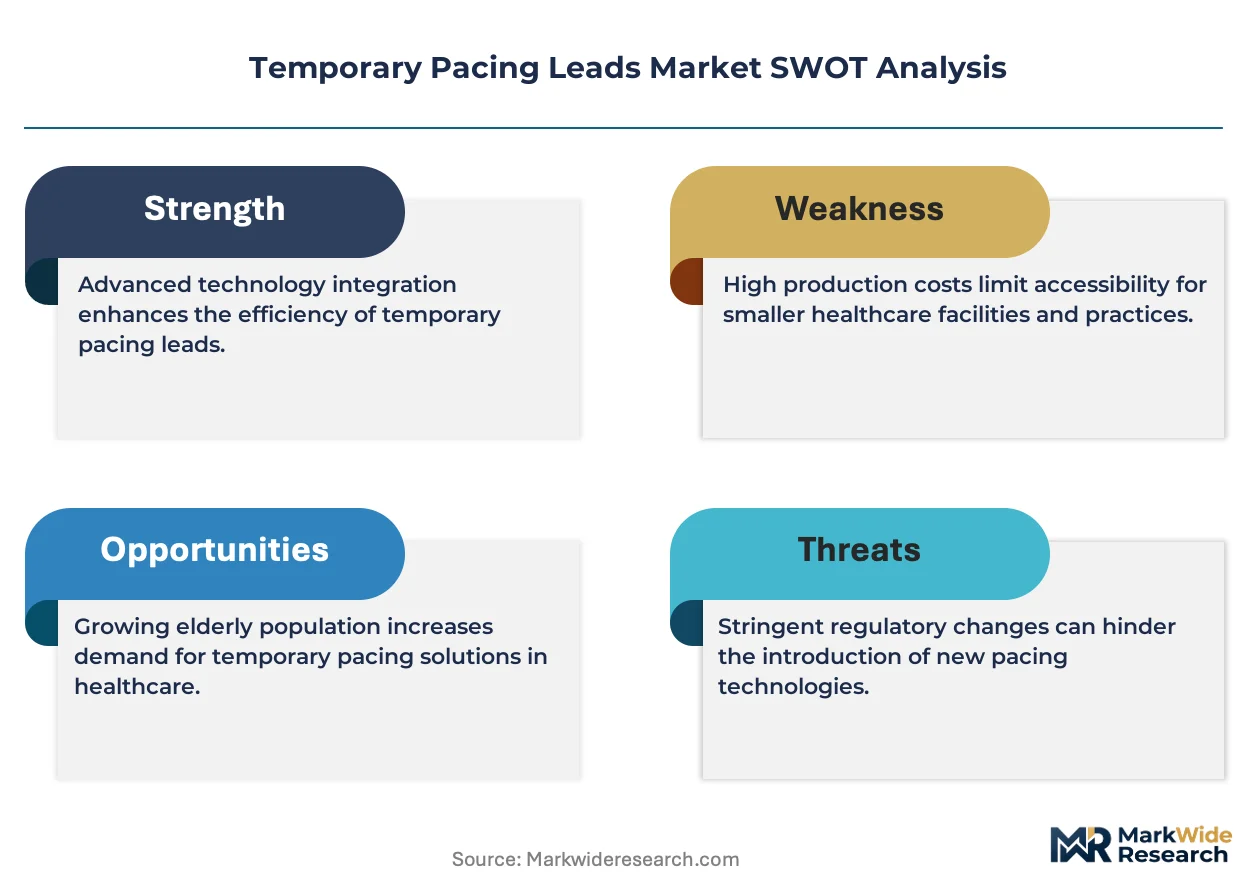
- Polymer supply concentration:Medical-grade polyurethane and silicone insulation relies on a narrow supplier base concentrated in Germany and Switzerland, creating input vulnerability.
- EU MDR clinical evidence requirements:Enhanced post-market surveillance obligations and notified body capacity constraints are extending conformity assessment timelines for new lead designs.
- Permanent pacemaker miniaturization:Smaller, faster-implantable permanent devices are shortening the window where temporary pacing remains clinically preferred.
Strategic Opportunities
- Outpatient procedural settings:Ambulatory surgical centers in Florida and Texas are expanding electrophysiology services, creating demand for simplified temporary pacing workflows outside traditional hospitals.
- Dual chamber lead underpenetration:Atrioventricular sequential pacing capabilities remain underutilized in hemodynamically compromised patient populations, representing white space for product differentiation.
- ISO 14708-2 certification alignment:Manufacturers validating insulation integrity and conductor fatigue resistance against this standard can accelerate regulatory pathways in multiple jurisdictions.
Industry Challenges
- Biocompatibility testing complexity:Novel polymer formulations require extended cytotoxicity and sensitization studies under evolving FDA guidance, compressing product development schedules.
- Electrophysiology workflow integration:Temporary pacing leads must interface with proprietary mapping systems from multiple manufacturers, demanding costly compatibility engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Pacing Leads Market |
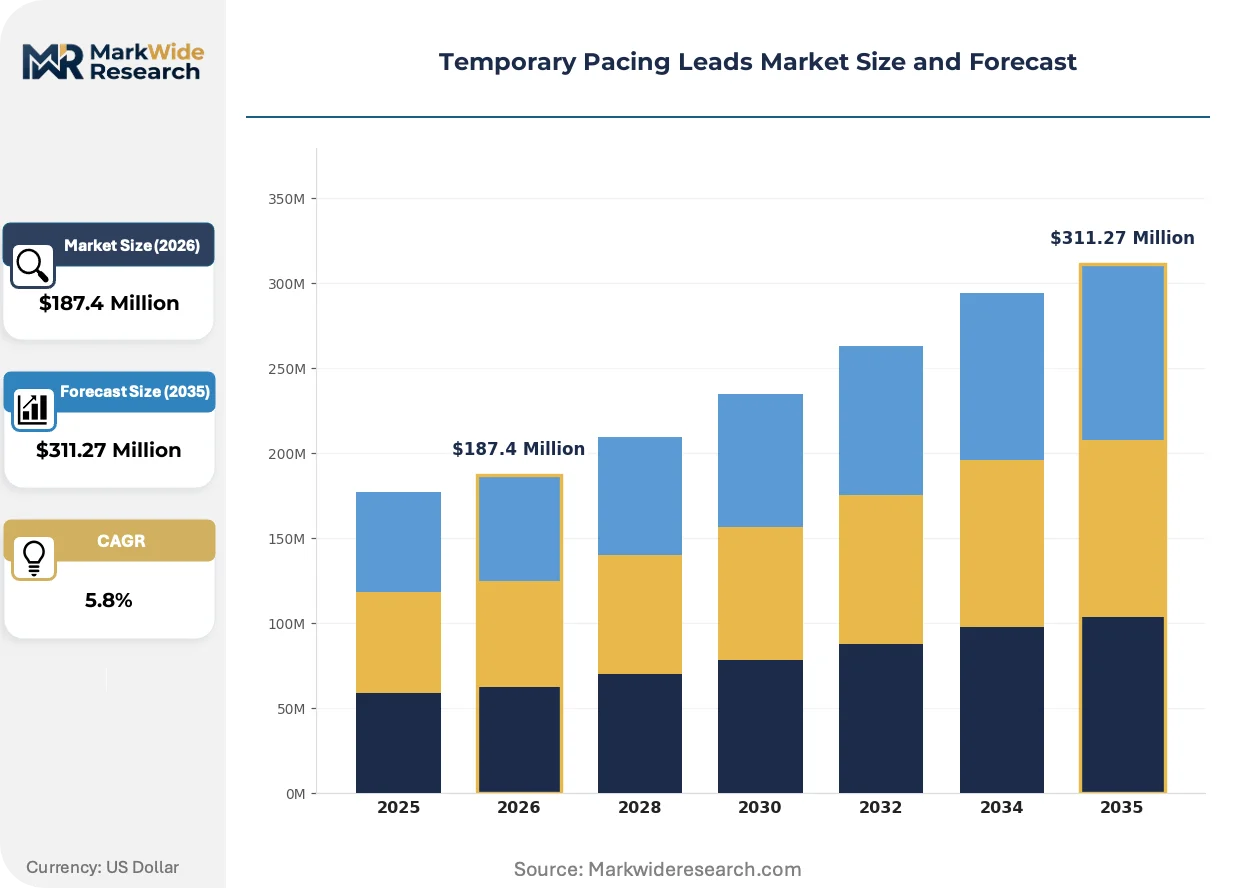
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unipolar Leads, Bipolar Leads, Dual Chamber Leads, Others Delivery Mode: Transvenous, Epicardial, Endocardial, Others End User: Cardiology Clinics, Hospitals, Outpatient Centers, Research Institutions Application: Cardiac Surgery, Electrophysiology, Resuscitation Procedures, Diagnostic Tests |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Biotronik, B. Braun Melsungen, Teleflex Incorporated, Oscor Inc., BioTrace Medical, Edwards Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Pacing Leads Market Evolving Landscape
Bipolar lead architectures are displacing unipolar designs across United States electrophysiology departments, driven by reduced electromagnetic interference and improved sensing performance. This shift is compressing the addressable market for legacy unipolar configurations while rewarding manufacturers with integrated bipolar portfolios.
Active fixation mechanisms are consolidating market preference for temporary transvenous leads. These helical or tined designs reduce dislodgment rates during patient movement. United States academic medical centers are adopting them for post-surgical recovery protocols. The technology is consolidating procurement decisions around reliability metrics rather than unit cost.
The FDA's updated biocompatibility testing guidance for cardiovascular leads is elevating validation requirements for novel polymer formulations. Manufacturers must now demonstrate extended cytotoxicity profiles and material stability data. Small and mid-sized suppliers without captive testing facilities face capital barriers to compliance, concentrating innovation capacity among established players with integrated laboratories.
Hospital purchasing committees are consolidating vendor relationships around electrophysiology workflow compatibility. Integrated delivery systems in California and New York now prioritize temporary pacing leads that interface with existing mapping and recording platforms. This behavior is compressing the viable supplier base and elevating technical service capabilities as a competitive differentiator.
Temporary Pacing Leads Market Segmentation
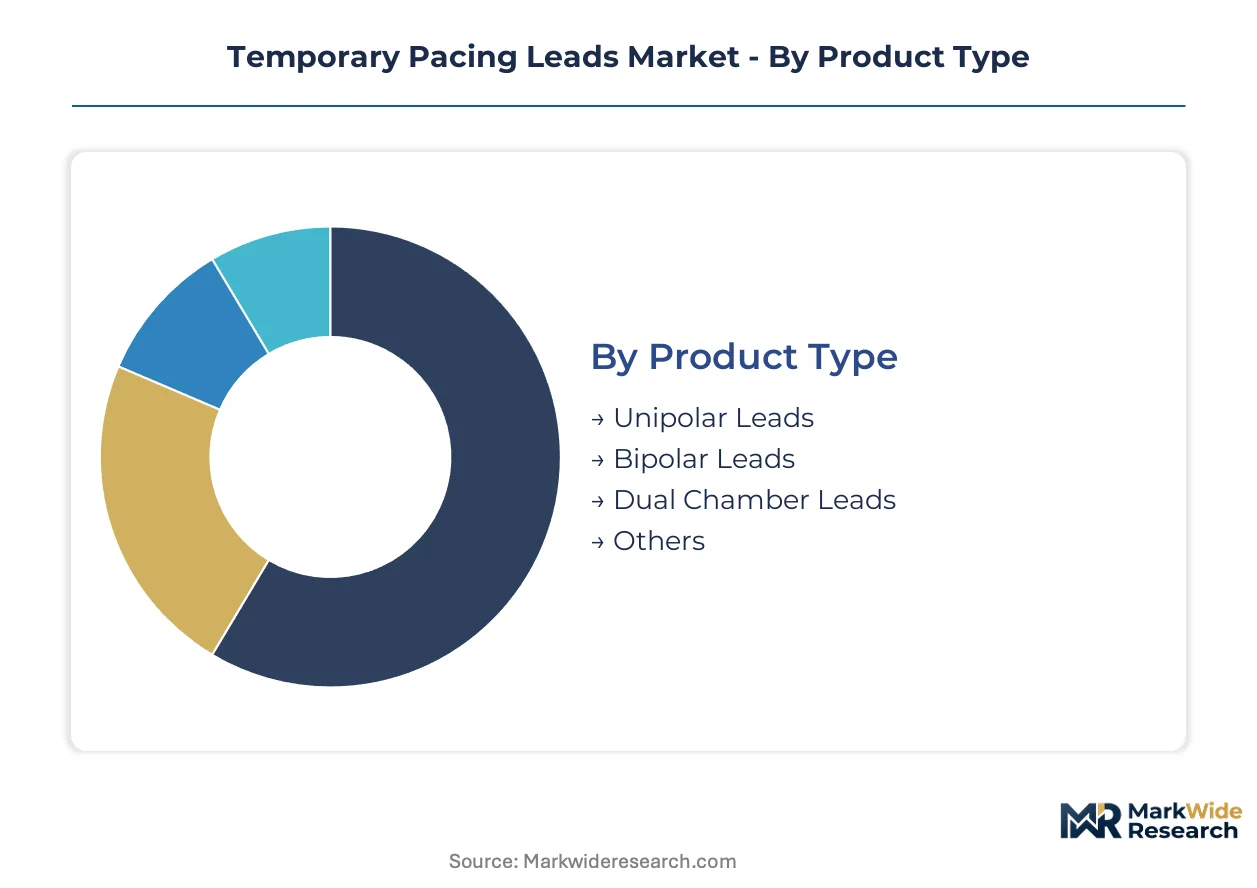
Temporary pacing leads serve distinct clinical workflows that demand differentiated electrical specifications and deployment protocols. Manufacturers align product portfolios across four segmentation dimensions that map directly to procedural economics and regulatory pathways.
Product Type:
Bipolar configurations command premium positioning through reduced interference profiles, while unipolar designs retain volume concentration in cost-sensitive procurement environments.
- Bipolar Leads:Paired conductor architecture with closely spaced platinum-iridium electrodes reduces myocardial stimulation thresholds and electromagnetic susceptibility. United States electrophysiology departments are consolidating purchasing around these configurations for mapping system compatibility. Reduced sensing artifacts during high-frequency ablation procedures drive preference in academic medical centers.
- Dual Chamber Leads:Atrioventricular sequential pacing capability integrates separate atrial and ventricular conductors within a single delivery system. Demand concentrates in hemodynamically compromised patient populations at tertiary care facilities where AV synchrony optimization is critical. This configuration is expanding most quickly as electrophysiologists adopt more sophisticated temporary pacing protocols.
- Unipolar Leads:Single electrode design with return path through the external pulse generator housing maintains cost advantages for short-term post-surgical applications.
- Others:Specialized configurations including active fixation temporary leads and pediatric-dimension variants address niche procedural requirements.
Mature deployment sits with unipolar designs in general surgical recovery. Newer deployment is concentrated in dual chamber systems for complex electrophysiology workflows.
Delivery Mode:
Minimally invasive insertion techniques dominate procedural economics, though open-chest applications retain critical utility in surgical contexts where vascular access is contraindicated.
- Transvenous:Catheter-based venous access via femoral or internal jugular approaches enables bedside placement without thoracotomy. United States catheterization laboratory expansion is accelerating procedural volumes for this delivery mode. Reduced fluoroscopy exposure requirements and shorter recovery times compress hospital length-of-stay metrics.
- Epicardial:Direct myocardial attachment via thoracotomy or sternotomy provides mechanical stability during open cardiac surgery. Demand concentrates in post-operative recovery protocols at surgical centers where temporary pacing bridges to permanent device implantation or weaning.
- Endocardial:Direct chamber access through atrial or ventricular puncture addresses specific anatomical constraints in congenital heart procedures.
- Others:Emerging approaches including transesophageal and transthoracic pacing configurations serve resuscitation scenarios.
Established utilization centers on transvenous deployment for electrophysiology procedures. Expanding utilization is occurring in epicardial applications for hybrid operating room environments.
End User:
Hospital purchasing committees control procurement volume, though ambulatory migration is fragmenting traditional supply relationships across new care settings.
- Hospitals:Integrated delivery systems and academic medical centers dominate volume through electrophysiology department expansion and catheterization laboratory construction. United States health system consolidation is compressing vendor relationships around workflow compatibility requirements.
- Outpatient Centers:Ambulatory surgical centers in Florida and Texas are building electrophysiology capabilities for low-complexity procedures. Simplified temporary pacing workflows and reduced capital equipment requirements enable service line expansion outside traditional hospital infrastructure.
- Cardiology Clinics:Office-based practices with procedural capabilities represent emerging demand for diagnostic and monitoring applications.
- Research Institutions:Academic research centers drive protocol development and training requirements for novel lead configurations.
Volume concentration remains with hospital-based electrophysiology. Fastest share gains are occurring in outpatient center procurement as ambulatory service lines expand.
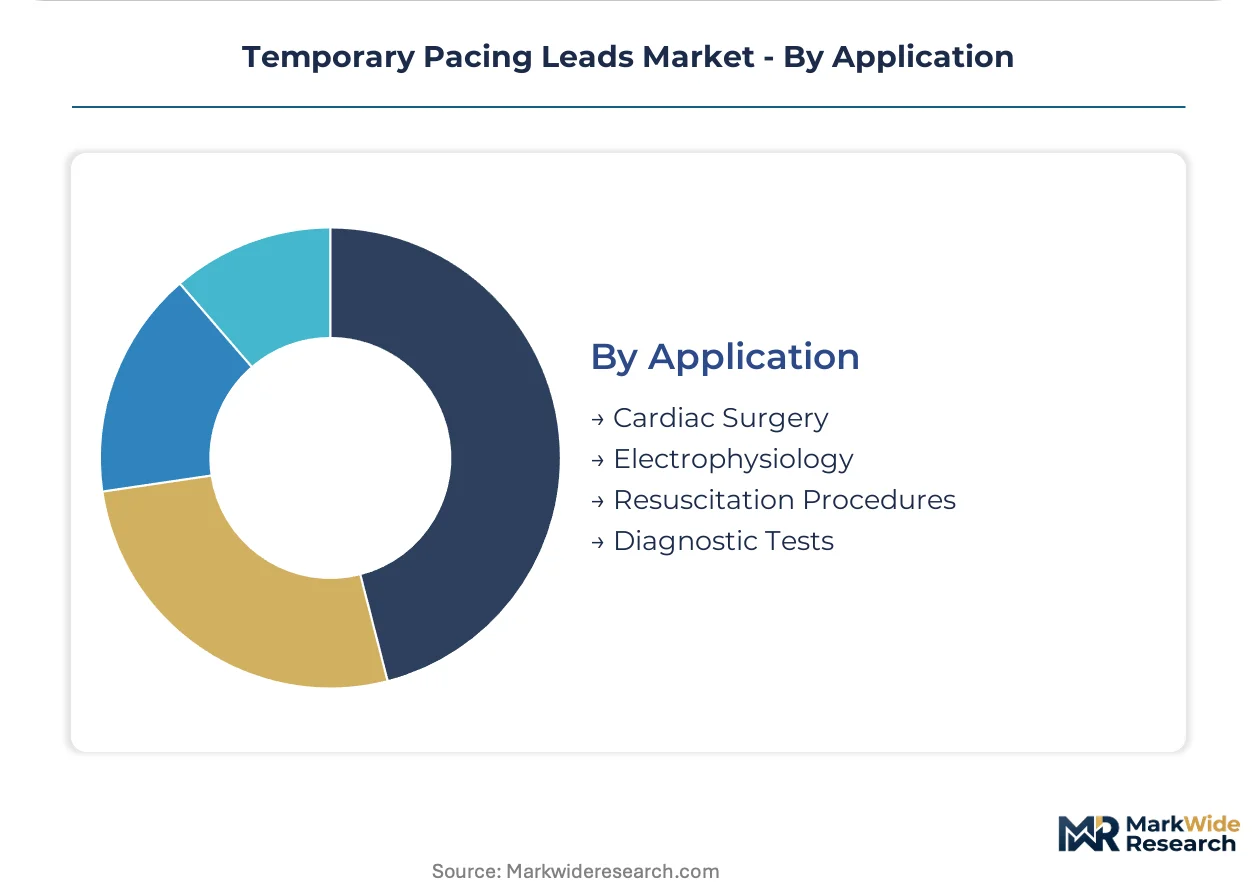
Application:
Peri-procedural rhythm management applications pull demand for higher-reliability lead configurations, while diagnostic applications tolerate lower-complexity alternatives.
- Electrophysiology:Ablation procedure support demands leads compatible with three-dimensional mapping systems and irrigated catheter platforms. United States academic medical centers require bipolar configurations with reduced electromagnetic interference for complex arrhythmia substrates.
- Cardiac Surgery:Post-operative temporary pacing bridges patients from cardiopulmonary bypass to stable rhythm or permanent device implantation. Epicardial delivery dominates this application with active fixation mechanisms reducing dislodgment during patient mobilization.
- Resuscitation Procedures:Emergency temporary pacing in acute myocardial infarction and high-grade block scenarios prioritizes rapid deployment reliability.
- Diagnostic Tests:Electrophysiology study support and pharmacological challenge procedures utilize temporary pacing for rate control and induction protocols.
Standardized deployment characterizes cardiac surgery applications. Technology evolution is accelerating in electrophysiology as mapping system integration requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade platinum-iridium electrode sourcing from South African mining operations anchors geographic supply security for temporary pacing lead manufacturing. Catheterization laboratory construction concentrates demand generation across developed healthcare systems with established electrophysiology infrastructure.
United States
FDA Class II device guidance updates under 21 CFR 870.1800 are tightening electrical performance testing protocols for cardiovascular leads. Hospital electrophysiology departments in Texas and Florida are expanding catheterization laboratory capacity for peri-procedural rhythm management. The Minneapolis medical device cluster sustains integrated manufacturing of bipolar and unipolar lead portfolios.
Germany
EU MDR conformity assessment requirements are extending timelines for new lead design certifications through notified body capacity constraints. Industrial concentration in Baden-Württemberg supports precision polymer processing for medical-grade polyurethane insulation. The Tübingen-Stuttgart corridor hosts specialized suppliers of conductor fatigue resistance testing equipment.
Switzerland
Swissmedic post-market surveillance obligations impose enhanced clinical evidence requirements for active implantable accessories. Geneva and Basel pharmaceutical clusters drive demand for temporary pacing systems in cardiac surgery recovery protocols. Zurich-based research institutions are advancing active fixation mechanism validation for reduced dislodgment rates.
Japan
PMDA regulatory harmonization with ISO 14708-2 standards accelerates approval pathways for insulation integrity certifications. Aging demographics in the Kanto region are expanding procedural volumes for acute myocardial infarction interventions. The Osaka-Kobe medical device manufacturing zone specializes in miniaturized electrode assemblies for pediatric applications.
Temporary Pacing Leads Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized fixation mechanisms and workflow integration capabilities. The supplier base concentrates around integrated electrophysiology portfolios with catheterization laboratory compatibility requirements. Three archetypes dominate: diversified cardiovascular conglomerates with captive lead production, mid-scale specialists in transvenous delivery systems, and regional fabricators serving cost-sensitive procurement environments. Competitive dynamics center on M&A consolidation of mapping system compatibility assets and vertical integration into medical-grade polymer compounding.
Among diversified cardiovascular conglomerates, Medtronic and Abbott Laboratories exemplify integrated supply chain architectures spanning bipolar lead portfolios and specialized transvenous delivery platforms. Boston Scientific Corporation occupies a position emphasizing electrophysiology workflow integration and outpatient procedural setting expansion. These three anchors represent distinct competitive vectors: cost-advantaged manufacturing scale, high-volume hospital purchasing dominance, and mapping system interoperability specialization.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Biotronik |
| B. Braun Melsungen |
| Teleflex Incorporated |
| Oscor Inc. |
| BioTrace Medical |
| Edwards Lifesciences |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up catheter specialists in the United States and Germany have consolidated procurement leverage over medical-grade polymer suppliers, translating supply-side discipline into premium pricing power for ISO 14708-2 certified lead portfolios while compressing margins for non-compliant competitors.
Pricing Analysis
Warranty and technical service bundling separates premium-tier suppliers from unbundled economy alternatives in hospital purchasing negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA Class II certification status and electrophysiology workflow integration depth. Pricing pressure stems from GPO consolidation in California and New York health systems demanding volume discounts. Academic medical centers show least price sensitivity for bipolar configurations with mapping system compatibility, while outpatient surgical centers in Florida and Texas prioritize unit cost minimization.
Supply Chain Analysis
Air freight and temperature-controlled logistics costs from South African platinum-iridium mining operations to Minnesota and Baden-Württemberg manufacturing centers elevate landed costs for electrode raw materials. Supply concentrates in Germany and Switzerland for medical-grade polyurethane and silicone insulation, with conductor assemblies drawing from Japanese precision wire suppliers. Single-source vulnerability sits with South African precious metal refining capacity. Distribution runs through hospital GPO contracts and specialized cardiovascular device distributors serving catheterization laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Class II device guidance under 21 CFR 870.1800 has erected a cost-of-compliance barrier that filters out undercapitalized competitors and entrenches certified incumbents with captive electrical safety testing infrastructure.
For Market Incumbents: Deploy backward integration into medical-grade polymer compounding to secure insulation supply against German and Swiss supplier concentration. Consolidate mapping system compatibility assets through targeted acquisition of workflow integration specialists. Permanent pacemaker miniaturization threatens temporary pacing windows; counter by expanding dual chamber lead portfolios for hemodynamically compromised patient populations. For New Entrants and Emerging Players: Ambulatory surgical center distributors in Florida and Texas represent the most penetrable channel for simplified temporary pacing workflows outside hospital GPO structures. Target outpatient electrophysiology service line expansion with capital-light delivery systems that reduce fluoroscopy exposure. White space exists in active fixation temporary leads for post-surgical recovery protocols where dislodgment rates drive procurement decisions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale transvenous delivery specialists with ISO 14708-2 certification alignment in Germany and Switzerland. Long-term viability hinges on MDR conformity assessment capacity and notified body relationships. Watch EU notified body queue lengths as the signal for regulatory access bottlenecks that will concentrate market share among compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Class II Compliance Investment | Electrical safety testing under 21 CFR 870.1800 filters out lower-reliability competitors from hospital procurement. |
| EU MDR Conformity Pathway | Enhanced clinical evidence requirements extend assessment timelines and concentrate innovation among established players. |
| Hospital System Partnership | Integrated delivery systems in California and New York prioritize workflow-compatible temporary pacing leads. |
| Software Companion Development | Mapping system integration with three-dimensional electrophysiology platforms drives academic medical center preference. |
| Reimbursement Strategy | CMS coding alignment for peri-procedural rhythm management supports catheterization laboratory service line economics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearances, EU MDR technical documentation, and ISO 14708-2 certification databases provided device-specific validation. Bottom-up procedural volume estimates from hospital construction databases combined with top-down market sizing from cardiovascular device trade associations.
Product-level granularity modeled bipolar, unipolar, and dual chamber configurations separately across transvenous, epicardial, and endocardial delivery modes. End-user segmentation distinguished hospital electrophysiology departments from outpatient surgical centers and cardiology clinics. Geographic modeling captured United States catheterization laboratory expansion, German polymer processing capacity, and Japanese miniaturization expertise. CAGRs derived from procedural volume trajectories and unit pricing trends across the analysis window.
Caveats apply where EU notified body capacity constraints, South African mining supply disruptions, or permanent pacemaker miniaturization acceleration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Video Dermatoscope Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Global Capnography Market
Medical Devices
Trocars Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Blood Lancet Market
Medical Devices
Gel Implants Market
Medical Devices
Global Medical Composite Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market