
 Pelvic Floor Electrical Stimulation Devices Market | 2026-2036
Pelvic Floor Electrical Stimulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Floor Electrical Stimulation Devices Market Outlook
Subscription-based leasing for home-use portable units is rewriting competitive entry barriers, allowing smaller entrants to bypass heavy capital outlays. Medtronic plc leverages its implantable neuromodulation heritage to sustain premium positioning in hospital procurement channels. Laborie, Inc. anchors its presence through specialized urogynecology distribution networks. TensCare Ltd. competes aggressively in direct-to-consumer retail across European pharmacy chains.
Pelvic Floor Electrical Stimulation Devices deliver controlled electrical impulses to pelvic musculature through surface electrodes or implanted leads, typically operating at frequencies between 1-50 Hz and pulse widths of 200-400 microseconds to induce rhythmic contraction for neuromuscular re-education. These systems serve primarily to restore voluntary muscle control in patients suffering from stress urinary incontinence, fecal incontinence, or post-surgical pelvic floor dysfunction. Portable units now command the fastest expansion trajectory as home care protocols displace facility-based treatment models, while implantable devices retain the deepest margin pools due to surgical placement requirements and long-term maintenance revenue. Electrode accessories represent a recurring consumable stream that locks in sustained supplier relationships across both institutional and home settings.
FDA premarket notification pathways and the EU Medical Device Regulation impose escalating clinical evidence requirements on neuromodulation manufacturers, directly extending product development timelines and favoring incumbents with established regulatory infrastructure. BIS certification in India and NMPA registration in China add further jurisdictional complexity for cross-border device distribution. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies, as coverage determinations for home-based electrical stimulation will decisively shape addressable market boundaries.
Market Dynamics
Subscription-based leasing for home-use portable units is collapsing upfront capital barriers and enabling smaller manufacturers to challenge established hospital procurement networks without heavy balance-sheet investment.
Growth Catalysts
- EU MDR compliance deadlines:Stricter clinical evidence requirements for implantable neuromodulation devices are consolidating regulatory expertise among prepared manufacturers, accelerating competitive exits.
- Postpartum recovery clinics:Specialized rehabilitation facilities in the United States are expanding pelvic floor dysfunction treatment protocols, driving institutional device procurement volumes.
- Pharmacy chain retail:Direct-to-consumer distribution through European pharmacy networks is bypassing traditional medical device distributor markups and expanding patient access.
Market Restraints
- Electrode consumable costs:Recurring accessory purchases for surface electrode replacement create persistent out-of-pocket burdens that limit patient adherence to prescribed treatment cycles.
- FDA premarket submission tightening:Escalating 510(k) evidentiary standards for neuromodulation devices are extending development timelines and freezing smaller developers from commercialization pathways.
- Home care substitution ceiling:Severe pelvic floor dysfunction requiring implanted lead systems cannot be addressed by portable surface electrode units, capping the addressable expansion of home-use segments.
Strategic Opportunities
- NMPA registration pathway:China's medical device regulator is streamlining review processes for Class II rehabilitation equipment, opening access to hospital procurement networks in tier-one cities.
- Telehealth integration:Remote monitoring capabilities paired with home-use stimulators enable asynchronous clinician oversight and create recurring platform revenue streams.
- India BIS certification:Mandatory quality standards for electromedical equipment are formalizing import channels and creating first-mover advantages for compliant foreign manufacturers.
Industry Challenges
- Reimbursement coding volatility:National health technology assessment bodies in Germany and France are revising coverage determinations for home-based electrical stimulation, creating revenue recognition uncertainty for device suppliers.
- Cross-jurisdictional evidence requirements:Divergent clinical trial standards between FDA, EU MDR, and NMPA are forcing redundant study designs that consume development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Floor Electrical Stimulation Devices Market |
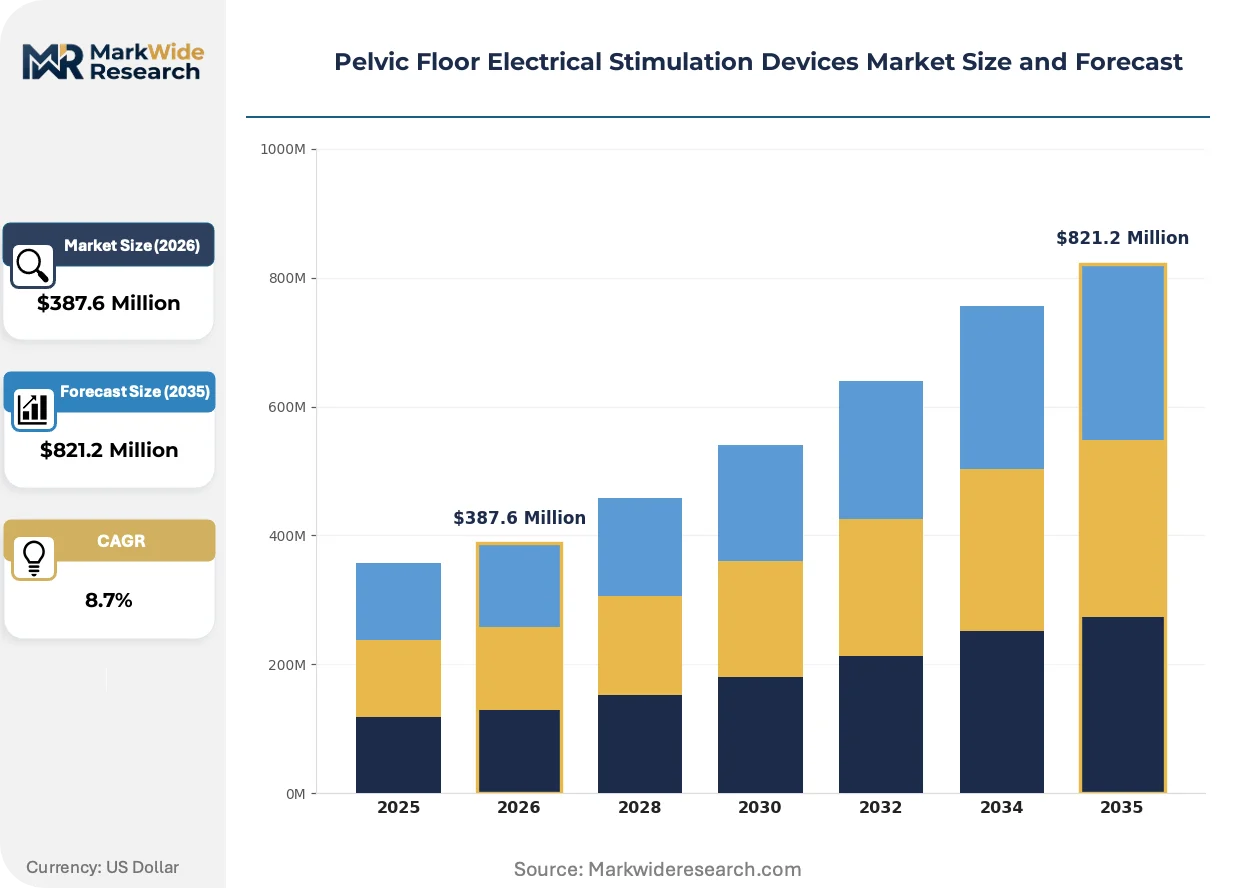
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, Portable Units, Biofeedback Systems, Electrode Accessories End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Technology: Transcutaneous Electrical Nerve Stimulation, Functional Electrical Stimulation, Neuromodulation, Magnetotherapy Application: Urinary Incontinence, Pelvic Pain Management, Sexual Dysfunction, Post-Surgical Rehabilitation |
| Companies Covered | Coloplast A/S, Laborie, Inc., Medtronic plc, InControl Medical, The Prometheus Group, Boston Scientific Corporation, BTL Industries, Inc., TensCare Ltd., Axonics Modulation Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Floor Electrical Stimulation Devices Market Strategic Shifts
Portable surface electrode systems with embedded biofeedback sensors are compressing treatment protocols and shifting clinical authority from specialized facilities toward patient-managed home environments.
Wireless connectivity modules integrated into portable stimulator units are rendering obsolete the tethered console designs that previously required clinical supervision for parameter adjustment. Postpartum recovery clinics in Germany and the United States are deploying these systems for unsupervised home protocols. The elimination of facility dependency is collapsing per-treatment reimbursement models and forcing providers toward capitated episode-based contracts.
EU MDR Article 10 technical documentation requirements for active implantable devices are mandating extended clinical follow-up periods that favor manufacturers with established post-market surveillance infrastructure. This regulatory friction is accelerating competitive consolidation as smaller developers lack resources for conformity assessment body negotiations. Implantable device portfolios face the steepest compliance cost escalation, reinforcing margin concentration among heritage neuromodulation suppliers.
Leasing arrangements for home-use equipment are displacing outright purchase patterns among cash-constrained patients and private rehabilitation networks. Subscription revenue models lock in multi-year supplier relationships and reduce quarterly sales volatility for device manufacturers. This shift is most pronounced in the United Kingdom and Netherlands, where private insurance co-payment structures incentivize spread-cost financing over upfront capital expenditure.
Pelvic Floor Electrical Stimulation Devices Market Segmentation
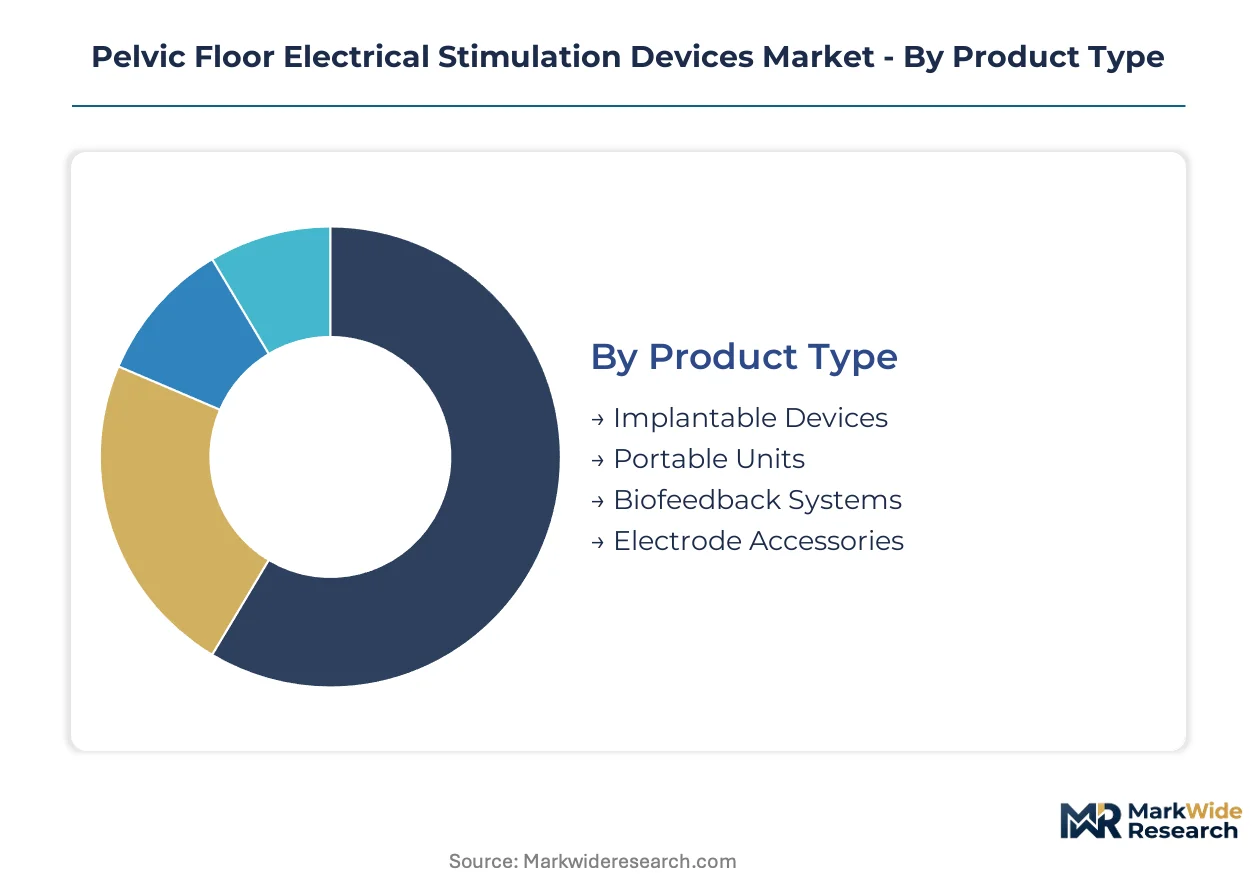
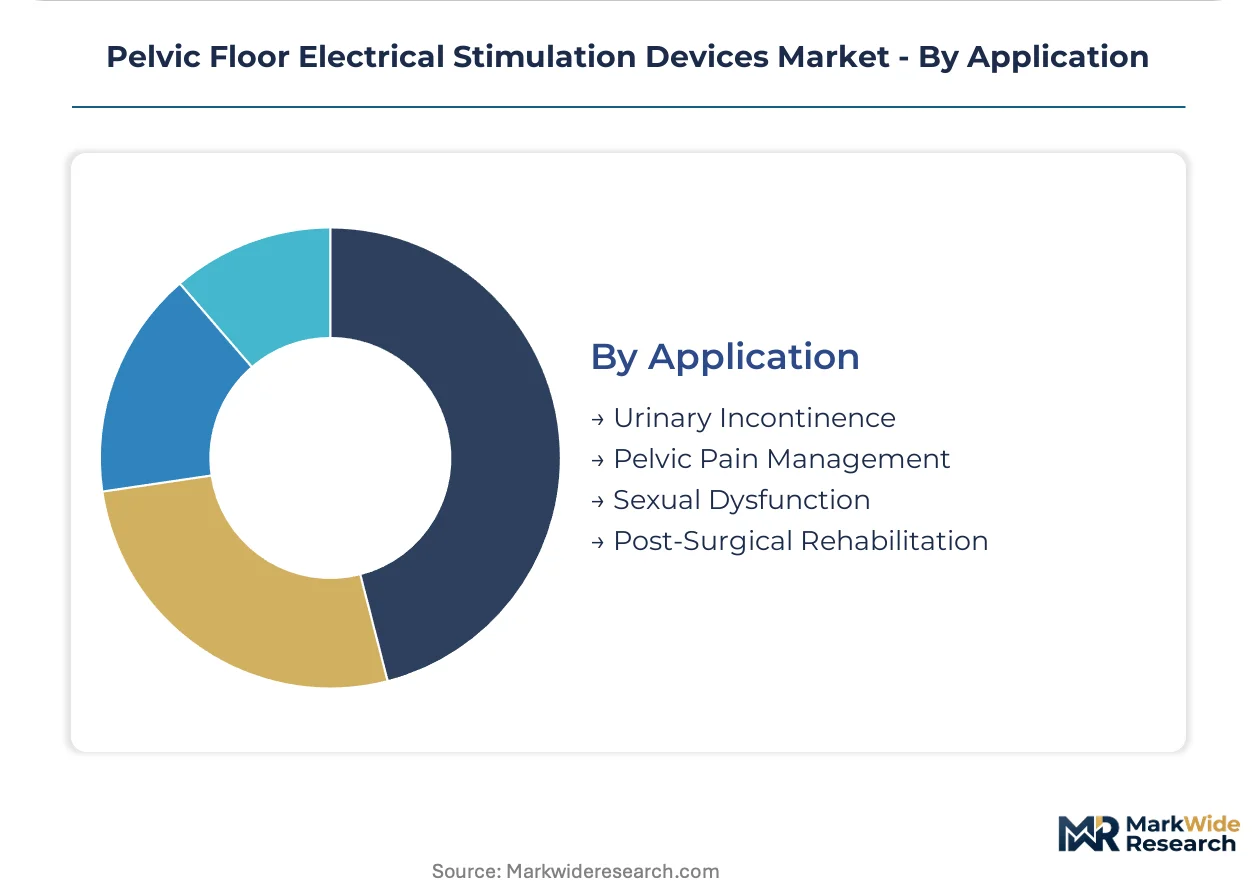
Pelvic Floor Electrical Stimulation Devices segment across four dimensions that determine procurement patterns and margin structures. Product type governs capital intensity and recurring revenue potential. End-user concentration shapes distribution channel economics and regulatory exposure.
Product Type:
Cycle times vary dramatically: electrode accessories turn over in weeks, portable units in 3-5 years, implantable devices in 7-10 years with surgical revision intervals.
- Implantable Devices:Surgically placed lead systems with internal pulse generators operating at programmable frequencies for severe dysfunction cases. Demand concentrates in German hospital neuromodulation centers where EU MDR compliance costs favor established manufacturers with post-market surveillance infrastructure.
- Portable Units:Battery-powered surface electrode stimulators with preset or adjustable parameter ranges for home-use protocols. Postpartum recovery clinics in the United States are driving fastest expansion as leasing models collapse upfront barriers for cash-constrained patients.
- Biofeedback Systems:Integrated pressure or EMG sensors paired with visual display units for real-time muscle activation training. Rehabilitation centers in tier-one Chinese cities are adopting these for supervised pelvic floor re-education programs.
- Electrode Accessories:Disposable surface pads and conductive gel interfaces requiring periodic replacement throughout treatment cycles. Pharmacy chain retail across European markets is bypassing traditional distributor markups for these high-frequency consumables.
Implantable devices dominate installed base. Portable units are where expansion concentrates.
End User:
Cost tier stratification runs from high-acuity hospital settings through mid-cost rehabilitation facilities to lowest per-episode home care environments.
- Hospitals:Acute care and surgical centers with catheterization laboratories and operating room capacity for lead implantation procedures. Procurement concentrates in Germany's university hospital networks where neuromodulation service lines command premium reimbursement.
- Rehabilitation Centers:Specialized physical therapy facilities with dedicated pelvic floor dysfunction protocols and trained clinician staff. India's emerging private rehabilitation chains are creating first-mover advantages for BIS-certified equipment suppliers.
- Home Care:Patient-managed environments with remote clinician oversight through telehealth-integrated portable units. The United Kingdom and Netherlands private insurance structures are accelerating subscription-based leasing adoption.
- Clinics:Outpatient urogynecology and postpartum recovery facilities with limited capital budgets and high patient throughput requirements. United States specialized postpartum recovery clinics are expanding device procurement volumes fastest.
Hospitals capture highest revenue per patient. Home care is climbing the fastest.
Technology:
Application maturity separates established electrical stimulation modalities from emerging magnetic field approaches still seeking reimbursement coding.
- Transcutaneous Electrical Nerve Stimulation:Surface electrode delivery of low-frequency pulses for pain modulation and muscle activation through intact skin. Home care protocols in the United States and European pharmacy retail are standardizing around these systems for stress urinary incontinence.
- Functional Electrical Stimulation:Targeted motor nerve activation with optimized pulse parameters to induce functional muscle contraction patterns. Rehabilitation centers in Germany are deploying these for post-surgical pelvic floor re-education with measurable outcome tracking.
- Neuromodulation:Implantable lead systems delivering chronic intermittent stimulation to sacral or pudendal nerve targets for refractory cases. FDA premarket submission tightening is extending development timelines and freezing smaller developers from commercialization pathways.
- Magnetotherapy:Pulsed electromagnetic field delivery without skin contact for patients intolerant of electrode adhesion or current sensation. China's NMPA streamlined Class II rehabilitation equipment review is opening hospital procurement access in tier-one cities.
Neuromodulation commands deepest margin pools. Functional electrical stimulation is gaining share fastest.
Application:
Volume concentration aligns with prevalence epidemiology, while margin concentration follows severity gradient and surgical intervention rates.
- Urinary Incontinence:Stress, urge, and mixed incontinence protocols representing the largest addressable patient population across all age demographics. Postpartum recovery clinics in the United States are driving institutional device procurement for stress incontinence protocols.
- Pelvic Pain Management:Chronic pelvic pain and dyspareunia treatment applications requiring specialized parameter programming and longer treatment courses. German rehabilitation center networks are expanding these service lines with biofeedback-integrated systems.
- Sexual Dysfunction:Female and male sexual function restoration through neuromuscular re-education and blood flow enhancement. Direct-to-consumer retail through European pharmacy chains is bypassing traditional medical device distributor markups.
- Post-Surgical Rehabilitation:Recovery protocols following prostatectomy, hysterectomy, or pelvic organ prolapse repair requiring structured muscle retraining. India's private hospital chains are formalizing post-surgical rehabilitation pathways for medical tourism patients.
Urinary incontinence dominates installed base. Post-surgical rehabilitation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy divergence across national health systems is fragmenting market access patterns. Germany's statutory health insurance funds maintain broad coverage for implantable neuromodulation, while United States commercial payers impose prior authorization hurdles that delay device adoption. China's NMPA streamlined Class II rehabilitation equipment review is accelerating hospital procurement in tier-one cities.
United States
Postpartum recovery clinics in metropolitan areas are expanding pelvic floor dysfunction treatment protocols, driving institutional device procurement volumes. FDA premarket submission tightening for neuromodulation devices is extending development timelines and freezing smaller developers from commercialization pathways. Texas and California rehabilitation networks are deploying subscription-based leasing models for home-use portable units.
Germany
University hospital neuromodulation centers command premium reimbursement rates for implantable lead procedures. EU MDR Article 10 technical documentation requirements mandate extended clinical follow-up periods that favor manufacturers with established post-market surveillance infrastructure. Bavaria's rehabilitation center network concentrates demand for biofeedback-integrated functional electrical stimulation systems.
China
Tier-one city hospital procurement networks are formalizing post-surgical rehabilitation pathways for medical tourism patients. NMPA registration streamlining for Class II rehabilitation equipment is opening access to domestic distribution channels. Yangtze River Delta medical device clusters are scaling manufacturing capacity for portable surface electrode stimulators.
United Kingdom
Private insurance co-payment structures incentivize spread-cost financing over upfront capital expenditure for home-use equipment. NHS England coverage determinations for home-based electrical stimulation remain under technology assessment review, creating revenue recognition uncertainty. London and Southeast private rehabilitation networks are accelerating subscription-based leasing adoption.
India
Emerging private rehabilitation chains are creating first-mover advantages for BIS-certified equipment suppliers. Mandatory BIS quality standards for electromedical equipment are formalizing import channels and filtering non-compliant foreign manufacturers. Maharashtra and Karnataka hospital procurement networks are expanding pelvic floor service lines for surgical recovery protocols.
Pelvic Floor Electrical Stimulation Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent distribution economics. The vendor base stratifies between heritage neuromodulation suppliers with established regulatory infrastructure and agile entrants leveraging subscription-based leasing to bypass capital barriers. Three archetypes dominate: implantable device heritage players with deep margin pools, portable unit specialists capturing home care expansion, and electrode accessory suppliers locking in recurring revenue streams. Consolidation pressure intensifies through EU MDR compliance cost escalation and FDA evidentiary standard tightening.
Among heritage neuromodulation suppliers, Medtronic plc and Boston Scientific Corporation occupy positions reflecting decades of implantable device portfolio development. Laborie, Inc. and TensCare Ltd. exemplify contrasting distribution strategies, with the former anchoring specialized urogynecology networks and the latter competing through direct-to-consumer pharmacy retail. Axonics Modulation Technologies, Inc. represents newer market entry attempting to carve position within sacral neuromodulation segments. Coloplast A/S and BTL Industries, Inc. sit within broader medical device portfolios where pelvic floor stimulation represents one vertical among multiple continence and rehabilitation product lines.
| Leading Market Players |
|---|
| Coloplast A/S |
| Laborie, Inc. |
| Medtronic plc |
| InControl Medical |
| The Prometheus Group |
| Boston Scientific Corporation |
| BTL Industries, Inc. |
| TensCare Ltd. |
| Axonics Modulation Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA premarket submission tightening functions as the dominant regulatory chokepoint determining both pricing tier spreads and supply chain shape. This evidentiary barrier compresses margins for unprepared manufacturers while concentrating procurement authority among heritage suppliers with established compliance infrastructure.
Pricing Analysis
Certification level creates the primary spread between FDA-cleared implantable systems and unregistered portable units. Three-tier pricing structure across premium, standard, and economy levels reflects EU MDR compliance status, post-market surveillance capability, and brand heritage in neuromodulation. Pricing pressure stems from subscription-based leasing models collapsing upfront capital barriers for home-use segments. Cash-constrained patients in private insurance markets exhibit highest price sensitivity, while German university hospital networks tolerate premium positioning for implantable lead systems.
Supply Chain Analysis
Contract manufacturing concentration rests with Yangtze River Delta electronics clusters and Bavarian precision component suppliers. Raw material dependencies center on medical-grade silicone for electrode pads, lithium-ion cells for portable power systems, and biocompatible alloys for implantable leads. Single-source vulnerability concentrates in FDA-registered sterilization facilities serving implantable device portfolios. Distribution runs through specialized urogynecology networks for institutional procurement and European pharmacy chains for direct-to-consumer electrode accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as home care substitution and telehealth integration create distinct competitive niches outside heritage hospital procurement networks. Postpartum recovery clinics and patient-managed protocols represent separable demand pools with divergent margin structures.
For Market Incumbents: Harden regulatory moats through accelerated EU MDR technical documentation investment and post-market surveillance infrastructure expansion. Consolidate electrode accessory supply relationships to lock in recurring revenue streams against pharmacy chain retail disintermediation. Sacral neuromodulation heritage positions command premium defense against Axonics Modulation Technologies and newer entrants lacking implantable device trial histories. For New Entrants and Emerging Players: India's emerging private rehabilitation chains offer the most penetrable geographic entry point given BIS certification formalization and medical tourism pathway development. Target tier-one Chinese city hospital procurement networks through NMPA streamlined Class II rehabilitation equipment review. Deploy telehealth-integrated portable units with embedded biofeedback sensors to bypass capital-intensive implantable device regulatory pathways entirely. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors electrode accessory specialists with pharmacy chain retail scale and recurring revenue predictability. Long-term viability over the next decade hinges on reimbursement coding decisions by national health technology assessment bodies. Monitor CMS Medicare coverage determinations and NHS England technology assessment reviews as primary inflection indicators for home-based electrical stimulation addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Premarket notification tightening extends timelines and freezes smaller developers from commercialization. |
| CE Marking Pathway | EU MDR Article 10 technical documentation mandates favor established post-market surveillance infrastructure. |
| Hospital System Partnership | German university hospital networks command premium reimbursement for implantable neuromodulation service lines. |
| Software Companion Development | Telehealth integration enables asynchronous clinician oversight and recurring platform revenue streams. |
| Reimbursement Strategy | Coverage determinations by Germany's G-BA and France's HAS shape home-based electrical stimulation market boundaries. |
Study Parameters
Initial hypotheses were tested against primary input from urogynecology clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. FDA 510(k) filings, EU MDR conformity assessment body records, CMS Medicare reimbursement databases, and hospital procurement transaction logs anchored quantitative sizing. Bottom-up installed base modeling and top-down epidemiology-based prevalence estimates were triangulated to resolve segmentation boundaries.
Demand-supply balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type capital intensity, end-user procurement channel, technology application maturity, and regional reimbursement policy cluster. CAGRs were derived from iterative convergence of patient population epidemiology, treatment protocol penetration curves, and device replacement cycle analysis. NMPA registration streamlining timelines and BIS certification formalization progress served as China-India specific forecast inputs.
Practitioners should monitor FDA premarket submission evidentiary standard evolution, EU MDR competitive exit acceleration, and national health technology assessment body coverage determination revisions for early signals. Forecasts reflect assumptions regarding telehealth integration adoption curves and subscription-based leasing model penetration. Quarterly review of CMS local coverage determination updates and NHS England technology appraisal pipeline status is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Single Use Contact Lenses Market