
 Electrical Stimulation Devices (Esds) Market | 2026-2036
Electrical Stimulation Devices (Esds) Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Stimulation Devices (Esds) Market Foresight
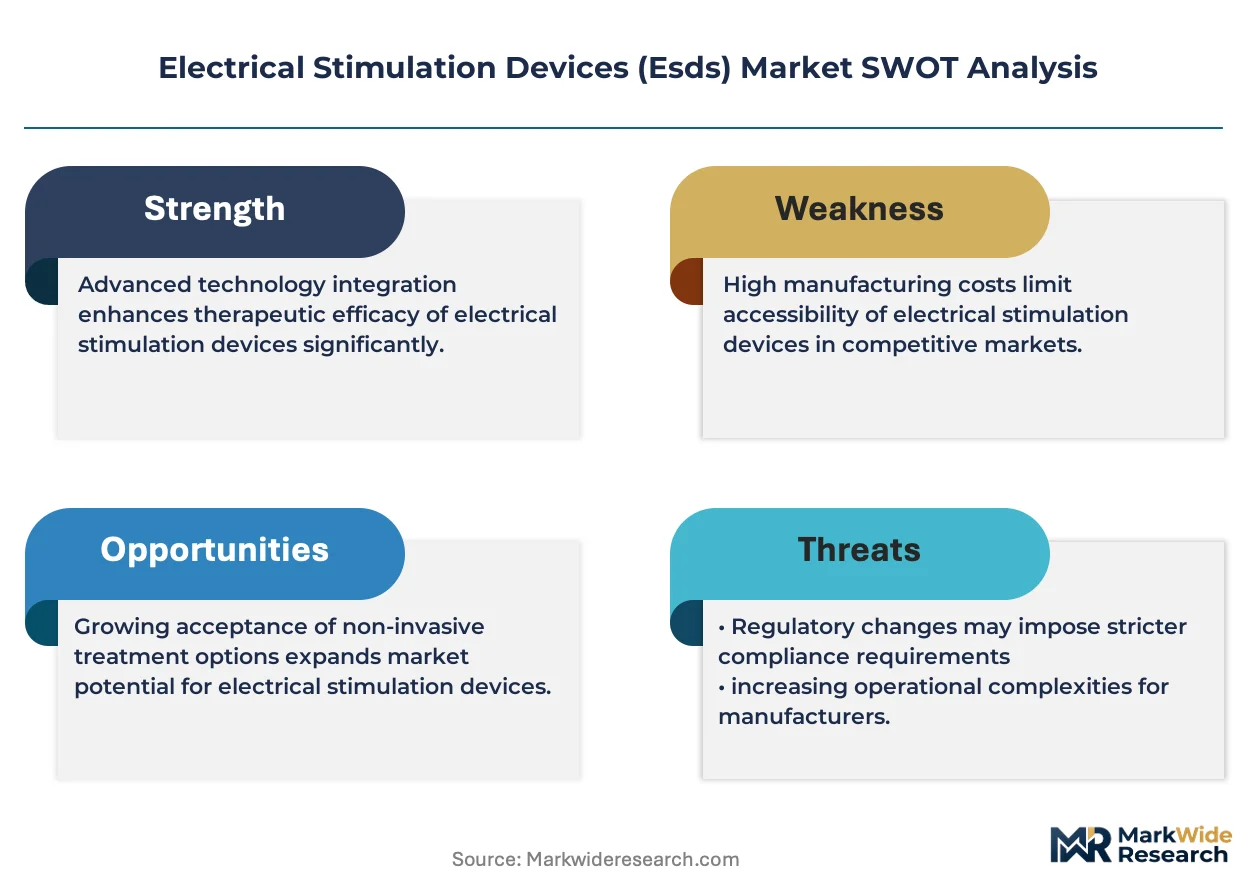
Software-defined dosing protocols is recalibrating what manufacturers bundle with hardware, shifting recurring revenue from device sales to algorithm subscriptions. Medtronic leverages its deep implantable portfolio to anchor premium service contracts across pain management centers. Boston Scientific competes through proprietary waveform libraries that lock clinicians into branded programming interfaces.
Electrical stimulation devices deliver controlled electrical impulses to nerves or muscles through surface electrodes or implanted leads, typically operating at frequencies between 1-150 Hz and pulse widths of 50-400 microseconds to modulate neural signaling or induce muscle contraction. The primary commercial purpose spans therapeutic pain blocking, motor function restoration, and tissue rehabilitation across clinical and home settings. Invasive electrical stimulation commands the highest margin pools due to surgical implantation requirements and long-term maintenance dependencies, while wearable devices represent the fastest-expanding delivery mode as lithium-ion miniaturization and Bluetooth connectivity enable prescription-grade monitoring outside facilities. Rehabilitation applications remain structurally mature in hospital settings but show accelerating displacement toward home care channels.
FDA premarket notification pathways and ISO 13485 quality management standards govern device commercialization in the United States, with the former dictating clinical evidence requirements that directly shape R&D budgets and market entry timelines. Europe's MDR and CE marking framework impose stricter post-market surveillance obligations that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor how FDA draft guidance on closed-loop adaptive stimulation alters the competitive bar for algorithm-driven systems.
Market Dynamics
Software-defined dosing protocols are recalibrating manufacturer revenue models, shifting hardware-centric sales toward recurring algorithm subscriptions that lock clinicians into proprietary programming ecosystems.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Pre-market notification timelines for wearable neuromodulation devices have compressed, accelerating commercialization for new entrants in pain management.
- German Statutory Reimbursement:Statutory health insurance coverage for electrotherapy remains among Europe's most generous, anchoring demand concentration in outpatient rehabilitation clinics.
- Lithium-Ion Miniaturization:Battery chemistry advances enable prescription-grade pulse delivery in palm-sized form factors, expanding clinical-grade monitoring beyond facility walls.
Market Restraints
- Implantable Surgical Costs:Invasive electrical stimulation requires operating theater infrastructure and specialized surgical training, limiting addressable patient pools to tertiary medical centers.
- European MDR Surveillance Burden:Stricter post-market clinical follow-up obligations under the Medical Device Regulation favor established players with dedicated regulatory affairs infrastructure.
- Non-Invasive Substitutes:Pharmacological pain management and physical therapy protocols retain physician familiarity and lower upfront patient cost barriers in primary care settings.
Strategic Opportunities
- Home Care Channel Expansion:Rehabilitation applications show accelerating displacement from hospital settings toward prescription-monitored home use, creating direct-to-patient logistics requirements.
- Closed-Loop Adaptive Stimulation:FDA draft guidance on real-time neural feedback algorithms is lowering the evidentiary bar for next-generation implantable systems that automatically adjust therapeutic output.
- Bluetooth-Enabled Remote Titration:Wireless connectivity integration allows clinicians to adjust waveform parameters without office visits, opening subscription-based remote monitoring revenue streams.
Industry Challenges
- ISO 13485 Quality System Complexity:Medical device quality management certification demands documented risk management processes that extend product development cycles by 12-18 months for new market entrants.
- Algorithm-Hardware Integration Talent Scarcity:The intersection of biomedical engineering and machine learning programming remains sparsely populated, constraining R&D velocity for adaptive stimulation platforms.
- Legacy EMR System Interoperability:Proprietary data formats from established electronic medical record vendors block seamless integration of stimulation device usage logs into centralized patient records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Stimulation Devices (Esds) Market |
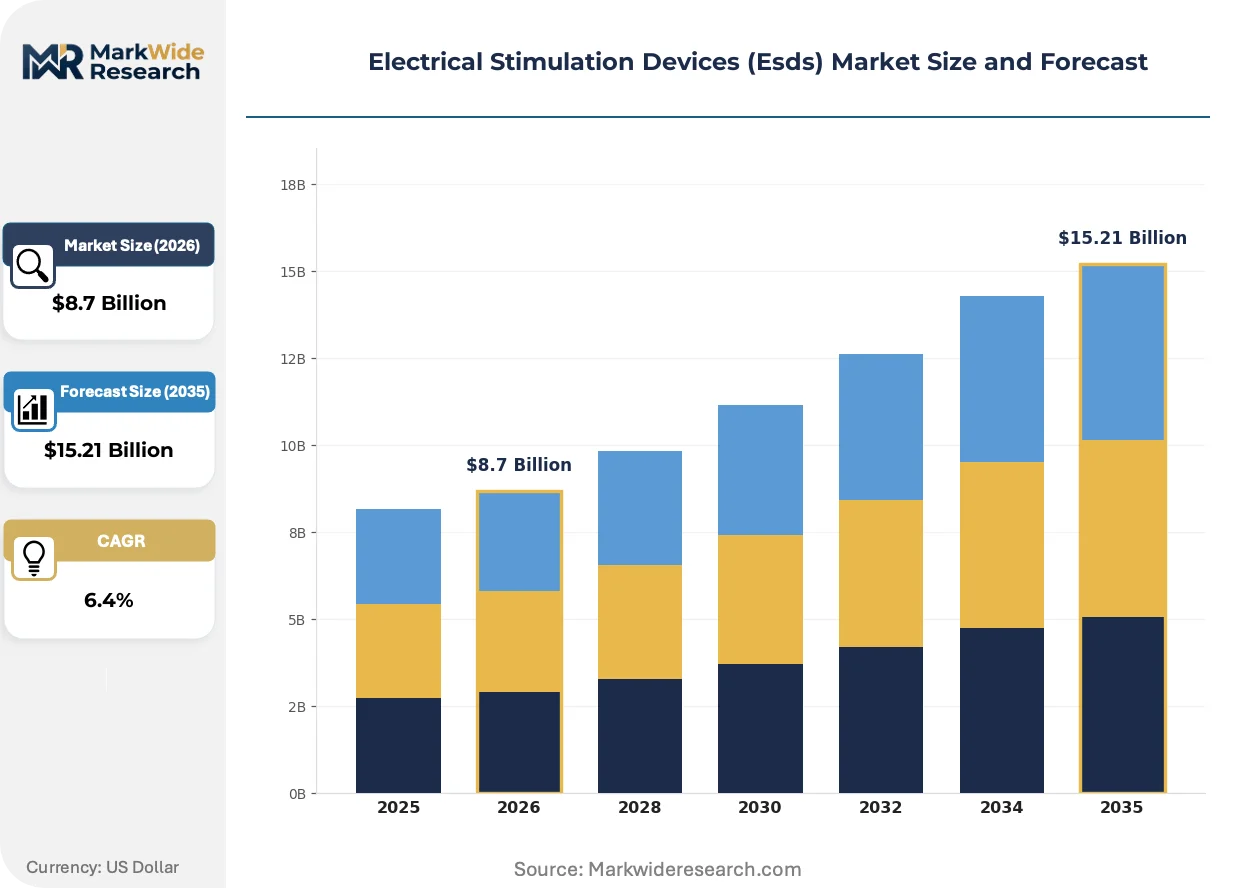
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcutaneous Electrical Nerve Stimulation, Functional Electrical Stimulation, Neuromuscular Electrical Stimulation, Invasive Electrical Stimulation Application: Pain Management, Rehabilitation, Muscle Stimulation, Electrotherapy End User: Hospitals, Rehabilitation Centers, Home Care, Sports Clinics Delivery Mode: Portable Devices, Tabletop Units, Wearable Devices, Stationary Systems |
| Companies Covered | Medtronic, Boston Scientific, Abbott Laboratories, Nevro, DJO Global, LivaNova, Bioness, BTL Industries, Zynex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Stimulation Devices (Esds) Market Shifts & Advancements
Waveform algorithm libraries are becoming the primary battleground for competitive differentiation, with proprietary software ecosystems now determining clinician switching costs more than hardware specifications.
Closed-loop adaptive stimulation is consolidating competitive positioning around real-time neural signal interpretation capabilities. Pain management centers in the United States are piloting these systems for chronic lower back conditions. The technology is consolidating vendor market power by embedding proprietary feedback algorithms that resist cross-platform migration.
Europe's Medical Device Regulation imposes expanded post-market clinical follow-up obligations that favor manufacturers with established pharmacovigilance infrastructure. Small and mid-sized device firms face disproportionate compliance cost burdens relative to revenue scale. Implantable neuromodulation categories are responding through strategic partnerships with contract research organizations to outsource surveillance data collection.
After-sales service unbundling is fragmenting traditional device-plus-maintenance contracting models. Hospital procurement departments now separately negotiate algorithm update subscriptions, hardware warranty extensions, and clinical training modules. Germany's rehabilitation clinic networks exhibit the most advanced service componentization, driven by statutory insurer pressure on facility operating margins.
Electrical Stimulation Devices (Esds) Market Segmentation
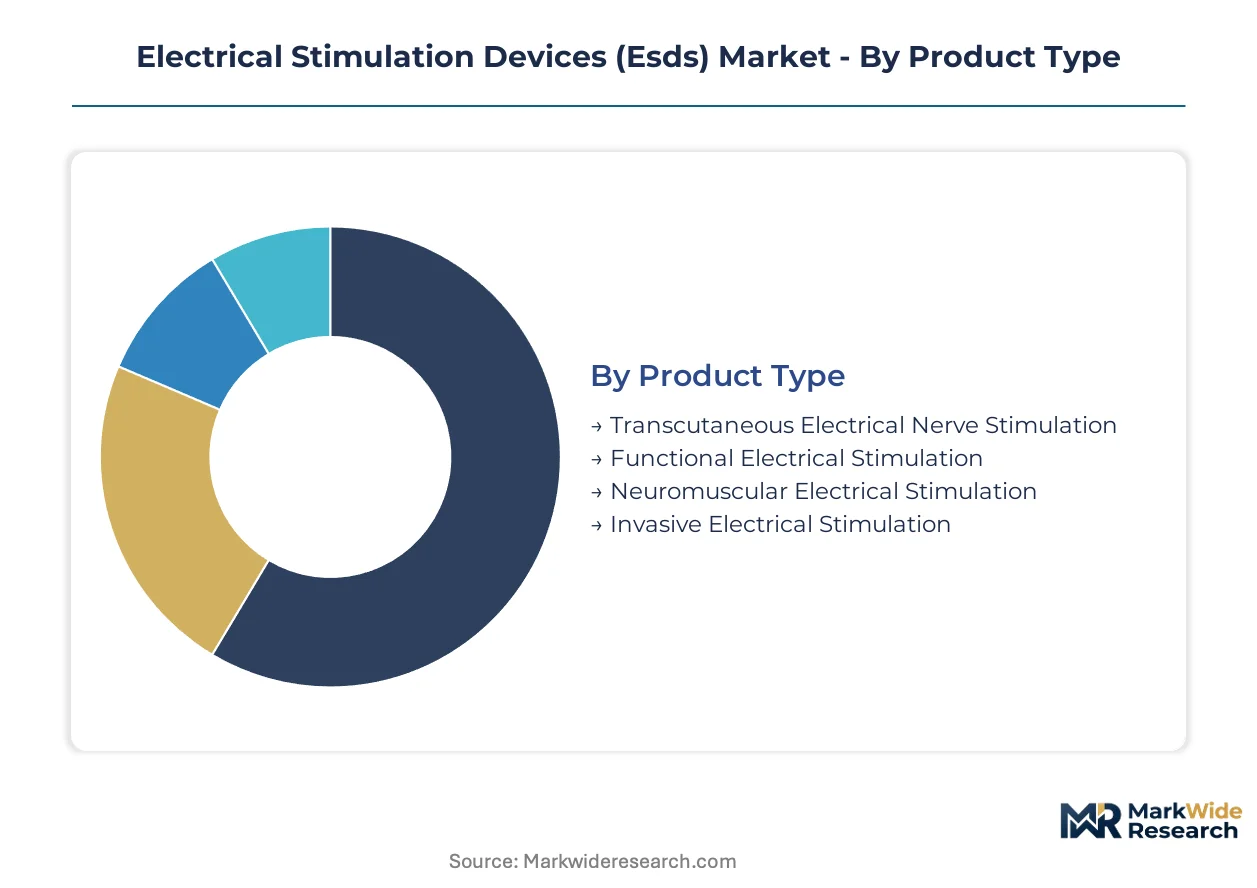
Segmentation in electrical stimulation devices reveals how regulatory pathways, reimbursement structures, and care delivery settings fragment commercial opportunity. Product complexity dictates certification burden, while end-user channel selection determines pricing power and service attach rates.
Product Type:
FDA 510(k) clearance timelines stretch longest for implantable systems requiring preclinical biocompatibility studies, while surface-based modalities navigate abbreviated review. CE marking under MDR imposes equivalent clinical evidence tiers across invasive categories.
- Transcutaneous Electrical Nerve Stimulation:Surface electrode systems delivering 1-150 Hz pulses through intact skin for nociceptive pathway interruption. Demand clusters in German outpatient rehabilitation clinics where statutory insurers reimburse electrotherapy sessions without prior authorization. Portable TENS units dominate home care channel expansion.
- Invasive Electrical Stimulation:Surgically implanted pulse generators with percutaneous leads targeting dorsal root ganglia or peripheral nerve trunks. Spinal cord stimulation systems command premium service contracts across United States pain management centers. Battery replacement cycles and programming dependencies lock patients into manufacturer ecosystems.
- Functional Electrical Stimulation:Patterned impulse sequences restoring motor function in hemiplegic or spinal cord injury patients. Stroke rehabilitation protocols in academic medical centers drive adoption.
- Neuromuscular Electrical Stimulation:Muscle fiber recruitment for strength maintenance and atrophy prevention. Sports medicine applications in professional athletic training facilities.
Leading the category by volume: Transcutaneous Electrical Nerve Stimulation. Growing fastest: Invasive Electrical Stimulation.
Application:
Reimbursement coding specificity varies sharply across clinical indications, with chronic pain diagnoses attracting more favorable physician fee schedules than wellness or performance applications.
- Pain Management:FDA-cleared modalities targeting neuropathic and nociceptive pain pathways through gate control or endogenous opioid release. United States pain clinics expanding portable device dispensing for home-based therapy. Prior authorization requirements for implantable systems limit penetration to tertiary referral networks.
- Rehabilitation:Motor function restoration following orthopedic surgery or neurological insult. Hospital discharge planners accelerating referral to home care channels for continued device-monitored exercise.
- Muscle Stimulation:Cosmetic and athletic performance applications with limited insurance coverage. Direct-to-consumer channels bypassing clinical prescription requirements.
- Electrotherapy:Broad diagnostic and therapeutic electrical applications in physical medicine. German statutory insurance reimbursement anchors European demand concentration.
Pain Management generates the highest absolute revenue. Rehabilitation shows the steepest expansion trajectory.
End User:
Procurement authority and service integration requirements diverge across facility types, with hospital value analysis committees demanding outcome data that home care distributors rarely provide.
- Hospitals:Inpatient and surgical suite deployment of implantable systems with captive anesthesia and neurosurgical support. Value-based purchasing metrics increasingly shape capital equipment committees.
- Home Care:Prescription-monitored portable devices with remote titration capabilities. Direct logistics requirements challenge traditional distributor relationships.
- Rehabilitation Centers:Outpatient electrotherapy protocols with therapist-supervised parameter adjustment. German clinic networks exhibit most advanced service componentization.
- Sports Clinics:Performance optimization and injury prevention applications. Cash-pay pricing outside insurance reimbursement structures.
Hospitals retain the largest installed base. Home Care is climbing the fastest.
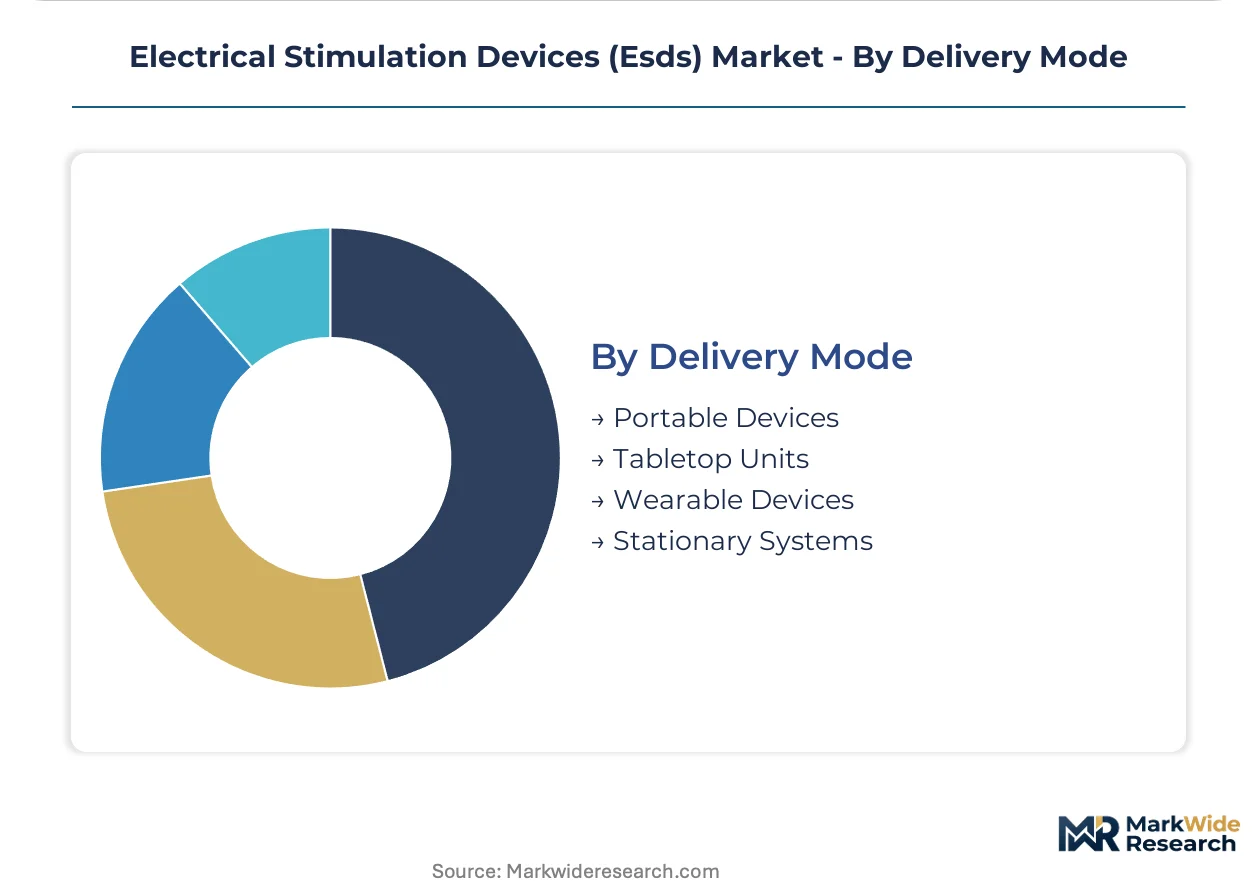
Delivery Mode:
Form factor miniaturization and wireless connectivity integration determine whether devices qualify for prescription-grade remote monitoring or remain confined to supervised clinical use.
- Wearable Devices:Garment-integrated or adhesive-patch systems with Bluetooth telemetry enabling real-time usage logging. FDA draft guidance on closed-loop adaptive stimulation favors algorithm-capable wearables.
- Portable Devices:Handheld units with rechargeable lithium-ion batteries bridging clinical and home settings. Pain management clinics in the United States expanding patient loaner programs.
- Tabletop Units:Clinic-based electrotherapy stations with multi-channel output and integrated EMG feedback. Physical therapy departments standardizing on interoperable platforms.
- Stationary Systems:Hardwired installations in dedicated rehabilitation suites with centralized parameter control. Hospital infrastructure investments favor modular upgrade paths.
Portable Devices dominate current shipment volumes. Wearable Devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of electrical stimulation devices clusters in the United States and Germany, while consumption spreads across outpatient rehabilitation networks in both markets plus expanding home care channels in Japan and Australia.
United States
Pain management clinics in Texas and Florida are expanding portable TENS dispensing programs for home-based therapy. FDA 510(k) pathway streamlining has compressed pre-market notification timelines for wearable neuromodulation devices. The Minneapolis-St. Paul corridor hosts concentrated implantable device engineering talent pools serving spinal cord stimulation system development.
Germany
Statutory health insurance reimbursement for electrotherapy remains Europe's most generous, anchoring outpatient rehabilitation clinic demand concentration. MDR post-market surveillance obligations favor established manufacturers with dedicated regulatory affairs infrastructure. The Bavaria region contains specialized physical medicine equipment fabricators supplying clinic networks across Baden-Württemberg and North Rhine-Westphalia.
Japan
Aging demographics are expanding addressable patient pools for motor function restoration devices in stroke rehabilitation protocols. PMDA regulatory frameworks maintain rigorous clinical evidence standards for implantable neuromodulation systems. The Kanto region around Tokyo hosts academic medical centers piloting closed-loop adaptive stimulation for chronic lower back conditions.
Australia
Sports medicine applications in professional athletic training facilities are driving neuromuscular electrical stimulation adoption outside reimbursement structures. TGA device registration requirements align with ISO 13485 quality management standards for market entry. Sydney and Melbourne rehabilitation clinic networks are standardizing on Bluetooth-enabled remote titration platforms for prescription-monitored home use.
United Kingdom
NHS value-based procurement frameworks are reshaping hospital capital equipment committee decision criteria for implantable systems. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while developing distinct UKCA conformity pathways. The London-Southeast corridor contains pain management centers transitioning from inpatient surgical suites toward outpatient device programming services.
Electrical Stimulation Devices (Esds) Market Competitive Landscape
Top-tier vendors anchor premium implantable segments, while mid-scale specialists concentrate on portable surface modalities. The competitive structure exhibits tiered consolidation around algorithm-hardware integration capabilities. Three archetypes dominate: diversified medical technology conglomerates with deep implantable portfolios, dedicated neuromodulation pure-plays with proprietary waveform libraries, and rehabilitation-focused device manufacturers emphasizing home care channel logistics. M&A activity targets algorithm talent acquisition, while strategic partnerships with contract research organizations address European MDR surveillance burdens.
Within the diversified conglomerate tier, Medtronic and Boston Scientific exemplify positioning around premium service contract anchoring across United States pain management centers. Abbott Laboratories occupies a distinct position spanning both implantable cardiac and neuromodulation device portfolios. These three entities represent the dominant competitive anchors shaping proprietary programming ecosystem dynamics and clinician switching cost structures.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Abbott Laboratories |
| Nevro |
| DJO Global |
| LivaNova |
| Bioness |
| BTL Industries |
| Zynex |
| Others |
Supply & Pricing Matrix
Lithium-ion miniaturization and algorithm-hardware integration are compressing production economics while concentrating component sourcing among battery chemistry specialists and semiconductor foundries with FDA quality system certifications.
Pricing Analysis
Margin tightening in portable surface modalities reflects algorithm subscription unbundling and hardware commoditization pressure from Asian contract manufacturers. Three-tier pricing structure across implantable premium, portable standard, and direct-to-consumer economy levels stratifies by certification grade and after-sales service bundling. Cost-down pressure on wearable units accelerates because German statutory insurers are squeezing clinic operating margins. Home care distributors exhibit highest price sensitivity; tertiary pain management centers demonstrate lowest.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital value analysis committees and German rehabilitation clinic networks require qualified secondary suppliers for pulse generators and lithium-ion cells. Manufacturing concentrates in the United States, Germany, and South Korea. Supply chains draw from rare earth magnet suppliers, medical-grade silicone fabricators, and Bluetooth chipset vendors. Single-source vulnerability sits with specialized neural signal processing ASICs. Distribution runs through GPO contracts for hospital systems and direct logistics for home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary algorithm development and captive electrode manufacturing is becoming the decisive competitive moat as hardware margins compress.
For Market Incumbents: Deploy exclusive waveform library licensing to lock clinicians into branded programming ecosystems. Consolidate position through strategic partnerships with contract research organizations to outsource European MDR post-market surveillance burdens. Counter emerging pure-play neuromodulation specialists by anchoring premium service contracts across United States pain management centers. For New Entrants and Emerging Players: Enter via prescription-monitored home care channels where direct-to-patient logistics requirements challenge legacy distributor relationships. Target Australian sports medicine applications and Japanese stroke rehabilitation protocols as underpenetrated white spaces. Pursue FDA 510(k) clearance for Bluetooth-enabled remote titration platforms as the fastest regulatory pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking algorithm talent and implantable device portfolios. Long-term viability hinges on adaptive stimulation platform capabilities and closed-loop neural feedback integration. Watch FDA draft guidance finalization on closed-loop adaptive stimulation as the signal indicating accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Subscription Unbundling | Shifts recurring revenue from device sales to proprietary software ecosystems. |
| MDR Surveillance Partnership | Outsources post-market clinical follow-up obligations to contract research organizations. |
| Home Care Channel Expansion | Creates direct-to-patient logistics requirements bypassing traditional distributor relationships. |
| Closed-Loop Adaptive Stimulation Development | Embeds proprietary feedback algorithms that resist cross-platform migration. |
| Bluetooth Remote Titration Integration | Enables subscription-based remote monitoring revenue streams without office visits. |
Research Methodology
Independent corroboration across primary interviews with biomedical engineers, pain management clinicians, hospital purchasing committee members, and GPO contracts managers, plus secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries, underwrites the qualitative findings. Bottom-up shipment modeling and top-down spending allocation triangulate market sizing.
Rate-of-change decomposition across the analysis window segments volume and value by product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to adoption data and pricing trajectory assumptions. Forecast inputs incorporate lithium-ion battery cost curves and statutory reimbursement rate revisions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance timeline delays or MDR enforcement intensity shifts. Deviation in German statutory insurance electrotherapy reimbursement rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
X-Ray Stretchers Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Alpha Emitter Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Global Holter ECG Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Global Digital Dose Inhaler Market