
 Next Generation Implants (NGI) Market | 2026-2036
Next Generation Implants (NGI) Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Implants (NGI) Market Outlook
European contract manufacturers is shifting toward additive production of titanium lattice structures for patient-specific orthopedic hardware. Zimmer Biomet leverages its Warsaw, Indiana manufacturing base to sustain high-volume output of knee and hip reconstruction systems. Medtronic anchors its cardiovascular implant portfolio through deep integration with electrophysiology catheter workflows. Abbott Laboratories differentiates in structural heart repair through transcatheter mitral valve platforms that bypass open-chest procedures.
Next Generation Implants encompass biocompatible devices engineered from titanium alloys, cobalt-chrome, PEEK polymers, and resorbable magnesium composites, manufactured via precision machining or electron beam melting to restore physiological function in bone, cardiac, neural, or dental tissue. Orthopedic implants dominate current revenue flow due to procedural volume in joint replacement and spinal fusion, while smart implants embedding biosensors and wireless telemetry represent the fastest-expanding margin pool as remote patient monitoring reimbursement matures. 3D printing solutions occupy a structurally critical position because geometric complexity at no marginal cost enables anatomically matched devices that reduce revision surgery rates.
FDA premarket approval pathways and the EU Medical Device Regulation impose clinical evidence thresholds that filter out undercapitalized developers and elongate commercialization timelines for novel implantable electronics. ISO 13485 quality management systems and ASTM F2077 cardiovascular device standards further constrain supplier qualification, favoring incumbents with established regulatory affairs infrastructure. Stakeholders must monitor reimbursement decisions by CMS and Germany's G-BA, as these determinations shape whether hospitals adopt premium-priced smart implant platforms over conventional alternatives.
Market Dynamics
The convergence of additive manufacturing with patient-specific anatomical modeling is compressing product development cycles and collapsing the traditional economies-of-scale advantage held by high-volume orthopedic manufacturers.
Growth Catalysts
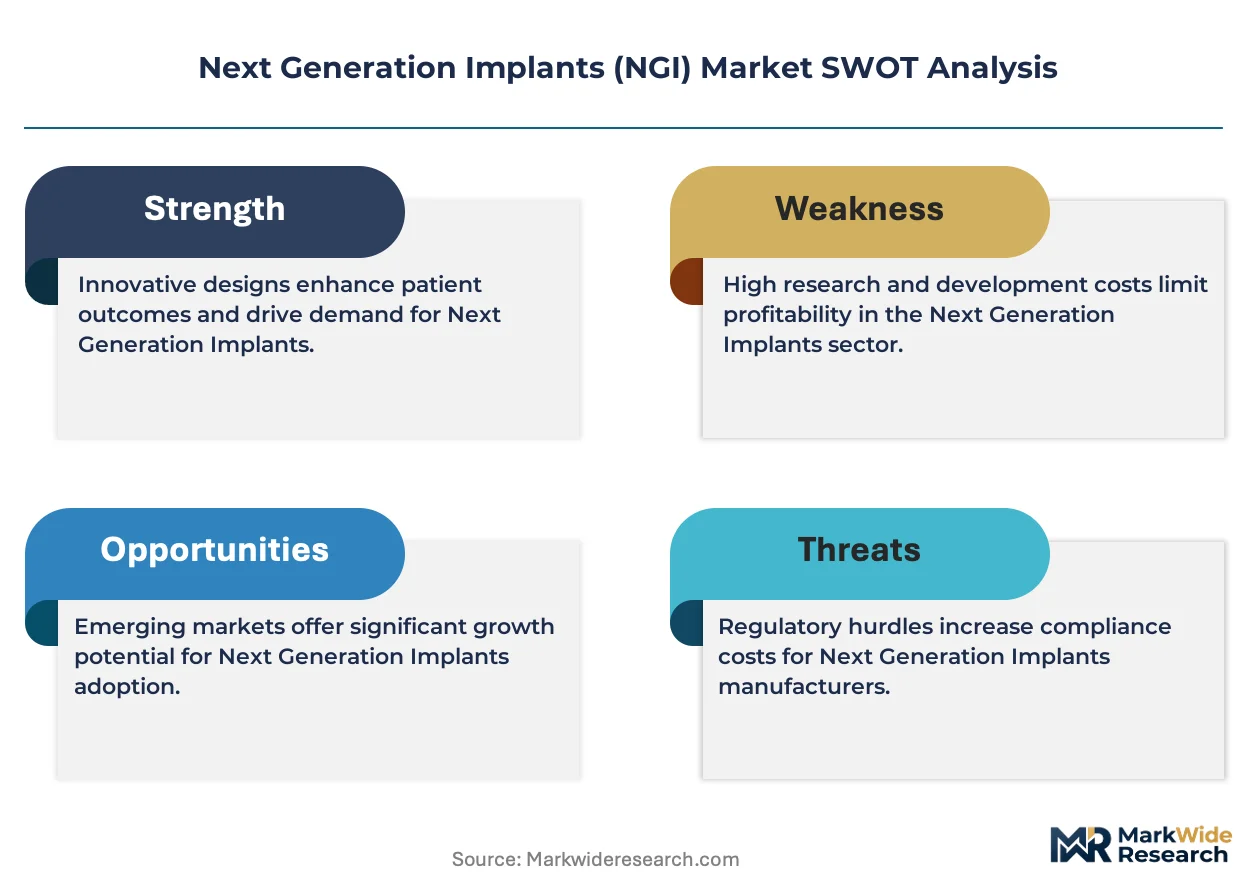
- Remote Patient Monitoring Reimbursement:CMS coverage determinations for implantable biosensors are creating sustainable revenue streams for smart cardiac and orthopedic devices in the United States.
- EU Medical Device Regulation:MDR Article 10 clinical evidence requirements are accelerating consolidation toward manufacturers with established notified body relationships and post-market surveillance infrastructure.
- Titanium Lattice Additive Production:Electron beam melting of patient-matched porous structures is reducing revision surgery rates in complex pelvic and spinal reconstruction cases.
Market Restraints
- Supply Concentration in Electron Beam Systems:Arcam and EOS equipment dominance creates procurement bottlenecks for contract manufacturers scaling titanium lattice production.
- Clinical Validation Timelines:FDA premarket approval pathways for novel implantable electronics impose 18-36 month evidence generation periods that filter undercapitalized developers.
- Bioresorbable Magnesium Degradation Control:Unpredictable corrosion kinetics in physiological environments limit structural heart and craniofacial applications despite theoretical advantages.
Strategic Opportunities
- Japan's Super-Aged Society:METI's healthcare robotics and implant innovation subsidies target 80+ demographic procedural volumes in hip fracture and degenerative spinal disease.
- Transcatheter Mitral Valve Repair:Structural heart platforms bypassing sternotomy are capturing surgical-eligible patients previously managed pharmacologically.
- Neural Implant Convergence:Integration of closed-loop neuromodulation with AI-driven seizure prediction algorithms is opening epilepsy and movement disorder indications.
Industry Challenges
- Regulatory Affairs Talent Scarcity:ISO 13485 quality management and FDA Q-Sub navigation expertise concentrates among incumbent manufacturers, constraining startup commercialization velocity.
- Post-Market Surveillance Infrastructure:MDR mandates for implant registries and unique device identification require capital deployment that mid-tier manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Implants (NGI) Market |
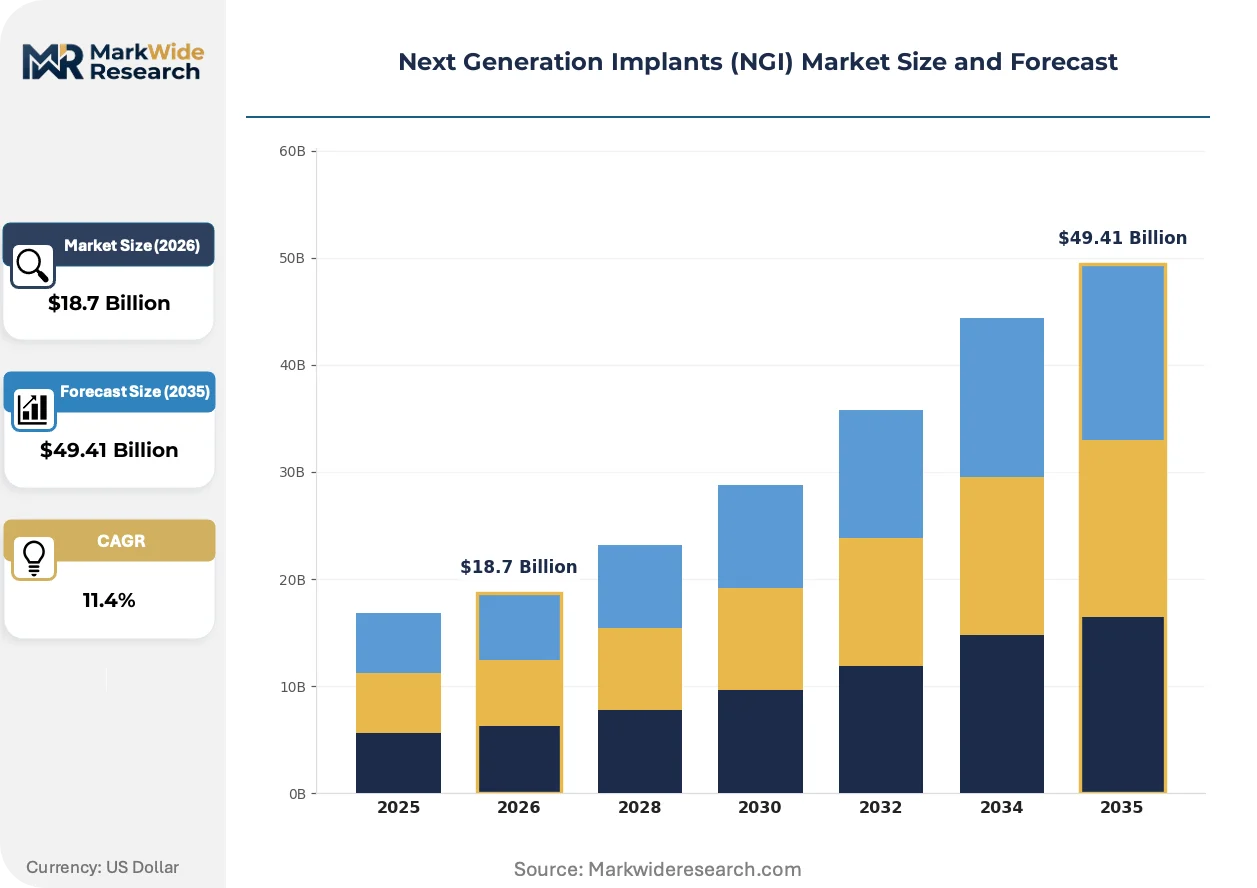
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Implants, Dental Implants, Cardiovascular Devices, Neurostimulators Technology: Biodegradable Materials, Smart Implants, 3D Printing Solutions, Coatings Technology End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Rehabilitation Facilities Application: Joint Replacement, Spinal Surgery, Cosmetic Enhancements, Dental Procedures |
| Companies Covered | Zimmer Biomet, Boston Scientific Corporation, Abbott Laboratories, Edwards Lifesciences Corporation, Arthrex, Medtronic, Johnson & Johnson, Globus Medical, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Implants (NGI) Market Strategic Shifts
Digital thread integration from preoperative imaging through postoperative monitoring is collapsing the traditional boundaries between device manufacturing and clinical service delivery, creating new margin pools for integrated platform providers.
Electron beam melting of titanium lattice structures is consolidating orthopedic implant production around geometrically complex, patient-matched devices that eliminate the cost advantage of standardized inventory. Academic medical centers in Germany and the United States are adopting these platforms for complex revision arthroplasty and spinal deformity cases. The technology is consolidating supplier relationships toward additive specialists with in-house metallurgical qualification capabilities and direct hospital contracting authority.
EU Medical Device Regulation's Article 10 clinical evaluation requirements are compressing the viable manufacturer base by imposing evidence thresholds that disproportionately burden novel implantable electronics. Notified body capacity constraints in Germany and the Netherlands are extending technical documentation review timelines. Cardiovascular implant developers are responding by front-loading clinical trials and acquiring post-market surveillance databases to satisfy MDR recertification demands.
Hospital procurement committees are unbundling implant supply from traditional distributor relationships and negotiating direct manufacturer contracts with performance guarantees on revision rates. This pattern concentrates purchasing authority at integrated delivery networks in the United States and hospital groups in Germany. The shift is most visible in knee and hip reconstruction, where volume commitments secure preferential pricing and dedicated surgical support teams.
Next Generation Implants (NGI) Market Segmentation
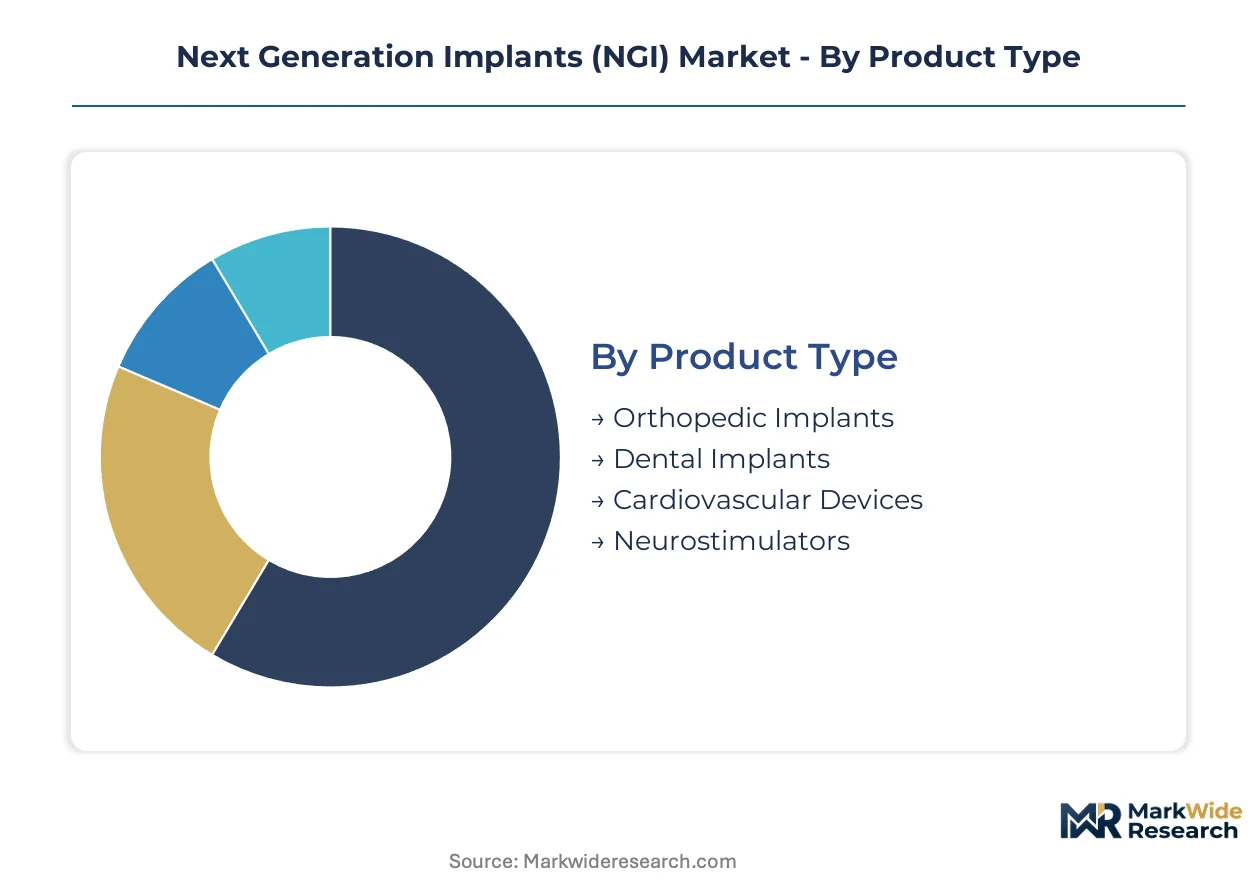
Segmentation in Next Generation Implants separates high-volume procedural categories from premium technology platforms with divergent margin profiles and regulatory pathways. Understanding these divisions reveals where capital deployment concentrates and which patient populations drive sustainable revenue.
Product Type:
Orthopedic implants command procedural volume while cardiovascular platforms capture premium pricing through minimally invasive delivery systems.
- Orthopedic Implants:Titanium alloy and cobalt-chrome constructs for joint reconstruction and spinal fusion dominate hospital purchasing volume. Demand concentrates in the United States and Germany where aging demographics sustain knee and hip replacement procedures, though revision surgery rates pressure manufacturers toward patient-matched additive solutions.
- Cardiovascular Devices:Structural heart platforms including transcatheter valves and electrophysiology-integrated implants command the highest per-procedure revenue. Japanese and German hospital systems prioritize these devices for octogenarian patients previously excluded from open-chest surgery.
- Dental Implants:Titanium root-form fixtures and zirconia abutments address edentulism in aging populations.
- Neurostimulators:Closed-loop neuromodulation devices for epilepsy and movement disorders represent an emerging therapeutic category.
Today's leader: Orthopedic Implants. Tomorrow's challenger: Cardiovascular Devices.
Technology:
Technology segmentation tracks the shift from passive mechanical devices toward active, data-generating implantable systems with recurring revenue potential.
- Smart Implants:Biosensor-embedded devices with wireless telemetry enable remote patient monitoring reimbursement under CMS frameworks. Cardiac and orthopedic applications in the United States are climbing the fastest as integrated delivery networks negotiate performance-based contracts.
- 3D Printing Solutions:Electron beam melting of titanium lattice structures produces patient-matched geometries without tooling cost penalties. German academic medical centers adopt these platforms for complex pelvic reconstruction where standardized inventory fails.
- Biodegradable Materials:Magnesium and polymer composites designed for controlled resorption in craniofacial and pediatric applications.
- Coatings Technology:Antimicrobial and osteoconductive surface treatments reduce implant-associated infection rates.
Smart Implants capture the steepest expansion trajectory as reimbursement frameworks mature for remote monitoring.
End User:
End user segmentation reflects the consolidation of purchasing authority toward integrated networks with direct manufacturer contracting power.
- Hospitals:Academic medical centers and community hospital systems in the United States and Germany concentrate procurement volume for joint replacement and spinal fusion. These institutions negotiate performance guarantees on revision rates, unbundling supply from traditional distributor relationships.
- Specialty Clinics:Orthopedic and dental-focused facilities in Japan target the super-aged demographic with streamlined procedural workflows.
- Ambulatory Surgical Centers:Outpatient settings capturing migration of lower-acuity implant procedures from inpatient facilities.
- Rehabilitation Facilities:Post-acute settings integrating implant performance data into recovery protocols.
Hospitals dominate current purchasing volume. Ambulatory Surgical Centers represent the structural shift in care delivery location.
Application:
Application segmentation distinguishes between medically necessary reconstruction and elective enhancement procedures with divergent reimbursement stability.
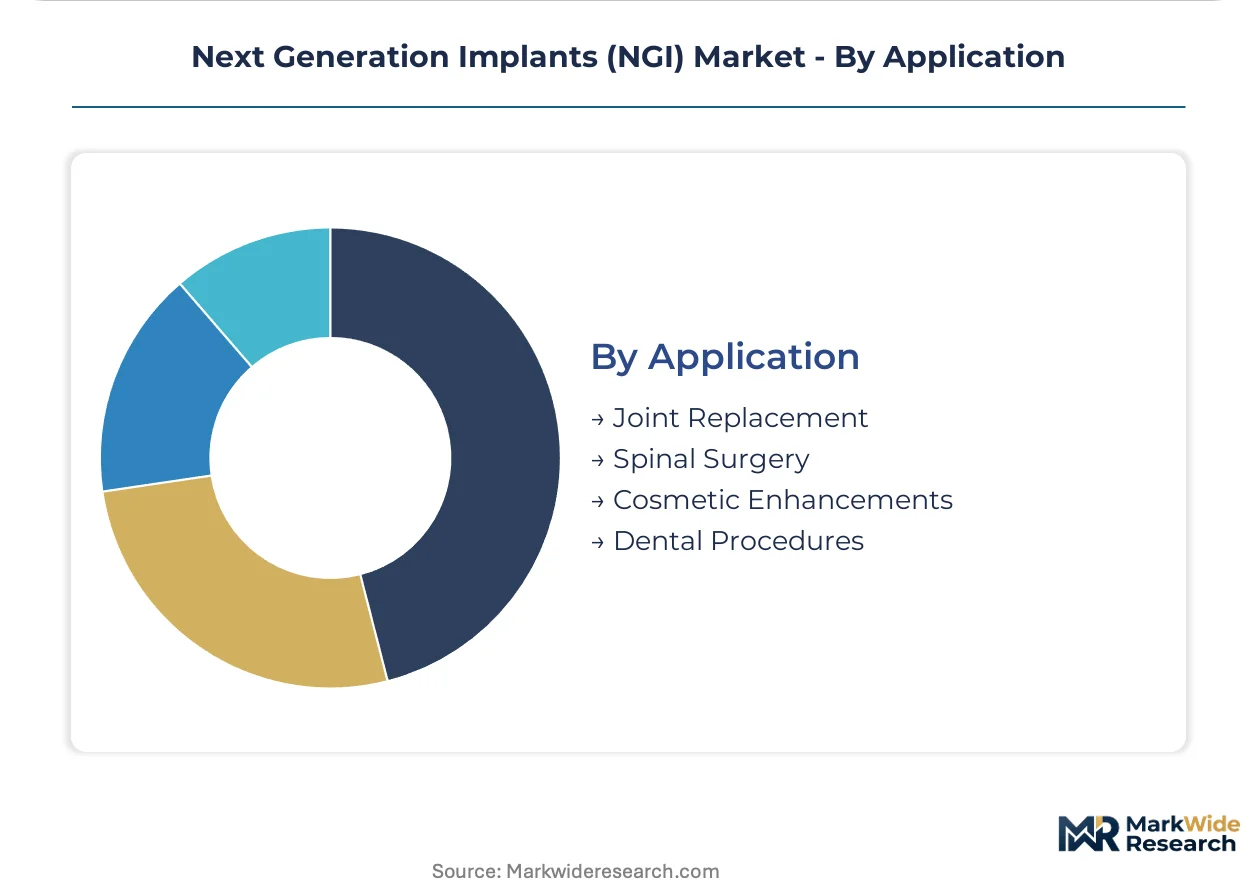
- Joint Replacement:Knee and hip arthroplasty generates the highest absolute procedure volume globally. German and United States reimbursement frameworks favor these interventions for mobility preservation in aging populations, though hospital procurement committees increasingly demand volume-commitment pricing.
- Spinal Surgery:Deformity correction and fusion procedures command premium implant pricing due to anatomical complexity. Japanese demand for degenerative disease intervention is expanding most quickly under METI healthcare innovation subsidies.
- Cosmetic Enhancements:Aesthetic implant procedures including facial reconstruction and elective augmentation.
- Dental Procedures:Implant-supported prosthetics for functional and aesthetic oral rehabilitation.
Joint Replacement anchors current revenue. Spinal Surgery offers the premium pricing resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting additive manufacturing capacity toward jurisdictions where FDA premarket approval costs exceed EU MDR compliance burdens, with contract manufacturers establishing titanium lattice production in Germany and the Netherlands to serve both markets.
United States
CMS reimbursement determinations for implantable biosensors are accelerating smart cardiac device adoption among integrated delivery networks. FDA premarket approval pathways impose 18-36 month clinical validation timelines that filter undercapitalized developers. Warsaw, Indiana anchors high-volume knee and hip reconstruction manufacturing through established orthopedic OEM supply relationships.
Germany
G-BA reimbursement frameworks favor minimally invasive implant procedures for aging populations in North Rhine-Westphalia and Bavaria. EU MDR Article 10 clinical evidence requirements are compressing the viable manufacturer base toward established notified body relationships. Academic medical centers in Berlin and Munich are adopting electron beam melting platforms for complex pelvic reconstruction cases.
Japan
METI healthcare robotics and implant innovation subsidies target procedural volumes among the 80-plus demographic for hip fracture and degenerative spinal disease. PMDA regulatory pathways for smart implantable devices are accelerating clinical validation timelines relative to historical benchmarks. The Kansai region around Osaka concentrates precision machining capacity for titanium alloy constructs.
Switzerland
Swissmedic regulatory frameworks for cardiovascular implantables attract developers seeking parallel FDA-EMA validation pathways. The country's precision manufacturing heritage supports cobalt-chrome and PEEK polymer device production. Zurich and Basel host specialized contract manufacturers serving structural heart and neurostimulation segments.
Next Generation Implants (NGI) Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart implantable electronics and patient-matched additive solutions. The market structure concentrates around three archetypes: diversified orthopedic conglomerates with Warsaw and Memphis manufacturing bases, cardiovascular specialists integrating electrophysiology workflows, and additive manufacturing contract specialists with electron beam melting qualifications. M&A activity targets post-market surveillance databases and notified body relationships, while capacity expansion focuses on titanium lattice production for complex revision cases.
Among diversified orthopedic manufacturers, Zimmer Biomet and Stryker occupy positions anchored to high-volume joint reconstruction systems. Medtronic exemplifies the cardiovascular-integrated archetype through its electrophysiology catheter workflow alignment. Boston Scientific Corporation sits within the structural heart specialist tier alongside Edwards Lifesciences Corporation.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| Arthrex |
| Medtronic |
| Johnson & Johnson |
| Globus Medical |
| Stryker |
| Others |
Value Chain & Pricing Dynamics
Titanium sponge price indices from the London Metal Exchange cascade through electron beam melting contract manufacturers into three-tier pricing structures across premium, standard, and economy implant tiers. Hospital procurement committees in Germany and the United States exploit this transparency to negotiate volume-commitment discounts that compress distributor margins.
Pricing Analysis
Distributor margins have compressed from traditional orthopedic supply arrangements toward direct-to-hospital contracts with performance guarantees. Pricing stratifies across premium patient-matched additive constructs, standard machined titanium inventory, and economy cobalt-chrome alternatives differentiated by ISO 13485 certification tier and revision-rate warranty terms. Cost compression in standard-tier joint replacement is intensifying because Warsaw-based manufacturers compete for integrated delivery network volume commitments. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement for complex revision cases, while ambulatory surgical centers drive hardest bargain on standardized hip and knee systems.
Supply Chain Analysis
Electron beam melting equipment supply rests on Swedish and German capital equipment producers, creating single-source vulnerability for contract manufacturers scaling titanium lattice production. Raw material flows draw from titanium sponge processors in Japan and China, cobalt-chrome alloy specialists in Germany, and PEEK polymer compounders in the United Kingdom. Tariff exposure on Chinese titanium sponge imports threatens margin stability for mid-tier orthopedic manufacturers. Distribution runs through specialized orthopedic distributors in the United States and direct manufacturer contracts with hospital groups in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Next Generation Implants market reads as a late-cycle quality story where hospital procurement committees reward patient-matched additive solutions with premium pricing and long-term supply contracts.
For Market Incumbents: Deepen backward integration into electron beam melting capacity to defend margin position against additive manufacturing contract specialists. Secure notified body relationships under EU MDR Article 10 to accelerate recertification timelines as regulatory affairs talent scarcity filters out undercapitalized competitors. Anchor Warsaw and Memphis manufacturing bases with dedicated surgical support teams that lock in integrated delivery network volume commitments. For New Entrants and Emerging Players: Smart implant biosensor platforms with wireless telemetry represent the most penetrable wedge for reimbursement-driven revenue streams under CMS remote patient monitoring frameworks. Target ambulatory surgical center migration of lower-acuity orthopedic procedures with streamlined inventory-light delivery models. Pursue direct hospital contracting authority in German academic medical centers where patient-matched pelvic reconstruction demand outstrips established supplier capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with additive manufacturing contract specialists holding electron beam melting qualifications and direct hospital relationships in Germany and the United States. Long-term viability over the next decade hinges on post-market surveillance database ownership that satisfies MDR recertification demands. Watch CMS coverage determinations for implantable biosensors as the inflection signal for smart implant platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Notified Body Relationship Acquisition | Accelerates technical documentation review timelines for cardiovascular implant developers facing Article 10 evidence thresholds. |
| Electron Beam Melting Capacity Expansion | Captures patient-matched orthopedic demand from German academic medical centers adopting titanium lattice platforms. |
| Post-Market Surveillance Database Buildout | Satisfies EU MDR recertification mandates that disproportionately burden novel implantable electronics developers. |
| CMS Reimbursement Strategy Development | Unlocks sustainable revenue streams for smart cardiac and orthopedic devices under remote patient monitoring frameworks. |
| Hospital System Partnership Formation | Secures performance-guaranteed direct contracts that unbundle supply from traditional orthopedic distributor relationships. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation against FDA premarket approval filings, EMA MDR submission databases, CMS coverage determination records, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue analysis.
Historical reference periods anchored the projection horizon through modeled segmentation across product type, technology platform, end-user facility class, and application indication with geographic regulatory cluster overlays. CAGRs derived from elasticity-adjusted demand curves incorporating aging demographic projections, reimbursement framework evolution, and additive manufacturing adoption curves. Industry-specific inputs included revision surgery rate data from orthopedic registries and smart implant biosensor clinical validation timelines.
The model holds under stable CMS and G-BA reimbursement conditions; deviation in FDA premarket approval timeline extensions or EU notified body capacity constraints would shift commercialization velocity assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implant Handpiece Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
ETCO2 Masks Market
Medical Devices
T-Piece Resuscitator Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Heating Pads Market
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Artificial Respirator Market
Medical Devices
Cardioscope Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
Global Medical Sensor Market