
 Guide Extension Catheter Market | 2026-2036
Guide Extension Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Guide Extension Catheter Market Intelligence
ISO 13485 quality management certification is redrawing competitive boundaries for guide extension catheter suppliers, filtering out contract manufacturers lacking documented design controls and risk management systems. Boston Scientific Corporation leverages in-house extrusion capabilities to sustain margin control across its catheter portfolio. Terumo Corporation anchors its position through specialized hydrophilic coating technology developed at its Japanese research centers. Medtronic competes by dominating hospital purchasing networks across North American integrated delivery systems.
A guide extension catheter is a long, thin, flexible tubular device designed to extend the working length of standard guiding catheters during percutaneous interventions, typically constructed from polyether block amide or nylon multilayer shafts with stainless steel braid reinforcement to balance pushability and torque response. Its primary purpose is to provide backup support and deep vessel access when anatomical tortuosity or calcified lesions prevent adequate guiding catheter engagement. Multi-lumen configurations command premium positioning due to their utility in simultaneous device delivery during chronic total occlusion procedures, while single-lumen variants occupy high-volume standard intervention segments. Hydrophilic coating technology leads technology-based differentiation, with flexible shaft designs gaining fastest adoption in radial access workflows where catheter kink resistance determines procedural success.
FDA 510(k) clearance requirements and EU MDR conformity assessment procedures shape product development timelines and commercial launch sequencing for guide extension catheter manufacturers, with notified body capacity constraints in Europe extending certification cycles. Japan's PMDA pharmaceutical and medical device agency maintains distinct master file requirements that condition market entry for foreign suppliers. Stakeholders must monitor evolving MDR clinical evidence expectations and FDA guidance on catheter-based device interoperability as these frameworks determine which product architectures achieve sustainable commercial access.
Market Dynamics
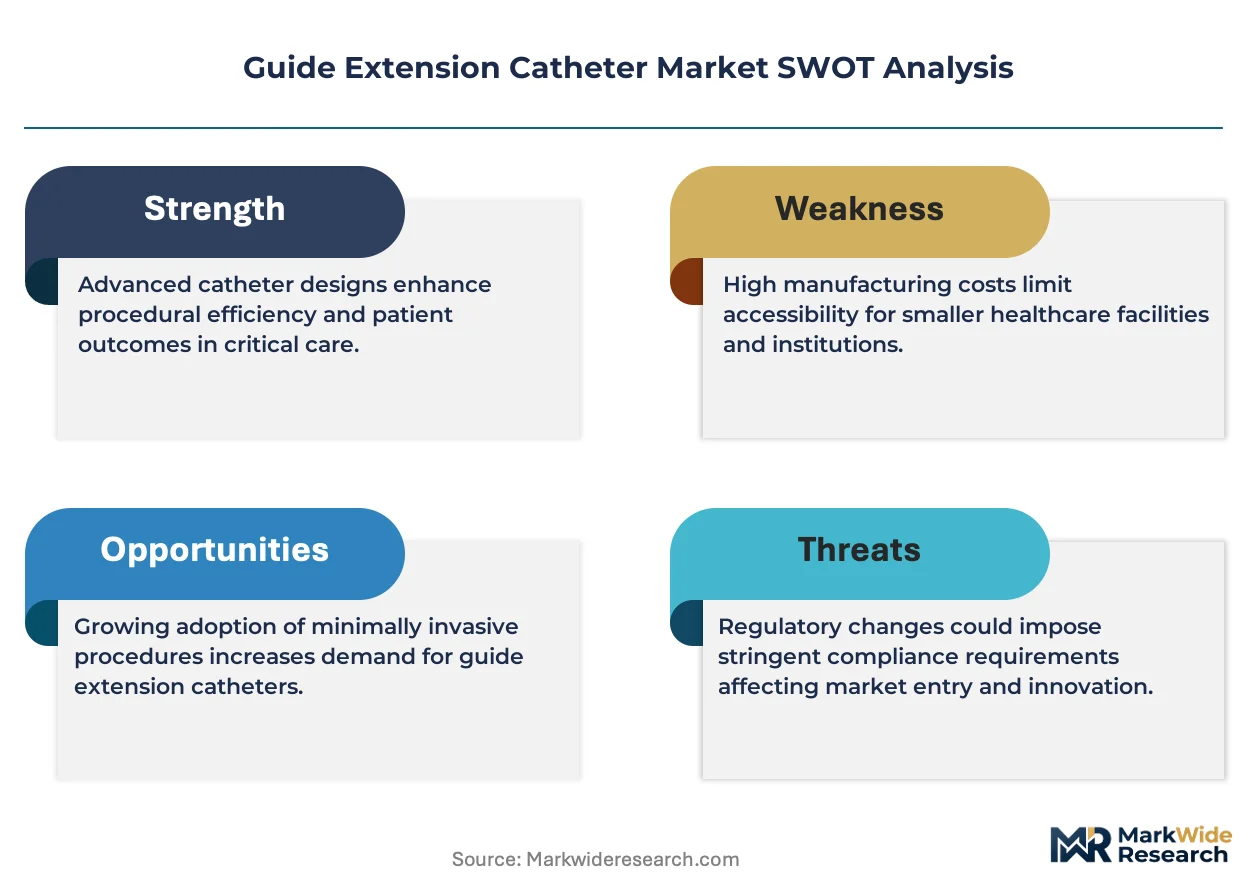
The guide extension catheter market is undergoing structural compression as EU MDR conformity assessment timelines extend certification cycles beyond historical norms, forcing manufacturers to pre-position clinical evidence portfolios before commercial launch windows.
Growth Catalysts
- Chronic total occlusion procedural volume:Complex PCI cases requiring multi-lumen catheter configurations are expanding hospital catheterization lab throughput in tertiary cardiac centers across Germany and Japan.
- MDR Article 61 clinical evidence requirements:Stricter conformity standards are filtering out marginal suppliers, consolidating qualified vendor pools and protecting pricing power for ISO 13485-certified manufacturers.
- Hydrophilic coating advancement:Terumo's specialized surface technology reduces vessel trauma during radial access procedures, accelerating adoption in Japan's aging patient population.
Market Restraints
- Polyether block amide resin concentration:Specialty polymer supply chains cluster among European and Japanese chemical suppliers, exposing shaft manufacturers to input cost volatility.
- PMDA master file complexity:Japan's pharmaceutical and medical device agency maintains distinct documentation requirements that extend foreign supplier market entry timelines.
- Balloon-expandable stent delivery systems:Integrated device platforms with built-in extension capabilities threaten standalone catheter demand in standard intervention segments.
Strategic Opportunities
- India's CDSCO regulatory pathway:Underpenetrated interventional cardiology infrastructure in tier-2 cities creates first-mover positioning for manufacturers establishing local technical service networks.
- Bioresorbable scaffold compatibility:Next-generation coronary devices require specialized catheter support during deployment, opening premium application segments.
- Direct-to-hospital digital procurement:Integrated delivery networks in the United States are consolidating purchasing through centralized platforms, favoring suppliers with EDI-capable order fulfillment systems.
Industry Challenges
- Notified body capacity constraints:EU MDR implementation has overwhelmed TÜV SÜD and BSI certification queues, delaying product launches by 12-18 months for manufacturers without established MDR technical files.
- Interoperability validation:FDA guidance on catheter-based device compatibility requires extensive bench testing against competitor guiding catheter platforms, inflating R&D expenditure without guaranteed commercial return.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guide Extension Catheter Market |
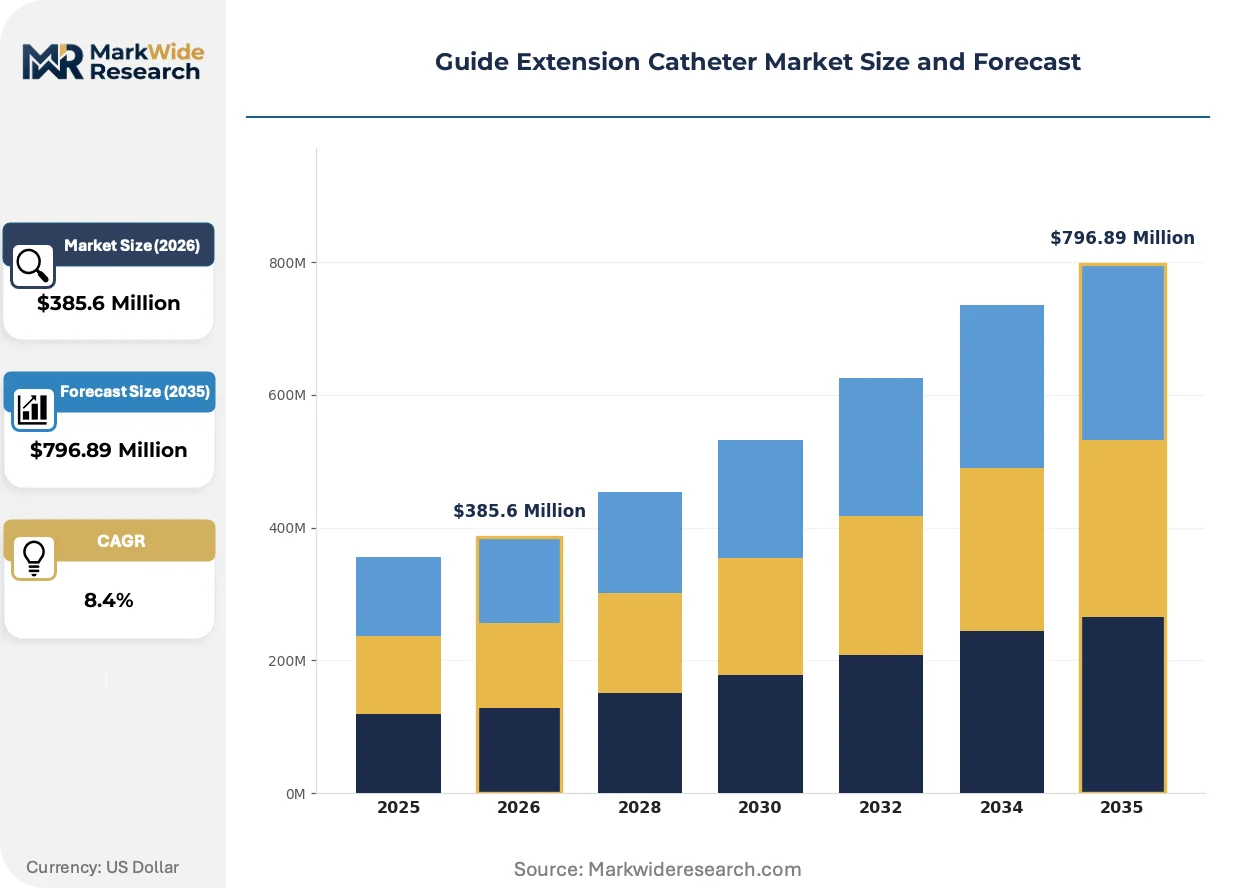
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Multi-Lumen, Specialty Guide, Customizable Designs Technology: Hydrophilic Coating, Biodegradable Materials, Flexible Shaft, Radiopaque Features End User: Hospitals, outpatient centers, Surgical Clinics, Diagnostic Labs Application: Cardiology, Neurology, Urology, Peripheral Vascular |
| Companies Covered | QXMédical, Terumo Corporation, Boston Scientific Corporation, IMDS (Interventional Medical Device Solutions), Nipro Corporation, Medtronic, Seigla Medical, Inc., BIOTRONIK, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guide Extension Catheter Market Strategic Shifts & Innovations
Active transformation in guide extension catheter design is compressing product lifecycles as manufacturers race to satisfy simultaneous demands for radial access compatibility and chronic total occlusion support capability.
Multi-lumen shaft architectures are bifurcating the competitive landscape. These configurations enable simultaneous guidewire and microcatheter positioning during complex revascularization. Interventional cardiologists in high-volume Japanese and German centers are specifying dual-lumen designs for over half of CTO cases. The technology is bifurcating premium positioning from standard single-lumen commoditization.
EU MDR clinical evidence requirements are restructuring product development economics. Manufacturers must now compile systematic literature reviews and post-market clinical follow-up protocols before CE marking. Smaller suppliers lacking dedicated regulatory affairs functions are outsourcing conformity assessment preparation to specialized consultancies in Ireland and Switzerland, inflating fixed costs per product iteration.
Hospital procurement consolidation is compressing vendor relationships. Integrated delivery networks in the United States are mandating sole-source agreements for catheter portfolios, replacing multi-vendor competitive bidding. Cardiovascular service line administrators now prioritize suppliers offering standardized pricing across affiliated facilities, visible most acutely in Medtronic's dominance of North American IDN contracts.
Guide Extension Catheter Market Segmentation
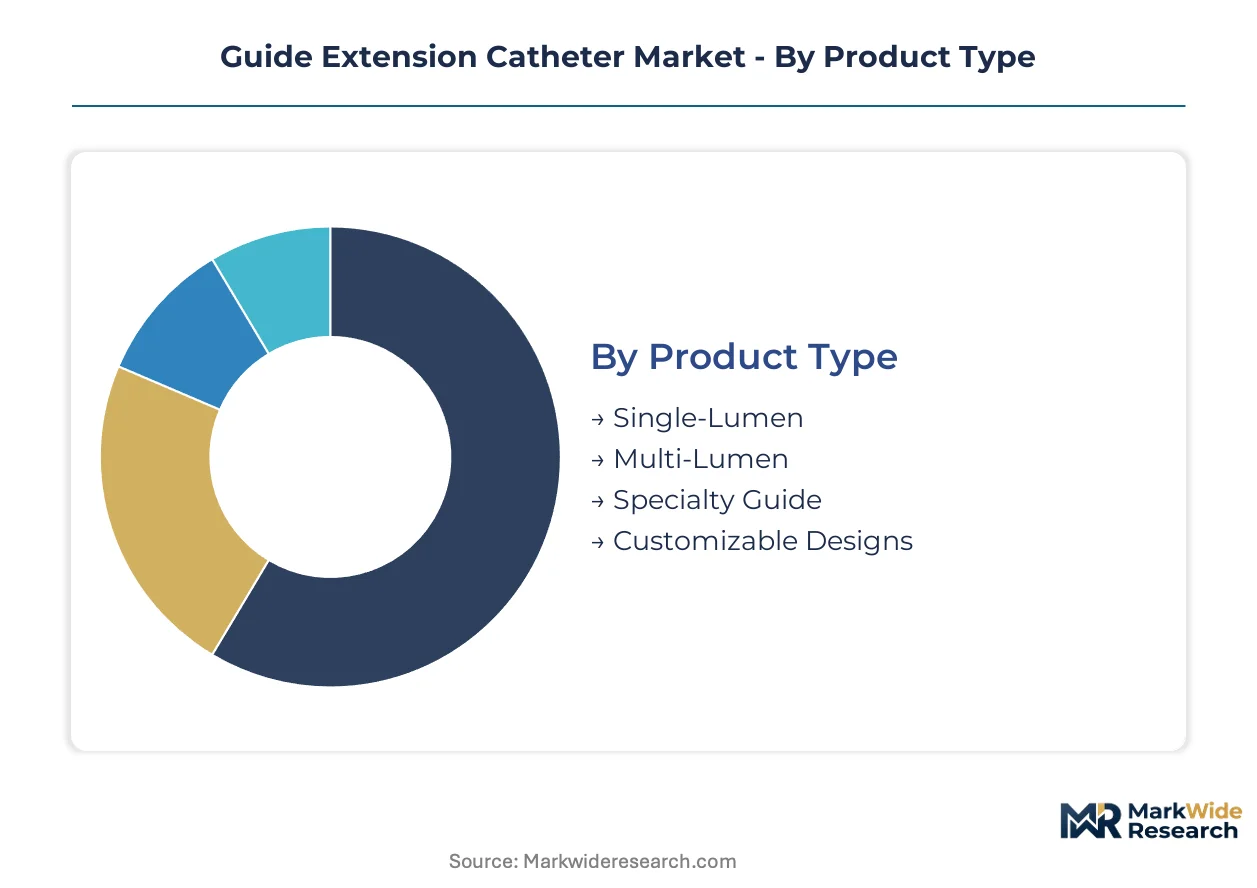
Product architecture and coating chemistry determine reimbursement pathways and clinical adoption velocity in guide extension catheter procurement. Regulatory differentiation across ISO 13485 certification tiers and MDR technical file depth segments vendor qualification and hospital contracting power.
Product Type:
FDA 510(k) clearance pathways and EU MDR conformity assessment complexity stratify competitive positioning across lumen configurations.
- Single-Lumen:Standard shaft construction with polyether block amide or nylon multilayer walls and stainless steel braid reinforcement. High-volume PCI centers in the United States and Germany specify these for routine coronary interventions where cost efficiency governs catheterization lab budgets.
- Multi-Lumen:Dual or triple internal channels enable simultaneous guidewire and microcatheter positioning during chronic total occlusion revascularization. Japanese tertiary cardiac centers specify multi-lumen designs for over half of complex CTO cases, commanding premium positioning through procedural necessity.
- Specialty Guide:Anatomically curved or pre-shaped distal segments for specific vessel takeoff angles.
- Customizable Designs:Physician-specified shaft lengths and tip configurations for individual patient anatomy.
Single-lumen handles the majority of throughput; multi-lumen is the fastest mover on share.
Technology:
Surface engineering and material science investments concentrate margin differentiation in coating and shaft flexibility platforms.
- Hydrophilic Coating:Polyvinylpyrrolidone or polyethylene oxide surface layers reduce friction coefficients during vessel navigation. Terumo's proprietary hydrophilic formulation developed at Japanese research centers reduces radial access complications in aging patient populations.
- Flexible Shaft:Variable-durometer polymer transitions along catheter length optimize kink resistance for radial artery entry. German interventional cardiologists specify flexible shaft designs for transradial workflows where catheter torque response determines procedural success.
- Biodegradable Materials:Experimental polylactic acid or polyglycolic acid shaft components for temporary structural support.
- Radiopaque Features:Tungsten-filled polymer bands or platinum marker coils for fluoroscopic visualization.
Hydrophilic coating commands the widest installed base; flexible shaft configurations are expanding most quickly in radial access adoption.
End User:
Procurement consolidation and reimbursement structure determine volume concentration across care delivery settings.
- Hospitals:Tertiary cardiac centers and academic medical centers with catheterization lab infrastructure. Integrated delivery networks in the United States consolidate purchasing through sole-source agreements favoring suppliers with EDI-capable fulfillment systems.
- Outpatient Centers:Ambulatory surgical facilities performing diagnostic catheterization and elective PCI. German outpatient cardiology clinics expand procedural volume under DRG reimbursement frameworks that reward same-day discharge.
- Surgical Clinics:Specialized cardiovascular surgery practices with hybrid operating room capabilities.
- Diagnostic Labs:Independent imaging centers performing coronary angiography without interventional capability.
Hospitals absorb the dominant procedure volume; outpatient centers are gaining share fastest as same-day discharge protocols spread.
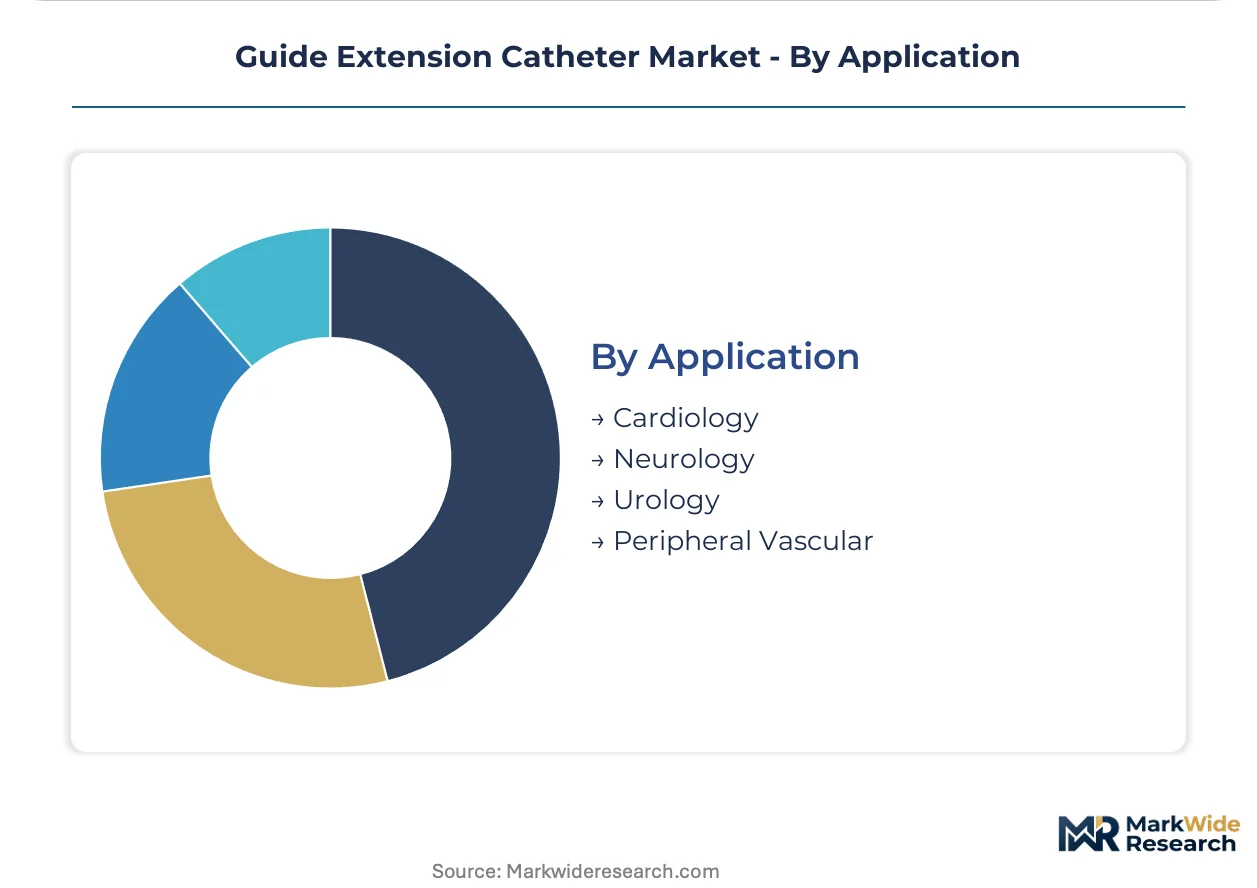
Application:
Anatomical target and disease complexity dictate catheter specification and pricing tier acceptance.
- Cardiology:Coronary artery disease interventions including CTO recanalization and bifurcation lesion treatment. Japanese aging demographics and established reimbursement for transcatheter procedures sustain procedural growth in hospital catheterization labs.
- Peripheral Vascular:Lower extremity artery disease and renal artery interventions. German vascular specialists specify extended working length catheters for femoropopliteal disease where calcified lesions challenge standard guiding catheter engagement.
- Neurology:Cerebrovascular interventions including intracranial aneurysm coiling and stroke thrombectomy.
- Urology:Ureteral and renal pelvis access procedures requiring extended reach capabilities.
Cardiology dominates absolute procedure volume; peripheral vascular is climbing the fastest as diabetes-related artery disease expands treatable patient pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathways, EU MDR conformity timelines, and Japan's PMDA master file requirements are redrawing commercial access conditions across major interventional cardiology markets. Reimbursement stability and aging demographics concentrate procedural demand in specific national clusters.
United States
Integrated delivery networks consolidate catheter procurement through sole-source agreements favoring EDI-capable suppliers. FDA premarket notification requirements under 510(k) pathways elevate compliance costs for foreign entrants. Minneapolis and Boston anchor device manufacturing clusters where catheter extrusion capabilities concentrate.
Germany
Tertiary cardiac centers in Munich and Hamburg drive complex PCI volumes requiring multi-lumen catheter configurations. EU MDR Article 61 clinical evidence requirements extend certification cycles, filtering marginal suppliers from notified body queues. Baden-Württemberg hosts specialized polymer suppliers serving shaft manufacturers.
Japan
Aging demographics sustain transcatheter procedure growth in Tokyo and Osaka catheterization labs. PMDA pharmaceutical and medical device agency maintains distinct master file documentation that extends foreign supplier market entry timelines. Terumo's research centers in Kanagawa prefecture anchor hydrophilic coating development.
India
Tier-2 city interventional cardiology infrastructure remains underpenetrated, creating first-mover positioning for technical service networks. CDSCO regulatory pathways condition import licensing and local clinical trial requirements. Maharashtra and Karnataka clusters concentrate private hospital catheterization lab expansion.
Switzerland
Swissmedic certification supports EU market access through mutual recognition agreements for MDR-compliant manufacturers. Zurich and Basel host regulatory consultancies specializing in conformity assessment preparation for catheter manufacturers. Precision polymer processing capabilities in the Jura region supply niche shaft components.
Guide Extension Catheter Market Key Industry Players
Player mix skews toward diversified cardiovascular device conglomerates with captive catheter portfolios. Market structure concentrates around manufacturers possessing in-house extrusion capabilities and established hospital purchasing network relationships. Three archetypes dominate: integrated multinationals with full catheter portfolios, specialized interventional access device firms, and regional contract manufacturers serving private-label programs. Competitive moves center on ISO 13485 certification maintenance and MDR technical file preparation ahead of notified body queue positions.
Within the integrated multinational tier, Boston Scientific Corporation and Terumo Corporation exemplify archetypes built on manufacturing control and surface technology specialization respectively. Medtronic occupies a position defined by North American hospital network dominance. Among specialized interventional firms, Teleflex Incorporated and BIOTRONIK sit within mid-scale tiers focused on procedure-specific catheter configurations. Seigla Medical, Inc. represents the emerging specialist archetype targeting complex access procedures.
| Leading Market Players |
|---|
| QXMédical |
| Terumo Corporation |
| Boston Scientific Corporation |
| IMDS (Interventional Medical Device Solutions) |
| Nipro Corporation |
| Medtronic |
| Seigla Medical, Inc. |
| BIOTRONIK |
| Teleflex Incorporated |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with polyether block amide suppliers in Germany and Japan lock in both shaft material access and cost visibility for catheter manufacturers navigating EU MDR certification timelines. These contractual structures insulate ISO 13485-certified producers from resin spot market volatility while marginal players absorb input cost swings.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across MDR-compliant premium, 510(k)-cleared standard, and economy private-label levels governs hospital procurement. Price differentiation hinges on hydrophilic coating IP ownership and notified body queue position. Cost compression in the economy tier is intensifying because integrated delivery networks consolidate sole-source contracts. Community hospitals exhibit highest price sensitivity; tertiary cardiac centers in Japan and Germany prioritize performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of specialty polymers dominates over just-in-time preferences given PMDA and FDA certification lead times. Shaft manufacturing concentrates in Germany, Japan, and the United States. Polyether block amide resin, stainless steel braid wire, and hydrophilic coating chemicals constitute critical inputs. Single-source vulnerability runs through European chemical suppliers for block amide formulations. Distribution runs through hospital group purchasing organizations and integrated delivery network centralized platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 61 clinical evidence requirements are compressing product development economics and filtering marginal suppliers, creating consolidation tailwinds for prepared incumbents.
For Market Incumbents: Shield market position by accelerating MDR technical file preparation ahead of notified body queue bottlenecks at TÜV SÜD and BSI. Deepen backward integration into polyether block amide extrusion to capture margin from resin volatility. Prioritize sole-source IDN contract renewals before procurement consolidation hardens vendor pools. For New Entrants and Emerging Players: Differentiate on radial access compatibility and CTO-specific multi-lumen configurations where Terumo and Boston Scientific hold narrower technical moats. Target India's tier-2 city catheterization labs as the most penetrable geography given CDSCO pathway accessibility and underdeveloped technical service networks. Pursue direct-to-hospital digital procurement integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale interventional access specialists possessing ISO 13485 certification and partial MDR technical files but lacking global distribution. Long-term viability rests on regulatory asset durability rather than volume scale. Monitor notified body capacity expansion announcements as the critical inflection signal for certification cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Preparation | Notified body queue positioning at BSI determines CE marking timeline and commercial launch sequencing. |
| Hydrophilic Coating R&D Investment | Terumo's Kanagawa research centers demonstrate surface technology as sustainable differentiation anchor. |
| IDN Sole-Source Contracting | Medtronic's North American hospital network dominance illustrates procurement consolidation leverage. |
| Radial Access Product Line Expansion | German interventional cardiologist preference for flexible shaft designs signals segment growth vector. |
| India Technical Service Network Buildout | Maharashtra and Karnataka private hospital expansion creates first-mover infrastructure positioning. |
Research Approach
Desk research of FDA 510(k) filings, EU MDR notified body databases, and PMDA master file registries preceded structured interviews with interventional cardiologists, catheterization lab directors, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare procedure data, and Japanese Ministry of Health reimbursement schedules. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Variance decomposition across product type, technology platform, end-user setting, and application area shaped the analytical framework over the projection horizon. CAGRs were derived from segmented procedure volume trajectories and pricing tier evolution. Forecast inputs incorporated chronic total occlusion prevalence modeling and radial access adoption curves by geography.
Decision-makers should treat outputs as directional under stable MDR implementation timelines and intact specialty polymer supply chains; material deviation in notified body capacity or resin availability would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pectus Bar Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
Smart Syringe Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Steerable Needles Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
Cyberknife Market