
 Medical Device Complaint Management Market | 2026-2036
Medical Device Complaint Management Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Complaint Management Market Intelligence
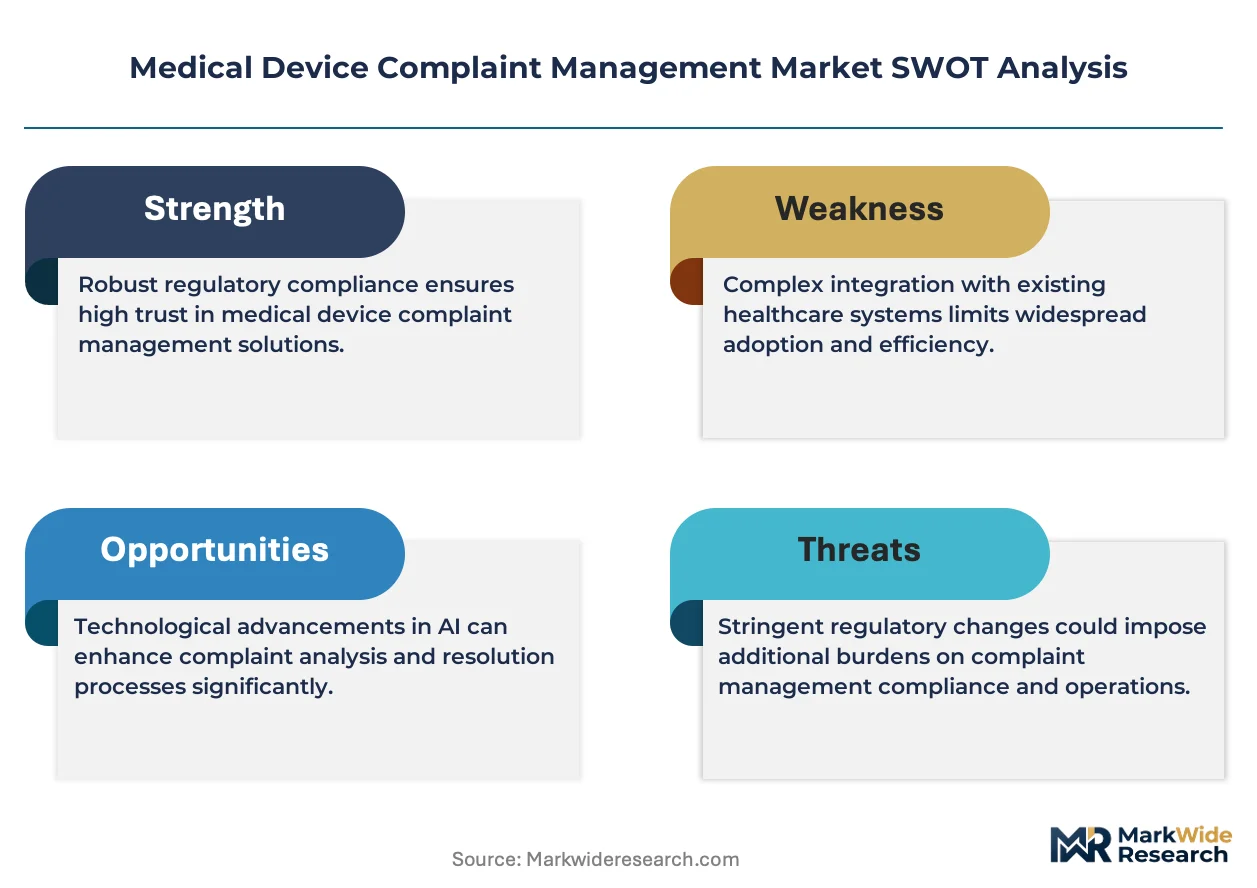
ISO 13485 certification is unwinding the competitive landscape by filtering out vendors lacking quality management credentials. MasterControl leverages its validated cloud infrastructure to dominate North American enterprise deployments. IQVIA sustains competitive positioning through integrated pharmacovigilance and real-world evidence capabilities. Sparta Systems specializes in configurable workflows that accommodate both FDA and EU MDR reporting pathways.
Medical device complaint management encompasses the systematic intake, investigation, trending, and regulatory reporting of product complaints, typically executed through software platforms with electronic signature workflows, audit trails, and automated escalation protocols. Its primary commercial purpose is enabling manufacturers to satisfy post-market surveillance obligations while mitigating recall risk and liability exposure. Software-based systems capture the dominant share of technology spending as validated on-premise and SaaS deployments replace paper-based processes. Cloud solutions represent the fastest-expanding technology segment, driven by multi-site manufacturers seeking centralized complaint repositories with elastic scalability. Diagnostic equipment generates disproportionate complaint volume due to software-intensive functionality and frequent firmware updates, concentrating vendor R&D investment in automated device-specific classification algorithms.
FDA 21 CFR Part 820 subpart M mandates complaint files with documented investigation records, while EU MDR Article 87 imposes strict vigilance reporting timelines that compress response windows for manufacturers. ISO 13485:2016 clause 8.2.2 requires documented procedures for complaint handling that align with both FDA and European requirements, effectively harmonizing baseline platform functionality across jurisdictions. CE marking under EU MDR now demands periodic safety update reports that feed directly from complaint databases, elevating system integration requirements. Stakeholders must evaluate whether their complaint infrastructure can absorb forthcoming FDA harmonization with IMDRF terminologies without disrupting existing workflow validations.
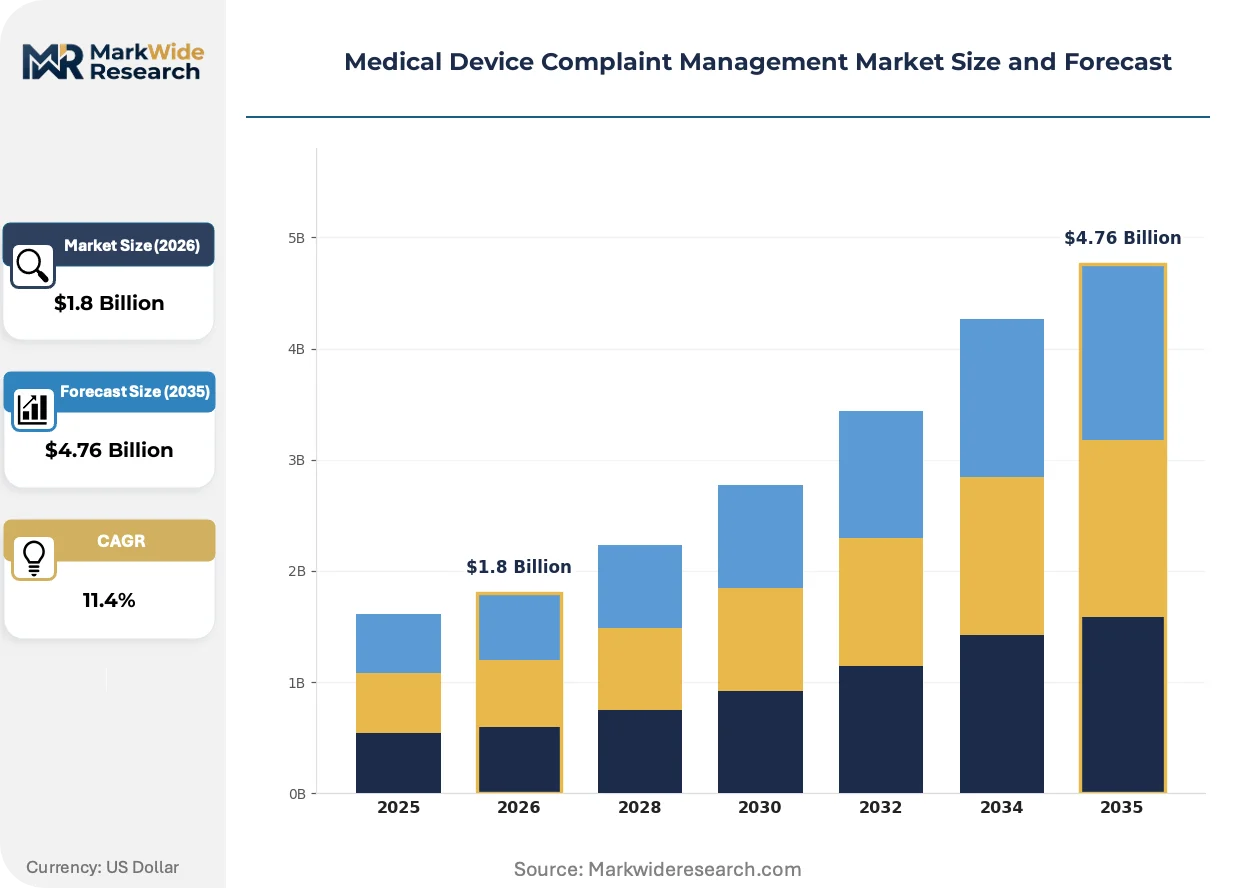
Market Dynamics
Cloud-native complaint management platforms are decomposing legacy on-premise architectures as multi-site medical device manufacturers consolidate distributed reporting systems into centralized, elastic repositories that satisfy both FDA 21 CFR Part 820 and EU MDR vigilance timelines.
Growth Catalysts
- EU MDR Article 87 vigilance mandates:Compressed reporting timelines force manufacturers to automate complaint intake-to-submission workflows, accelerating replacement of paper-based systems with validated electronic platforms.
- Diagnostic equipment firmware complexity:Software-intensive devices generate disproportionate complaint volumes, concentrating R&D investment in automated classification algorithms that reduce manual triage bottlenecks.
- United States liability exposure:Hospitals deploy complaint management platforms to streamline adverse event documentation and reduce malpractice litigation risk from delayed reporting.
Market Restraints
- Validation cost structure:FDA 21 CFR Part 11 compliance for electronic records demands extensive IQ/OQ/PQ documentation, creating six-figure implementation barriers for mid-tier manufacturers.
- Cloud infrastructure concentration:Validated SaaS providers cluster in North American data center regions, exposing EU and Asia-Pacific manufacturers to cross-border data residency compliance friction.
- ISO 13485 certification scarcity:Quality management credentials filter vendor pools, leaving buyers dependent on a narrow base of qualified platform suppliers.
Strategic Opportunities
- Japan PMDA harmonization:Convergence with IMDRF terminologies creates whitespace for platforms offering multi-jurisdiction reporting templates without workflow revalidation.
- Real-world evidence integration:Convergence of complaint databases with post-market surveillance analytics enables predictive safety signal detection, opening premium pricing tiers.
- Small-scale manufacturer underpenetration:Class II device producers in Germany and Switzerland remain paper-dependent, presenting channel expansion targets for configurable mid-market solutions.
Industry Challenges
- Legacy system integration complexity:ERP and MES connectivity demands custom API development, extending deployment timelines and requiring specialized validation engineering talent.
- Audit trail integrity maintenance:Multi-site manufacturers struggle to synchronize timestamp protocols across distributed complaint repositories, risking FDA 483 observations during inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Complaint Management Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, Surgical Instruments, Diagnostic Equipment, Therapeutic Devices Technology: Software-Based Systems, Cloud Solutions, Mobile Applications, Data Analytics End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Providers Compliance Type: FDA Regulations, ISO Standards, CE Marking, Other Certifications |
| Companies Covered | MasterControl, Freyr, IQVIA, SAS, Sparta Systems, Wipro, Biovia, AssurX, Tata Consultancy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Complaint Management Market Strategic Shifts & Innovations
Artificial intelligence and machine learning capabilities are embedding into complaint management platforms, transforming retrospective reporting into predictive safety surveillance while regulatory harmonization pressures force architectural flexibility.
Natural language processing is decomposing unstructured complaint narratives into structured regulatory taxonomies, enabling automated IMDRF code assignment. Large-scale manufacturers in the United States and Germany are deploying these engines at intake nodes, compressing triage cycles from days to hours. The technology is decomposing traditional manual classification labor pools while elevating platform value propositions toward predictive signal detection.
EU MDR periodic safety update report mandates now require direct database feeds from complaint repositories, forcing manufacturers to rearchitect system integrations. This obligation compresses reporting preparation from weeks to automated generation cycles. Diagnostic equipment and implantable device categories face the steepest compliance velocity, driving demand for platforms with pre-validated PSUR module configurations.
Hospital procurement committees now mandate ISO 13485-certified platforms as a baseline qualification filter, displacing generic quality management software. This certification-driven preference shift concentrates vendor selection among specialized medical device compliance providers. The pattern is most visible in United States health system consolidations, where centralized IT governance standardizes enterprise-wide complaint infrastructure selections.
Medical Device Complaint Management Market Segmentation
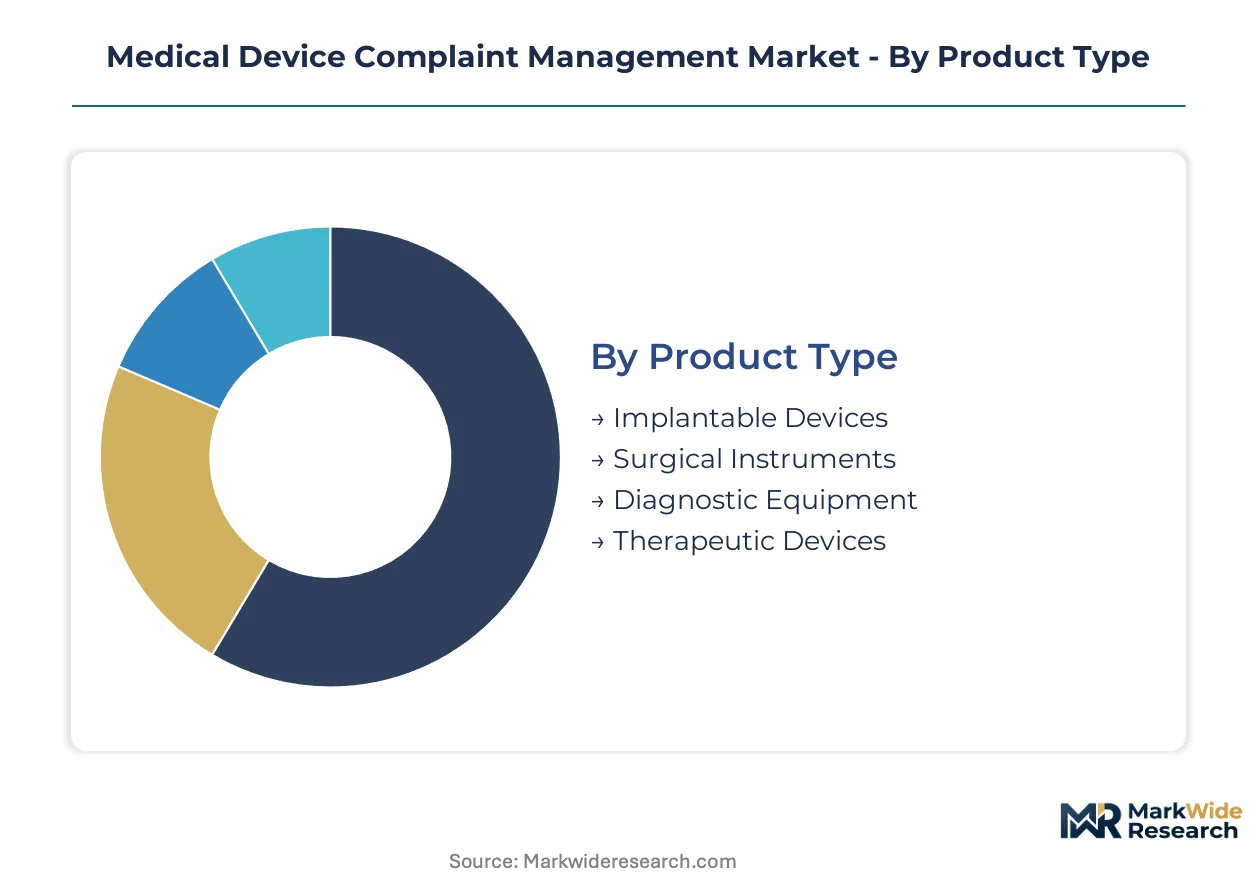
Medical device complaint management segmentation reflects divergent regulatory intensity across product risk classes and deployment architectures. Manufacturers configure platform investments around specific compliance pathways rather than generic quality management needs.
Product Type:
FDA 21 CFR Part 820 subpart M imposes escalating documentation requirements as device risk classification rises, concentrating platform sophistication in higher-risk categories.
- Diagnostic Equipment:Firmware-intensive functionality generates disproportionate complaint volumes from software malfunctions and update failures. United States hospitals deploy automated classification algorithms to compress triage cycles for imaging and laboratory systems. EU MDR vigilance timelines force manufacturers to maintain direct database feeds for adverse event reporting.
- Implantable Devices:Long-term patient exposure elevates post-market surveillance obligations with mandatory periodic safety update reports. Germany and Japan concentrate demand for platforms with validated traceability from complaint intake to regulatory submission. Strict liability exposure drives premium pricing for enterprise-grade solutions.
- Surgical Instruments:Sterilization failures and material defects dominate complaint categories with shorter investigation cycles.
- Therapeutic Devices:Drug-device combination products face dual regulatory pathways requiring harmonized reporting workflows.
Established volume favors Diagnostic Equipment; emerging adoption favors Implantable Devices.
Technology:
Deployment cost tiers separate validated enterprise platforms from configurable mid-market solutions, with infrastructure elasticity becoming the decisive procurement criterion.
- Software-Based Systems:On-premise validated deployments retain dominance in large-scale manufacturers with legacy ERP integrations. FDA 21 CFR Part 11 compliance demands extensive IQ/OQ/PQ documentation that entrenches incumbent vendors. United States medical device clusters sustain highest concentration of validated installations.
- Cloud Solutions:Multi-site manufacturers consolidate distributed repositories into centralized elastic architectures satisfying both FDA and EU MDR requirements. Germany and Switzerland lead European migration as data residency frameworks mature. Subscription pricing expands access for mid-tier manufacturers previously excluded by capital-intensive on-premise models.
- Mobile Applications:Field-based complaint intake extends platform reach beyond traditional desktop workflows.
- Data Analytics:Predictive signal detection capabilities command premium positioning within integrated surveillance platforms.
Software-Based Systems retain the largest installed base; Cloud Solutions are climbing the fastest.
End User:
Procurement authority concentration determines platform standardization scope, with health system consolidations favoring enterprise-wide deployments over point solutions.
- Hospitals:Adverse event documentation liability drives adoption of complaint management platforms with automated escalation protocols. United States health system consolidations centralize IT governance around ISO 13485-certified solutions. Enterprise licensing models predominate as procurement committees mandate standardized infrastructure.
- Clinics:Smaller patient volumes and limited IT resources constrain platform sophistication to essential intake and routing functions.
- Ambulatory Surgical Centers:Procedure-specific complaint patterns favor modular configurations with rapid deployment timelines.
- Home Care Providers:Distributed care settings create data synchronization challenges for centralized complaint repositories.
Hospitals command the deepest functionality requirements; Ambulatory Surgical Centers present the steepest expansion trajectory.
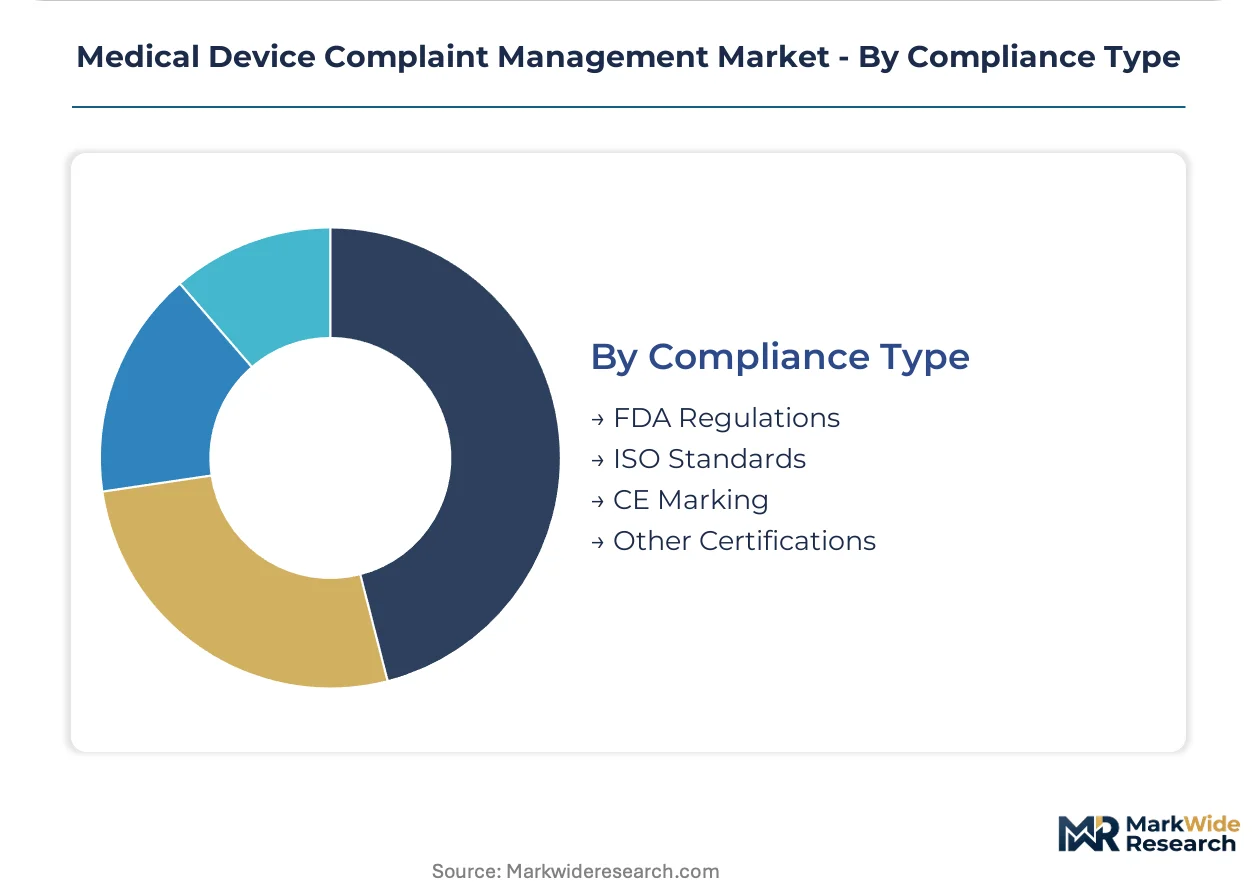
Compliance Type:
Jurisdiction-specific regulatory architecture shapes platform configuration, with multi-market manufacturers demanding modular compliance engines.
- FDA Regulations:21 CFR Part 820 subpart M mandates complaint files with documented investigation records and electronic signature workflows. United States manufacturers face strictest enforcement through FDA 483 observations and warning letter exposure. Platform validation documentation constitutes six-figure implementation barriers.
- ISO Standards:ISO 13485:2016 clause 8.2.2 harmonizes baseline functionality across FDA and European requirements, effectively filtering vendor pools by quality management credentials. Certification scarcity concentrates buyer dependence on qualified suppliers.
- CE Marking:EU MDR Article 87 imposes compressed vigilance reporting timelines with direct database feed requirements for periodic safety update reports.
- Other Certifications:Japan PMDA and Swissmedic pathways require additional workflow templates without revalidation.
FDA Regulations anchor the largest compliance investment; CE Marking is gaining share fastest as EU MDR enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement committees in United States health systems concentrate buying power for complaint management platforms, while mid-tier manufacturers in Germany and Japan drive regional specialization demands.
United States
FDA 21 CFR Part 820 enforcement through warning letters and 483 observations compels manufacturers to maintain validated electronic complaint files. Hospital consolidation into mega-systems like HCA and Kaiser Permanente centralizes IT governance around ISO 13485-certified platforms. Minneapolis and Boston medical device clusters sustain dense vendor ecosystems serving both domestic and export markets.
Germany
EU MDR Article 87 vigilance timelines compress reporting windows for manufacturers exporting implantable devices across Europe. BfArM and notified body scrutiny elevates platform validation requirements beyond baseline ISO standards. Baden-Württemberg and Bavaria host concentrated orthopedic and cardiovascular device manufacturing operations requiring integrated PSUR automation.
Japan
PMDA harmonization with IMDRF terminologies creates demand for multi-jurisdiction reporting templates without workflow revalidation. Aging demographics expand implantable device volumes, intensifying post-market surveillance obligations. Tokyo-Osaka industrial corridors concentrate procurement authority among consolidated medical device conglomerates.
Switzerland
Swissmedic requirements for Class II device vigilance reporting filter vendor pools to ISO 13485-certified specialists. Precision instrument manufacturers in Basel and Zurich regions maintain paper-dependent complaint processes ripe for digital migration. Medtech SME density exceeds any European peer on a per-capita basis.
India
CDSCO medical device rules alignment with IMDRF standards opens export pathways for domestic manufacturers serving regulated markets. Hyderabad and Bangalore medical device parks attract contract manufacturers requiring complaint infrastructure for OEM partnerships. Cost-sensitive procurement favors configurable cloud solutions over capital-intensive on-premise deployments.
Medical Device Complaint Management Market Key Industry Players
Player mix skews toward validated software specialists with quality management credentials, creating tiered competition between enterprise-grade platforms and configurable mid-market solutions. ISO 13485 certification filters the vendor pool to a narrow qualified base, concentrating procurement decisions among buyers with limited supplier alternatives. Strategic archetypes divide between cloud-native SaaS providers, legacy on-premise validators, and IT services integrators. Dominant competitive moves include geographic expansion into underpenetrated European mid-markets and technology licensing partnerships for AI-enabled classification engines.
Within the validated enterprise tier, MasterControl and IQVIA occupy positions as North American anchors, while Sparta Systems exemplifies specialization in multi-jurisdiction compliance workflows. These three represent distinct strategic postures: infrastructure dominance, integrated pharmacovigilance convergence, and configurable regulatory pathway accommodation respectively. Wipro and Tata Consultancy Services sit within the IT services integrator archetype, leveraging offshore engineering capacity for validation documentation and custom API development. Freyr and AssurX represent emerging competitive pressure from regulatory consulting firms extending into software platforms.
| Leading Market Players |
|---|
| MasterControl |
| Freyr |
| IQVIA |
| SAS |
| Sparta Systems |
| Wipro |
| Biovia |
| AssurX |
| Tata Consultancy Services |
| Others |
Cost & Logistics Intelligence
Validated cloud infrastructure scale economies in North American data centers compress unit economics for FDA 21 CFR Part 11 compliant platforms, concentrating pricing power among ISO 13485 certified vendors while erecting six-figure validation barriers that filter mid-tier manufacturers toward subscription SaaS tiers.
Pricing Analysis
Cost-plus contracts with annual CPI indexation dominate enterprise licensing agreements for on-premise validated deployments, while cloud-native SaaS providers deploy three-tier pricing structures across premium, standard, and economy levels differentiated by audit trail retention periods and API integration depth. Price differentiation hinges on ISO 13485 certification tier and multi-jurisdiction workflow coverage, with EU MDR PSUR automation commanding substantial premiums. Pricing pressure stems from mid-tier manufacturers in Germany and Switzerland migrating from capital-intensive perpetual licenses to elastic subscription models. Hospital procurement committees exhibit lowest price sensitivity due to liability exposure, while Class II device SMEs in India demonstrate highest elasticity.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion elevate total cost of ownership for EU manufacturers dependent on North American validated SaaS infrastructure, compressing deployment timelines for multi-site rollouts. Cloud infrastructure concentrates in the United States, Germany, and Ireland, with compute capacity expansion tethered to data residency frameworks. Raw material dependencies span encrypted database engines, electronic signature modules, and IMDRF taxonomy libraries. Single-source vulnerability concentrates in AWS and Azure validated environments, exposing manufacturers to cross-border compliance friction. Distribution runs through direct enterprise sales with specialized validation engineering support, supplemented by channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR enforcement fragmentation across notified bodies creates specialization niches for complaint management platforms, as divergent interpretation of Article 87 vigilance timelines splinters standardized workflow demand into jurisdiction-specific configurations.
For Market Incumbents: Shield enterprise installed bases through backward integration into validation documentation services, deepening IQ/OQ/PQ engineering capacity to extend switching costs. Acquire ISO 13485 certified mid-market specialists in Germany and Switzerland before cloud-native challengers establish channel presence. Counter threat from regulatory consulting firms extending into software platforms by embedding predictive analytics modules that justify premium retention. For New Entrants and Emerging Players: Lead with configurable cloud solutions targeting Class II device manufacturers in Baden-Württemberg and Bavaria, where paper-dependent complaint processes present immediate displacement opportunity. Penetrate through Swissmedic-aligned workflow templates that minimize revalidation burden for precision instrument SMEs. Deploy channel partnerships with European medical device trade associations to bypass direct competition with entrenched North American validators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regulatory technology specialists with proven FDA and EU MDR dual-pathway validation, as AI-enabled classification engines mature from experimental to table-stakes functionality. Long-term viability rests on convergence with pharmacovigilance and real-world evidence platforms. Target acquisition archetype: ISO 13485 certified SaaS providers with pre-validated PSUR modules and established European data center presence. Signal to watch: PMDA harmonization implementation velocity in Japan, which will anoint preferred template providers for Asia-Pacific expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 87 compliance accelerates platform replacement cycles for implantable device manufacturers. |
| Hospital System Partnership | United States health system consolidations centralize procurement around ISO 13485 certified enterprise solutions. |
| Software Companion Development | Diagnostic equipment firmware complexity demands automated classification algorithms reducing manual triage. |
| Reimbursement Strategy | CMS adverse event reporting requirements elevate platform value within hospital risk management budgets. |
| Geographic Expansion | Japan PMDA IMDRF harmonization creates whitespace for multi-jurisdiction template providers. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with regulatory affairs directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 483 observation databases, EU MDR vigilance reports, ISO 13485 certification registries, and hospital IT spending disclosures. Bottom-up triangulation aggregated deployment counts by technology tier and compliance pathway, while top-down reconciliation tested aggregate market sizing against vendor revenue disclosures and channel partner estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning device risk classification, deployment architecture, end-user procurement authority, and jurisdiction-specific regulatory intensity. CAGRs derived from elasticity-adjusted adoption curves calibrated to EU MDR enforcement phase-in schedules and FDA harmonization with IMDRF terminologies. Industry-specific inputs incorporated diagnostic equipment firmware update frequency, implantable device PSUR automation penetration, and cloud data residency framework maturation.
Underlying assumptions cover sustained EU MDR enforcement rigor and FDA 21 CFR Part 820 inspection intensity, with deviation risk concentrated in regulatory harmonization delays or cloud infrastructure concentration policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Blood Collection Devices Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Cranial Clamps Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market