
 Global Cervical Total Disc Replacement (CTDR) Market | 2026-2036
Global Cervical Total Disc Replacement (CTDR) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cervical Total Disc Replacement (CTDR) Market Foresight
FDA premarket approval under the PMA pathway is redrawing competitive boundaries in cervical disc replacement. Medtronic plc leverages its established PMA portfolio and surgeon training infrastructure to sustain market presence across multiple geographies. Zimmer Biomet Holdings, Inc. anchors its position through specialized instrumentation sets and broad hospital contracting relationships. Globus Medical, Inc. differentiates via integrated imaging-to-implant workflows and robotics-compatible device platforms.
Cervical total disc replacement substitutes an artificial prosthesis for a damaged cervical disc, typically employing cobalt-chromium or titanium alloy endplates with ultra-high molecular weight polyethylene cores to restore segmental motion and disc height. The procedure preserves cervical kinematics and reduces adjacent segment degeneration compared to anterior cervical discectomy and fusion. Metal-on-metal constructs dominate current procedural volumes due to established long-term survivorship data, while ceramic-on-ceramic bearings attract growing interest for reduced wear debris profiles in younger patient cohorts. Degenerative disc disease applications command the largest addressable patient pool, though herniated disc indications are expanding as surgeon familiarity with motion-preservation techniques broadens.
The FDA maintains stringent PMA requirements for CTDR devices, while the EU Medical Device Regulation imposes enhanced clinical evidence standards through notified body oversight. Japan's PMDA evaluates foreign trial data alongside domestic post-market surveillance to shape approval timelines for imported cervical disc systems. Stakeholders must monitor evolving reimbursement decisions by Medicare and major European statutory insurers, as coverage determinations directly influence hospital purchasing committees and surgeon device selection.
Market Dynamics
The FDA's PMA pathway is compressing competitive timelines while simultaneously elevating clinical evidence thresholds for new cervical disc entrants, forcing device manufacturers to front-load substantial R&D expenditure before revenue realization.
Growth Catalysts
- Japan's PMDA streamlined review:Expedited approval timelines for motion-preservation devices with existing FDA PMA clearance are accelerating market entry for qualified foreign manufacturers.
- Ceramic-on-ceramic bearing migration:Younger patient cohorts under 50 are driving surgeon preference toward reduced wear debris profiles in biocompatible constructs.
- Adjacent segment disease avoidance:Spine clinics are expanding CTDR volumes as kinematic preservation data accumulates versus fusion alternatives.
Market Restraints
- Cobalt-chromium alloy supply concentration:Specialized medical-grade metal sourcing concentrates among a limited supplier base in Germany and the United States, creating input vulnerability.
- EU MDR clinical evidence escalation:Enhanced notified body oversight extends recertification timelines for legacy devices, compressing revenue windows.
- Anterior cervical discectomy and fusion substitution:Established reimbursement codes and surgeon familiarity with fusion techniques sustain competitive pressure in Medicare populations.
Strategic Opportunities
- Brazil's ANVISA pathway expansion:Latin America's largest healthcare market is formalizing equivalency recognition for FDA-cleared devices, reducing duplicative trial requirements.
- Robotics-integrated surgical workflows:Navigation platforms are converging with CTDR instrumentation to enable precision implant positioning in outpatient settings.
- India's CDSCO priority review:Central Drug Standard Control Organization fast-track designations for orphan spinal indications are opening procedural volume in private hospital chains.
Industry Challenges
- Biomechanical testing capacity scarcity:Validated wear simulators for cervical motion segments are limited to three North American and European facilities, creating validation bottlenecks.
- ISO 18192-1 compliance complexity:Wear testing standard interpretation variance across notified bodies generates submission revision cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cervical Total Disc Replacement (CTDR) Market |
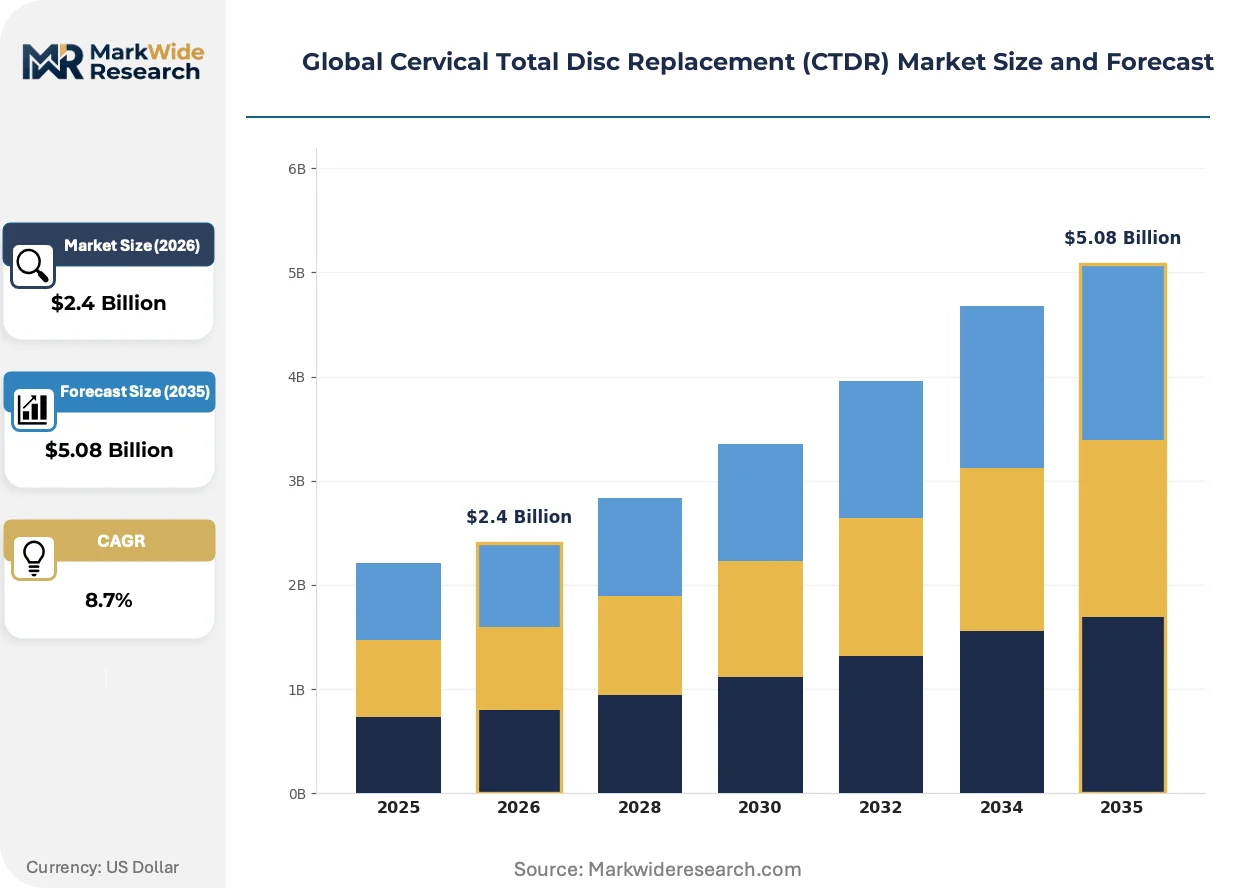
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal-on-Metal, Polyethylene-on-Metal, Ceramic-on-Ceramic, Hybrid Implants Application: Degenerative Disc Disease, Cervical Spondylosis, Herniated Disc, Spinal Stenosis End User: Spine Clinics, Orthopedic Centers, Neurosurgery Hospitals, Rehabilitation Facilities Deployment: Hospital Settings, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes |
| Companies Covered | Medtronic plc, Stryker Corporation, Zimmer Biomet Holdings, Inc., Globus Medical, Inc., NuVasive, Inc., Orthofix Medical Inc., Centinel Spine, Inc., FH Orthopedics, ZimVie, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cervical Total Disc Replacement (CTDR) Market Shifts & Advancements
Device architecture is pivoting toward patient-specific kinematic matching while regulatory science evolves to capture long-term motion preservation outcomes. Three converging developments are restructuring competitive requirements.
Polyethylene core engineering is miniaturizing. Ultra-high molecular weight polyethylene inserts with vitamin E stabilization are reducing wear rates in cervical applications. Academic medical centers in Germany and Japan are adopting these constructs for two-level procedures. The technology is miniaturizing implant footprints while maintaining load-bearing capacity, enabling expanded indications in smaller cervical anatomies.
MDR Article 61 clinical evaluation requirements are reshaping post-market surveillance obligations for CE-marked devices. Manufacturers must now demonstrate equivalence through head-to-head biomechanical data rather than historical predicate claims. European spine clinics are responding by consolidating purchasing around suppliers with established MDR technical documentation, compressing vendor diversity.
Surgeon training credentialing is displacing traditional device loyalty in hospital purchasing decisions. Neurosurgery departments are mandating proctored case completion before granting CTDR privileges, shifting influence toward institutions with simulation infrastructure. This behavioral shift concentrates volume in United States academic centers and German university hospitals with established fellowship pipelines.
Global Cervical Total Disc Replacement (CTDR) Market Segmentation
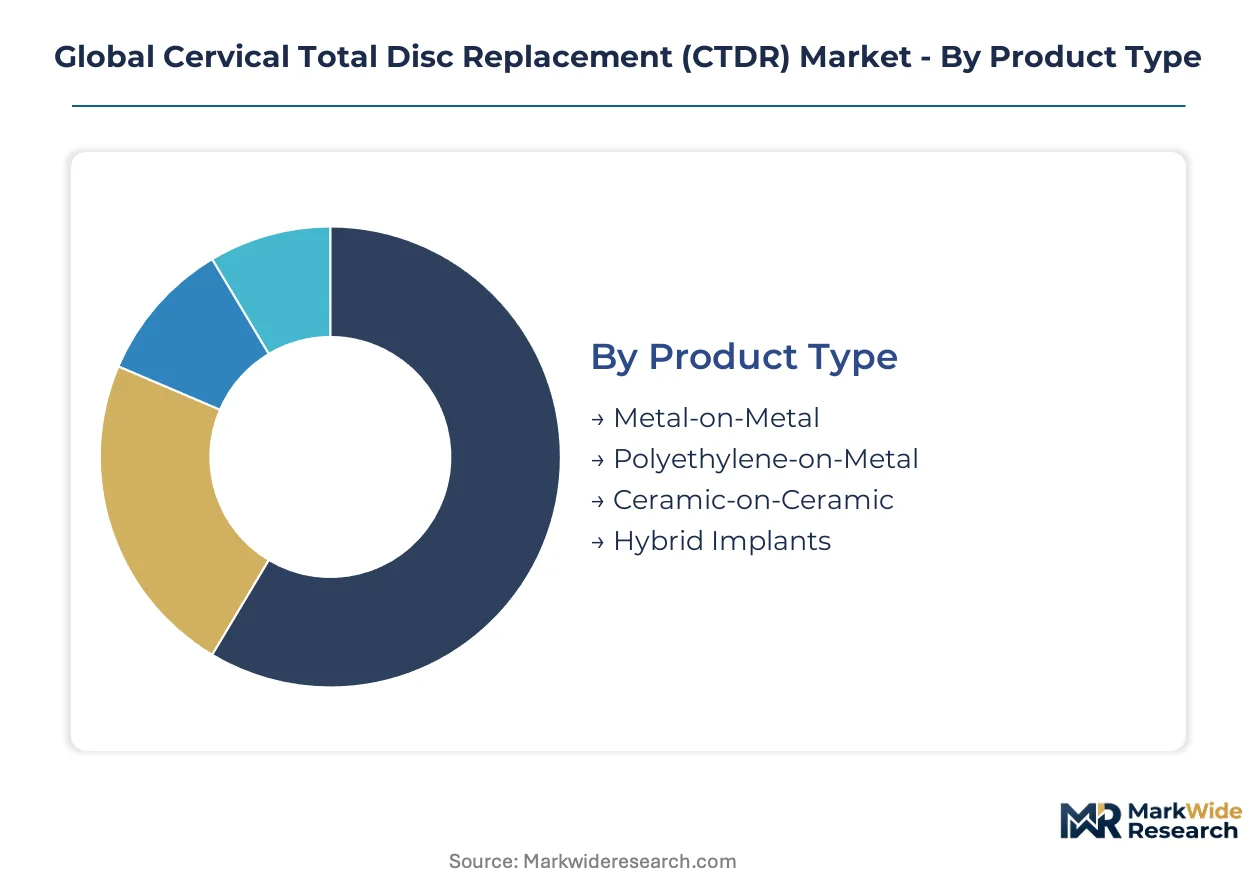
CTDR segmentation reveals distinct procurement patterns across bearing surfaces, clinical indications, and care settings. Manufacturers must align device portfolios with specific reimbursement codes and surgeon training pathways that vary dramatically by segment.
Product Type:
Metal-on-metal constructs dominate domestic procedural volumes in the United States and Germany, while ceramic-on-ceramic bearings command premium export positioning toward Japanese and Australian markets.
- Metal-on-Metal:Cobalt-chromium endplates with mobile polyethylene cores deliver established long-term survivorship data. United States spine clinics concentrate demand here due to extensive FDA PMA track records and straightforward Medicare reimbursement alignment.
- Ceramic-on-Ceramic:Alumina or zirconia-toughened bearings generate minimal wear debris. Japanese neurosurgery hospitals and select German academic centers are expanding adoption for patients under 50 seeking motion preservation over multi-decade horizons.
- Polyethylene-on-Metal:Conventional bearing couples with vitamin E-stabilized inserts reduce oxidative degradation. Standard workhorse configuration for cost-sensitive hospital purchasing committees.
- Hybrid Implants:Modular platforms enabling intraoperative bearing surface selection. Emerging niche for surgeons managing heterogeneous patient anatomies across multi-level procedures.
Metal-on-metal holds the largest share; momentum sits with ceramic-on-ceramic.
Application:
Cost tier stratification separates high-volume degenerative indications from complex stenosis cases requiring specialized instrumentation sets and extended hospital stays.
- Degenerative Disc Disease:Progressive cervical disc collapse with axial neck pain and radiculopathy. Accounts for the broadest addressable patient pool across United States Medicare populations and German statutory insurance frameworks.
- Herniated Disc:Acute disc herniation with nerve root compression. Fastest-expanding indication as United States orthopedic centers build surgeon proficiency through proctored case programs.
- Cervical Spondylosis:Chronic degenerative changes with osteophyte formation. Concentrated in Japanese patient populations with elevated lifetime cervical spine loading.
- Spinal Stenosis:Central or foraminal canal narrowing with myelopathic symptoms. Requires careful patient selection to exclude significant facet arthropathy contraindicating motion preservation.
Degenerative disc disease anchors volume; herniated disc applications are climbing the fastest.
End User:
Customer type determines capital equipment bundling requirements, with neurosurgery hospitals demanding robotics integration while spine clinics prioritize instrument set portability.
- Spine Clinics:Dedicated outpatient facilities with focused cervical expertise. United States ambulatory surgery centers are expanding CTDR volumes as anesthesia protocols enable same-day discharge.
- Neurosurgery Hospitals:Academic medical centers with fellowship training pipelines. German university hospitals concentrate complex multi-level and revision procedures here.
- Orthopedic Centers:General musculoskeletal practices adding cervical spine capabilities. Volume-sensitive segment where device pricing and instrument loaner programs determine vendor selection.
- Rehabilitation Facilities:Post-acute settings managing non-surgical candidates. Limited direct device procurement; influence care pathway design through referral network relationships.
Neurosurgery hospitals capture the highest acuity cases; spine clinics are gaining share fastest.
Deployment:
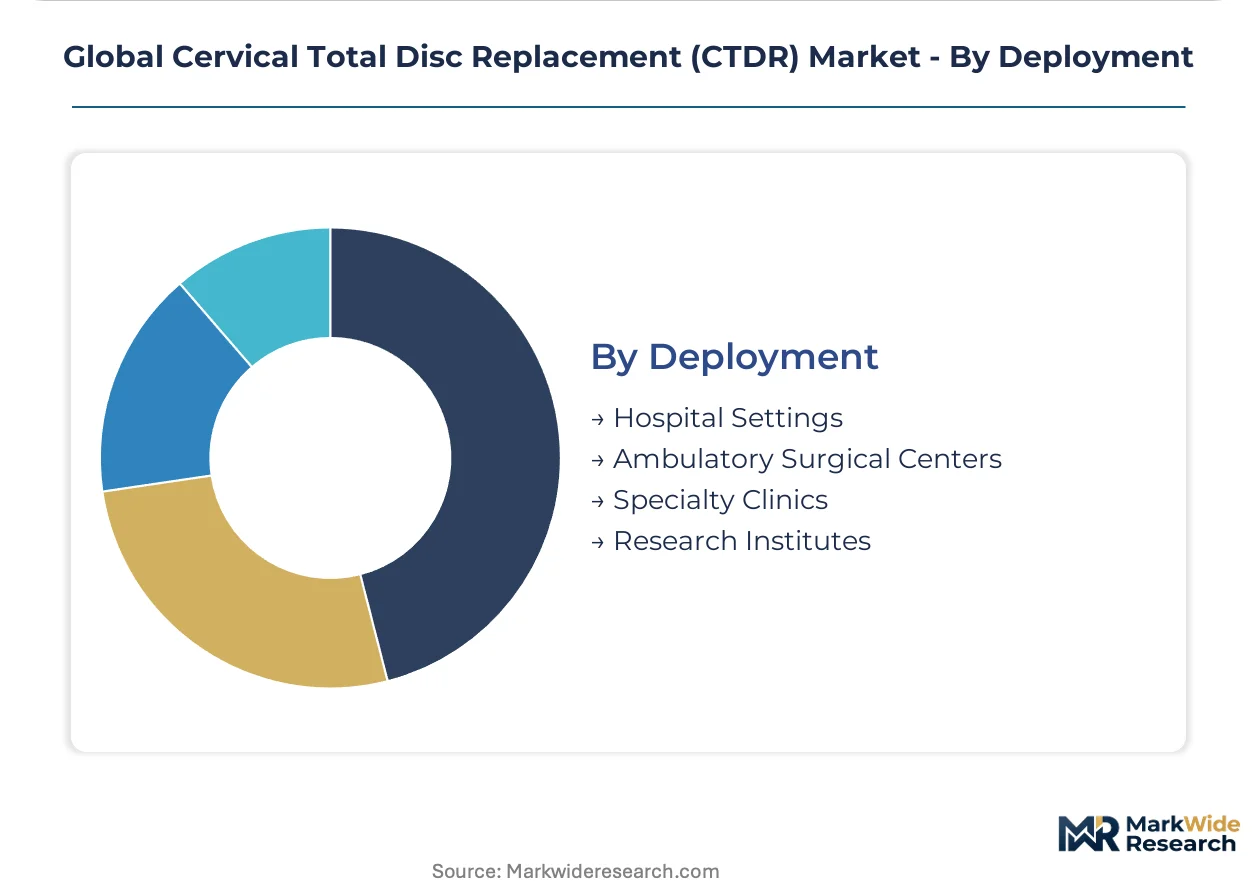
Supply concentration varies dramatically by setting, with hospital-based procurement committees negotiating enterprise contracts while ambulatory centers prioritize disposable instrument economics.
- Hospital Settings:Inpatient wards and attached surgical suites with 23-hour observation capabilities. Japanese and German frameworks require overnight stay documentation for statutory reimbursement.
- Ambulatory Surgical Centers:Standalone facilities optimized for rapid throughput. United States Medicare ASC payment reforms are accelerating site-of-service migration for single-level procedures.
- Specialty Clinics:Physician-owned facilities with limited bed capacity. Concentrated in United States metropolitan markets with favorable state-level certificate-of-need regulations.
- Research Institutes:Academic centers conducting IDE trials and post-market surveillance. Critical channel for generating PMA-supporting clinical evidence and long-term kinematic data.
Hospital settings retain the dominant share; ambulatory surgical centers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways and Japan's PMDA streamlined review programs are redrawing geographic entry sequences for motion-preservation device manufacturers. Reimbursement frameworks in statutory insurance systems directly shape hospital purchasing committee priorities across major procedural markets.
United States
Medicare reimbursement codes for cervical disc replacement anchor procedural volume in aging patient cohorts. The FDA's PMA pathway maintains stringent clinical evidence thresholds that compress competitive timelines for new entrants. Academic medical centers in Boston and Baltimore concentrate fellowship-trained surgeon pools and generate long-term kinematic data supporting motion-preservation claims.
Germany
Statutory health insurance frameworks under G-BA evaluation procedures sustain reimbursement for motion-preservation alternatives to fusion. The EU MDR imposes enhanced clinical evidence standards through notified body oversight that extends recertification timelines. University hospitals in Munich and Heidelberg anchor complex multi-level procedure volumes and post-market surveillance obligations.
Japan
PMDA expedited review pathways for devices with existing FDA clearance accelerate market entry for qualified foreign manufacturers. Aging demographics with elevated lifetime cervical spine loading expand the addressable patient pool for degenerative indications. Tokyo and Osaka metropolitan clusters concentrate neurosurgery hospital capacity and domestic post-market surveillance infrastructure.
Australia
TGA evaluation of foreign trial data alongside domestic clinical evidence requirements shapes approval timelines for imported cervical disc systems. Private hospital chains in Sydney and Melbourne drive procedural volume through surgeon training credentialing programs. The regulatory framework emphasizes long-term survivorship data in bearing surface selection for younger patient cohorts.
Brazil
ANVISA pathway expansion formalizing equivalency recognition for FDA-cleared devices reduces duplicative trial requirements for market entry. Private hospital networks in São Paulo and Rio de Janeiro concentrate purchasing committee influence over device selection. The regulatory evolution opens procedural volume for motion-preservation techniques in Latin America's largest healthcare market.
Global Cervical Total Disc Replacement (CTDR) Market Competitive Landscape
Player mix skews toward diversified orthopedic conglomerates with established PMA portfolios and specialized spine-focused innovators with robotics-compatible platforms. Market structure concentrates around manufacturers with surgeon training infrastructure and validated wear testing documentation. Two strategic archetypes dominate: integrated device-navigation platforms and bearing-surface specialists with ceramic-on-ceramic portfolios. Competitive moves center on M&A for robotics integration and capacity expansion in biomechanical testing facilities.
Within the diversified conglomerate tier, Medtronic plc and Stryker Corporation occupy positions shaped by broad hospital contracting relationships and established PMA track records. Zimmer Biomet Holdings, Inc. sits within the instrumentation-specialist archetype, with Globus Medical, Inc. representing the integrated imaging-to-implant workflow segment. These three entities exemplify how scale-driven manufacturers anchor competitive positioning through fellowship pipeline relationships and enterprise purchasing committee access.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Globus Medical, Inc. |
| NuVasive, Inc. |
| Orthofix Medical Inc. |
| Centinel Spine, Inc. |
| FH Orthopedics |
| ZimVie, Inc. |
| Others |
Supply & Pricing Matrix
Capacity utilization at specialized medical-grade alloy foundries in Germany and the United States creates dual pressure on CTDR manufacturers, concentrating supply leverage among a handful of cobalt-chromium suppliers while simultaneously establishing price floors that resist downward negotiation from hospital purchasing committees.
Pricing Analysis
Certification level creates the primary spread between premium FDA PMA-cleared constructs and standard CE-marked alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects PMA track record depth, with metal-on-metal bearing couples commanding premium positioning over polyethylene-on-metal workhorse configurations. Cost compression in standard tiers is intensifying because Brazilian and Indian regulators are fast-tracking equivalency recognition for established devices, expanding price-competitive supply. Orthopedic centers exhibit the highest price sensitivity due to limited case volumes and instrument loaner dependency, while neurosurgery hospitals prioritize long-term kinematic data over acquisition cost.
Supply Chain Analysis
Strategic stockpiling of cobalt-chromium and titanium alloy feedstock dominates procurement behavior among tier-one manufacturers, buffering against medical-grade metal supply interruptions. Germany, the United States, and Japan anchor upstream supply, with specialized foundries in Essen and Pittsburgh producing the majority of endplate-grade alloys. Component dependencies center on ultra-high molecular weight polyethylene cores, ceramic bearing inserts, and precision-machined instrumentation sets. Single-source vulnerability concentrates in validated wear simulators, limited to three North American and European facilities. Distribution runs through hospital purchasing committees and GPO contracts in the United States, direct manufacturer-to-hospital relationships in Germany, and specialized orthopedic distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CTDR market evolution is approaching a platform-economics inflection where robotics-integrated surgical workflows and imaging-to-implant software ecosystems are displacing standalone device loyalty in hospital procurement decisions.
For Market Incumbents: Shield PMA portfolio value by deepening surgeon training infrastructure and simulation credentialing relationships before robotics platforms commoditize implant selection. Acquire or partner with navigation software developers to maintain influence over purchasing committee decisions. Prioritize MDR technical documentation completion for legacy devices to compress competitor recertification windows in Europe. For New Entrants and Emerging Players: Surgeon training infrastructure gaps in United States ambulatory surgery centers and Brazilian private hospital networks offer the most penetrable entry points. Target ceramic-on-ceramic bearing portfolios for Japanese and Australian markets where younger patient demographics and long-term survivorship data requirements favor specialized constructs. Pursue ANVISA equivalency pathways to bypass duplicative trial costs in Latin America's largest healthcare market. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated imaging-to-implant workflow providers over standalone device manufacturers as hospital systems consolidate vendor relationships. Long-term viability hinges on robotics compatibility and software ecosystem integration rather than incremental bearing surface innovation. Watch for FDA PMA pathway compression signals as an inflection indicator for accelerated competitive entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Platform Integration | Navigation-enabled precision positioning expands CTDR eligibility to outpatient settings. |
| MDR Technical Documentation Completion | European notified body readiness preserves CE-marked device revenue windows. |
| Ceramic-on-Ceramic Portfolio Expansion | Reduced wear debris profiles capture Japanese and Australian younger patient segments. |
| Surgeon Training Infrastructure Investment | Proctored case credentialing secures hospital purchasing committee influence. |
| ANVISA Equivalency Pathway Execution | FDA clearance recognition accelerates Brazilian market entry without duplicative trials. |
Research Methodology
A standing panel of spine surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration throughout the research process. Primary fieldwork combined structured interviews with secondary validation against FDA PMA filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue analysis across bearing surface, indication, and deployment segments.
Consistency checks validated volume and value outputs against external benchmarks including statutory insurance claims data and academic medical center procedural registries. The analytical framework modeled demand across product type, application, end user, and deployment setting dimensions over the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating aging demographic projections, reimbursement policy evolution, and regulatory approval timeline assumptions. Forecast inputs included PMDA streamlined review uptake rates and ASC site-of-service migration patterns.
Underlying assumptions cover reimbursement stability, regulatory pathway continuity, and supply chain input availability, with deviation risk concentrated in EU MDR recertification delays and cobalt-chromium alloy supply disruptions. Practitioners should keep alternative scenarios live as Medicare ASC payment reforms and ceramic bearing adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Creatinine Meter Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Pharma Robots Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Neurovascular Catheters Market