
 Europe Sternal Closure Systems Market | 2026-2036
Europe Sternal Closure Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sternal Closure Systems Market Intelligence
A shift from single-source titanium supply to multi-source procurement is restructuring cost dynamics across European manufacturers. Zimmer Biomet leverages captive forging partnerships to secure alloy consistency for plate systems. KLS Martin Group anchors its position through specialized distribution across German and Italian cardiac centers. B. Braun competes by extending sterile packaging capabilities that reduce OR preparation time.
Sternal closure systems encompass mechanical and biologic devices engineered to stabilize the sternum following median sternotomy, typically achieving fixation loads exceeding 300 N to withstand respiratory mechanics during bone healing. Titanium plate systems with locking screw interfaces now dominate premium positioning, while stainless steel wires occupy mature cost-sensitive tiers across public hospital procurement. Automated closure systems represent the fastest-expanding technology segment, though manual techniques retain volume leadership in Eastern European facilities where capital budgets constrain robotic adoption. Biodegradable polymer research is reshaping R&D pipelines as manufacturers anticipate future MDR sustainability requirements.
CE marking under the EU MDR and EMA device oversight govern market access, with notified bodies in Germany and the Netherlands conducting expanded clinical evidence reviews that extend approval timelines. The EU Green Deal's medical device sustainability criteria are forcing material disclosure requirements that favor recyclable titanium over polymer composites. Stakeholders must monitor how ECHA substance restrictions on nickel-bearing alloys reshape stainless steel wire formulations across Southern European supply chains.
Market Dynamics
The EU Medical Device Regulation (MDR) enforcement is compressing approval timelines and forcing clinical evidence upgrades across sternal closure portfolios, while titanium plate systems displace stainless steel wires in German and Italian cardiac centers.
Growth Catalysts
- MDR Clinical Evidence Mandates:German notified bodies are accelerating titanium plate approvals through streamlined equivalence pathways, creating regulatory momentum for premium fixation systems.
- Hybrid Closure Techniques:Cardiac centers in Milan and Munich are combining plate-and-wire methods to reduce sternal non-union rates, expanding addressable procedure volumes.
- Respiratory Mechanics Research:Biomechanical studies demonstrating 300+ N load tolerance for titanium locking interfaces are converting skeptical surgeons across Western European teaching hospitals.
Market Restraints
- Titanium Alloy Supply Concentration:European forgers source sponge primarily from Russian and Chinese refiners, exposing plate manufacturers to geopolitical input volatility.
- Stainless Steel Wire Substitution:Public hospital procurement in Poland and Romania retains mature wire systems due to reimbursement caps that compress device budgets.
- ECHA Nickel Restrictions:Proposed substance restrictions on nickel-bearing alloys threaten 316L stainless steel formulations across Southern European supply chains.
Strategic Opportunities
- Portuguese and Greek Market Entry:Underpenetrated Iberian and Balkan cardiac surgery volumes offer first-mover positioning before MDR compliance costs rise.
- Biodegradable Polymer R&D:Anticipated EU Green Deal sustainability criteria are redirecting pipeline investment toward absorbable sternal fixation alternatives.
- Sterile Packaging Innovation:Pre-sterilized kit configurations reduce operating room preparation time, creating channel differentiation against traditional bulk packaging.
Industry Challenges
- Notified Body Capacity Bottlenecks:German and Dutch conformity assessment organizations face 12-18 month review queues, delaying product line extensions.
- Surgeon Training Requirements:Plate-and-screw techniques demand specialized instrumentation skills that wire-closure trained cardiac surgeons must acquire through proctored cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sternal Closure Systems Market |
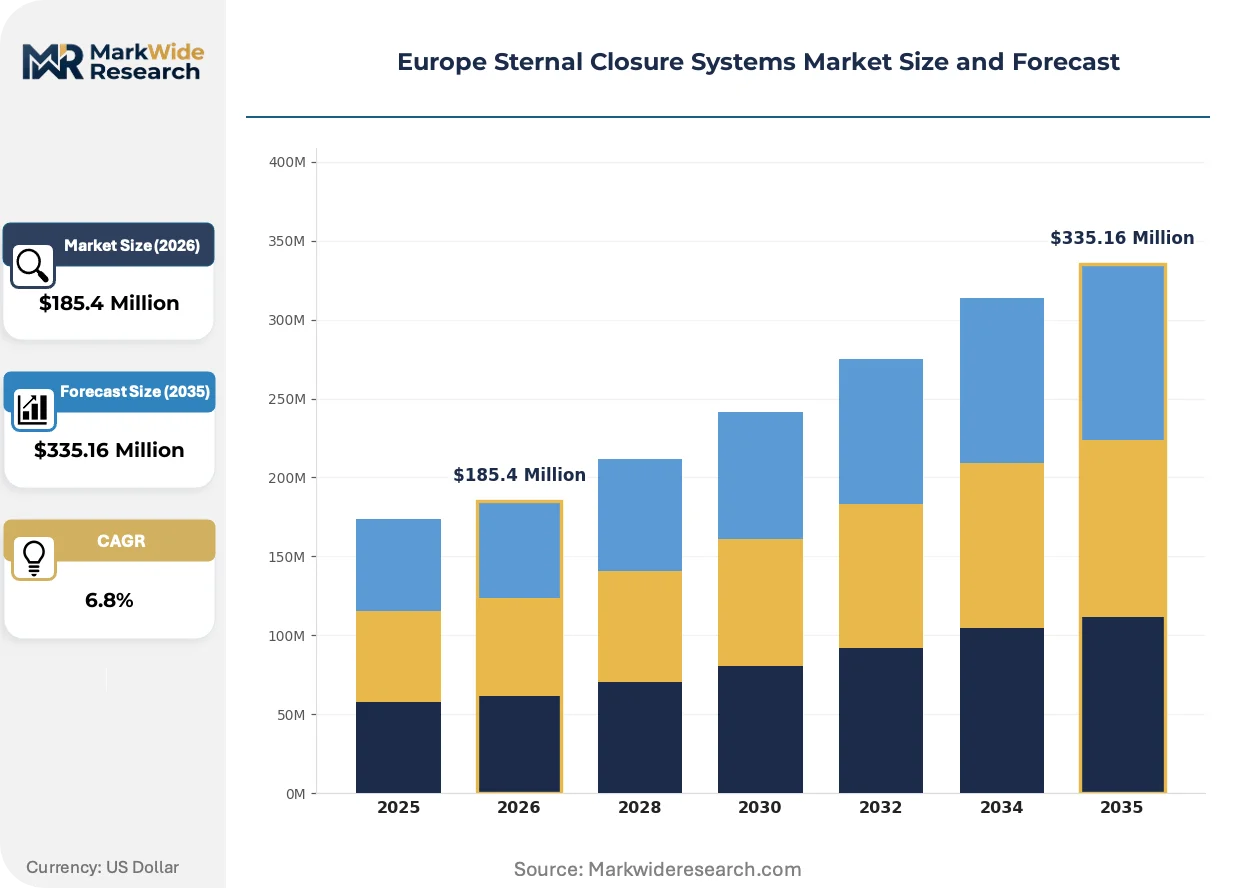
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sternal Clips, Sternal Wires, Plate Systems, Adhesives End User: Hospitals, Cardiac Centers, Specialty Clinics, Research Institutions Material: Metallic, Biodegradable Polymers, Titanium, Stainless Steel Technology: Manual Closure, Automated Systems, Hybrid Techniques, Biologic Approaches |
| Companies Covered | Zimmer Biomet, Johnson & Johnson, KLS Martin Group, B. Braun, Stryker, Acumed LLC, IDEAR SRL, Orthofix, Kinamed Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sternal Closure Systems Market Strategic Shifts & Innovations
Automated closure technologies are fragmenting traditional manual technique dominance while regulatory sustainability mandates and procurement centralization reshape competitive positioning across European cardiac surgery supply chains.
Patient-specific 3D-printed titanium plates with anatomically contoured geometries are decentralizing sternal fixation planning from centralized implant libraries toward hospital-based additive manufacturing partnerships. University hospitals in Heidelberg and Leuven are piloting in-house printing workflows that compress preoperative planning from weeks to days. This distributed production model is decentralizing inventory risk and enabling same-day customization for complex redo sternotomy cases.
CE marking under the EU MDR and expanded EMA device oversight are forcing manufacturers to submit post-market clinical follow-up data that wire-based legacy systems never generated. The Netherlands-based notified bodies are conducting deeper design dossier reviews that extend titanium plate approval cycles by 8-14 months. Cardiac centers in Scandinavia are responding by consolidating purchasing around suppliers with established MDR technical documentation, compressing vendor shortlists.
Hospital procurement consortia across France and Belgium are unbundling device pricing from service contracts, forcing manufacturers to compete on standalone implant cost rather than bundled training and support. Group purchasing organizations in the Paris and Brussels metro areas are centralizing sternal closure tenders that previously ran through individual cardiac surgery departments. This concentration is most visible in Belgian academic medical centers, where three-hospital alliances now negotiate multi-year plate system agreements.
Europe Sternal Closure Systems Market Segmentation
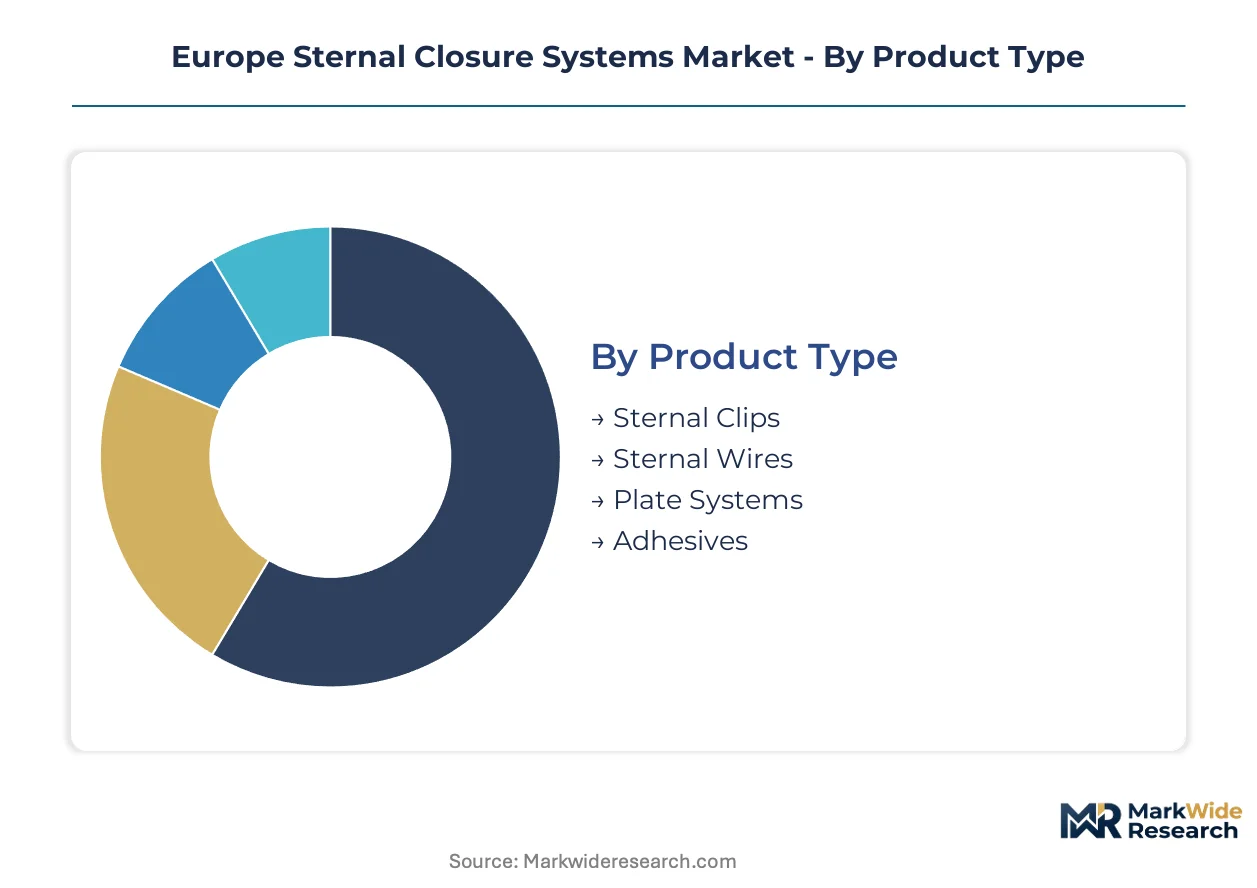
European cardiac surgery procurement increasingly segments around fixation performance specifications and MDR compliance tiers rather than traditional price-based categories. Surgeons in German and Italian centers now specify closure systems by biomechanical load tolerance and sterilization workflow compatibility.
Product Type:
Titanium plate systems with locking screw interfaces now anchor premium positioning while stainless steel wires retain volume leadership in cost-constrained procurement channels.
- Plate Systems:Titanium locking plates with 300+ N load tolerance dominate German cardiac center adoption following MDR clinical evidence requirements. Milan and Munich teaching hospitals specify these for complex redo sternotomy cases where sternal non-union risks escalate.
- Sternal Wires:Stainless steel 316L configurations remain the default across Polish and Romanian public hospitals where reimbursement caps compress device budgets. Wire techniques require minimal surgeon retraining, preserving utilization in Eastern European facilities.
- Sternal Clips:Compression clip systems offer intermediate fixation strength for standard median sternotomy procedures in Belgian and French community hospitals.
- Adhesives:Cyanoacrylate and fibrin-based adjuncts supplement mechanical fixation in Leuven and Heidelberg university protocols.
Plate systems lead on scale; plate systems lead on momentum.
End User:
Procurement centralization across metropolitan hospital consortia is collapsing traditional distinctions between academic and community cardiac surgery volumes.
- Cardiac Centers:Dedicated cardiothoracic units in Germany and Italy drive titanium plate specification through surgeon preference for hybrid closure protocols. Three-hospital alliances in Brussels and Paris now negotiate multi-year plate system agreements.
- Hospitals:General acute care facilities across Iberia and the Balkans represent underpenetrated volumes where MDR compliance costs have not yet consolidated vendor shortlists.
- Specialty Clinics:Ambulatory surgical centers in Scandinavia concentrate on low-complexity coronary bypass volumes.
- Research Institutions:University hospitals in Heidelberg and Leuven pilot patient-specific 3D-printed titanium workflows.
Cardiac centers command pricing power; hospitals represent untapped expansion terrain.
Material:
ECHA substance restrictions and EU Green Deal sustainability criteria are forcing material disclosure that favors recyclable titanium over nickel-bearing alternatives.
- Titanium:Ti-6Al-4V ELI alloy delivers superior fatigue resistance and biocompatibility for locking plate systems. German forgers source sponge from Russian and Chinese refiners, exposing supply chains to geopolitical volatility.
- Biodegradable Polymers:Polylactic acid and polyglycolic acid research pipelines anticipate future MDR sustainability mandates. Absorbable fixation alternatives redirect R&D investment across European manufacturers.
- Stainless Steel:316L formulations face proposed ECHA nickel restrictions that threaten Southern European wire supply chains.
- Metallic:Cobalt-chrome and nitinol alloys occupy niche applications in sternal clip configurations.
Titanium dominates current revenue; biodegradable polymers climb the fastest.
Technology:
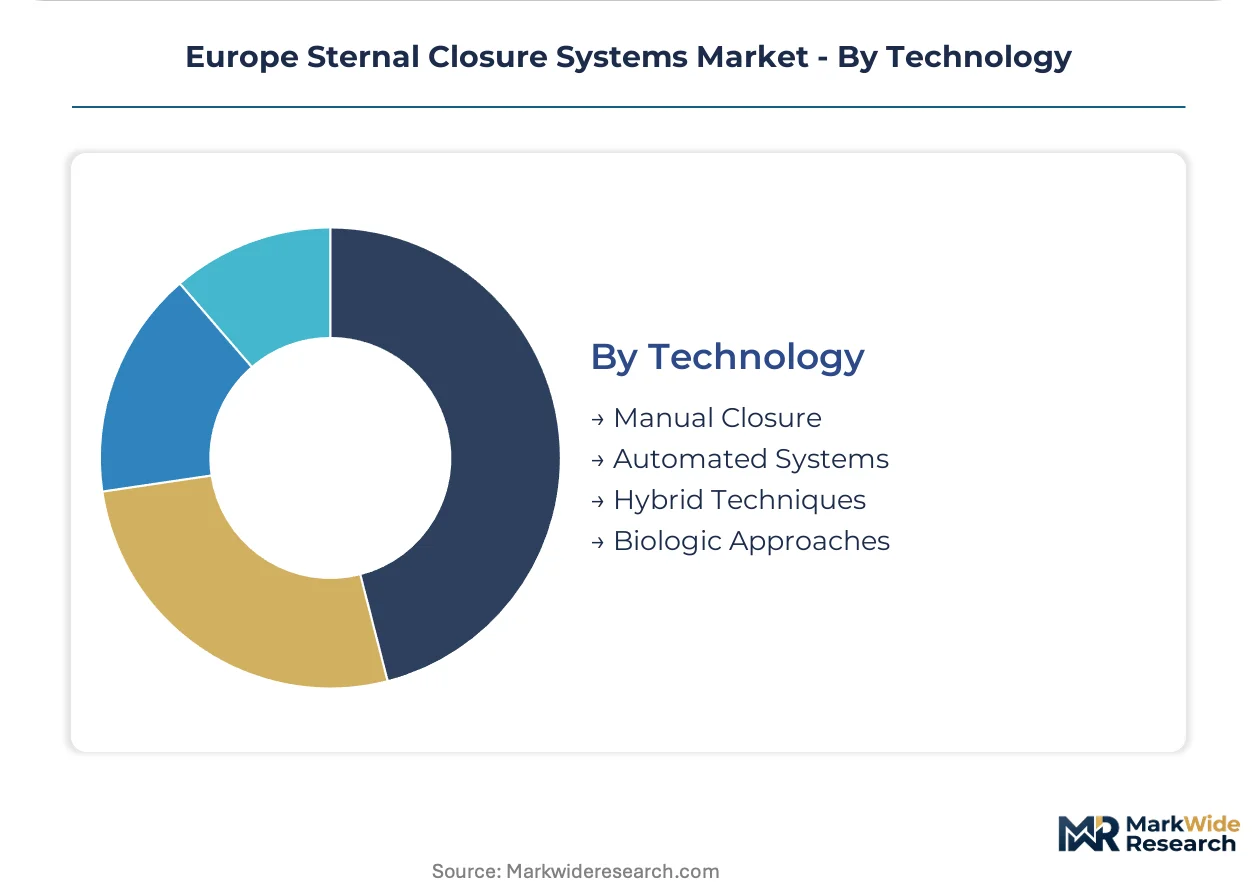
Automated closure systems fragment traditional manual technique dominance while hybrid methods gain surgeon adoption across Western European teaching hospitals.
- Hybrid Techniques:Plate-and-wire combinations reduce sternal non-union rates in Milan and Munich cardiac centers. These protocols expand addressable procedure volumes for patients with osteoporosis or diabetes.
- Automated Systems:Robotic-assisted closure platforms gain traction in Scandinavian facilities with capital budget flexibility. Eastern European adoption remains constrained by equipment procurement cycles.
- Manual Closure:Traditional wire twisting techniques persist in volume across Romanian and Polish public hospitals.
- Biologic Approaches:Osteoinductive coatings and bone graft adjuncts complement mechanical fixation in complex revision cases.
Manual closure retains volume leadership; hybrid techniques gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cardiac surgery clusters anchor European sternal closure demand through titanium plate adoption following MDR enforcement. Western European teaching hospitals drive premium fixation specification while Eastern European facilities retain cost-sensitive procurement patterns.
Germany
Munich and Heidelberg cardiac centers specify hybrid plate-and-wire protocols for complex redo sternotomy cases. The EU MDR streamlines titanium plate approvals through German notified bodies using equivalence pathways. Bavarian university hospitals pilot patient-specific 3D-printed titanium workflows that compress preoperative planning timelines.
Italy
Milan teaching hospitals combine locking plate interfaces with traditional wires to reduce sternal non-union rates in diabetic patients. CE marking requirements under MDR extend approval cycles for new fixation systems entering the Italian market. Lombardy cardiac surgery volumes concentrate procurement influence among three major metropolitan hospital networks.
France
Paris metro hospital consortia centralize sternal closure tenders that previously ran through individual cardiac surgery departments. The EU Green Deal sustainability criteria force material disclosure requirements favoring recyclable titanium over polymer alternatives. Ile-de-France academic medical centers negotiate multi-year plate system agreements through three-hospital alliances.
Belgium
Brussels cardiac centers consolidate purchasing around suppliers with established MDR technical documentation, compressing vendor shortlists. ECHA substance restrictions on nickel-bearing alloys threaten 316L stainless steel wire formulations across Belgian supply chains. Leuven university hospitals pioneer osteoinductive coating protocols that complement mechanical fixation in complex revision cases.
Poland
Public hospital procurement in Warsaw and Krakow retains mature stainless steel wire systems due to reimbursement caps that compress device budgets. National health ministry procurement frameworks prioritize cost containment over premium fixation technology adoption. Polish cardiac surgery volumes remain underpenetrated for titanium plate systems despite growing Western European influence.
Europe Sternal Closure Systems Market Key Industry Players
Global majors compete with regional champions across regulatory compliance capabilities and sterile packaging workflows. Market structure tilts toward consolidated premium tiers where MDR technical documentation creates vendor selection barriers, while cost-sensitive Eastern European channels sustain fragmented wire-system competition. Three archetypes dominate: diversified orthopedic conglomerates with captive forging partnerships, specialized German and Italian distribution anchors, and sterile packaging innovators reducing OR preparation friction. Competitive moves concentrate on MDR dossier acceleration and hospital consortium tender consolidation.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker occupy positions where scale-driven regulatory resources and captive supply arrangements reinforce market presence. KLS Martin Group exemplifies the specialized regional champion archetype through focused distribution across German and Italian cardiac centers. B. Braun represents sterile packaging differentiation that reduces operating room preparation time against traditional bulk configurations.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Johnson & Johnson |
| KLS Martin Group |
| B. Braun |
| Stryker |
| Acumed LLC |
| IDEAR SRL |
| Orthofix |
| Kinamed Incorporated |
| Others |
Cost & Logistics Intelligence
Sponge titanium price indices from Russian and Chinese refiners cascade through European forging networks into three-tier pricing structures across plate systems, wire configurations, and clip-based alternatives. German cardiac centers absorb premium plate costs through consolidated procurement consortia while Eastern European public hospitals amplify price sensitivity in wire-dominated tiers.
Pricing Analysis
Input-cost pass-through from titanium alloy feedstock anchors premium plate pricing at German and Italian cardiac centers, where CE marking under MDR tiers separate validated locking interfaces from legacy wire alternatives. Price differentiation stratifies across biomechanical load tolerance, sterile packaging configuration, and surgeon training bundling. Cost compression in stainless steel wire tiers intensifies because Polish and Romanian reimbursement caps compress device budgets. Public hospital procurement committees exhibit highest price sensitivity; German teaching hospital alliances demonstrate lowest sensitivity due to outcome-based contracting.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Milan, and Rotterdam orchestrate hub-and-spoke patterns that position pre-sterilized kits within 48-hour reach of Western European cardiac surgery clusters. Manufacturing concentrates in Germany, Switzerland, and the Netherlands, with titanium sponge drawing from Russian and Chinese refiners. Single-source vulnerability in alloy feedstock exposes plate manufacturers to geopolitical disruption. Distribution runs through specialized cardiovascular device distributors rather than broadline medical supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Sternal Closure Systems functions as a stable compounder anchored by irreplaceable cardiac surgery volumes and MDR-driven vendor consolidation that protects incumbent positions.
For Market Incumbents: Hedge titanium supply exposure through dual-source sponge arrangements with Chinese and alternative refiners while accelerating MDR technical documentation for plate system line extensions. Biodegradable polymer substitutes threaten long-term titanium dominance; sterile packaging capabilities defend channel position against bulk-configuration competitors. For New Entrants and Emerging Players: Launch via direct hospital contracting in Portuguese and Greek cardiac centers where MDR compliance costs have not yet consolidated vendor shortlists. Iberian and Balkan markets offer white-space penetration before procurement centralization accelerates. Target automated closure platforms for Scandinavian facilities with capital budget flexibility. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR dossier capabilities separate viable suppliers from stranded wire-system manufacturers without clinical evidence infrastructure. Five-to-ten year viability favors specialized distribution anchors with German and Italian cardiac center relationships over diversified orthopedic conglomerates facing portfolio rationalization. Monitor ECHA nickel restriction timelines as inflection signal for stainless steel wire segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | German notified body equivalence pathways compress titanium plate approval timelines against wire-system legacy documentation gaps. |
| Hospital System Partnership | Three-hospital alliances in Paris and Brussels centralize multi-year plate system agreements that collapse vendor shortlists. |
| Backward Integration into Titanium Forging | Captive alloy consistency partnerships insulate plate manufacturers from Russian and Chinese sponge price volatility. |
| Sterile Packaging Innovation | Pre-sterilized kit configurations reduce OR preparation time and differentiate against traditional bulk packaging workflows. |
| Biodegradable Polymer R&D Investment | EU Green Deal sustainability criteria redirect pipeline investment toward absorbable fixation alternatives ahead of MDR material disclosure mandates. |
Research Approach
Bottom-up cardiac procedure volume modeling reconciled against top-down implant shipment tracking forms the analytical core of this study. Primary interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers cross-validated against secondary sources including EMA device registration databases, German hospital procurement records, and EU MDR notified body approval filings. Triangulation between demand-side utilization patterns and supply-side manufacturing disclosures anchors segmentation integrity.
Input-output matrices map titanium plate, wire, and clip system flows across German, Italian, French, Belgian, and Polish end-use facilities throughout the projection horizon. Segmentation dimensions span product type, material composition, end-user facility tier, and technology adoption intensity. CAGRs derive from procedure volume trajectories modulated by MDR compliance cost pass-through and reimbursement framework evolution. Forecast inputs incorporate cardiac surgery demographic drivers and hybrid closure technique diffusion curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA nickel restriction enforcement or titanium supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Global Casting Devices Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Supraglottic Device Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Kirschner Wires Market
Medical Devices
Clot Management Devices Market
Medical Devices
Breathing Circuits Market
Medical Devices
Endoprosthesis Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Global Surgical Polypropylene Mesh Market