
 Global Non Fusion Spinal Devices Market | 2026-2036
Global Non Fusion Spinal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non Fusion Spinal Devices Market Foresight
Buyer concentration among ambulatory surgical centers is restructuring procurement dynamics across the non fusion spinal devices landscape. Medtronic leverages its integrated spine platform to dominate hospital system contracts, while NuVasive Inc. differentiates through lateral single-position surgery workflows that reduce operative time. Globus Medical specializes in expandable interbody technologies that compete directly with traditional fusion systems.
Non fusion spinal devices encompass motion-preserving implants including artificial discs, dynamic stabilization systems, and interspinous spacers engineered from titanium alloys, PEEK polymers, or porous titanium structures to maintain segmental mobility while relieving neural compression. These devices serve primarily to treat degenerative disc disease and spinal stenosis in patients requiring alternatives to arthrodesis. Artificial discs command premium positioning due to favorable long-term biomechanical outcomes, while dynamic stabilization devices represent the fastest-growing product category as surgeons seek intermediate solutions between decompression and fusion. Posterior stabilization systems occupy mature margin pools sustained by established reimbursement codes and broad surgeon familiarity.
FDA premarket approval pathways and EU MDR technical documentation requirements shape product development timelines and commercial access for manufacturers across multiple jurisdictions. Japan's PMDA and Health Canada impose additional clinical evidence standards that filter market entrants by trial infrastructure capability. Stakeholders must monitor evolving real-world evidence requirements from payers in the United States and Germany as value-based frameworks tighten coverage criteria for motion-preserving interventions.
Market Dynamics
Ambulatory surgical centers now capture a rising share of motion-preserving spine procedures, compressing hospital procurement timelines and forcing manufacturers to reconfigure distribution networks around same-day discharge protocols.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress commercialization cycles for artificial disc implants, enabling faster patient access to motion-preserving alternatives.
- PEEK Polymer Biocompatibility:Advanced polymer formulations reduce inflammatory response rates, expanding surgeon confidence in dynamic stabilization systems for younger patient cohorts.
- Japan's Aging Demographics:Procedural volume expansion in Tokyo and Osaka metropolitan areas drives demand for cervical artificial discs as alternatives to fusion in active elderly populations.
Market Restraints
- Titanium Alloy Input Volatility:Aerospace and defense sector competition for medical-grade titanium creates price instability for porous implant manufacturers.
- EU MDR Technical Documentation:Expanded clinical evidence requirements for Class III devices extend recertification timelines, freezing product portfolios for mid-tier manufacturers.
- Arthrodesis Substitution Threat:Robotic-assisted fusion systems with guaranteed reimbursement codes pull surgeons toward established fusion protocols despite motion-preserving alternatives.
Strategic Opportunities
- Germany's Value-Based Reimbursement:Real-world evidence frameworks reward long-term biomechanical outcomes, creating premium positioning for artificial disc manufacturers with decade-plus follow-up data.
- 3D-Printed Porous Titanium Convergence:Additive manufacturing integration with patient-specific imaging enables custom interbody geometries that match individual vertebral endplate morphology.
- Direct-to-Ambulatory Distribution:Bypassing hospital purchasing committees through specialized spine distributors serving freestanding surgical centers reduces sales cycle friction.
Industry Challenges
- Surgeon Retraining Requirements:Lateral single-position surgery and motion-preserving implantation demand specialized fellowship programs that extend sales force education timelines.
- EU MDR Notified Body Bottlenecks:Consolidation of certification bodies under stricter oversight creates 18-24 month backlogs for technical file reviews.
- Legacy Hospital Contract Lock-In:Integrated delivery network purchasing agreements bundle fusion and non-fusion devices, blocking standalone non-fusion vendors from formulary access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non Fusion Spinal Devices Market |
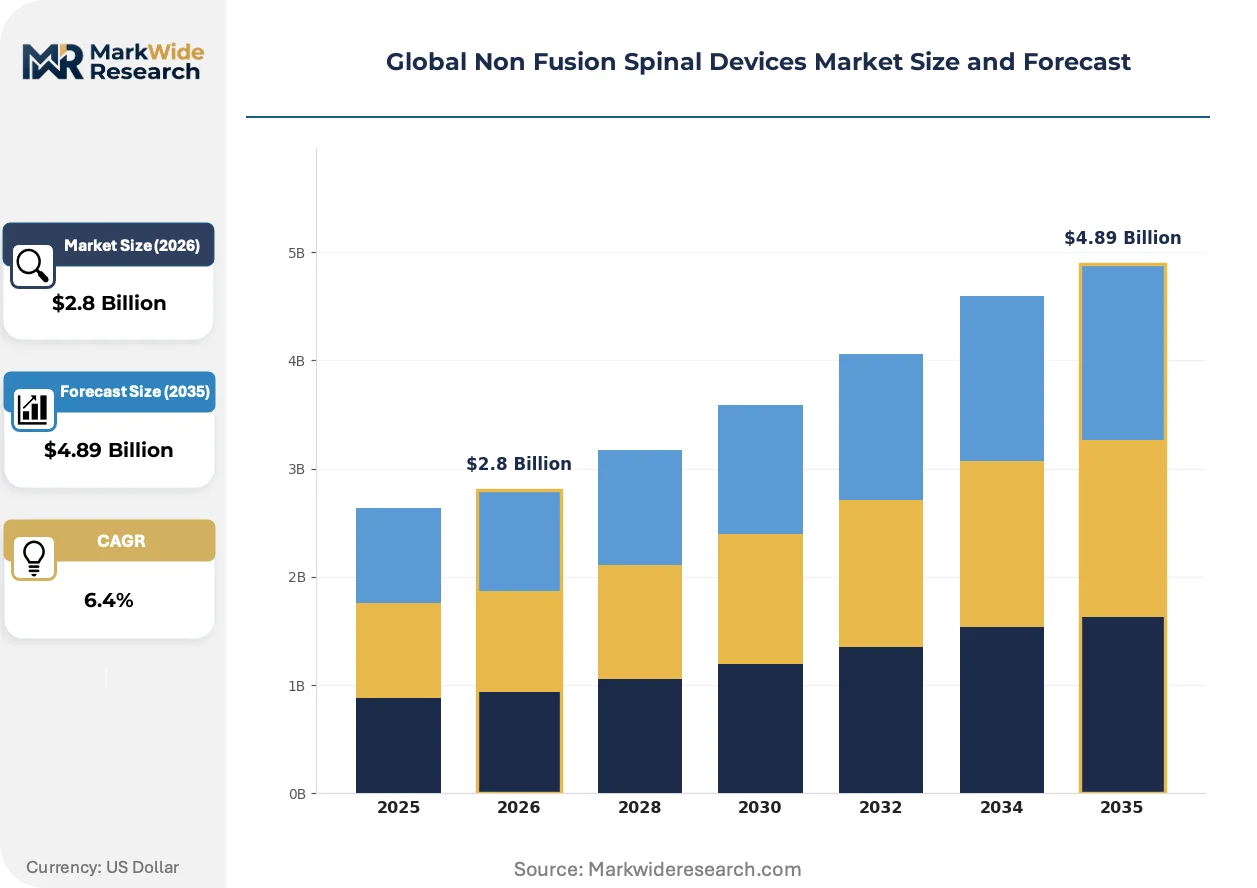
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interspinous Spacers, Dynamic Stabilization Devices, Artificial Discs, Posterior Stabilization Systems Application: Degenerative Disc Disease, Spondylolisthesis, Spinal Stenosis, Trauma End User: Hospitals, Ambulatory Surgical Centers, Clinics, Rehabilitation Centers Material: Metal, Polymer, Composite, Biomaterials |
| Companies Covered | Medtronic, Stryker Corporation, NuVasive Inc., ZimVie Inc., B. Braun SE, Globus Medical, Orthofix Medical Inc., Johnson & Johnson, Centinel Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non Fusion Spinal Devices Market Shifts & Advancements
Motion-preserving implant design is converging with additive manufacturing and surface engineering, enabling patient-matched geometries that were economically unfeasible under subtractive machining paradigms.
Expandable interbody cage technology is consolidating competitive positioning in the lumbar spacer segment. Ambulatory surgical centers in the United States adopt these devices at accelerating rates because intraoperative height adjustment eliminates multiple implant trials. This capability is compressing operative time and reducing fluoroscopy exposure, consolidating expandable systems as the default choice over static PEEK cages in outpatient settings.
Japan's PMDA has tightened post-market surveillance requirements for artificial disc implants, mandating 10-year follow-up registries for cervical and lumbar devices. Manufacturers must now submit annual adverse event reports and biomechanical performance data. Cervical disc replacement portfolios face the steepest compliance burden, with sponsors in Tokyo and Osaka restructuring clinical affairs departments to manage real-world evidence collection.
Hospital purchasing committees are fragmenting into specialty-specific decision units, with spine service lines gaining autonomous procurement authority separate from central supply chains. Ambulatory surgical centers in Germany and the United States lead this disintermediation, negotiating directly with manufacturers for motion-preserving device contracts. This pattern is most visible in metropolitan markets where freestanding spine centers compete aggressively with hospital outpatient departments for commercially insured patients.
Global Non Fusion Spinal Devices Market Segmentation
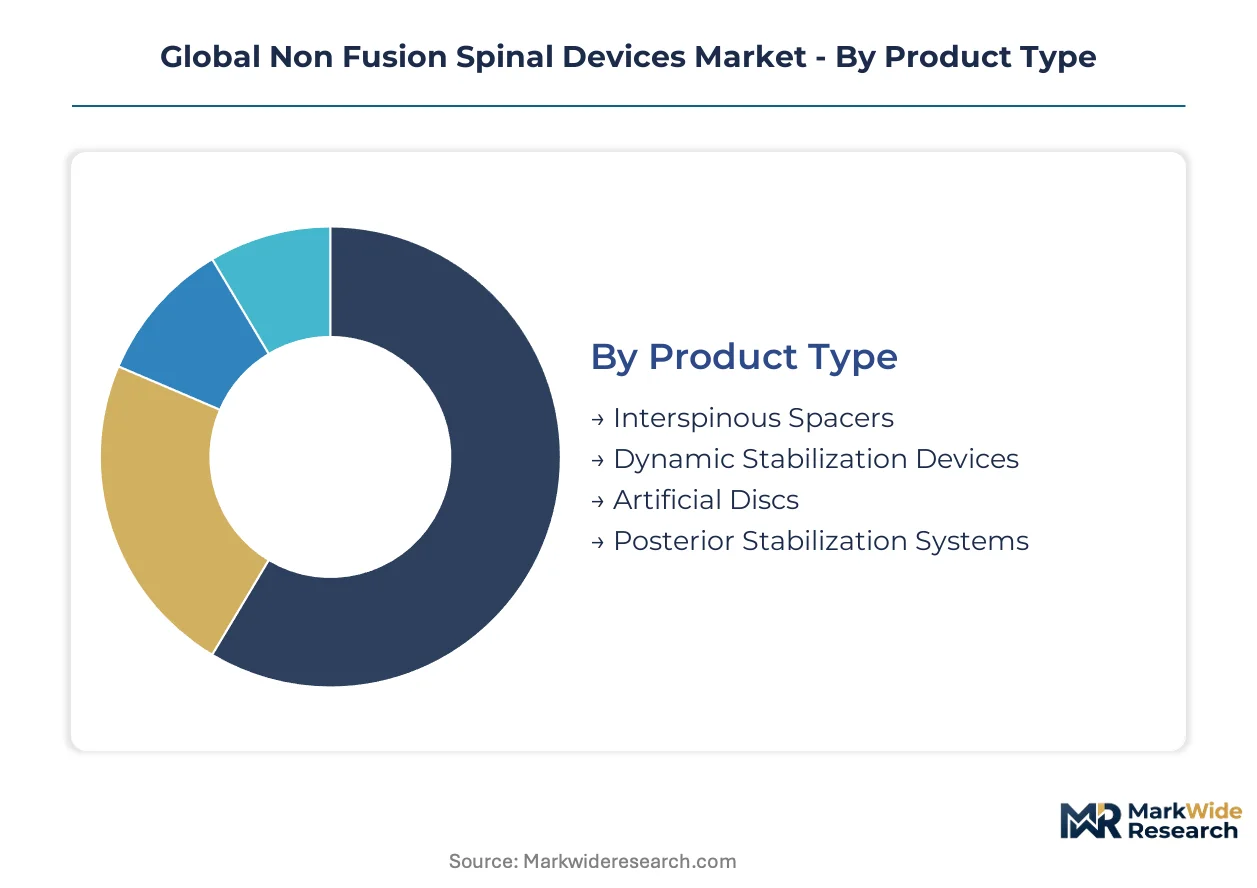
Segmentation in non fusion spinal devices reveals how procurement authority, reimbursement pathways, and material science converge to determine commercial outcomes. Manufacturers must align product portfolios with the specific decision-making structures of ambulatory surgical centers versus hospital systems, while navigating divergent clinical evidence requirements across motion-preserving technologies.
Product Type:
Surgeon familiarity with implantation technique and long-term biomechanical data availability drive purchasing committee preferences across motion-preserving categories.
- Artificial Discs:Titanium alloy and PEEK polymer constructs replace native disc structures to preserve segmental rotation and flexion-extension. Demand concentrates in the United States and Germany where FDA premarket approval and EU MDR certification enable favorable reimbursement for cervical and lumbar arthroplasty in active patient cohorts seeking alternatives to fusion.
- Dynamic Stabilization Devices:Pedicle screw-based systems with flexible rods or interspinous tension bands limit excessive motion while avoiding complete immobilization. Ambulatory surgical centers in Japan and the United States are expanding procedural volumes fastest as intermediate solutions between decompression and fusion gain acceptance among younger patients with early degenerative changes.
- Interspinous Spacers:Minimally invasive implants distract spinous processes to relieve neurogenic claudication in lumbar spinal stenosis.
- Posterior Stabilization Systems:Rigid rod-screw constructs for posterior non-fusion stabilization occupy mature reimbursement codes with established hospital contracts.
Volume sits with posterior stabilization systems; growth tilts toward dynamic stabilization devices.
Application:
Pathology severity and patient age stratify addressable populations across decompression-preservation versus motion-restoration interventions.
- Degenerative Disc Disease:Progressive disc dehydration and height loss drive neural compression in the cervical and lumbar spine. Cervical artificial disc replacement in patients under 65 dominates volume in the United States and Japan where payers cover motion-preserving alternatives to fusion for single-level pathology.
- Spinal Stenosis:Central canal and foraminal narrowing from ligamentum flavum hypertrophy and facet arthropathy produces neurogenic symptoms. Interspinous spacer adoption is climbing the fastest in German ambulatory surgical centers where minimally invasive decompression with motion preservation aligns with value-based reimbursement frameworks rewarding reduced hospitalization.
- Spondylolisthesis:Vertebral slip from pars defect or degenerative facet incompetence challenges motion-preserving approaches.
- Trauma:Acute fracture and dislocation scenarios rarely accommodate elective motion-preserving implantation.
Procedural volume concentrates in degenerative disc disease; steepest expansion trajectory belongs to spinal stenosis interventions.
End User:
Capital intensity and case complexity determine site-of-service economics for motion-preserving spine procedures.
- Ambulatory Surgical Centers:Freestanding facilities with specialized anesthesia and rapid-recovery protocols perform same-day cervical disc replacement and lumbar interspinous spacer placement. Procurement in the United States bypasses hospital purchasing committees through direct distributor relationships, compressing sales cycles for manufacturers with outpatient-focused product configurations.
- Hospitals:Academic medical centers and community hospital systems retain complex multi-level cases and revision surgeries requiring overnight observation. Integrated delivery networks in Germany and Japan bundle fusion and non-fusion device contracts, blocking standalone vendors without full spine portfolios.
- Clinics:Office-based settings provide diagnostic and conservative management without surgical implantation capacity.
- Rehabilitation Centers:Post-acute facilities manage recovery following hospital or ASC discharge without direct device procurement authority.
Revenue concentration remains with hospitals; ambulatory surgical centers are gaining share fastest.
Material:
Biocompatibility profiles and manufacturing scalability determine cost structures and regulatory clearance pathways.
- Metal:Titanium alloys and cobalt-chromium enable porous ingrowth surfaces and radiolucent imaging compatibility. Porous titanium structures produced via additive manufacturing are expanding most quickly in Japan and the United States where patient-matched interbody geometries command premium pricing.
- Polymer:PEEK and radiopaque PEEK-OPTIMA formulations provide modulus-matching to vertebral bone with reduced stress shielding. Dynamic stabilization demand in Germany favors polymer rod systems for reduced inflammatory response in younger, active patients.
- Composite:Carbon fiber-reinforced polymers combine strength with radiolucency for postoperative imaging assessment.
- Biomaterials:Resorbable polymers and bone graft substitutes occupy adjunctive roles rather than primary load-bearing applications.
Implant volume concentrates in metal constructs; polymer formulations are expanding fastest in dynamic stabilization segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where aging populations and reimbursement clarity support procedural volume expansion for motion-preserving alternatives to spinal fusion.
United States
FDA breakthrough device designations compress commercialization timelines for artificial disc implants. Ambulatory surgical centers in Florida and Texas negotiate directly with manufacturers, bypassing hospital purchasing committees. The Southeast corridor from Atlanta to Dallas captures accelerating outpatient migration for cervical disc replacement procedures.
Germany
Value-based reimbursement frameworks reward long-term biomechanical outcomes from motion-preserving interventions. EU MDR recertification timelines filter mid-tier manufacturers from the Class III device market. The Rhine-Ruhr metropolitan cluster around Düsseldorf and Cologne hosts specialized spine distributors serving freestanding surgical centers.
Japan
PMDA mandates 10-year follow-up registries for cervical and lumbar artificial disc implants. Tokyo and Osaka metropolitan areas drive procedural volume expansion for active elderly populations seeking alternatives to fusion. Kanto region manufacturers restructure clinical affairs departments to manage real-world evidence collection.
Switzerland
Swissmedic maintains stringent clinical evidence standards that favor established players with decade-plus follow-up data. Zurich and Geneva medical centers pioneer patient-matched interbody geometries using additive manufacturing. The Basel pharmaceutical corridor influences adjacent medical device regulatory expectations.
United Kingdom
NICE technology appraisals determine coverage criteria for dynamic stabilization systems in the National Health Service. London and Manchester academic medical centers retain complex multi-level cases requiring overnight observation. Integrated care systems bundle fusion and non-fusion device contracts, blocking standalone vendors.
Global Non Fusion Spinal Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue patient-specific additive manufacturing and ambulatory-focused distribution models. The vendor base stratifies across integrated spine platforms, lateral surgery workflow specialists, and expandable interbody technology developers. Three archetypes dominate: diversified orthopedic conglomerates with hospital system contracts, mid-cap spine pure-plays with surgeon training ecosystems, and additive manufacturing specialists with porous titanium capabilities. Competitive moves concentrate on M&A for complementary motion-preserving portfolios and direct-to-ASC distribution partnerships that bypass traditional purchasing committees.
Among diversified orthopedic conglomerates, Medtronic and Stryker Corporation anchor the integrated platform tier with comprehensive spine portfolios spanning fusion and non-fusion modalities. NuVasive Inc. exemplifies the workflow-specialist archetype through its lateral single-position surgery positioning. Globus Medical occupies a distinct position in expandable interbody technology competing directly with traditional fusion systems.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| NuVasive Inc. |
| ZimVie Inc. |
| B. Braun SE |
| Globus Medical |
| Orthofix Medical Inc. |
| Johnson & Johnson |
| Centinel Spine |
| Others |
Supply & Pricing Matrix
Additive manufacturing adoption for porous titanium interbody devices simultaneously compresses per-unit production costs at scale and concentrates supply capability among manufacturers with capital-intensive 3D printing infrastructure. This technology transition rewards early movers with patient-matched geometry capabilities while locking out mid-tier competitors from premium pricing tiers.
Pricing Analysis
Volume concentrates in posterior stabilization systems with commoditized reimbursement codes, while margins concentrate in artificial disc portfolios where decade-plus follow-up data commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated cervical discs from CE-marked dynamic stabilization systems and basic interspinous spacers. Pricing pressure stems from robotic-assisted fusion systems pulling surgeons toward guaranteed-reimbursement arthrodesis protocols. Ambulatory surgical centers exhibit highest price sensitivity as direct distributor negotiations compress procurement margins, while academic medical centers absorb premium tiers for complex multi-level cases.
Supply Chain Analysis
Specialized biomedical engineers and additive manufacturing technicians concentrate in Switzerland, the United States, and Germany, constraining production scaling for patient-matched implant geometries. Raw material dependencies center on medical-grade titanium alloys from aerospace-certified suppliers, PEEK polymer feedstock from specialty chemical producers, and cobalt-chromium for bearing surfaces. Single-source vulnerability runs through aerospace sector competition for medical-grade titanium creating input price volatility. Distribution runs through specialized spine distributors serving ambulatory surgical centers directly, bypassing hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body bottlenecks constrain Class III device recertification capacity, propping pricing power for manufacturers with cleared technical files while freezing mid-tier competitors from market access.
For Market Incumbents: Lock in ambulatory surgical center distribution partnerships before hospital systems consolidate purchasing authority through integrated delivery networks. Deepen backward integration into medical-grade titanium supply through captive sourcing agreements with aerospace-certified mills, insulating production from input volatility. Prioritize real-world evidence collection for artificial disc portfolios to defend premium positioning against robotic-assisted fusion substitution threats. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for artificial disc challengers with novel biomaterial constructs to compress commercialization timelines against established players. Target German ambulatory surgical centers where value-based reimbursement rewards long-term biomechanical outcomes and hospital purchasing committee fragmentation enables direct distributor access. Lead with patient-specific additive manufacturing capabilities for porous titanium interbody devices, bypassing capital-intensive machining infrastructure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified orthopedic conglomerates seeking motion-preserving portfolio gaps. Five-to-ten year viability hinges on regulatory clearance durability and ambulatory surgical center channel penetration rather than hospital system contract breadth. Watch for FDA breakthrough device designation announcements as inflection indicators for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses commercialization cycles for artificial disc implants in the United States. |
| EU MDR Technical File Investment | Recertification readiness filters mid-tier manufacturers from Class III device market access. |
| Ambulatory Surgical Center Partnership | Direct distributor relationships bypass hospital purchasing committee lock-in for outpatient procedural volume. |
| Real-World Evidence Registry | Decade-plus follow-up data commands premium reimbursement in German value-based frameworks. |
| Additive Manufacturing Scale-Up | Patient-matched porous titanium geometries consolidate competitive positioning against subtractive machining. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with spine surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. FDA 510(k) and PMA databases, EU MDR notified body technical file registries, CMS Medicare reimbursement schedules, and hospital procurement databases provided validation. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue disclosures.
Data-stream reconciliation across product type, application pathology, end-user site of service, material composition, and regional regulatory cluster enabled forecast construction across the analysis window. CAGRs derived from segmented growth rate modeling incorporating ambulatory surgical center migration trajectories, aging demographic projections, and reimbursement policy evolution. Forecast inputs incorporated EU MDR recertification timeline assumptions and PMDA post-market surveillance burden impacts.
Caveats apply where EU MDR notified body capacity constraints or titanium alloy input volatility could materially shift the outlook. Forecasts reflect assumptions about ambulatory surgical center reimbursement durability and surgeon retraining program scaling. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Vaginal Applicators Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Global Medical Device Security Market