
 Veterinary Respiratory Ventilators Market | 2026-2036
Veterinary Respiratory Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Respiratory Ventilators Market Analytics
Silicone-based breathing circuits is rebalancing cost structures in mid-range ventilator assemblies as manufacturers reduce reliance on legacy PVC formulations. MIDEN MEDICAL leverages European manufacturing partnerships to sustain cost-competitive production of precision flow sensors. Midmark Corporation anchors North American distribution through dedicated veterinary equipment channels. Vetronic Services Ltd. specializes in aftermarket calibration protocols that extend installed-base longevity.
Veterinary respiratory ventilators are electromechanical life-support systems designed to deliver controlled oxygen mixtures to sedated or incapacitated animals, typically operating across pressure ranges of 0-60 cmH₂O and tidal volumes scaled to species-specific lung capacities from 0.5 mL to 20 L. These devices serve primary functions in anesthesia maintenance, acute respiratory failure intervention, and postoperative recovery monitoring across companion and production animal settings. Invasive ventilators dominate revenue contribution due to higher per-unit pricing and mandatory presence in tertiary veterinary hospitals, while portable ventilators represent the fastest-expanding category as field emergency services and mobile veterinary units multiply. Volume-controlled ventilation technology occupies the largest installed base, though pressure-controlled modes are gaining preference in brachycephalic breeds and small exotic species where barotrauma risks constrain treatment options.
FDA Center for Veterinary Medicine oversight shapes pre-market notification pathways for novel ventilator platforms, while ISO 80601-2-80 establishes international safety benchmarks for respiratory equipment deployed in animal care settings. USDA National Institute of Food and Agriculture funding priorities indirectly steer research facility procurement toward systems supporting large-animal surgical studies. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications as ventilator platforms integrate artificial intelligence-driven breath-pattern recognition algorithms.
Market Dynamics
ISO 80601-2-80 compliance requirements are compressing vendor development timelines while FDA Center for Veterinary Medicine pre-market notification pathways extend clearance durations for novel ventilator platforms.
Growth Catalysts
- Companion animal critical care standards:Emergency care units in specialty veterinary referral hospitals are expanding ventilator procurement as client expectations for intensive care capabilities rise.
- USDA NIFA funding priorities:Research facility procurement is steering toward systems supporting large-animal surgical studies, creating institutional demand for high-capacity ventilation platforms.
- Silicone-based breathing circuits:Manufacturers are reducing reliance on legacy PVC formulations, rebalancing cost structures in mid-range ventilator assemblies and improving biocompatibility profiles.
Market Restraints
- Precision flow sensor supply concentration:European manufacturing partnerships dominate component sourcing, creating vulnerability for North American assemblers facing logistics disruptions.
- Software-as-medical-device classification uncertainty:FDA guidance evolution on artificial intelligence-driven breath-pattern recognition algorithms is creating regulatory friction for platform developers.
- Field emergency service economics:Mobile veterinary units face capital intensity barriers that constrain portable ventilator penetration despite clinical utility.
Strategic Opportunities
- Brachycephalic breed specialization:Pressure-controlled ventilation modes are gaining preference in flat-faced companion species where barotrauma risks constrain treatment options, creating segment-specific product development white space.
- Aftermarket calibration services:Extended installed-base longevity protocols are emerging as a revenue diversification channel for technical service providers.
- Small exotic species adaptation:Tidal volume scaling below 50 mL represents an underserved technical frontier in avian and reptile critical care.
Industry Challenges
- Veterinary anesthesia technician certification:Specialized ventilator operation training programs remain inconsistently standardized across academic institutions, constraining clinical deployment.
- Legacy system integration:Tertiary hospitals face complexity connecting new pressure-controlled platforms to existing patient monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Respiratory Ventilators Market |
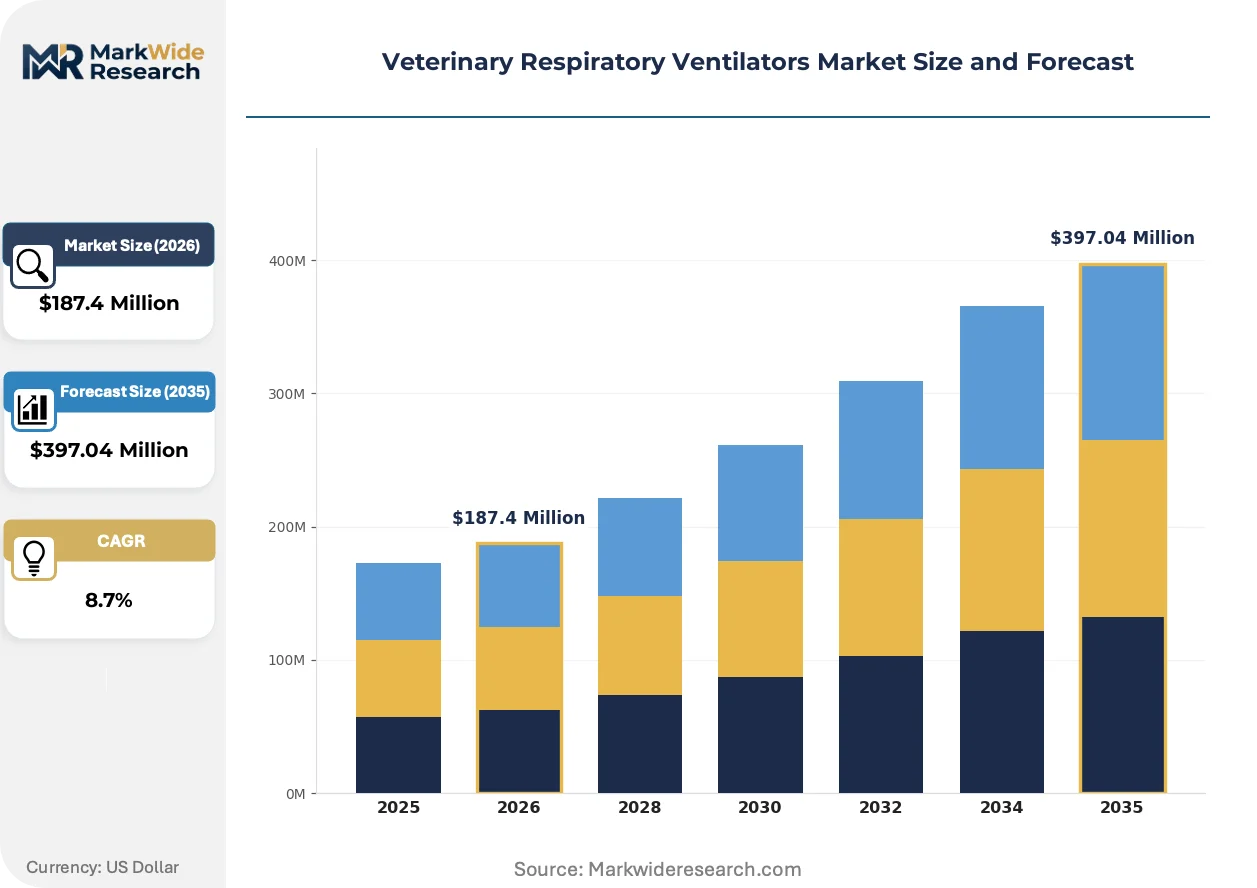
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Ventilators, Non-Invasive Ventilators, Portable Ventilators, Multi-Parameter Ventilators Application: Emergency Care, Anesthesia, Critical Care, Postoperative Care End User: Veterinary Hospitals, Clinics, Research Facilities, Animal Shelters Technology: Mechanical Ventilation, Volume-Controlled Ventilation, Pressure-Controlled Ventilation, BiPAP |
| Companies Covered | MIDEN MEDICAL, Midmark Corporation, Vetronic Services Ltd., Hallowell EMC, Metran Co., Ltd., RWD Life Science Co., LTD, EICKEMEYER, VetEquip Inc., MINERVE Veterinary Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Respiratory Ventilators Market Evolving Landscape
Artificial intelligence integration is redefining breath-pattern recognition capabilities while materials science advances and procurement model evolution reshape competitive positioning across the veterinary respiratory ventilator landscape.
Machine learning algorithms for automated respiratory parameter adjustment are consolidating control functions previously requiring manual clinician intervention. Tertiary veterinary hospitals in the United States are piloting these platforms for postoperative recovery monitoring. This consolidation is compressing the skill gap between general practice and specialty critical care settings.
FDA guidance development on software-as-medical-device classifications is creating compliance roadmaps for ventilator manufacturers integrating predictive analytics. The industrial consequence is extended pre-market notification preparation cycles for platform developers. Small exotic species ventilation systems face the most pronounced timeline impacts due to limited predicate device availability.
Service unbundling is separating ventilator hardware procurement from aftermarket calibration and maintenance contracts. Specialty veterinary referral hospitals are negotiating direct technical service agreements independent of original equipment manufacturers. This pattern is most visible in United States metropolitan markets with concentrated critical care infrastructure.
Veterinary Respiratory Ventilators Market Segmentation
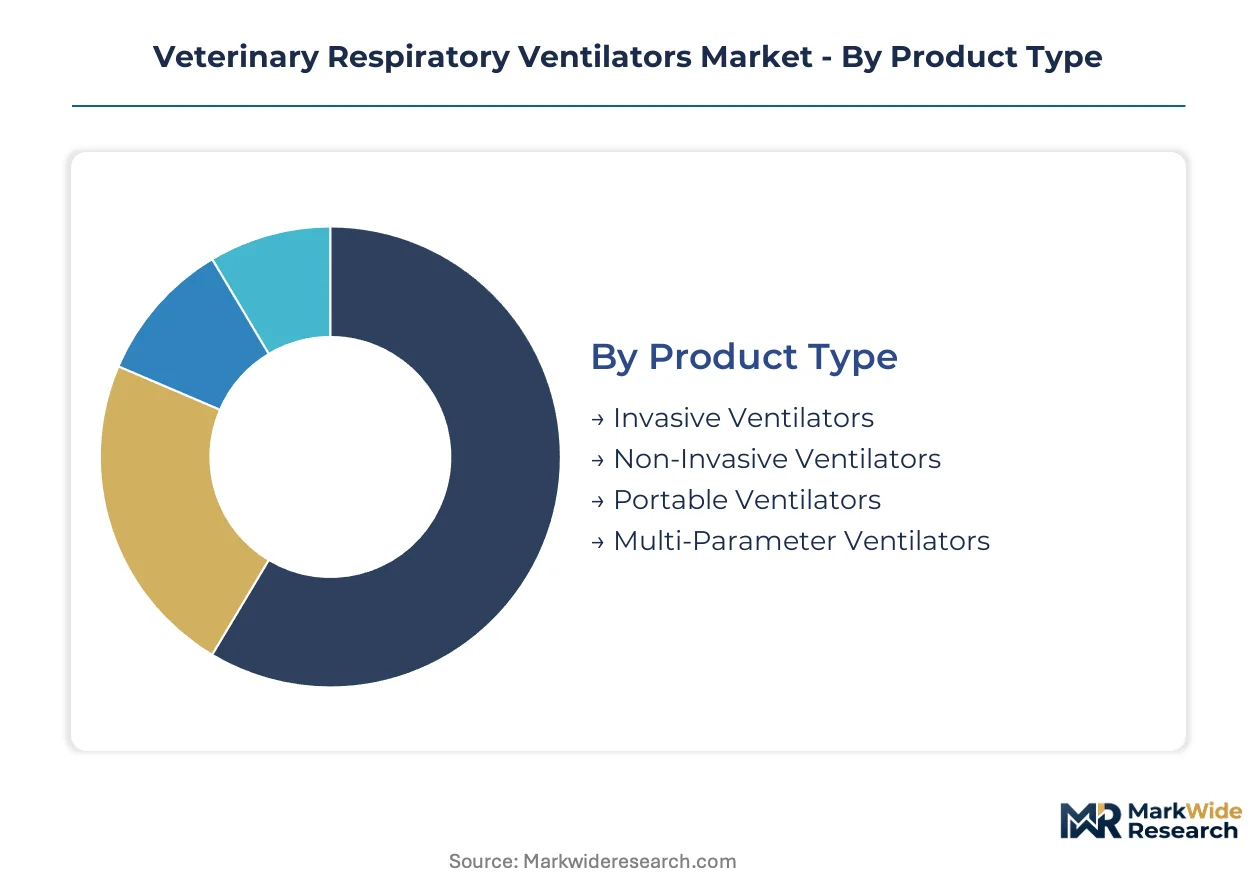
Segmentation in veterinary respiratory ventilators reveals divergent equipment requirements across clinical settings. Species size variation, procedure complexity, and facility infrastructure create distinct purchasing patterns that manufacturers must address through targeted platform configurations.
Product Type:
Invasive ventilators command premium positioning through higher per-unit pricing and mandatory presence in tertiary facilities, while portable systems capture volume expansion in field deployment.
- Invasive Ventilators:These systems deliver controlled oxygen mixtures via endotracheal tubes or tracheostomy, operating across pressure ranges of 0-60 cmH₂O with tidal volumes scaling to 20 L. Specialty veterinary referral hospitals in the United States drive procurement as companion animal critical care standards rise and client expectations for intensive care capabilities intensify.
- Portable Ventilators:Battery-powered units weighing under 15 kg enable field emergency services and mobile veterinary units to deliver mechanical ventilation outside hospital settings. Mobile veterinary units face capital intensity barriers that constrain penetration despite clinical utility, though demand is climbing fastest among equine emergency response teams and disaster relief organizations.
- Non-Invasive Ventilators:Mask-based systems avoid intubation for conscious patients with moderate respiratory distress.
- Multi-Parameter Ventilators:Integrated platforms combine ventilation with patient monitoring, anesthesia delivery, and data logging.
Today's leader: Invasive Ventilators. Tomorrow's challenger: Portable Ventilators.
Application:
Emergency care applications concentrate investment in rapid-deployment capabilities, whereas anesthesia maintenance prioritizes precision control and integration with surgical workflows.
- Emergency Care:Acute respiratory failure intervention demands immediate mechanical support with minimal setup time. Emergency care units in veterinary hospitals are expanding ventilator procurement as specialty referral networks extend 24-hour critical care coverage.
- Anesthesia:Controlled ventilation during surgical procedures requires seamless integration with gas delivery systems and patient monitoring architectures. Tertiary hospitals face complexity connecting new pressure-controlled platforms to existing monitoring infrastructures, creating upgrade friction.
- Critical Care:Extended mechanical ventilation for postoperative recovery and respiratory failure management.
- Postoperative Care:Weaning protocols and respiratory support following surgical intervention.
Emergency Care anchors current procurement volumes; Critical Care is gaining share fastest as recovery monitoring protocols extend ventilation duration.
End User:
Veterinary hospitals dominate capital expenditure, while research facilities follow distinct procurement cycles tied to grant funding timelines.
- Veterinary Hospitals:Tertiary and specialty referral institutions represent the primary installed base for high-capacity ventilation platforms. These facilities prioritize pressure-controlled modes for brachycephalic breeds and small exotic species where barotrauma risks constrain treatment options.
- Research Facilities:Institutional demand for large-animal surgical studies steers procurement toward systems supporting species from 5 kg to 500 kg. USDA National Institute of Food and Agriculture funding priorities indirectly shape equipment selection for agricultural and biomedical research programs.
- Clinics:General practice settings with limited critical care infrastructure.
- Animal Shelters:Non-profit operations with constrained capital budgets and intermittent ventilation needs.
Veterinary Hospitals hold installed-base dominance; Research Facilities present the steepest expansion trajectory as large-animal surgical study funding increases.
Technology:
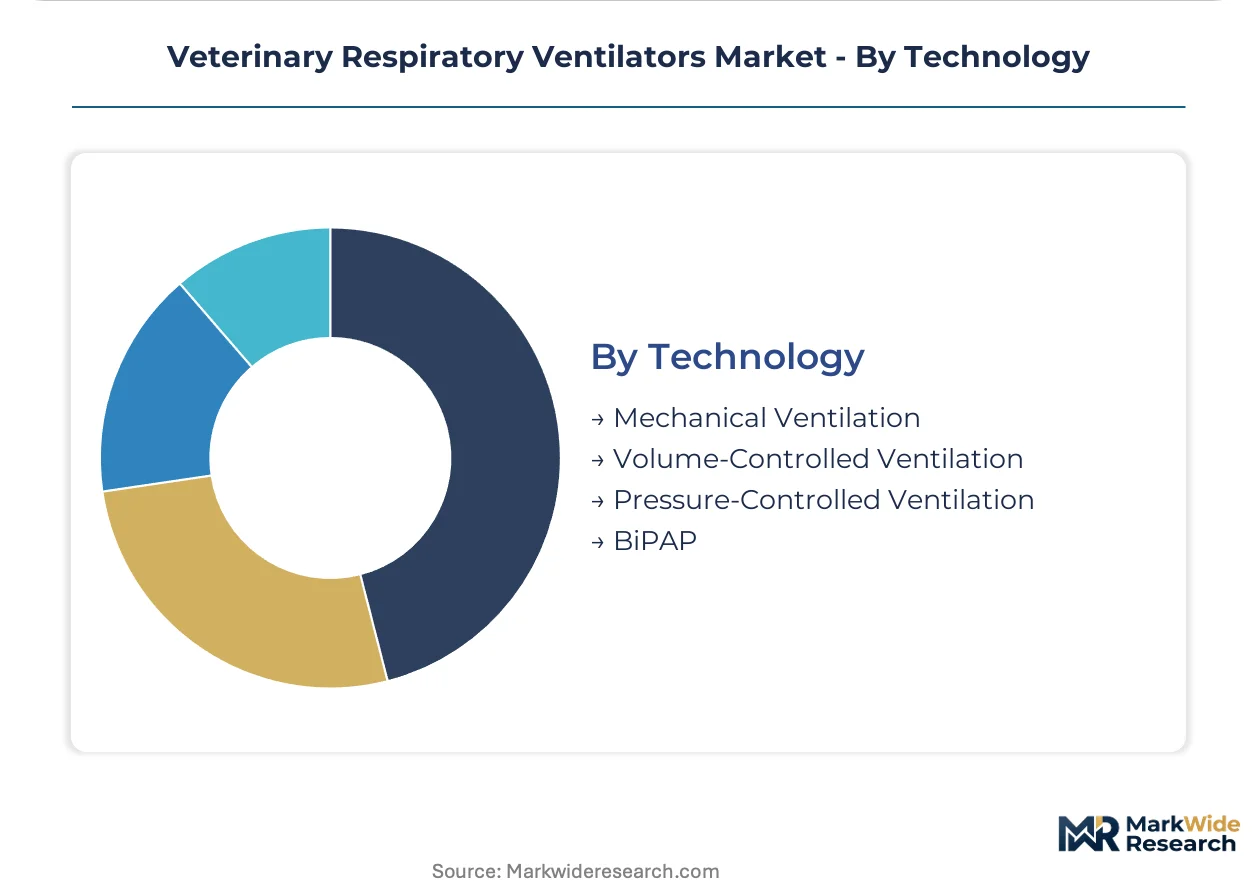
Volume-controlled ventilation occupies the largest installed base, though pressure-controlled modes are displacing legacy systems in specialized applications.
- Volume-Controlled Ventilation:Delivers preset tidal volumes regardless of airway pressure, dominating current installations across general veterinary practice. This technology faces displacement pressure in brachycephalic breed applications where rigid pressure limits reduce barotrauma risk.
- Pressure-Controlled Ventilation:Maintains preset airway pressure with variable tidal volume, gaining preference in flat-faced companion species and small exotic animals. Machine learning algorithms for automated parameter adjustment are consolidating control functions previously requiring manual clinician intervention in tertiary United States hospitals.
- Mechanical Ventilation:Traditional time-cycled or pressure-limited systems without microprocessor control.
- BiPAP:Bilevel positive airway pressure for non-invasive support of spontaneous breathing.
Volume-Controlled Ventilation maintains installed-base leadership; Pressure-Controlled Ventilation is climbing fastest as AI-driven breath-pattern recognition enables automated adjustment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty veterinary referral hospitals in the United States concentrate the highest installed base of invasive ventilation platforms, with procurement patterns rippling outward to research institutions and mobile service providers across developed economies.
United States
Tertiary veterinary hospitals in metropolitan corridors drive premium equipment upgrades as companion animal critical care standards intensify. FDA Center for Veterinary Medicine pre-market notification pathways extend clearance timelines for novel ventilator platforms integrating artificial intelligence. The Research Triangle in North Carolina anchors large-animal surgical study infrastructure, with USDA National Institute of Food and Agriculture funding steering procurement toward high-capacity systems.
Germany
ISO 80601-2-80 compliance requirements compress vendor development timelines while academic veterinary centers expand critical care capabilities. EMA-aligned regulatory frameworks for medical device software create parallel compliance obligations for manufacturers exporting to European research institutions. Munich and Berlin veterinary schools concentrate demand for pressure-controlled ventilation modes in brachycephalic breed applications.
Japan
PMDA oversight shapes import pathways for veterinary respiratory equipment, with METI industrial standards influencing domestic manufacturer specifications. Small exotic species veterinary practices in Tokyo and Osaka drive demand for tidal volume scaling below 50 mL. Domestic production of precision flow sensors reduces supply chain vulnerability for regional assemblers.
United Kingdom
Veterinary referral networks in London and the Southeast extend 24-hour critical care coverage, expanding ventilator procurement for emergency intervention. MHRA post-Brexit regulatory autonomy creates divergence from EU CE marking timelines for novel platform clearances. Vetronic Services Ltd. anchors aftermarket calibration protocols that extend installed-base longevity across British specialty hospitals.
Australia
TGA medical device regulations govern veterinary ventilator importation, with state veterinary schools in New South Wales and Victoria piloting pressure-controlled platforms for wildlife rehabilitation. Mobile veterinary units serving remote equine populations face capital intensity barriers that constrain portable ventilator penetration despite clinical utility in field emergency response.
Veterinary Respiratory Ventilators Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to secure component supply and extend service reach. The vendor base clusters around three tiers: European precision sensor specialists, North American distribution-anchored platforms, and Asian scale manufacturers. Archetypes include technology licensors, aftermarket service providers, and integrated platform developers. M&A activity and geographic expansion through regional manufacturing partnerships represent the primary competitive vectors reshaping market structure.
Among European-based specialists, MIDEN MEDICAL leverages manufacturing partnerships to sustain cost-competitive production of precision flow sensors. Midmark Corporation anchors North American distribution through dedicated veterinary equipment channels. Vetronic Services Ltd. occupies a position exemplifying the aftermarket service archetype, specializing in calibration protocols that extend installed-base longevity for technical service providers.
| Leading Market Players |
|---|
| MIDEN MEDICAL |
| Midmark Corporation |
| Vetronic Services Ltd. |
| Hallowell EMC |
| Metran Co., Ltd. |
| RWD Life Science Co., LTD |
| EICKEMEYER |
| VetEquip Inc. |
| MINERVE Veterinary Equipment |
| Others |
Value Network & Pricing Analysis
Specialty veterinary referral hospitals in the United States anchor procurement volumes and enforce a three-tier pricing structure across premium, standard, and economy levels. Their concentration of purchasing power compresses margins for mid-range assemblers while rewarding ISO 80601-2-80 certified platforms with pricing premiums.
Pricing Analysis
Input-cost pass-through from European precision flow sensor sourcing is compressing margins for North American assemblers. Pricing stratifies across premium, standard, and economy tiers, with FDA 510(k) clearance tier and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from silicone-based breathing circuit substitution reducing legacy PVC cost structures. General practice clinics exhibit highest price sensitivity; tertiary hospitals prioritize certification tier over unit cost.
Supply Chain Analysis
ISO 80601-2-80 and FDA Center for Veterinary Medicine qualification requirements gate component sourcing for platform developers. Precision flow sensor production concentrates in Germany and Japan; final assembly draws from China and the United States. Single-source vulnerability in European sensor partnerships creates logistics risk for North American ventilator manufacturers. Distribution runs through dedicated veterinary equipment channels anchored by specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary respiratory ventilators constitute a late-cycle quality market where companion animal critical care standards have shifted demand toward AI-integrated, pressure-controlled platforms. Premium specification requirements now dominate procurement at tertiary hospitals.
For Market Incumbents: Deepen backward integration into precision flow sensor production to reduce European partnership dependency. Anchor channel control through exclusive service agreements with specialty veterinary referral networks. Defend against portable ventilator entrants by embedding calibration protocols within hardware contracts. Certification investment in FDA software-as-medical-device pathways represents the critical defensive lever. For New Entrants and Emerging Players: Launch via direct technical service agreements targeting metropolitan United States markets with concentrated critical care infrastructure. Small exotic species ventilation below 50 mL tidal volume offers the most penetrable white space. Brachycephalic breed specialization in pressure-controlled modes provides segment-specific entry. Field emergency service economics constraints create partnership opportunities with equine emergency response teams rather than capital sales. For Investors and Strategic Acquirers: Veterinary equipment conglomerates are the most active acquirer in this space, consolidating aftermarket service providers and precision sensor specialists. Long-term viability hinges on software-enabled recurring revenue streams displacing transactional hardware sales. Target acquisition archetype: calibration protocol specialists with installed-base relationships. Watch FDA guidance finalization on AI-driven breath-pattern recognition as inflection indicator for platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Clearance pathways for AI-integrated platforms unlock premium pricing at tertiary hospitals. |
| Precision Flow Sensor Supply Agreement | European manufacturing partnerships reduce cost volatility for North American assemblers. |
| Aftermarket Calibration Service Expansion | Vetronic Services Ltd. demonstrates installed-base longevity protocols diversify revenue. |
| Small Exotic Species Platform Development | Tidal volume scaling below 50 mL addresses underserved avian and reptile critical care. |
| Brachycephalic Breed Specialization | Pressure-controlled modes gain preference where barotrauma risks constrain treatment options. |
Research Methodology
Bottom-up veterinary hospital procurement modeling reconciled against top-down precision sensor production tracking forms the analytical core of this study. Primary interviews with biomedical engineers, veterinary critical care specialists, GPO contracts managers, and aftermarket service technicians combined with secondary validation from FDA 510(k) filings, ISO 80601-2-80 certification databases, USDA NIFA funding disclosures, and veterinary equipment import records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of invasive and portable ventilator shipments established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, application, technology, and end-user facility tier. CAGRs were derived from curve-fitting against documented procurement cycles at specialty referral hospitals. Forecast inputs incorporate FDA pre-market notification timeline assumptions and silicone-based circuit adoption trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software classification delays or precision sensor supply disruptions. Model outputs reflect assumptions about companion animal critical care standard evolution and research facility funding continuity. A model refresh is warranted upon material change in FDA Center for Veterinary Medicine guidance on AI-driven ventilator platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Inversion Table Market
Medical Devices
Microdebrider Market
Medical Devices
Veterinary Catheters Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Retinal Implant Market
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Biomedical Warming and Thawing Devices Market