
 Cranial Clamps Market | 2026-2036
Cranial Clamps Market Size, Share, and Industry Trends Forecast 2026-2036
Cranial Clamps Market Analysis
Titanium is rebalancing cost-performance economics across cranial clamp portfolios as surgeons prioritize radiolucency and biocompatibility over legacy stainless steel. Stryker Corporation leverages its orthopedic instrumentation heritage to sustain dominance in adjustable clamp configurations. Integra LifeSciences Corporation anchors its position through specialized neurosurgical portfolios, while PRO-MED Instrumente GmbH competes on precision-engineered German manufacturing standards.
Cranial clamps are mechanical fixation devices that secure a patient's head during intracranial procedures, typically manufactured from titanium, stainless steel, or aluminum alloys with torque-limiting mechanisms to prevent skull perforation. Adjustable clamp designs command premium positioning due to their intraoperative flexibility across pediatric and adult cranial dimensions. Hospitals represent the dominant end-user channel, though surgical centers are capturing faster volume growth as outpatient neurosurgical volumes expand.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and commercial access across North American and European markets. The EU AI Act and updated F-Gas Regulation on medical device sterilization gases are forcing manufacturers to revalidate cleaning and packaging protocols. Stakeholders must monitor evolving reimbursement codes for stereotactic and trauma neurosurgery to anticipate which clamp configurations will secure favorable hospital procurement status.
Market Dynamics
EU MDR Class IIa sterilization mandates and FDA 510(k) pathway revisions are compressing product development timelines while elevating compliance costs for cranial clamp manufacturers serving tertiary neurosurgical centers.
Growth Catalysts
- Radiolucent Titanium Alloys:German surgical centers prioritize titanium configurations that eliminate MRI artifact interference during post-operative imaging protocols.
- Outpatient Neurosurgery Expansion:Ambulatory surgical centers in the United States are capturing cranial clamp volume as stereotactic biopsy procedures migrate from inpatient settings.
- EU AI Act:Automated sterilization validation systems are gaining deployment across European manufacturing facilities to preempt regulatory enforcement.
Market Restraints
- Titanium Price Volatility:Aerospace and defense sector demand for Grade 5 titanium sponge constrains medical-grade alloy availability and inflates raw material costs.
- Supply Concentration in Forging:Precision forging capacity for cranial clamp components clusters among specialized German and Japanese metallurgical suppliers.
- Legacy Stainless Steel Lock-In:Hospital procurement departments face sunk-cost pressure from existing stainless steel instrument inventories that resist fleet replacement.
Strategic Opportunities
- Pediatric Adjustable Configurations:Underserved pediatric neurosurgical segments in India present white space for torque-calibrated clamp systems scaled to infant cranial dimensions.
- Single-Use Sterile Packaging:Pre-sterilized disposable cranial clamp kits are penetrating Japanese surgical centers seeking to eliminate reprocessing liability.
- CE-MDR Certification Arbitrage:Early compliance investments position manufacturers to capture market share from competitors facing delayed EU market re-entry.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity evaluation queues at contracted laboratories extend product launch timelines by eight to fourteen months.
- Legacy EMR Integration:Adjustable clamp torque data logging requires API development with hospital information systems that lack standardized device connectivity protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranial Clamps Market |
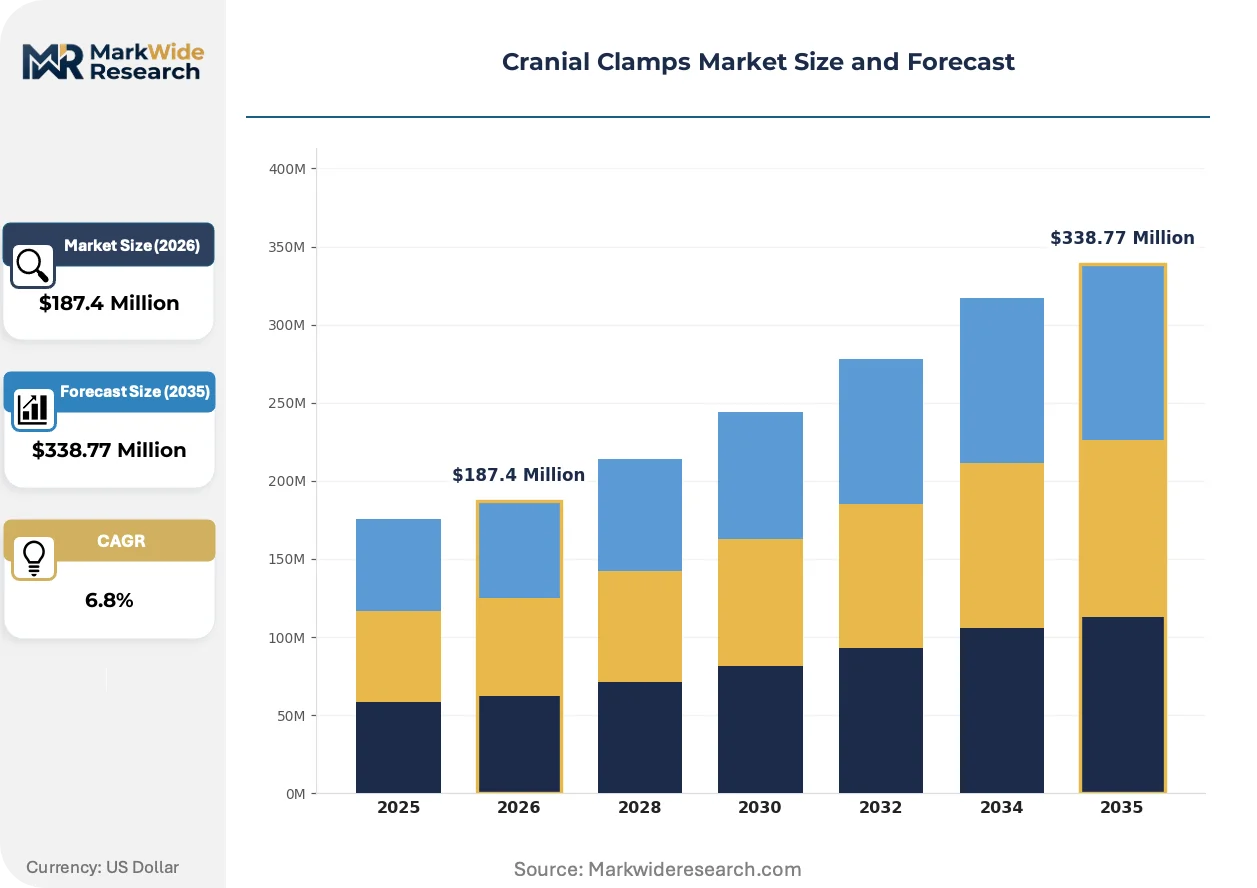
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Pin, Double Pin, Fixed Clamp, Adjustable Clamp End User: Hospitals, Surgical Centers, Research Institutions, Rehabilitation Facilities Material: Stainless Steel, Aluminum, Plastic, Titanium Application: Neurosurgery, Trauma Surgery, Pediatric Surgery, Stereotactic Surgery |
| Companies Covered | Integra LifeSciences Corporation, PRO-MED Instrumente GmbH, Stryker Corporation, Medtronic plc, B. Braun Melsungen AG, Zimmer Biomet Holdings, Inc., STERIS plc, Hillrom, Mizuho Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranial Clamps Market Emerging Trajectories
Digital torque sensing and automated sterilization tracking are displacing manual calibration methods across cranial clamp portfolios. These innovations compress surgical setup time while generating compliance documentation that satisfies tightening regulatory audit requirements.
Additive manufacturing of titanium lattice structures is electrifying cranial clamp design by enabling patient-specific anatomical conformance. Tertiary hospitals in Switzerland and the United States are piloting these configurations for complex cranial trauma cases. This technology is electrifying competitive differentiation as manufacturers compete on geometric complexity rather than material grades alone.
The EU F-Gas Regulation on medical device sterilization gases is forcing revalidation of ethylene oxide cleaning protocols across European manufacturing facilities. German producers are accelerating plasma sterilization alternative investments to preempt 2026 phase-down deadlines. Pediatric clamp configurations face the steepest compliance cost escalation due to smaller batch sizes and higher per-unit validation burden.
Hospital procurement departments are consolidating cranial clamp purchasing into multi-year enterprise agreements that bundle fixation devices with stereotactic navigation systems. This bundling displaces standalone instrument vendors in favor of integrated platform suppliers. The United States exhibits the most pronounced concentration as health system mergers reduce independent purchasing authority at individual facilities.
Cranial Clamps Market Segmentation
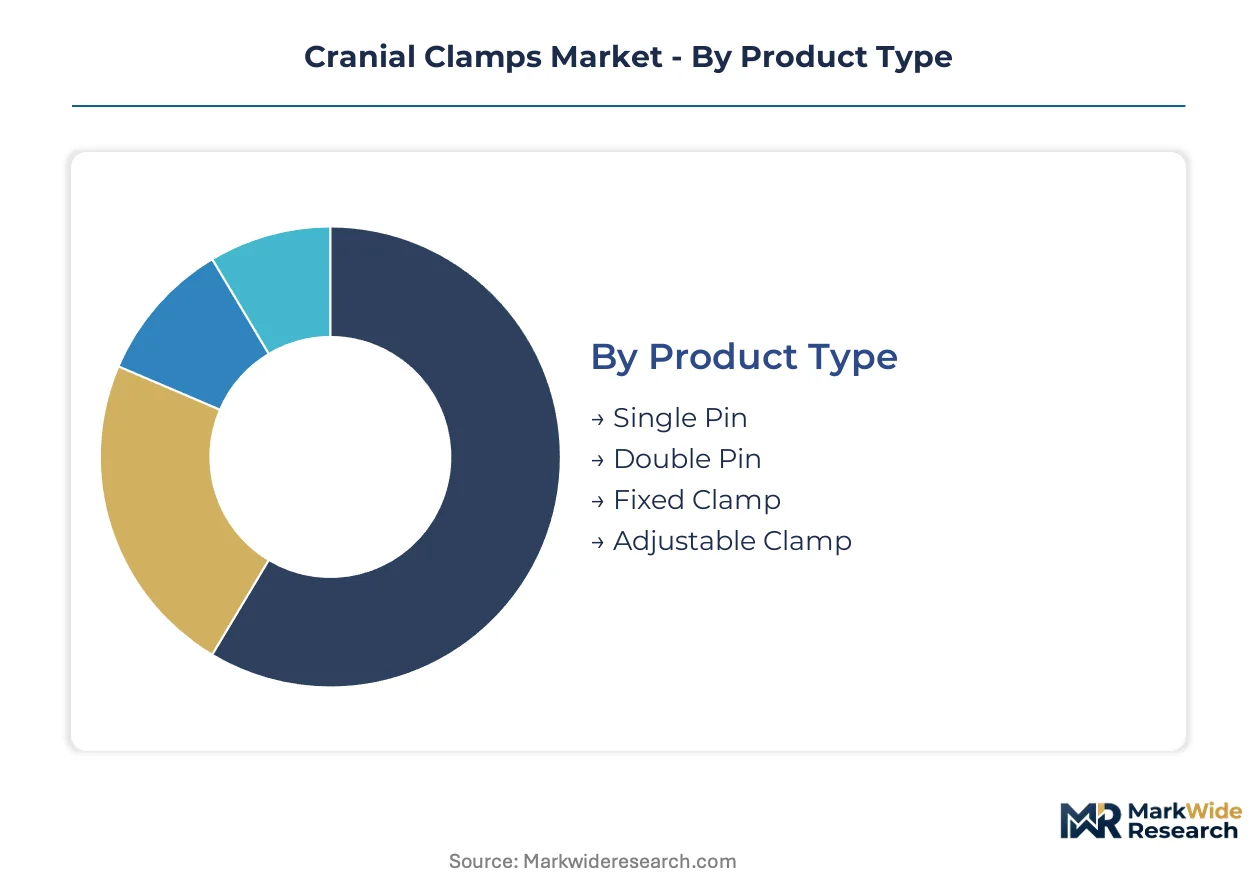
Cranial clamp segmentation reveals how procurement decisions bifurcate between high-volume standardized configurations and premium adjustable systems. Understanding these divides exposes where margin compression concentrates versus where technology premiums sustain.
Product Type:
Precision forging capacity clusters among German and Japanese metallurgical suppliers, concentrating supply-side leverage for complex multi-pin configurations.
- Adjustable Clamp:Torque-limiting mechanisms accommodate pediatric through adult cranial dimensions intraoperatively. Tertiary hospitals in Germany and the United States prioritize these configurations for mixed patient populations despite titanium alloy cost premiums.
- Double Pin:Dual-point fixation distributes mechanical load across the skull, reducing focal pressure risks during extended procedures. Demand concentrates in Swiss and Japanese neurosurgical centers performing complex cranial trauma reconstructions where stability tolerance is narrow.
- Single Pin:Simplified mechanical design for rapid deployment in emergency trauma settings.
- Fixed Clamp:Non-adjustable geometry suited to high-volume standardized procedures with predictable anatomical parameters.
Today's leader: Adjustable Clamp. Tomorrow's challenger: Double Pin.
End User:
Procurement authority is consolidating into multi-year enterprise agreements that bundle fixation devices with navigation systems, reshaping channel economics.
- Hospitals:Tertiary neurosurgical departments command the dominant volume share, driven by inpatient cranial trauma and tumor resection caseloads. FDA 510(k) clearance pathways and EU MDR Class IIa mandates elevate compliance costs that disadvantage smaller surgical centers.
- Surgical Centers:Ambulatory facilities in the United States are capturing volume as stereotactic biopsy procedures migrate from inpatient settings. These centers prioritize single-use sterile packaging to eliminate reprocessing liability.
- Research Institutions:Academic medical centers in Switzerland and the United States pilot additive-manufactured patient-specific configurations.
- Rehabilitation Facilities:Post-operative cranial stabilization requirements in specialized recovery units.
Volume concentrates in Hospitals. Expansion accelerates fastest in Surgical Centers.
Material:
Raw material availability constraints from aerospace and defense sector competition for Grade 5 titanium sponge are rebalancing cost-performance calculations across portfolios.
- Titanium:Grade 5 titanium alloys deliver radiolucency eliminating MRI artifact interference during post-operative imaging. German surgical centers and Japanese facilities prioritize these configurations despite raw material cost volatility from competing industrial demand.
- Stainless Steel:Legacy instrument fleets in hospital procurement departments create sunk-cost resistance to fleet replacement. These configurations retain volume in cost-constrained health systems where radiolucency is non-critical.
- Aluminum:Lightweight alternative for pediatric applications where cranial load minimization is prioritized.
- Plastic:Disposable configurations penetrating Japanese surgical centers seeking sterilization protocol simplification.
Technology leadership resides in Titanium. Cost-driven substitution favors Stainless Steel.
Application:
Reimbursement code evolution for stereotactic and trauma neurosurgery is determining which clamp configurations secure favorable hospital procurement status.
- Neurosurgery:Tumor resection and vascular procedures demand the highest mechanical stability specifications. Tertiary hospitals in the United States and Germany anchor demand for premium adjustable titanium configurations in this segment.
- Stereotactic Surgery:Frame-based and frameless navigation systems require precise cranial reference geometry. Outpatient migration in the United States is expanding surgical center volume for biopsy procedures.
- Trauma Surgery:Emergency stabilization requirements prioritize rapid deployment and universal anatomical fit.
- Pediatric Surgery:Underserved segments in India present white space for torque-calibrated systems scaled to infant cranial dimensions.
Revenue concentration sits with Neurosurgery. Volume expansion is climbing fastest in Stereotactic Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision forging clusters in Solingen and Tuttlingen anchor cranial clamp manufacturing capacity, with tertiary hospitals across industrialized economies driving demand for radiolucent titanium configurations amid tightening sterilization mandates.
United States
Tertiary neurosurgical departments at academic medical centers in Boston, Baltimore, and Houston anchor demand for adjustable titanium clamp systems. FDA 510(k) clearance pathways compress product development timelines while elevating compliance documentation burdens for manufacturers. Ambulatory surgical centers in Florida and Texas are capturing volume as stereotactic biopsy procedures migrate from inpatient settings.
Germany
Surgical centers in Munich, Heidelberg, and Berlin prioritize Grade 5 titanium configurations that eliminate MRI artifact interference during post-operative imaging protocols. EU MDR Class IIa certification requirements and the F-Gas Regulation on sterilization gases are forcing revalidation of ethylene oxide cleaning protocols. Precision forging capacity clusters in Solingen and Tuttlingen concentrate supply-side leverage for complex multi-pin configurations.
Japan
PMDA regulatory frameworks and JIS standards govern market access for cranial clamp manufacturers serving Tokyo, Osaka, and Nagoya metropolitan hospital networks. Japanese surgical centers are piloting single-use sterile packaging configurations to eliminate reprocessing liability. METI industrial policy supports domestic titanium alloy processing capabilities against aerospace sector competition for medical-grade sponge.
Switzerland
Academic medical centers in Zurich, Geneva, and Basel pilot additive-manufactured patient-specific cranial clamp configurations for complex trauma reconstructions. Swissmedic certification requirements align with EU MDR standards while permitting accelerated evaluation pathways for innovative geometries. Swiss orthopedic device clusters leverage precision machining heritage to advance lattice-structure fabrication capabilities.
India
Underserved pediatric neurosurgical segments in Maharashtra, Karnataka, and Tamil Nadu present white space for torque-calibrated clamp systems scaled to infant cranial dimensions. CDSCO regulatory frameworks are converging toward international standards for Class IIa medical devices. Hospital procurement in Delhi-NCR and Mumbai demonstrates cost-constrained preference for stainless steel configurations despite titanium performance advantages.
Cranial Clamps Market Vendor Landscape
Global majors compete with regional champions across regulatory certification and precision manufacturing capabilities. The cranial clamp market exhibits tiered consolidation with orthopedic conglomerates, specialized neurosurgical instrument firms, and precision German metalworkers occupying distinct competitive positions. Three strategic archetypes dominate: diversified orthopedic platforms leveraging cross-portfolio synergies, neurosurgical pure-plays commanding specialized clinical relationships, and metallurgical specialists competing on forging precision. M&A activity targets sterilization-compliant manufacturing assets, while portfolio diversification into navigation-compatible configurations accelerates.
Within the diversified orthopedic tier, Stryker Corporation and Zimmer Biomet Holdings, Inc. occupy positions defined by cross-selling leverage across fixation device portfolios. Among neurosurgical specialists, Integra LifeSciences Corporation exemplifies pure-play positioning through dedicated cranial access portfolios. PRO-MED Instrumente GmbH represents the precision-forging archetype, anchoring German manufacturing standards for torque-limiting mechanisms. These three firms illustrate how competitive differentiation flows from distinct capability foundations rather than undifferentiated scale.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| PRO-MED Instrumente GmbH |
| Stryker Corporation |
| Medtronic plc |
| B. Braun Melsungen AG |
| Zimmer Biomet Holdings, Inc. |
| STERIS plc |
| Hillrom |
| Mizuho Medical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Grade 5 titanium sponge scarcity bifurcates cranial clamp portfolios into radiolucent premium configurations and legacy stainless steel alternatives, with aerospace and defense sector competition for metallurgical feedstock compressing margins on high-performance tiers while hospital procurement departments amortize sunk-cost instrument fleets across standard offerings. This material divergence concentrates pricing power among German and Japanese forging specialists who command torque-limiting mechanism production, while sterilization compliance costs escalate per-unit validation burdens disproportionately for pediatric batch sizes.
Pricing Analysis
Input-cost pass-through from Grade 5 titanium sponge volatility anchors premium tier positioning, with aerospace sector demand inflating medical-grade alloy procurement expenses that manufacturers partially recover through adjustable clamp configurations. Price differentiation separates radiolucent titanium systems validated for MRI compatibility from stainless steel alternatives retained in cost-constrained health systems. Pricing pressure stems from hospital procurement consolidation into multi-year enterprise agreements bundling fixation devices with navigation platforms. Surgical centers exhibit highest price sensitivity due to outpatient margin compression, while academic medical centers absorb premium positioning for intraoperative flexibility.
Supply Chain Analysis
Dual-sourcing requirements for torque-limiting components mandate multi-supplier qualification across German and Japanese precision forging facilities, with tertiary hospitals insisting on redundant metallurgical validation to mitigate single-source disruption risks. Raw material dependencies center on Grade 5 titanium sponge, surgical-grade stainless steel, and aluminum alloys for pediatric applications. Supply chain risk concentrates in single-source vulnerability for complex multi-pin forging capacity clustered in Solingen and Tuttlingen. Distribution runs through hospital procurement committees and GPO contracts in the United States, direct sales to neurosurgical departments in Germany, and specialized instrument distributors serving Japanese surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cranial clamps function as a stable compounder anchored by irreversible neurosurgical procedure volumes and regulatory barriers that sustain incumbent positioning across sterilization-mandated replacement cycles.
For Market Incumbents: Deploy CE-MDR certification arbitrage to capture share from competitors facing delayed EU market re-entry, while accelerating plasma sterilization alternative investments to preempt F-Gas Regulation phase-down deadlines. Consolidate adjustable clamp portfolios with stereotactic navigation platforms to defend against standalone instrument vendor displacement. Fortify precision forging relationships in Solingen and Tuttlingen against aerospace sector titanium sponge competition. For New Entrants and Emerging Players: Specialized pediatric distributors in Maharashtra and Tamil Nadu offer the most penetrable channel for torque-calibrated infant cranial systems, with CDSCO regulatory convergence lowering entry barriers against legacy stainless steel incumbents. Target single-use sterile packaging configurations for Japanese surgical centers seeking reprocessing liability elimination. Pursue hospital system partnership models bundling disposable kits with outpatient stereotactic biopsy migration. For Investors and Strategic Acquirers: Consolidation pressure builds where sterilization-compliant manufacturing assets face valuation discounts against EU MDR enforcement timelines. Long-term viability frames around 5-10 year regulatory compliance moats rather than undifferentiated scale. Target precision-forging specialists with torque-limiting mechanism IP and validated ethylene oxide alternative protocols. Watch FDA 510(k) clearance velocity and EU MDR notified body capacity as inflection indicators for competitive re-entry dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Certification Pathway | Early compliance investments capture share from delayed competitors across German and French hospital networks. |
| Plasma Sterilization Transition | F-Gas Regulation phase-down mandates revalidation of ethylene oxide protocols for European manufacturing facilities. |
| Hospital System Partnership | Enterprise agreements bundling fixation devices with navigation platforms displace standalone instrument vendors. |
| Pediatric Configuration Development | Torque-calibrated systems for infant cranial dimensions address underserved demand in Indian neurosurgical centers. |
| Single-Use Sterile Packaging | Pre-sterilized disposable kits eliminate reprocessing liability for Japanese ambulatory surgical centers. |
Methodological Framework
Multiple input streams — primary interviews with neurosurgical department heads, biomedical engineers, and hospital procurement managers; secondary validation through FDA 510(k) filings, EU MDR notified body databases, and hospital GPO contract records; and trade data on titanium sponge and surgical instrument imports — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Data-stream reconciliation across product type, material grade, end-user channel, and application dimensions fed analytical frameworks spanning the projection horizon, with CAGRs derived from procedure volume elasticity to neurosurgical caseload expansion and replacement cycle dynamics tied to sterilization mandate compliance. Forecast inputs incorporated EU AI Act automated validation deployment timelines and FDA pathway revision impacts on commercial access velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aerospace sector titanium sponge demand shocks and notified body capacity constraints for EU MDR conformity assessments. Deviation in hospital merger consolidation velocity or outpatient stereotactic migration pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Microcatheter Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Spinal Needles Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
United Kingdom General Surgical Devices Market