
 Germany Hospital Supplies Market | 2026-2036
Germany Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Hospital Supplies Market Foresight
Silicone is replacing natural rubber latex in catheter and tubing formulations, which is realigning cost structures across Germany's hospital supply chain. B. Braun SE leverages its vertically integrated silicone processing capabilities to sustain margin advantages in urology and anesthesia sets. Medtronic competes through concentrated R&D spending on polymer science for cardiac procedure kits. Cardinal Health anchors its German position through direct-to-hospital distribution networks that bypass traditional wholesale layers.
Hospital supplies encompass sterile and non-sterile goods used in patient diagnosis, treatment, and institutional care, including single-use polymers, stainless steel instruments, and electronic monitoring peripherals rated for IEC 60601 electrical safety standards. Medical consumables generate recurring revenue streams through predictable replacement cycles, while diagnostic equipment commands higher upfront capital outlays with extended amortization periods. Surgical instruments occupy a mature segment where German manufacturers compete on precision engineering heritage, whereas patient care supplies see faster growth from aging-population-driven demand for pressure-relief surfaces and mobility aids.
The Federal Institute for Drugs and Medical Devices (BfArM) enforces Medical Device Regulation compliance certificates, while the Robert Koch Institute mandates infection-control protocol adherence that shapes product specifications for sterilization wraps and antimicrobial coatings. Germany's Social Code Book V reimbursement frameworks, administered by the Federal Joint Committee (G-BA), directly influence hospital procurement budgets and supplier qualification criteria. Stakeholders must monitor how BfArM's pending guidance on sustainable medical device disposal reshapes material selection decisions and supplier environmental certification requirements.
Market Dynamics
Medical Device Regulation (MDR) compliance under BfArM oversight is compressing supplier qualification timelines while Bavaria's hospital cluster accelerates single-use surgical consumables procurement, forcing distributors to reconfigure inventory depth and sterilization documentation workflows.
Growth Catalysts
- Ambulatory surgery expansion:Outpatient procedure volume in Bavaria and Baden-Württemberg is pulling catheter, dressing, and anesthesia kit demand away from traditional inpatient settings.
- REACH-compliant polymer substitution:Silicone formulations replacing natural rubber latex in tubing and drainage systems are opening procurement pathways for EU-manufactured alternatives.
- BfArM sterile supply mandates:Stricter infection-control protocol adherence is mandating antimicrobial-coated wound care and sterilization wrap upgrades across university hospitals.
Market Restraints
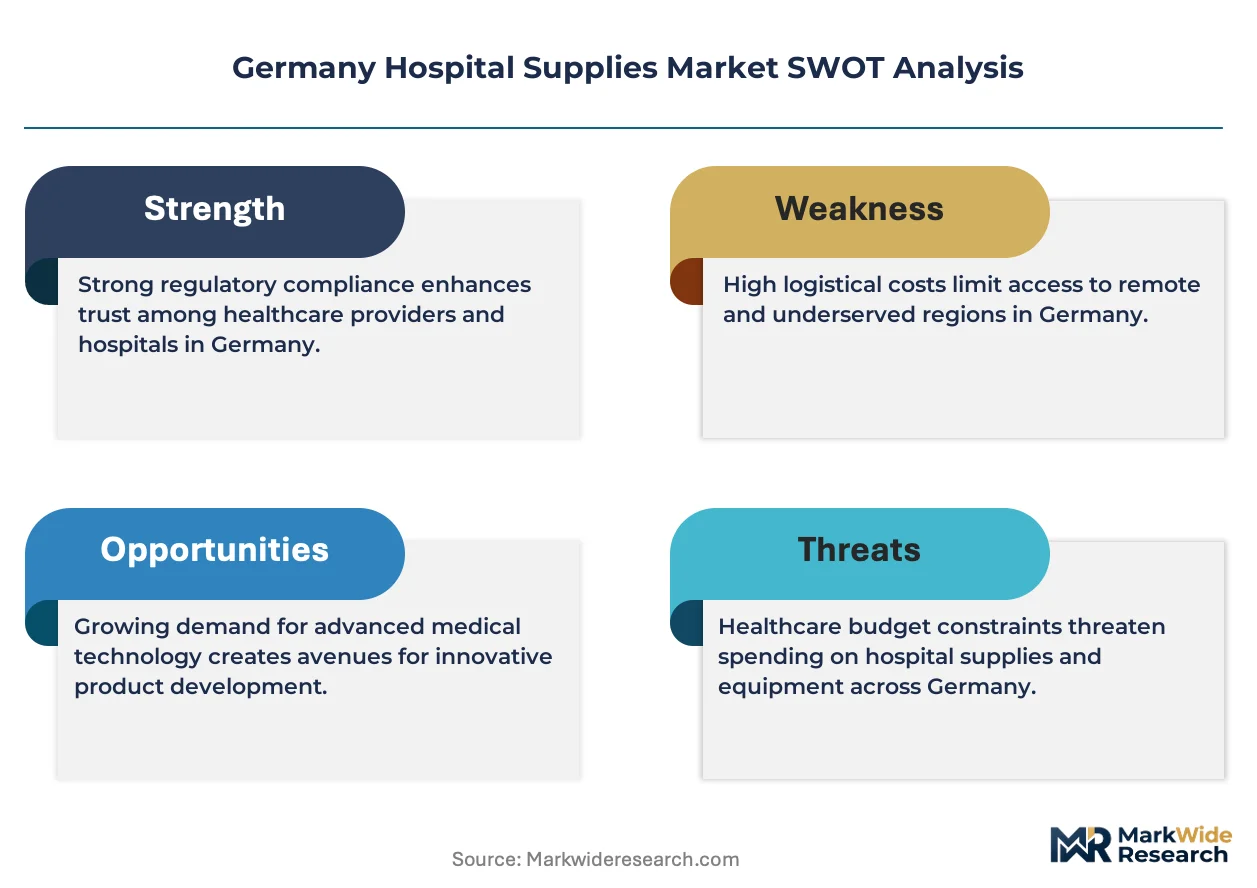
- Silicone feedstock volatility:Petrochemical-derived silicone precursor costs fluctuate with natural gas pricing, squeezing margin structures for catheter and tubing manufacturers.
- Single-source sterilization services:Gamma and ethylene oxide sterilization capacity concentrates in Rhineland-Palatinate and Saxony, creating geographic supply vulnerability for northern hospital networks.
- MDR certificate backlog:BfArM's notified body capacity constraints extend product registration timelines by 12-18 months for Class IIa and IIb devices.
Strategic Opportunities
- Reusable surgical instrument refurbishment:Stainless steel forceps and retractor reconditioning services address G-BA cost-containment pressure on procurement budgets in North Rhine-Westphalia.
- Digital inventory management integration:RFID-tracked consignment stock models reduce hospital working capital tied to suture and staple inventories.
- Bio-based polymer development:PLA and PHA alternatives to petroleum-derived plastics align with pending BfArM guidance on sustainable medical device disposal pathways.
Industry Challenges
- Sterilization validation expertise shortage:Ethylene oxide residue testing and bioburden assay specialists are scarce in eastern German manufacturing zones, slowing product release cycles.
- Legacy ERP integration friction:Hospital procurement systems in Saarland and Thuringia require manual data entry for MDR-compliant unique device identification tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Hospital Supplies Market |
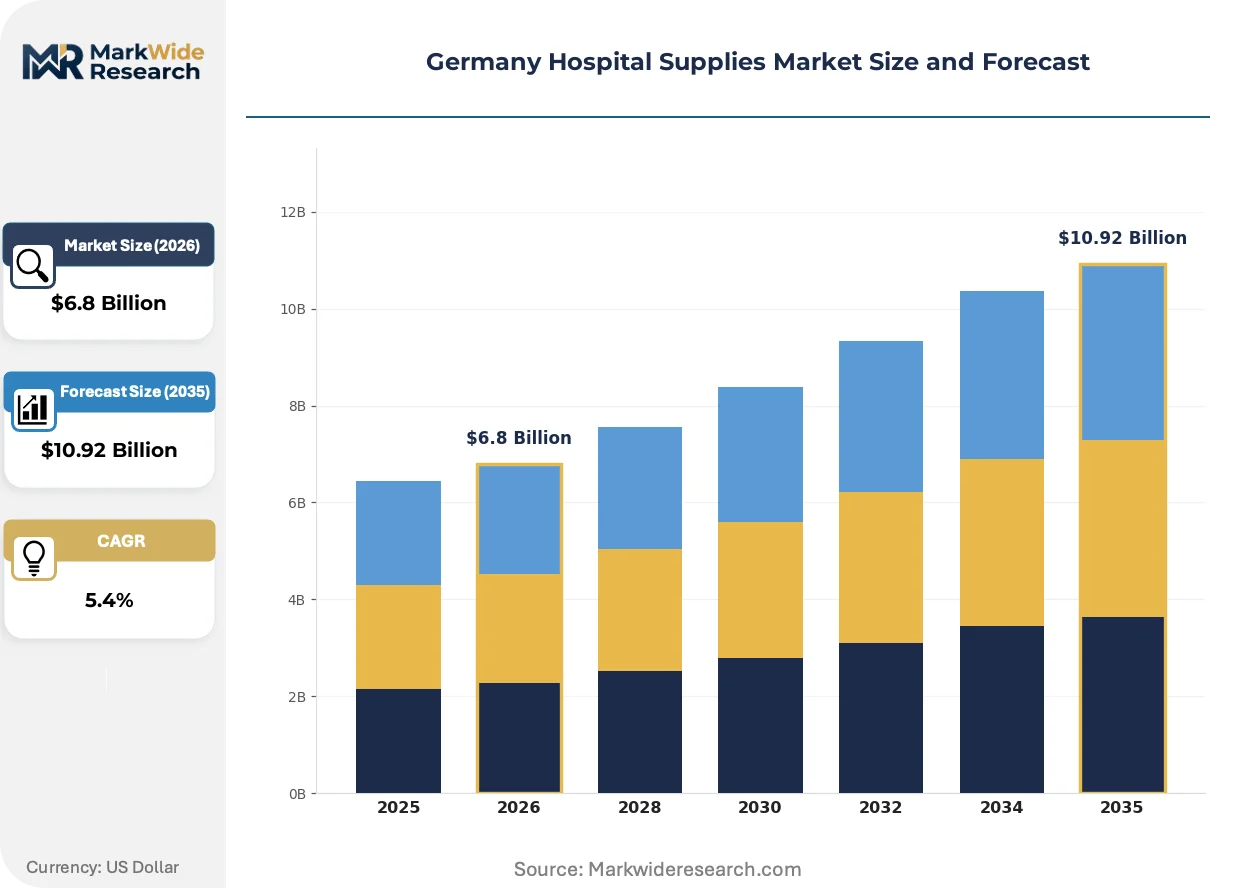
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Consumables, Surgical Instruments, Diagnostic Equipment, Patient Care Supplies, Laboratory Equipment Application: Surgical Procedures, Diagnostic Testing, Patient Monitoring, Emergency Care, Infection Control End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Nursing Facilities, Rehabilitation Centers Distribution Channel: Direct Sales, Medical Distributors, Online Platforms, Wholesalers, Group Purchasing Organizations |
| Companies Covered | B. Braun SE, Medtronic, Cardinal Health, Boston Scientific, 3M, Stryker, GE Healthcare, Becton Dickinson and Company, Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Hospital Supplies Market Shifts & Advancements
Electrification of point-of-care monitoring peripherals is collapsing the boundary between diagnostic equipment and consumables, while regulatory pressure on material safety is accelerating polymer science investment across German manufacturing bases.
Smart sensor-embedded wound dressings is electrifying post-operative monitoring by transmitting moisture and temperature data to nursing stations. University hospitals in Berlin and Hamburg are piloting these systems for diabetic foot ulcer protocols. The technology is electrifying competitive positioning by merging disposable supply recurring revenue with remote patient monitoring service contracts.
BfArM's pending guidance on sustainable medical device disposal is mandating lifecycle assessment documentation for single-use polymers. Manufacturers must now submit environmental footprint data alongside clinical safety dossiers. Sterilization wrap and suction canister segments face the steepest reformulation requirements as biodegradable alternatives displace conventional PP and PVC.
Direct-to-hospital distribution bypasses traditional wholesale layers for high-velocity consumables like sutures, gloves, and syringes. Cardinal Health and regional cooperatives in Lower Saxony are building captive last-mile networks. This channel compression is most visible in Bavaria's Munich-Nuremberg corridor where hospital group purchasing organizations consolidate supplier panels.
Germany Hospital Supplies Market Segmentation
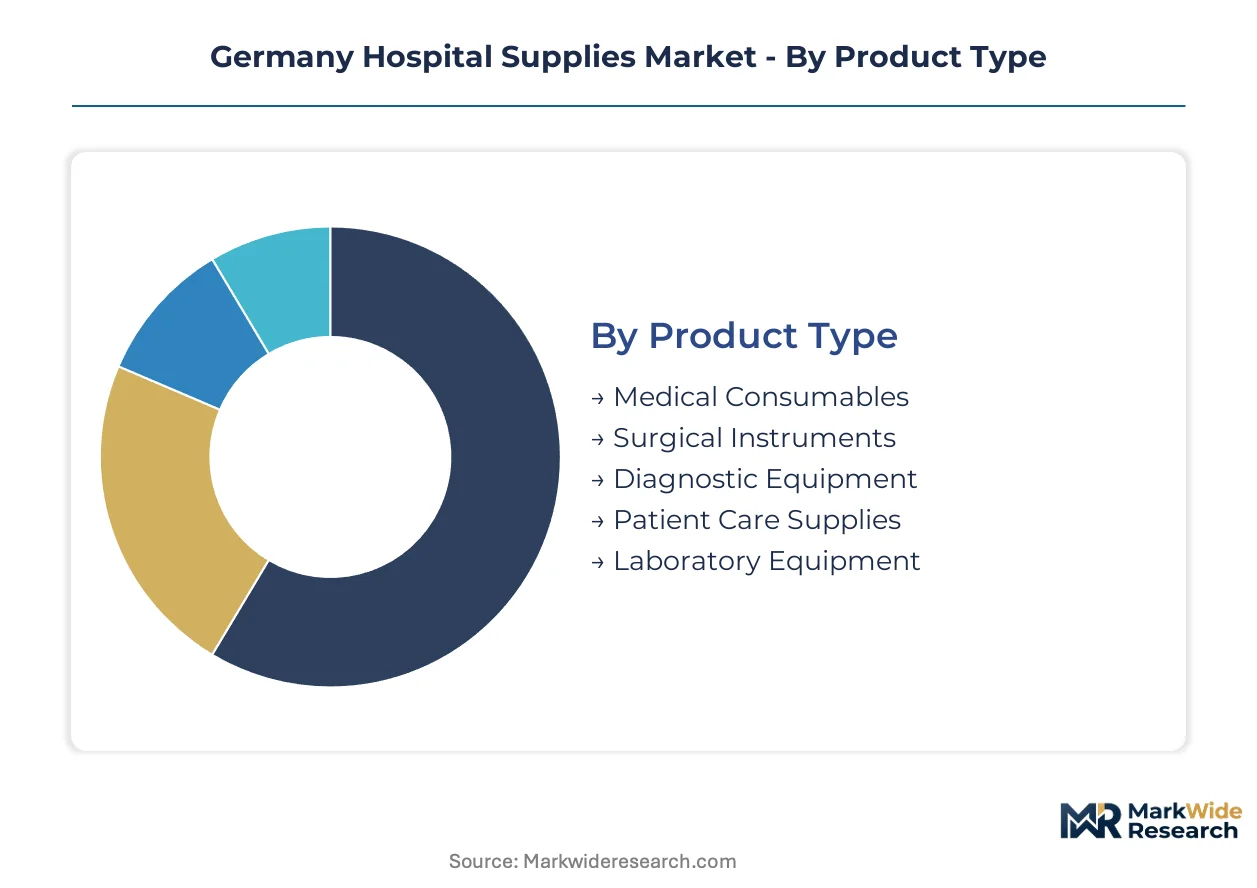
Hospital supplies segmentation in Germany reflects procurement complexity driven by BfArM compliance tiers and regional hospital cluster concentration. Each category demands distinct commercial strategies based on sterilization documentation requirements and reimbursement pathway alignment under G-BA frameworks.
Product Type:
Customization intensity varies from commoditized polymers to precision-engineered stainless steel, reshaping supplier margin structures across Bavaria and North Rhine-Westphalia.
- Medical Consumables:Single-use polymers including catheters, syringes, and wound dressings manufactured to ISO 13485 quality systems. Demand concentrates in Munich-Nuremberg hospital clusters where ambulatory surgery expansion accelerates catheter kit procurement cycles.
- Surgical Instruments:Stainless steel forceps, retractors, and scalpels requiring reconditioning services to meet G-BA cost-containment mandates. Tuttlingen's manufacturing heritage anchors German precision engineering competitiveness in this mature segment.
- Diagnostic Equipment:IEC 60601-rated monitoring peripherals with extended amortization periods.
- Patient Care Supplies:Pressure-relief surfaces and mobility aids responding to aging-population demand in Baden-Württemberg.
- Laboratory Equipment:Analyzers and centrifuges subject to IVDR compliance under BfArM oversight.
Leading the category by volume: Medical Consumables. Growing fastest: Patient Care Supplies.
Application:
Procedure site migration from inpatient to ambulatory settings is reconfiguring demand patterns across each application area.
- Surgical Procedures:Operating room consumables spanning anesthesia kits to sterile drapes. Bavaria's outpatient surgery volume surge pulls procurement toward single-use preference over reusable alternatives.
- Diagnostic Testing:Point-of-care consumables and laboratory reagents. Berlin-Brandenburg university hospitals drive molecular diagnostics demand through integrated care pathway investments.
- Patient Monitoring:Continuous vital sign acquisition devices and disposable sensors.
- Emergency Care:Trauma kits and resuscitation supplies for emergency department throughput.
- Infection Control:Sterilization wraps and antimicrobial coatings mandated by Robert Koch Institute protocols.
Volume leadership sits with Surgical Procedures. Steepest expansion trajectory: Infection Control.
End User:
Procurement sophistication tiers separate capital-rich university hospitals from budget-constrained nursing facilities.
- Hospitals:Maximum Care and General Care institutions with centralized procurement departments. North Rhine-Westphalia's hospital networks consolidate supplier panels through multi-year framework agreements.
- Ambulatory Care Centers:Outpatient surgery and dialysis facilities with high-velocity consumables turnover. Baden-Württemberg's center density drives same-day procedure kit demand.
- Diagnostic Laboratories:Independent and hospital-affiliated testing facilities.
- Nursing Facilities:Long-term care institutions with basic wound care and hygiene product requirements.
- Rehabilitation Centers:Post-acute facilities prioritizing mobility aids and patient safety equipment.
Hospitals dominate procurement value. Ambulatory Care Centers are climbing the fastest.
Distribution Channel:
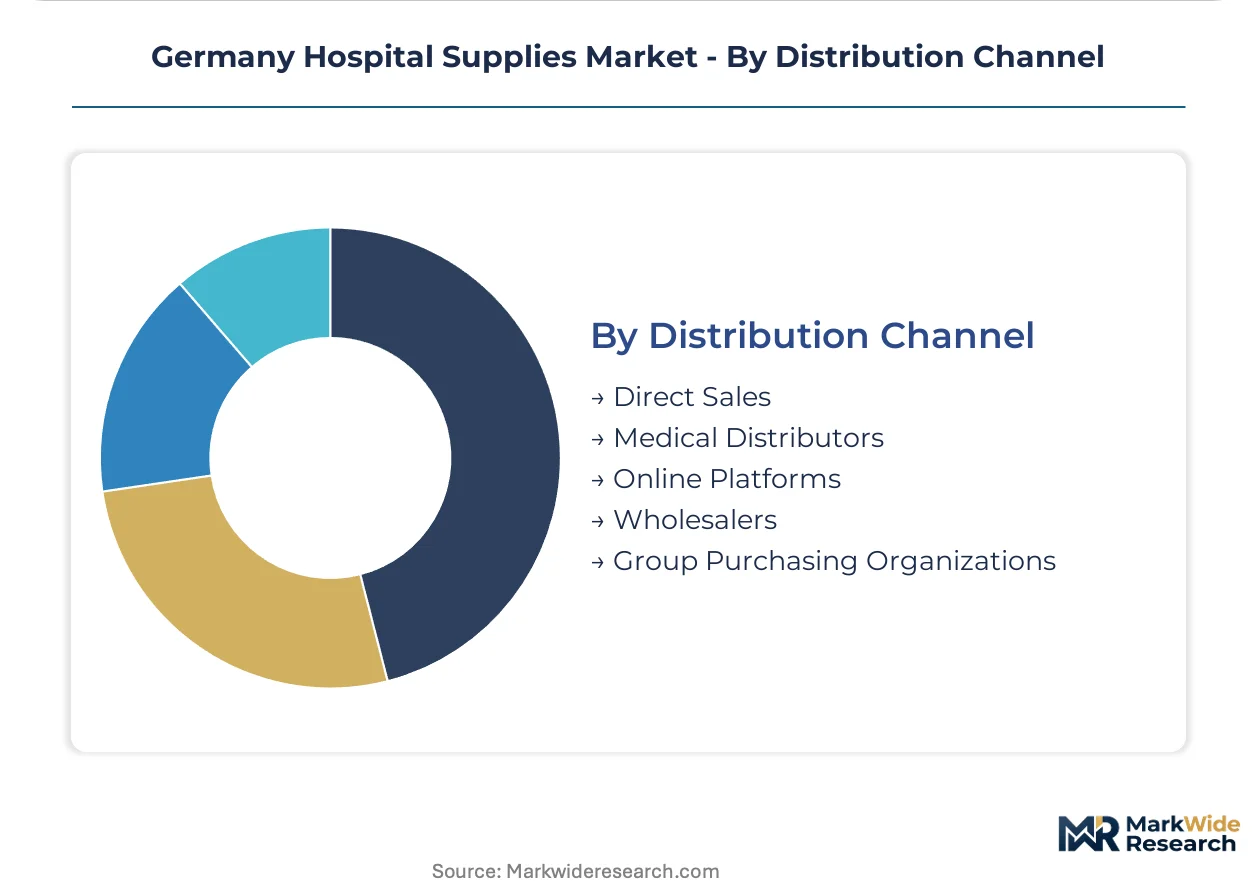
Channel compression is eliminating intermediary layers for high-velocity consumables while complex equipment retains specialist distribution.
- Direct Sales:Manufacturer-to-hospital relationships for high-volume consumables. Cardinal Health's captive last-mile networks bypass traditional wholesale in Lower Saxony.
- Medical Distributors:Regional specialists with sterilization documentation expertise. Rhineland-Palatinate distributors concentrate gamma sterilization logistics capabilities.
- Online Platforms:E-procurement portals for standardized consumables.
- Wholesalers:Traditional layered distribution for low-velocity specialty items.
- Group Purchasing Organizations:Hospital consortiums leveraging collective bargaining power in Bavaria's Munich-Nuremberg corridor.
Direct Sales captures the largest volume share. Group Purchasing Organizations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital supply procurement concentrates in Bavaria's Munich-Nuremberg corridor, where university hospitals and ambulatory surgery centers drive catheter kit and anesthesia consumables demand. BfArM's Medical Device Regulation enforcement tightens supplier qualification timelines across all German states. Regional clusters exhibit distinct procurement sophistication tiers.
Bavaria
Ambulatory surgery volume expansion pulls single-use consumables demand toward outpatient settings. BfArM compliance certificates concentrate here due to university hospital density. Munich-Nuremberg hospital purchasing organizations consolidate supplier panels through multi-year framework agreements.
North Rhine-Westphalia
Maximum Care institutions anchor procurement value with centralized supply chain departments. G-BA cost-containment mandates drive reusable surgical instrument refurbishment services. Cologne-Düsseldorf hospital networks bypass traditional wholesale through direct manufacturer relationships.
Baden-Württemberg
Aging-population demand accelerates patient care supplies procurement for pressure-relief surfaces and mobility aids. Robert Koch Institute infection-control protocols shape sterilization wrap specifications. Stuttgart-Karlsruhe ambulatory care center density supports same-day procedure kit turnover.
Lower Saxony
Direct-to-hospital distribution networks eliminate intermediary layers for high-velocity consumables. Regional cooperatives build captive last-mile logistics capabilities. Hanover-Braunschweig hospital clusters adopt RFID-tracked consignment stock models.
Berlin-Brandenburg
Integrated care pathway investments drive molecular diagnostics and point-of-care consumables demand. BfArM's pending sustainable disposal guidance shapes material selection decisions. Berlin university hospitals pilot smart sensor-embedded wound dressing systems for diabetic foot protocols.
Germany Hospital Supplies Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers build sterilization documentation capabilities and captive silicone processing facilities. The vendor base stratifies across three tiers: diversified multinationals with full portfolio coverage, mid-scale specialists concentrating on polymer science or precision instruments, and regional distributors with logistics integration. Two strategic archetypes define competitive positioning: vertically integrated manufacturers controlling raw material through finished goods, and platform distributors consolidating hospital purchasing organization relationships. M&A activity and geographic expansion into eastern German manufacturing zones represent the dominant competitive moves.
Among diversified healthcare conglomerates, B. Braun SE and Medtronic occupy positions exemplifying vertical integration archetypes, with the former representing German precision engineering heritage and the latter anchoring polymer science investment for procedure kits. Cardinal Health sits within the distribution-platform tier, illustrating direct-to-hospital channel compression strategies that bypass traditional wholesale layers in northern hospital networks.
| Leading Market Players |
|---|
| B. Braun SE |
| Medtronic |
| Cardinal Health |
| Boston Scientific |
| 3M |
| Stryker |
| GE Healthcare |
| Becton Dickinson and Company |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
BfArM's pending sustainable medical device disposal guidance gates both qualified supply and premium-tier pricing access, forcing manufacturers to submit lifecycle assessment documentation alongside clinical safety dossiers while hospital procurement committees restrict vendor panels to environmentally certified suppliers.
Pricing Analysis
Volume leadership in medical consumables generates thin margins, while diagnostic equipment and patient care supplies retain pricing power. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified sterile supplies from basic non-sterile alternatives, with silicone-based catheter kits commanding brand premiums over latex formulations. Cost compression in standard-tier consumables is intensifying because petrochemical-derived silicone precursor costs fluctuate with natural gas pricing. Ambulatory care centers exhibit highest price sensitivity due to G-BA reimbursement pressure, whereas university hospitals prioritize certification grade over unit cost.
Supply Chain Analysis
Domestic-content mandates under EU Medical Device Regulation are reshaping sourcing toward EU-manufactured polymer alternatives. Germany's silicone processing capacity draws from Rhineland-Palatinate and Saxony chemical corridors, while stainless steel instrument forging rests on Tuttlingen's precision engineering heritage. Single-source sterilization services in gamma and ethylene oxide create geographic supply vulnerability for northern hospital networks. Distribution runs through direct-to-hospital channels for high-velocity consumables, with Cardinal Health and regional cooperatives building captive last-mile logistics that bypass traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's hospital supplies market functions as a cost-of-compliance story where BfArM's Medical Device Regulation certificate backlog creates a 12-18 month barrier-to-entry moat for compliant players.
For Market Incumbents: Deploy sterilization documentation capabilities as the primary defensive lever. Build captive silicone processing facilities to secure margin structure against petrochemical feedstock volatility. Consolidate supplier panel relationships with Bavaria's Munich-Nuremberg hospital purchasing organizations before MDR compliance timelines compress further. For New Entrants and Emerging Players: Capture reusable surgical instrument refurbishment services in North Rhine-Westphalia where G-BA cost-containment mandates drive demand away from premium single-use alternatives. Target ambulatory care center procurement in Baden-Württemberg with same-day procedure kit offerings. Establish direct-to-hospital distribution partnerships rather than wholesaler relationships. For Investors and Strategic Acquirers: BfArM's issuance of sustainable disposal guidance is the leading indicator that environmental certification will separate viable acquisition targets from stranded assets. The five-to-ten year viability window favors vertically integrated manufacturers with in-house polymer science capabilities over pure-play distributors. Monitor sterilization validation expertise scarcity in eastern German manufacturing zones as a signal for consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | BfArM compliance certificates compress competitor qualification timelines by 12-18 months. |
| Silicone Processing Integration | Backward integration into petrochemical-derived precursors insulates margin structures from natural gas volatility. |
| Direct-to-Hospital Distribution | Cardinal Health's captive last-mile networks demonstrate channel compression viability in Lower Saxony. |
| Sustainable Polymer Development | PLA and PHA alternatives align with pending BfArM guidance on medical device disposal pathways. |
| RFID Inventory Integration | Consignment stock models reduce hospital working capital requirements for suture and staple inventories. |
Research Methodology
Independent corroboration across hospital procurement committees, biomedical engineers, GPO contracts managers, and BfArM regulatory affairs specialists underwrites the qualitative findings. Primary interviews with Bavaria's Munich-Nuremberg purchasing organizations and North Rhine-Westphalia Maximum Care supply chain directors combined with secondary validation from BfArM device registration databases, GPO contract repositories, and Robert Koch Institute infection-control protocol filings. Bottom-up demand modeling across catheter kit procurement cycles and top-down reimbursement framework analysis triangulate market sizing.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models product type, application, end user, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs derive from procedure volume trajectories, reimbursement pathway evolution, and polymer substitution elasticity. Sterilization capacity utilization rates and silicone precursor cost curves inform margin structure projections.
The model holds under stable BfArM regulatory enforcement and continued G-BA reimbursement framework continuity; deviation in notified body capacity constraints or REACH polymer restriction tightening would shift competitive positioning. Forecasts reflect assumptions about ambulatory surgery migration pace and sustainable disposal guidance implementation timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Compression Socks Market
Medical Supplies
Smear Mask Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Global Sterilization Container Systems Market