
 Non-Invasive Glucose Monitoring Devices Market | 2026-2036
Non-Invasive Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Glucose Monitoring Devices Market Intelligence
The US FDA's evolving pre-market approval framework for digital health technologies is pivoting the cost-of-entry calculus for new device manufacturers. Established medical device firms like Medtronic leverage their extensive clinical trial experience to navigate these pathways. Abbott Laboratories sustains its market position through strong brand recognition in diabetes care. Meanwhile, specialists like DiaMonTech GmbH differentiate through novel technology platforms.
Non-invasive glucose monitoring devices measure blood glucose levels without piercing the skin, often utilizing technologies like infrared spectroscopy to analyze interstitial fluid. Their primary purpose is to provide continuous or frequent glucose data for diabetes management and wellness tracking. Wearable sensors represent the fastest-growing product type, driven by consumer preference for convenience. In terms of end-users, the homecare segment dominates volume, while hospitals command higher-value, clinically validated systems.
Regulatory clearance pathways from bodies such as the US FDA and the European Medicines Agency (EMA) are critical for market access. The CE marking process in Europe, for instance, dictates stringent design and performance standards for all medical devices. Future device approval will depend on demonstrating clinical-grade accuracy comparable to minimally invasive systems. This requires a strategic focus on robust clinical validation and data integrity for all market participants.
Market Dynamics
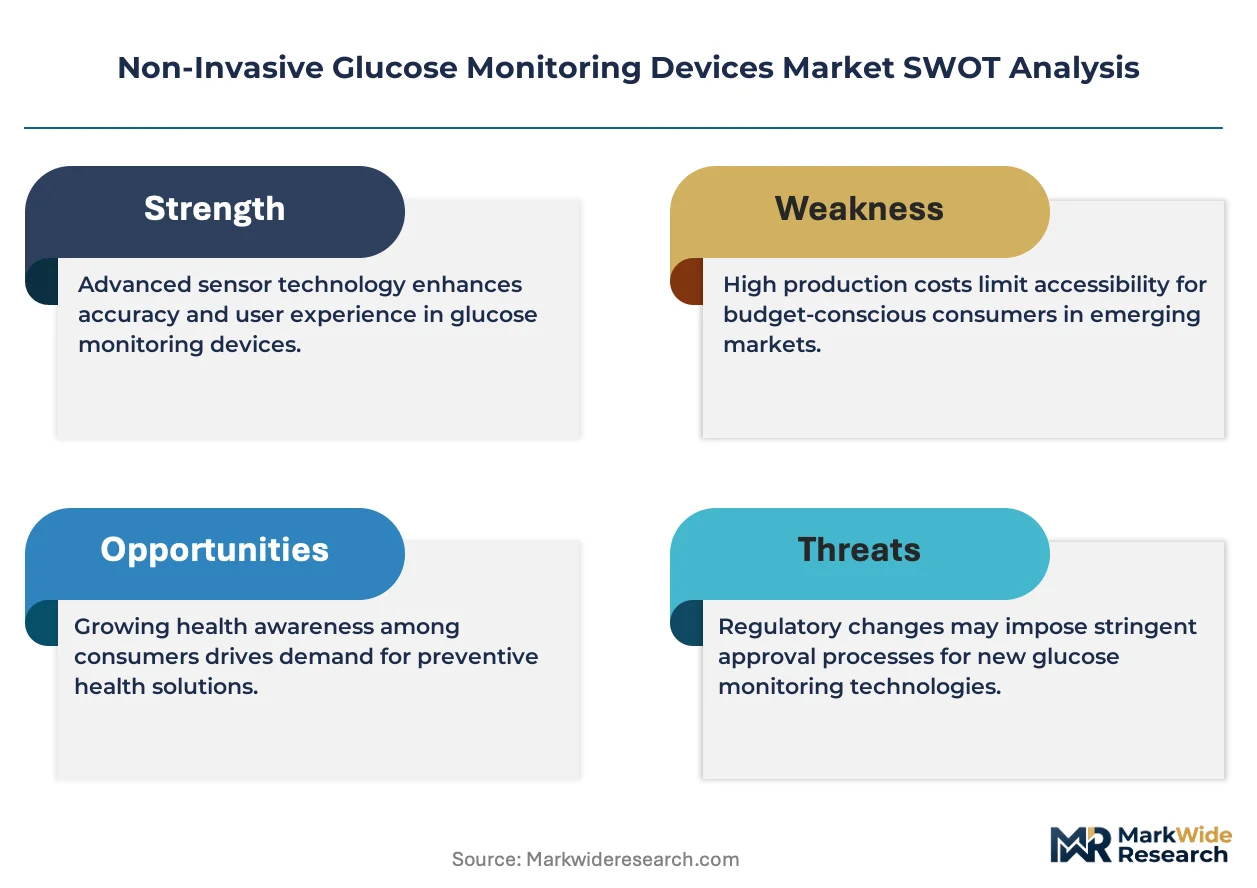
The market's central dynamic is the tension between the consumer push for convenient, wearable form factors and the stringent clinical accuracy standards demanded by medical regulators. This is forcing a rapid evolution in sensor technology, particularly infrared spectroscopy, to meet both needs simultaneously.
Growth Catalysts
- Sensor Miniaturization:Advances in infrared spectroscopy and microelectronics enable the integration of glucose sensors into smaller, more consumer-friendly devices like smartwatches and skin patches, expanding accessibility beyond traditional medical hardware and into the wellness segment.
- Wellness Monitoring Adoption:Demand from athletes and health-conscious consumers for continuous metabolic data to optimize performance and diet provides a significant commercialization pathway outside the regulated diabetes care market, fostering innovation in user experience and data analytics.
- Evolving Digital Health Frameworks:Regulatory pathways, such as the US FDA's pre-certification program for software and digital health, are being developed to streamline the approval process for lower-risk devices, potentially reducing time-to-market for new wellness-oriented monitors.
Market Restraints
- Clinical Accuracy Gap:A primary restraint is the difficulty for non-invasive technologies to consistently match the accuracy and reliability of established minimally invasive continuous glucose monitors (CGMs) or blood glucose meters, delaying regulatory approval for medical use.
- Stringent Regulatory Hurdles:Gaining clearance from bodies like the EMA or the US FDA requires extensive and costly clinical trials to prove safety and efficacy, creating a significant barrier to entry for startups and smaller technology firms.
- High Research and Development Costs:The substantial capital investment required for novel sensor development, clinical validation, and miniaturization limits the number of companies that can compete effectively, concentrating the market among well-funded entities.
Strategic Opportunities
- Underserved Diabetic Populations:Markets like Brazil and India, with large and growing diabetic populations but lower penetration of invasive monitoring, present a major opportunity for affordable and accessible non-invasive solutions tailored to homecare settings.
- Pre-diabetes Management Programs:A significant opportunity exists in developing devices and platforms targeted at the pre-diabetic population for lifestyle intervention and disease prevention, a segment largely unaddressed by current medical-grade monitors.
- Integration with Digital Therapeutics:Combining non-invasive glucose data with digital coaching platforms, AI-driven dietary advice, and other biometric inputs from wearables creates a powerful opportunity for comprehensive, personalized chronic disease management solutions.
Industry Challenges
- Data Security and Privacy:Ensuring the security of sensitive personal health information against breaches and complying with regulations like HIPAA in the US and GDPR in Europe is a critical operational challenge, especially for cloud-connected devices.
- Clinical Trial Recruitment and Execution:The process of designing and executing large-scale clinical studies to generate the robust data required for regulatory submission is a lengthy and complex operational hurdle for all device manufacturers.
- System Interoperability:A lack of standardization presents challenges in integrating data from non-invasive monitors into existing electronic health record (EHR) systems used by hospitals and clinics, limiting their utility in professional healthcare settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Glucose Monitoring Devices Market |
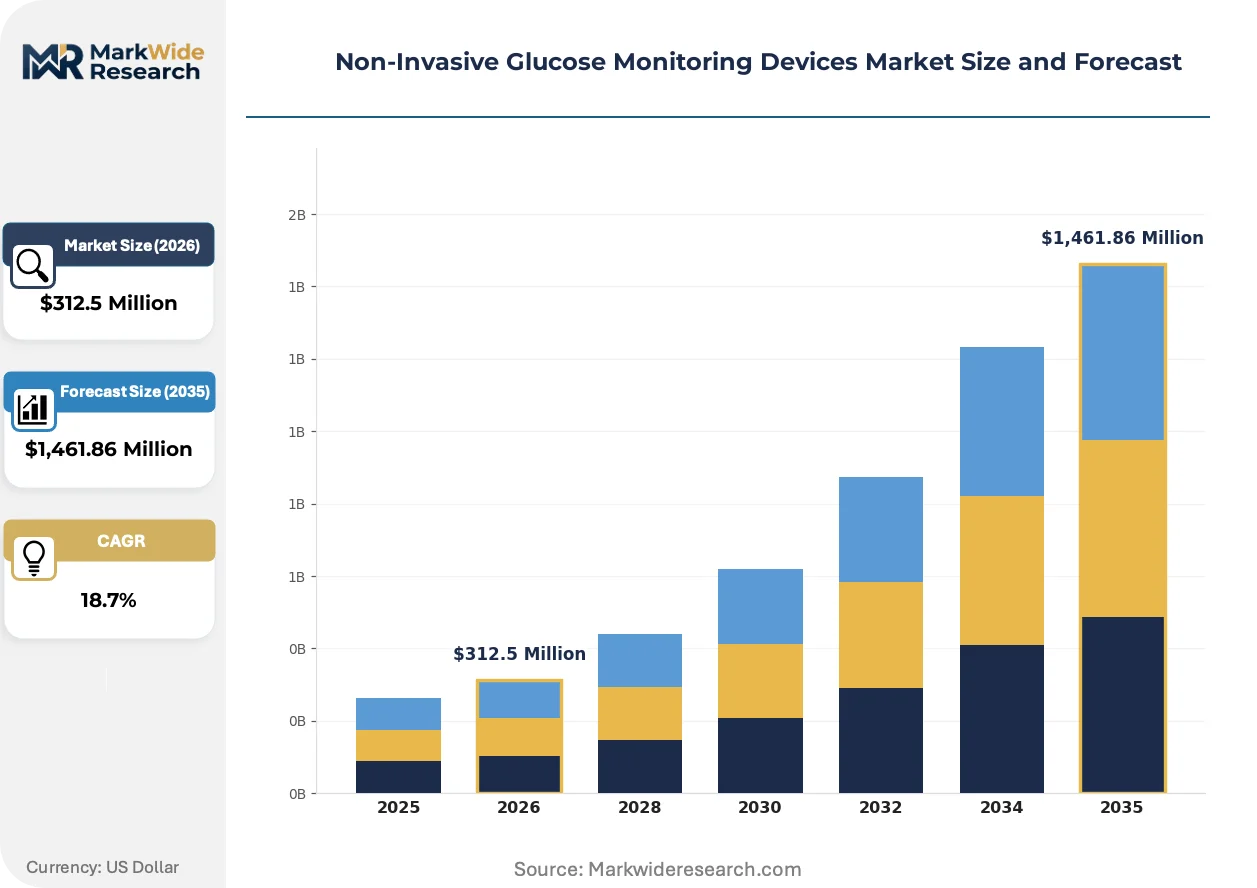
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Devices, Handheld Monitors, Smartphone Accessories Technology: Infrared Spectroscopy, Optical Coherence Tomography, Microwave Resonance, Raman Spectroscopy End User: Hospitals, Homecare, Diagnostic Labs, Research Institutions Application: Diabetes Management, Wellness Monitoring, Clinical Research, Athletes |
| Companies Covered | Dexcom, Inc., Medtronic, Abbott Laboratories, DiaMonTech GmbH, Nemaura Medical, LifePlus, Afon Technology, Know Labs, OrSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Glucose Monitoring Devices Market Strategic Shifts & Innovations
The market is being reshaped by the fusion of consumer electronics design principles with medical-grade sensing technology. This creates a new product class that prioritizes user experience and data integration for both wellness tracking and chronic disease management applications.
Infrared spectroscopy sensor technology enables the analysis of glucose in interstitial fluid without skin penetration. Adoption is accelerating within the consumer wellness segment, particularly among users of advanced fitness trackers. This technology is converging with biometric sensors in smartwatches and other wearables, enabling a more holistic view of metabolic health beyond single-point glucose measurements.
The European Union’s Medical Device Regulation (MDR) has elevated the requirements for market access. This regulation mandates more rigorous clinical evidence and continuous post-market surveillance for all medical devices, including non-invasive monitors. Device manufacturers targeting the European market are most affected, forcing them to reinvest in their quality management systems and data collection strategies to maintain their CE marking.
A clear behavioral shift toward data personalization is altering user expectations. Consumers and patients are moving away from passive data collection and demanding tools that allow them to integrate their glucose data with other health apps and wellness platforms. This trend is most visible in the direct-to-consumer channel in North America, where tech-savvy users prioritize ecosystem connectivity over closed, proprietary systems.
Non-Invasive Glucose Monitoring Devices Market Segmentation
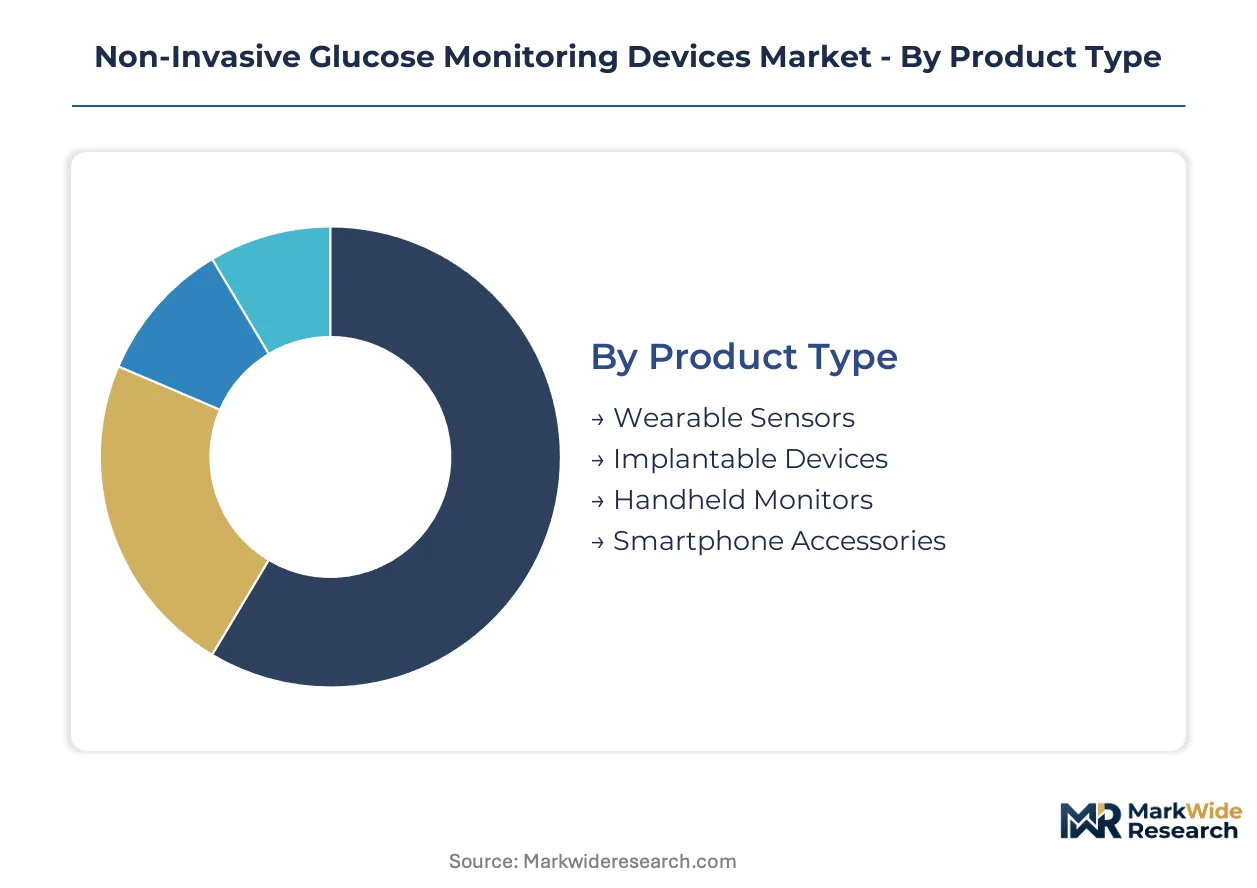
The non-invasive glucose monitoring devices market categorizes product offerings and demand drivers to illuminate specific growth opportunities. Understanding these distinct segments allows manufacturers to tailor technology development and market entry strategies. This granular view helps identify underserved populations and high-potential application areas within the evolving healthcare landscape.
Product Type:
The product type segmentation highlights the spectrum from highly customized, integrated solutions to standardized, portable devices for broad consumer access.
- Wearable Sensors:These devices integrate directly onto the skin, continuously measuring glucose levels in interstitial fluid through various non-invasive techniques. Demand concentrates in the wellness monitoring segment, particularly among athletes, driven by convenience and continuous data access for performance optimization.
- Handheld Monitors:These compact, portable devices provide on-demand glucose readings, often utilizing technologies like infrared spectroscopy for rapid analysis. Demand is strong in homecare settings, where ease of use and immediate results support daily diabetes management for a broad user base.
- Implantable Devices:These advanced systems offer long-term, continuous glucose monitoring from beneath the skin, providing highly consistent data.
- Smartphone Accessories:These peripherals connect to mobile devices, leveraging their processing power and display for glucose data acquisition and visualization.
Leading the category by volume: Handheld Monitors. Growing fastest: Wearable Sensors.
Technology:
The market's technology segmentation reveals varying levels of scientific maturity and supply chain concentration for specialized sensor components.
- Infrared Spectroscopy:This technique analyzes the absorption of infrared light by glucose molecules in interstitial fluid, providing real-time concentration data. Adoption is accelerating within the consumer wellness segment, particularly among users of advanced fitness trackers, due to miniaturization advances.
- Raman Spectroscopy:This method uses inelastic light scattering to identify glucose concentrations based on unique molecular vibrations, offering high specificity. Research institutions and advanced diagnostic labs prioritize this technology for its potential high accuracy and detailed biochemical analysis capabilities.
- Optical Coherence Tomography:This imaging technique uses light waves to capture high-resolution cross-sectional images of tissue, allowing for glucose concentration assessment.
- Microwave Resonance:This technology measures changes in microwave energy absorption by glucose molecules, providing a non-invasive pathway for blood glucose estimation.
Infrared Spectroscopy currently drives the most commercial deployments, with Raman Spectroscopy poised for significant advancements in clinical accuracy.
End User:
The end-user classification illustrates how different customer types prioritize convenience, clinical validation, or specialized analytical capabilities in their glucose monitoring solutions.
- Homecare:This segment includes individuals managing diabetes at home and health-conscious consumers utilizing devices for wellness tracking. The homecare environment prioritizes user-friendly interfaces and portability, driving demand for wearable sensors and smartphone accessories.
- Hospitals:Clinical settings demand high accuracy, data integration with electronic health records, and robust regulatory compliance for patient management. Hospitals command higher-value, clinically validated systems for critical care and inpatient diabetes monitoring, often requiring US FDA or EMA clearance.
- Diagnostic Labs:These facilities utilize non-invasive technologies for specialized testing and validation studies, focusing on precision and comparative analysis.
- Research Institutions:Academic and corporate research centers employ non-invasive monitors for clinical trials, technology development, and physiological studies.
The homecare segment accounts for the largest volume of device usage, while hospitals generate substantial revenue through high-value clinical systems.
Application:
The application segment highlights the varying maturity levels and regulatory pathways for non-invasive glucose monitoring across different use cases.
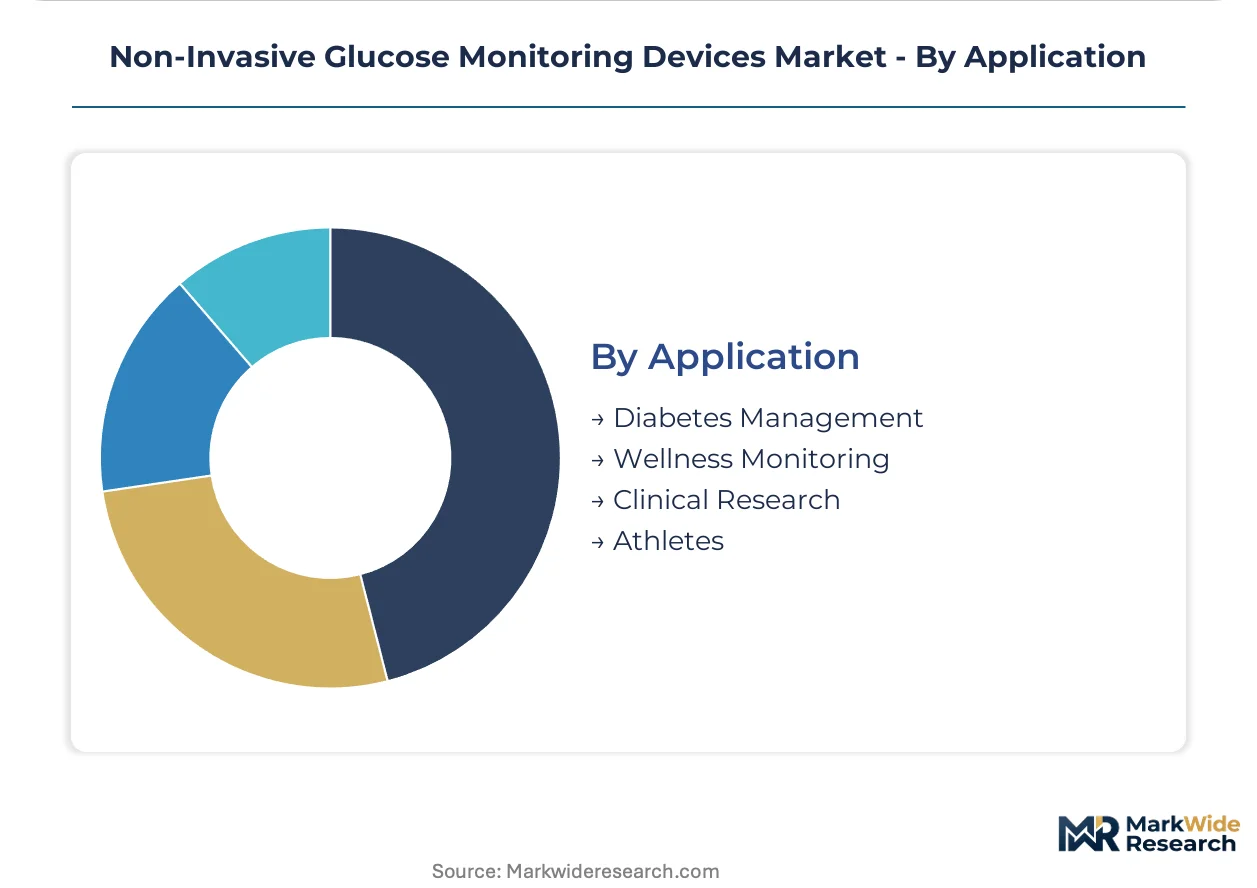
- Diabetes Management:This core application focuses on providing essential glucose data for individuals with diagnosed diabetes, enabling medication adjustments and lifestyle interventions. Regulatory bodies like the US FDA and EMA mandate stringent accuracy and clinical validation for devices intended for this medical purpose.
- Wellness Monitoring:This segment caters to health-conscious individuals and those focusing on metabolic optimization, utilizing glucose data for diet, exercise, and performance insights. Demand from athletes and health-conscious consumers provides a significant commercialization pathway outside the regulated diabetes care market.
- Clinical Research:Non-invasive monitors are employed in studies to evaluate new therapies, understand physiological responses, and validate novel device prototypes.
- Athletes:Elite and recreational athletes use these devices to optimize training, nutrition, and recovery by monitoring real-time glucose fluctuations during physical activity.
Diabetes Management forms the foundational demand for these devices, with Wellness Monitoring currently exhibiting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medtech innovation zones and specialized economic corridors globally concentrate investment and research efforts for non-invasive glucose monitoring devices. These regions benefit from a confluence of advanced healthcare infrastructure, high diabetes prevalence, and robust regulatory frameworks supporting digital health technologies. Manufacturers strategically target these areas for initial market penetration and clinical validation due to their high patient populations and technological readiness.
United States
Demand for non-invasive glucose monitoring devices stems from a large diabetic population and a strong consumer wellness segment. The US FDA's evolving pre-market approval framework for digital health technologies influences market entry strategies. Biotech and medical device innovation clusters in the Boston/Cambridge area drive significant research and development in this field.
Germany
Germany's advanced healthcare system and high diabetes prevalence create a substantial market for non-invasive glucose monitoring solutions. The European Medical Device Regulation (MDR) dictates stringent design and performance standards for all medical devices, including these monitors. Medical technology hubs in Bavaria, like Erlangen, actively develop and manufacture advanced diagnostic equipment.
Japan
An aging population and a tech-savvy consumer base drive the demand for convenient, non-invasive glucose monitoring in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees the rigorous approval process for medical devices. Tokyo's extensive research institutions and tech companies contribute to innovations in wearable health sensors.
India
India presents a significant opportunity due to its vast and growing diabetic population, alongside an increasing demand for affordable homecare solutions. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, focusing on accessibility and safety for local markets. Bengaluru's burgeoning health-tech startup ecosystem develops localized solutions for chronic disease management.
Brazil
Brazil's large underserved diabetic population offers a major market for accessible non-invasive glucose monitoring devices tailored to homecare settings. The National Health Surveillance Agency (ANVISA) provides regulatory oversight for medical device registration and market entry. São Paulo's medical technology sector sees investment in solutions addressing public health challenges.
Non-Invasive Glucose Monitoring Devices Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the non-invasive glucose monitoring devices market. The market structure includes established medical device firms, brand leaders in diabetes care, and innovative technology developers. Companies pursue strategic partnerships for technology integration and invest heavily in extensive clinical validation to meet stringent regulatory hurdles.
Established medical device firms like Medtronic and Abbott Laboratories occupy a significant position, leveraging their extensive clinical trial experience and brand recognition in diabetes care. DiaMonTech GmbH exemplifies a specialist focusing on novel technology platforms, differentiating through unique sensor capabilities. These companies anchor different segments of the market, from high-value clinical systems to innovative consumer-oriented solutions.
| Leading Market Players |
|---|
| Dexcom, Inc. |
| Medtronic |
| Abbott Laboratories |
| DiaMonTech GmbH |
| Nemaura Medical |
| LifePlus |
| Afon Technology |
| Know Labs |
| OrSense |
| Others |
Cost & Logistics Intelligence
Specialized optical lens material costs, essential for infrared spectroscopy, cascade through the non-invasive glucose monitoring supply chain, influencing the final device pricing tiers. This concentration of advanced component manufacturing capabilities largely dictates the cost structure for high-performance sensors, affecting market accessibility.
Pricing Analysis
Lead-time-driven pricing allows premium rates for rapid deployment of medical-grade systems, while standard inventory sees competitive discounts. Value-based pricing dominates medical device sales, reflecting clinical accuracy and patient outcomes. Price differentiation stems from US FDA or CE certification levels and established brand recognition in diabetes care. Pricing softness reflects increasing competition in the wellness segment, where consumer-grade devices compete on features and convenience. The homecare segment exhibits the highest price sensitivity, prioritizing affordability for frequent personal use.
Supply Chain Analysis
Rising logistics and freight costs impact the delivery of delicate sensor components and finished devices across global markets. Geographic supply concentration for critical microelectronics centers in Taiwan, while specialized optical sensors often originate from Germany and Japan. The supply chain relies on semiconductor chips, specialized optical sensors, and biocompatible plastics. Single-source vulnerability for advanced sensor components presents a structural risk. Distribution runs through a dual model, with direct-to-consumer channels serving the wellness market and specialized medical distributors reaching hospitals and clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story, with specialized sensor component manufacturing capacity serving as a primary bottleneck propping up pricing across all tiers.
For Market Incumbents: To counter the threat from emerging specialized startups with novel sensor technologies, established medical device firms must strategically acquire promising technology developers. Incumbents should also increase investment in advanced clinical trials to secure US FDA or EMA clearance for new non-invasive solutions. Expanding manufacturing capacity for miniaturized sensor components in key regions like Germany reinforces supply chain resilience. Prioritizing certification investment ensures sustained market access for medical-grade devices.
For New Entrants and Emerging Players: Enter via the underserved pre-diabetes management segment, offering accessible and user-friendly devices for lifestyle intervention. A significant white-space opportunity exists within large diabetic populations in emerging markets like India and Brazil, which demand affordable homecare solutions. Target the wellness segment in North America with a go-to-market strategy focused on data personalization and seamless ecosystem connectivity with existing health applications. Emphasize user experience and data integration capabilities to differentiate products.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with proprietary sensor technology in Germany, where stringent EU MDR compliance creates acquisition opportunities. The long-term viability of this market remains strong for integrated solutions combining glucose data with digital therapeutics. Identify acquisition targets possessing robust intellectual property in non-invasive sensing or established clinical validation pathways. The signal to watch is successful US FDA 510(k) or de novo clearance for a truly non-invasive medical-grade device.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Medical Use | Establishes clinical credibility and expands market access beyond wellness applications. |
| Partnership with Digital Health Platforms | Integrates glucose data for comprehensive personalized health management solutions. |
| Investment in Miniaturization R&D | Enables new wearable form factors and broadens consumer adoption pathways. |
| Geographic Expansion into Underserved Markets | Taps into large diabetic populations lacking current monitoring solutions. |
| Acquisition of Sensor Technology Specialist | Accelerates innovation and secures intellectual property in novel sensing methods. |
Research Approach
Document review covered US FDA filings, EMA submissions, medical device registries, and academic research papers, complemented by interviews with industry stakeholders. Primary research involved discussions with biomedical engineers, regulatory affairs specialists, hospital procurement managers, and diabetes educators. This approach enabled comprehensive data collection, triangulating findings through both bottom-up and top-down analyses.
Historical market trends were cross-referenced with expert panel insights to construct the forecast framework across the analysis window. The analytical framework segmented the market by product type, technology, end-user, application, and regional regulatory frameworks. Compound annual growth rates were derived from a weighted average of segment-specific growth drivers. Forecast inputs included sensor technology maturation rates and evolving digital health reimbursement policies.
Revisions become necessary when significant regulatory changes, unforeseen technological breakthroughs, or major shifts in healthcare reimbursement materialize. Forecasts reflect assumptions regarding clinical accuracy benchmarks and regulatory approval timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Global External Fixators Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
Embolization Plugs Market
Medical Devices
Cardioscope Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
Varicose Vein Treatment Devices Market