
 Medical Devices Vigilance Market | 2026-2036
Medical Devices Vigilance Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Devices Vigilance Market Analysis
Modular vigilance service bundling is restructuring how hospital systems evaluate post-market surveillance contracts. Oracle Corporation leverages its cloud infrastructure to anchor multi-tenant adverse event platforms across integrated delivery networks. Siemens Healthineers sustains competitive positioning through embedded vigilance modules within its imaging device ecosystems. Medtronic dominates cardiac device segments with proprietary signal detection algorithms that streamline regulatory submission workflows.
Medical devices vigilance encompasses the systematic collection, assessment, and reporting of adverse events and product performance data across the post-market lifecycle of regulated medical technologies, requiring structured electronic data interchange formats such as E2B(R3) for regulatory transmission. Its primary commercial purpose centers on enabling manufacturers to satisfy legally mandated safety surveillance obligations while minimizing product liability exposure and preserving market authorization. Diagnostic equipment vigilance currently occupies the largest service revenue pool due to the high volume of in-vitro diagnostic reagents subject to recurring performance monitoring across distributed laboratory networks. Patient monitors represent the fastest-expanding application segment as wearable and remote monitoring devices generate continuous streams of real-world performance data requiring automated signal detection. Surgical instruments vigilance remains comparatively mature, with established reporting protocols and lower incident variability limiting incremental service pricing power.
The FDA's MedWatch program and the EU MDR's post-market clinical follow-up requirements collectively shape product design investments and geographic launch sequencing for device manufacturers. ISO 13485 quality management system certification and MDSAP audit recognition now function as baseline market access credentials rather than competitive differentiators in procurement decisions. Health Canada and Japan's PMDA maintain distinct adverse event coding standards that fragment vigilance platform standardization efforts. Stakeholders must monitor convergence negotiations between the International Medical Device Regulators Forum and national competent authorities to anticipate harmonization timelines that will reshape compliance cost structures.
Market Dynamics
The EU Medical Device Regulation's tightened post-market surveillance obligations are forcing manufacturers to rebuild vigilance infrastructure around E2B(R3) electronic data interchange formats and automated signal detection workflows.
Growth Catalysts
- E2B(R3) Mandate:The International Council for Harmonisation's E2B(R3) standard is accelerating platform consolidation as manufacturers replace legacy reporting systems with structured electronic interchange capabilities.
- Remote Monitoring Expansion:Wearable cardiac monitors and continuous glucose sensors generate real-world performance data streams that require automated vigilance processing across distributed patient populations.
- Germany:The country's notified body infrastructure attracts device manufacturers seeking centralized EU MDR compliance, concentrating demand for integrated vigilance services in Munich and Berlin clusters.
Market Restraints
- Fragmented Coding Standards:Health Canada and Japan's PMDA maintain distinct adverse event classification systems that prevent single-platform standardization and force redundant data mapping investments.
- Specialized Talent Scarcity:Pharmacovigilance professionals with dual competency in medical device risk management and regulatory informatics command premium compensation that inflates service delivery costs.
- Legacy System Entrenchment:Hospital procurement departments face switching costs from decade-old adverse event databases with embedded workflow customizations that resist cloud migration.
Strategic Opportunities
- India:CDSCO's expanding medical device rules create compliance gaps that vigilance service providers can fill as domestic manufacturers build post-market surveillance capabilities.
- AI-Enabled Signal Detection:Machine learning algorithms applied to unstructured complaint data and social media monitoring converge with traditional statistical methods to identify safety signals earlier in product lifecycles.
- Integrated Delivery Networks:Multi-hospital systems are consolidating vendor relationships around single-vigilance platforms that span inpatient, ambulatory, and home care settings.
Industry Challenges
- Competency Shortfalls:Clinical data managers lack training in ISO 13485 quality management systems and MDSAP audit protocols, creating bottlenecks in adverse event documentation workflows.
- Interoperability Friction:Vigilance platforms must integrate with electronic health records, enterprise resource planning systems, and regulatory submission gateways that use incompatible data schemas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Devices Vigilance Market |
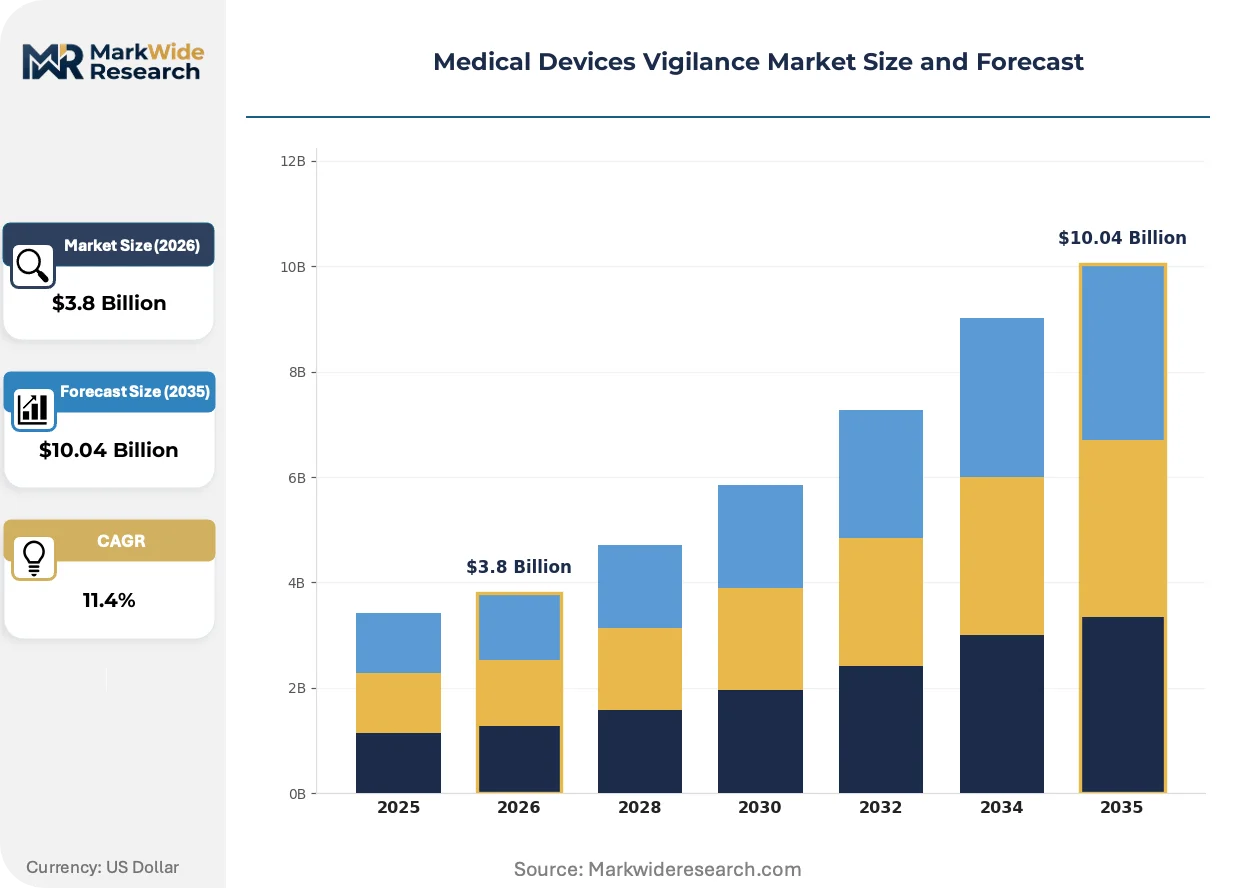
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Imaging Devices, Diagnostic Equipment, Patient Monitors Regulatory Framework: FDA, CE Mark, ISO 13485, MDSAP Application Area: Cardiology, Neurology, Orthopedics, Urology End User: Hospitals, Clinics, Research Laboratories, Home Care Providers |
| Companies Covered | Johnson & Johnson, Medtronic, Oracle Corporation, Siemens Healthineers, GE Healthcare, Abbott Laboratories, Boston Scientific, Stryker Corporation, ZEINCRO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Devices Vigilance Market Emerging Trajectories
Cloud-native vigilance architectures are displacing on-premise installations as hospital systems prioritize scalability and multi-tenant cost sharing across integrated delivery networks.
Natural language processing is decentralizing signal detection from centralized pharmacovigilance teams to point-of-care clinicians who capture adverse events through voice-enabled mobile interfaces. Emergency departments and surgical suites at academic medical centers in Boston and Cleveland are piloting these ambient documentation tools. This capability is compressing the latency between device malfunction observation and regulatory database entry from weeks to hours.
The FDA's MedWatch program has expanded mandatory reporting categories for software-as-a-medical-device products, compelling manufacturers of AI-enabled diagnostic algorithms to establish continuous performance monitoring infrastructure. Companies marketing radiology decision-support tools must now submit periodic algorithm performance reports that track sensitivity drift across diverse patient populations. This obligation is most acute among California-based digital health ventures seeking 510(k) clearance for computer-aided detection systems.
Hospital procurement departments are bundling vigilance services with cybersecurity monitoring contracts as ransomware attacks against medical device networks expose liability interdependencies. Integrated delivery networks in Texas and Florida now require single-vendor accountability for both adverse event reporting and threat detection across their device fleets. This consolidation is visible among faith-based hospital systems that have centralized supply chain decision-making at regional headquarters.
Medical Devices Vigilance Market Segmentation
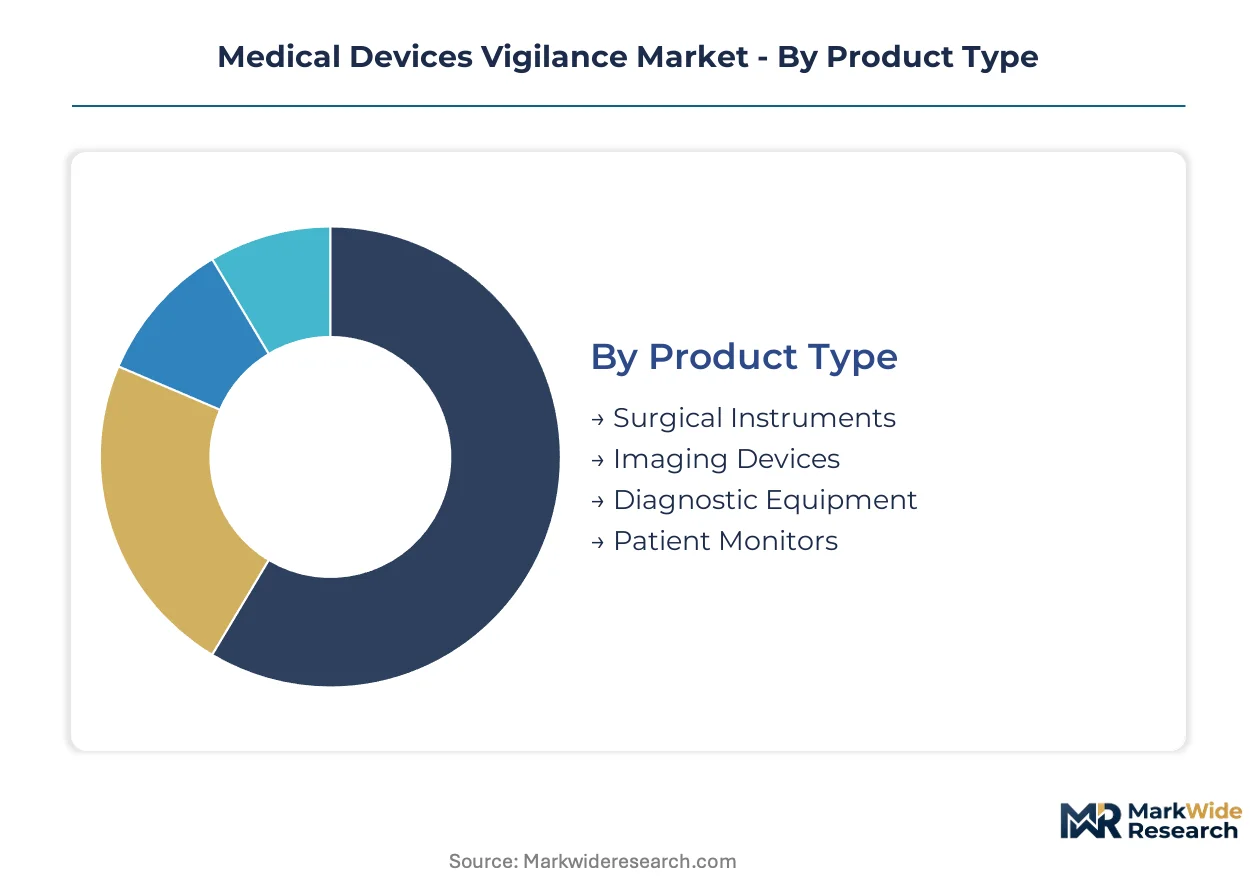
Vigilance service providers structure their offerings around distinct product categories, regulatory jurisdictions, clinical applications, and care settings. Each segmentation axis reveals divergent compliance cost structures and technology requirements that shape vendor pricing and platform architecture decisions.
Product Type:
Diagnostic equipment commands premium service fees due to recurring reagent performance monitoring, while surgical instruments operate on volume-based contract economics.
- Diagnostic Equipment:In-vitro diagnostic reagents require continuous lot tracking and distributed laboratory network surveillance. Hospital systems in Germany consolidate these contracts around E2B(R3)-compliant platforms that automate performance drift detection across reference laboratories.
- Patient Monitors:Wearable cardiac monitors and continuous glucose sensors generate high-velocity real-world data streams. Remote monitoring expansion in the US and Japan drives demand for automated signal detection that compresses reporting latency from weeks to hours.
- Surgical Instruments:Established adverse event protocols and lower incident variability limit incremental pricing power for vigilance services.
- Imaging Devices:Embedded vigilance modules within radiology ecosystems reduce standalone service attach rates.
Today's leader: Diagnostic Equipment. Tomorrow's challenger: Patient Monitors.
Regulatory Framework:
Jurisdiction-specific compliance obligations fragment platform standardization and force redundant data architecture investments.
- FDA:MedWatch program mandates structure adverse event reporting through standardized forms and electronic gateways. California-based digital health ventures face expanded software-as-a-medical-device surveillance obligations requiring continuous algorithm performance monitoring.
- CE Mark:EU MDR post-market clinical follow-up requirements tighten surveillance obligations across member states. Manufacturers seeking centralized compliance concentrate vigilance operations in Germany's notified body clusters.
- ISO 13485:Quality management system certification now functions as baseline market access credential rather than competitive differentiator in procurement evaluations.
- MDSAP:Audit recognition streamlines multi-jurisdictional compliance but requires harmonized documentation workflows across FDA, Health Canada, and Japan's PMDA standards.
CE Mark requirements are expanding most quickly as EU MDR implementation accelerates platform consolidation.
Application Area:
Cardiology's device density and signal complexity justify premium vigilance investment, while orthopedics operates on mature reporting protocols.
- Cardiology:Cardiac implantable electronic devices and hemodynamic monitors demand proprietary signal detection algorithms. Medtronic's dominance in this segment stems from integrated regulatory submission workflows that streamline FDA interaction.
- Neurology:Deep brain stimulators and seizure monitoring devices require specialized adverse event coding that fragments standardization efforts.
- Orthopedics:Joint replacement and spinal implant surveillance follows established protocols with lower real-time data velocity.
- Urology:Incontinence devices and endoscopic instruments generate moderate adverse event volumes with standardized reporting pathways.
Cardiology captures current revenue concentration. Neurology presents the steepest expansion trajectory as implantable neurotechnology advances.
End User:
Hospital procurement departments drive contract consolidation, while home care providers create distributed data capture challenges.
- Hospitals:Integrated delivery networks in Texas and Florida bundle vigilance with cybersecurity monitoring contracts. Faith-based systems centralize vendor selection at regional headquarters to enforce single-platform accountability.
- Home Care Providers:Remote patient monitoring devices generate continuous data streams requiring cloud-native architectures. Wearable deployment across distributed populations strains legacy on-premise systems.
- Clinics:Ambulatory surgical centers rely on manufacturer-sponsored vigilance services due to limited internal regulatory expertise.
- Research Laboratories:Investigational device exemption studies require parallel safety surveillance that duplicates commercial vigilance infrastructure.
Hospitals dominate contract value. Home Care Providers are gaining share fastest as remote monitoring reimbursement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical devices vigilance infrastructure first scaled in the United States through FDA's MedWatch program, then diffused to Europe via the Medical Device Directive framework. Today's compliance geography reflects this bifurcated heritage while new clusters emerge in Asia-Pacific manufacturing hubs.
United States
FDA's expanded software-as-a-medical-device surveillance obligations now require continuous algorithm performance monitoring from AI-enabled diagnostic ventures. The MedWatch program mandates structured adverse event reporting through standardized electronic gateways. California-based digital health companies in the San Francisco Bay Area face the most acute compliance pressure as they seek 510(k) clearance for computer-aided detection systems.
Germany
The country's notified body infrastructure attracts device manufacturers seeking centralized EU MDR compliance, concentrating demand in Munich and Berlin metropolitan clusters. Post-market clinical follow-up requirements under the EU Medical Device Regulation tighten surveillance obligations across all member states. Bavaria's regulatory services ecosystem anchors continental vigilance operations for cardiac implantable electronic devices.
Japan
PMDA maintains distinct adverse event coding standards that fragment platform standardization efforts and force redundant data mapping investments. The country's pharmaceutical and medical device agency requires harmonized documentation workflows alongside FDA and Health Canada standards under MDSAP recognition. Tokyo's regulatory consulting clusters specialize in bridging these classification gaps for multinational manufacturers.
India
CDSCO's expanding medical device rules create compliance gaps that vigilance service providers target as domestic manufacturers build post-market surveillance capabilities. The Central Drugs Standard Control Organization now classifies additional product categories under formal regulatory oversight. Hyderabad and Mumbai host emerging regulatory technology firms that serve both export-oriented device makers and hospital procurement departments.
United Kingdom
The Medicines and Healthcare products Regulatory Agency maintains post-market surveillance requirements that diverged from EU MDR following Brexit, creating parallel compliance obligations. MHRA's standalone vigilance database forces manufacturers to maintain separate UK reporting streams alongside European systems. London's regulatory affairs consultancies specialize in managing this dual-track documentation burden for cardiovascular device manufacturers.
Medical Devices Vigilance Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory informatics capability and integrated platform scale. The market structures around three tiers: diversified healthcare conglomerates with captive vigilance infrastructure, specialized regulatory technology vendors, and hospital systems insourcing through custom platform builds. Consolidation pressure intensifies as procurement departments demand single-vendor accountability spanning adverse event reporting, cybersecurity monitoring, and cloud-native data architectures.
Within the diversified healthcare technology tier, Oracle Corporation and Siemens Healthineers exemplify contrasting platform strategies. Oracle leverages cloud infrastructure to anchor multi-tenant adverse event platforms across integrated delivery networks. Siemens Healthineers sustains positioning through embedded vigilance modules within imaging device ecosystems that reduce standalone service attach rates. Medtronic occupies a distinct archetype as a device manufacturer with proprietary regulatory submission workflows, dominating cardiac segments through integrated signal detection algorithms.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Oracle Corporation |
| Siemens Healthineers |
| GE Healthcare |
| Abbott Laboratories |
| Boston Scientific |
| Stryker Corporation |
| ZEINCRO |
| Others |
Supply Flow & Price Mechanics
Cloud-native platform migration simultaneously compresses marginal service delivery costs and concentrates procurement leverage among integrated delivery networks capable of multi-tenant SaaS contracting. This technological shift rewards vendors with hyperscale data center footprints while fragmenting pricing power for on-premise legacy providers locked into hospital-specific customization cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, with premium tiers commanding attach rates for AI-enabled signal detection modules and dedicated regulatory submission support. Price differentiation hinges on ISO 13485 certification depth and E2B(R3) compliance automation, with FDA-audited platforms extracting 40-60% premiums over CE-mark-only alternatives. Cost compression in the standard tier is intensifying because hospital procurement departments now mandate bundled cybersecurity-vigilance contracts that erase standalone service margins. Ambulatory surgical centers exhibit the highest price sensitivity due to limited adverse event volumes, while academic medical centers in Germany and the United States demonstrate lowest sensitivity given liability exposure and research funding cushions.
Supply Chain Analysis
Freight costs for specialized regulatory hardware and encrypted data transmission infrastructure exert modest pressure relative to talent acquisition expenses, which dominate service delivery economics. Supply concentration rests on Ireland and India for pharmacovigilance talent pools, Germany for notified body proximity, and the United States for FDA relationship management. Raw material dependencies include cloud compute capacity from hyperscale providers, specialized adverse event coding software licenses, and secure data center real estate in regulatory-compliant jurisdictions. Single-source vulnerability concentrates in the notified body accreditation layer, where Germany's BfArM and Ireland's HPRA anchor EU MDR compliance pathways. Distribution runs through direct enterprise sales to hospital procurement departments and GPO-negotiated master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical devices vigilance functions as a regulatory compounder, with the EU MDR's E2B(R3) mandate forcing infrastructure rebuilds that expand addressable service revenue per manufacturer relationship.
For Market Incumbents: Lock in multi-year platform contracts before hospital procurement departments complete vendor consolidation cycles, prioritizing embedded AI signal detection capabilities that raise switching costs. Oracle Corporation and Siemens Healthineers exemplify this defensive posture through cloud infrastructure anchoring and imaging ecosystem integration respectively. Defensive moves must address emerging regulatory technology vendors offering modular point solutions at 30-40% cost discounts. For New Entrants and Emerging Players: Capture white-space in India's CDSCO compliance gap as domestic manufacturers build first-generation post-market surveillance capabilities, and in neurology device vigilance where specialized adverse event coding fragments incumbent standardization. The most penetrable segment lies in mid-tier Indian device manufacturers lacking ISO 13485 infrastructure. A regulatory-technology-as-a-service model bypassing capital-intensive platform builds offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional regulatory consulting boutiques with captive notified body relationships and established E2B(R3) implementation track records. Long-term viability over the next decade hinges on AI-enabled signal detection differentiation as statistical methods commoditize. Acquisition targets should demonstrate installed bases within Germany's notified body clusters. The critical inflection signal to watch is FDA-EMA convergence negotiations on adverse event coding harmonization, which would collapse redundant platform investments and reward scaled multi-jurisdictional players.| Strategic Initiative | Industry Significance |
|---|---|
| E2B(R3) Compliance Platform Deployment | EU MDR mandates force manufacturer infrastructure replacement, expanding service attach rates. |
| AI Signal Detection Module Integration | Machine learning differentiation compresses reporting latency from weeks to hours for cardiac monitors. |
| Cybersecurity-Vigilance Bundle Development | Texas and Florida IDNs now mandate single-vendor accountability for threat detection and adverse event reporting. |
| India CDSCO Regulatory Technology Buildout | Domestic device classification expansion creates compliance gaps for export-oriented manufacturers. |
| Notified Body Relationship Deepening | Germany's BfArM and Ireland's HPRA clusters anchor centralized EU MDR compliance pathways. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down regulatory technology vendor tracking forms the analytical core of this study. Primary interviews with hospital GPO contracts managers, biomedical engineers, regulatory affairs directors at device manufacturers, and pharmacovigilance officers at CROs generated demand-side validation. Secondary sources include FDA MedWatch submission databases, EUDAMED vigilance reports, ISO 13485 certification registries, and hospital procurement contract disclosures. Cross-referencing bottom-up adverse event volume estimates with top-down platform revenue disclosures enabled triangulation integrity checks.
Historical trendline analysis of vigilance service contract values and adverse event reporting volumes established baseline growth trajectories across the projection horizon. The analytical framework segments by product type, regulatory jurisdiction, clinical application, and end-user setting, with specialized modeling for software-as-a-medical-device surveillance obligations. CAGRs derive from regression-adjusted trend extrapolation incorporating E2B(R3) mandate implementation timelines and remote monitoring device deployment curves. Forecast inputs include hospital IDN consolidation rates and CDSCO regulatory expansion schedules.
Underlying measurement precision varies by segment; diagnostic equipment and patient monitors carry tighter precision than surgical instruments due to higher data velocity and established reporting protocols. Forecasts reflect assumptions regarding regulatory harmonization timelines and hospital procurement centralization rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Colposcopes Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Implantable Port Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Organ Preservation & Perfusion Products Market