
 Global Implantable Insulin Pump Market | 2026-2036
Global Implantable Insulin Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Implantable Insulin Pump Market Foresight
Multi-source component procurement is pivoting toward captive manufacturing of precision dosing mechanisms as supply security concerns mount. Medtronic plc leverages its vertically integrated sensor-pump ecosystem to dominate high-acuity segments. Tandem Diabetes Care Inc. competes through algorithm-first architecture that sustains software differentiation. Ypsomed Holding AG anchors European manufacturing capacity with automated fill-finish lines.
An implantable insulin pump is a fully enclosed, biocompatible device surgically placed in the subcutaneous tissue of the abdomen that delivers basal and bolus insulin through a catheter directly into the peritoneal cavity, typically operating at delivery accuracies within five percent and requiring refills every several months via transcutaneous ports. Its primary purpose is to replicate physiological pancreatic beta-cell function in insulin-dependent patients while eliminating external tubing and reducing infection risk versus traditional tethered systems. Patch pumps now occupy the fastest-expanding product category as patient preference shifts toward tubeless, discreet form factors. Endocrinology centers capture concentrated margin pools because complex patient onboarding and algorithm calibration generate recurring service revenue streams that device manufacturers cannot replicate through direct sales alone.
FDA premarket approval pathways enforce clinical evidence thresholds that delay market entry for novel pump architectures, while EMA MDR compliance demands expanded biocompatibility testing that elevates development costs for European market access. ISO 14155 governs clinical investigation design across jurisdictions, creating harmonized but rigorous trial execution standards that shape competitive timelines. Stakeholders must monitor reimbursement code consolidation between implantable and external pump categories as payers recalibrate coverage policies around total cost-of-care outcomes.
Market Dynamics
Closed-loop algorithm integration with continuous glucose monitoring is compressing product development cycles while elevating clinical evidence thresholds for regulatory clearance, forcing manufacturers to restructure R&D spending toward software validation and biocompatibility testing.
Growth Catalysts
- FDA premarket approval pathway harmonization:Streamlined clinical investigation design under ISO 14155 reduces redundant trial execution across jurisdictions, accelerating time-to-market for novel pump architectures.
- Peritoneal cavity delivery mechanism:Direct intraperitoneal insulin infusion replicates physiological pancreatic beta-cell kinetics more faithfully than subcutaneous delivery, driving endocrinology center adoption for glycemic lability cases.
- Germany reimbursement framework recalibration:Statutory health insurance funds now cover next-generation implantable systems under Diagnosis-Related Group carve-outs, expanding patient access beyond private payers.
Market Restraints
- Precision dosing mechanism supply concentration:Captive manufacturing of microfluidic pumps and ceramic pressure sensors concentrates among three specialized component suppliers in Switzerland and Japan, creating single-source vulnerability.
- EMA MDR biocompatibility testing escalation:Expanded cytotoxicity and sensitization studies for long-term implantable devices add 18-24 months to European market entry timelines and elevate development costs substantially.
- External patch pump substitution threat:Tubeless tethered systems from Tandem and Insulet capture patient preference for non-surgical intervention, particularly among Type 2 diabetes populations with residual beta-cell function.
Strategic Opportunities
- Japan aging diabetes demographic:METI reimbursement incentives for closed-loop systems in patients over 65 create a concentrated demand pool underserved by current algorithm calibration protocols.
- Dual-hormone pump convergence:Integration of glucagon micro-dosing alongside insulin delivery addresses hypoglycemia unawareness in high-acuity patients, opening premium pricing tiers.
- Direct-to-patient refill service models:Subscription-based transcutaneous port maintenance and insulin reservoir replacement bypass endocrinology center margin capture while improving adherence metrics.
Industry Challenges
- Algorithm validation engineer scarcity:Closed-loop control systems require specialized expertise in glucose prediction modeling and fault-tolerant software architecture that outpaces current biomedical engineering pipeline output.
- Legacy external pump data migration:Interoperability gaps between proprietary continuous glucose monitor protocols and new implantable platforms force redundant sensor purchases and frustrate patient onboarding.
- CE marking technical documentation burden:EMDR compliance demands exhaustive clinical evaluation reports and post-market surveillance systems that strain mid-cap manufacturer quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Implantable Insulin Pump Market |
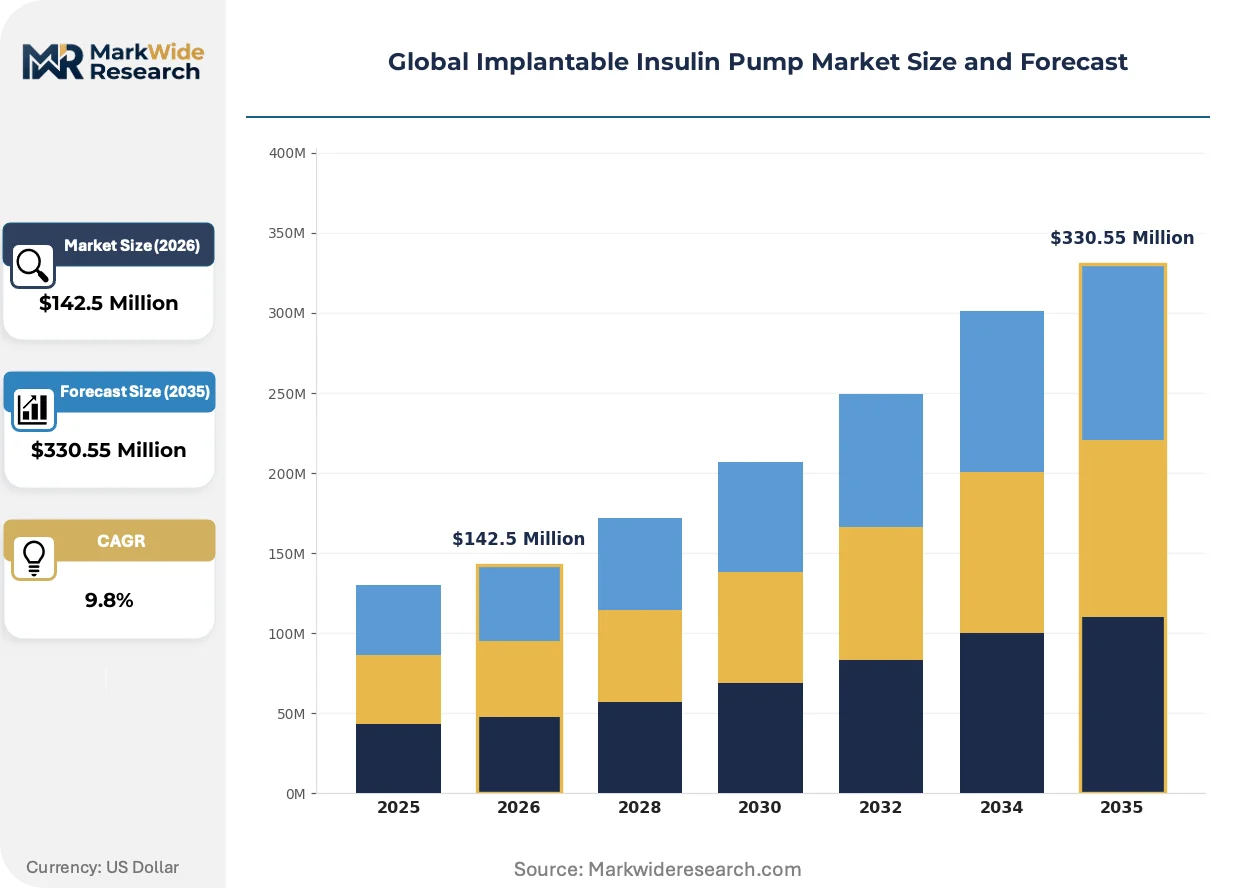
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $330.55 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reservoir Pumps, Patch Pumps, Catheter-Based Pumps, Refillable Pumps, Programmable Pumps Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Insulin-Dependent Diabetes, Non-Insulin-Dependent Diabetes End User: Specialty Clinics, Endocrinology Centers, Diabetes Care Units, Home Healthcare Providers, Long-Term Care Facilities Distribution Channel: Direct Sales, Online Pharmacies, Authorized Distributors, Specialty Medical Stores, Hospital Pharmacies |
| Companies Covered | Medtronic plc, F. Hoffmann-La Roche Ltd, Tandem Diabetes Care Inc., Insulet Corporation, Johnson & Johnson, Diabeloop SA, SOOIL Developments Co. Ltd., Apex Medical, Ypsomed Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Implantable Insulin Pump Market Shifts & Advancements
Algorithm-first product architecture is displacing hardware-centric development paradigms, while regulatory frameworks on both sides of the Atlantic recalibrate around software-as-a-medical-device classification and real-world evidence acceptance criteria.
Artificial pancreas control systems is converging with machine learning-enabled predictive glucose algorithms to enable anticipatory insulin dosing adjustments. Academic medical centers in the United States and the Netherlands are piloting these hybrid closed-loop configurations in adolescent Type 1 diabetes populations. The technology is converging with existing continuous glucose monitor infrastructure to compress the competitive moat around proprietary sensor-pump ecosystems.
EMA Medical Device Regulation implementation is elevating clinical evidence requirements for long-term implantable active devices. Manufacturers must now submit post-market clinical follow-up protocols and periodic safety update reports that extend far beyond pre-MDR obligations. European notified bodies are prioritizing implantable insulin pumps for enhanced surveillance, forcing sponsors to restructure quality management systems around risk-class III documentation standards.
Patient preference is shifting toward discreet, tubeless form factors that eliminate external tubing and reduce infection risk. Endocrinology centers in Germany and Japan report rising refusal rates for traditional tethered pump upgrades among working-age adults. This behavioral pivot is compressing demand for percutaneous catheter systems while elevating interest in fully implanted reservoir designs with transcutaneous refill ports.
Global Implantable Insulin Pump Market Segmentation
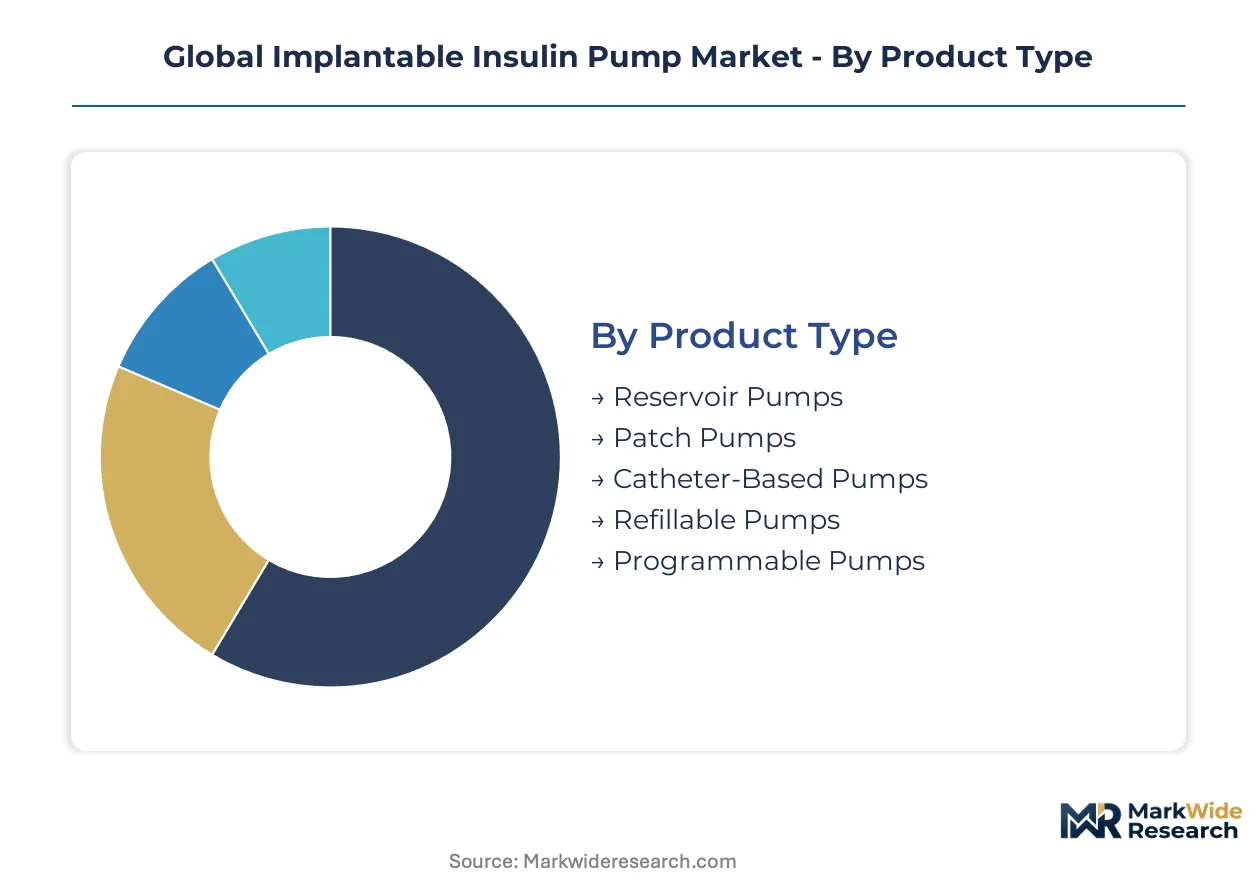
Segmentation in the implantable insulin pump market reveals how device architecture, patient metabolic profiles, and care delivery settings interact to shape procurement decisions. Manufacturers must align product roadmaps with specific reimbursement codes and clinical workflow requirements that vary sharply across these dimensions.
Product Type:
Replacement cycles for implantable pumps span 4-7 years depending on reservoir capacity and battery longevity, creating distinct upgrade windows for each architecture.
- Reservoir Pumps:These devices store insulin in a sealed titanium chamber with 3-6 month capacity between refills. Demand concentrates in Germany and Japan where statutory insurance covers extended-interval maintenance for working-age Type 1 patients facing glycemic volatility.
- Patch Pumps:Tubeless, fully disposable units adhere directly to subcutaneous tissue with integrated glucose sensing. Patient preference in the United States is shifting fastest toward these discreet form factors, particularly among adolescents and young adults prioritizing body image and activity flexibility.
- Catheter-Based Pumps:Traditional percutaneous delivery systems with external tubing connections.
- Refillable Pumps:Semi-permanent implants with transcutaneous port access for reservoir replenishment.
- Programmable Pumps:Devices with clinician-adjustable basal rate profiles and bolus calculators.
Volume placements concentrate in Reservoir Pumps; the faster expansion belongs to Patch Pumps.
Therapy Area:
Cost tier stratification across therapy areas determines pricing power, with premium capture strongest where complication risk justifies intensive monitoring investment.
- Type 1 Diabetes:Absolute insulin deficiency requiring continuous basal-bolus replacement. Endocrinology centers in the United States and the Netherlands drive demand for closed-loop integration as these facilities absorb algorithm calibration complexity.
- Type 2 Diabetes:Progressive beta-cell failure with residual insulin production. Japan's METI reimbursement incentives for patients over 65 are expanding addressable population, though patch pump substitution limits implantable uptake in less severe cases.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring temporary insulin intervention.
- Insulin-Dependent Diabetes:Broad category encompassing all etiologies requiring exogenous insulin.
- Non-Insulin-Dependent Diabetes:Early-stage disease managed through oral agents with limited pump applicability.
Revenue concentration sits with Type 1 Diabetes; Type 2 Diabetes is climbing the fastest as aging demographics expand eligible populations.
End User:
Margin structure varies by end user type, with service-integrated channels capturing recurring revenue streams unavailable through pure device sales.
- Endocrinology Centers:Specialized facilities with in-house pump programming expertise and continuous glucose monitor integration capabilities. Germany's Diagnosis-Related Group carve-outs for next-generation systems have concentrated procurement authority here.
- Specialty Clinics:Focused diabetes management practices with limited surgical implantation capacity.
- Diabetes Care Units:Hospital-based departments managing acute glycemic crises.
- Home Healthcare Providers:Agencies delivering transcutaneous refill and troubleshooting services.
- Long-Term Care Facilities:Skilled nursing settings managing elderly patients with complex comorbidities.
Algorithm calibration revenue pools deepest at Endocrinology Centers; Home Healthcare Providers are gaining share fastest as direct-to-patient refill models proliferate.
Distribution Channel:
Supply chain configuration determines speed-to-implantation and inventory carrying costs, with channel choice reflecting patient acuity and device complexity.
- Direct Sales:Manufacturer-to-provider relationships for high-acuity programmable systems requiring specialized training. Medtronic and Tandem dominate this channel in the United States through field clinical specialist deployment.
- Authorized Distributors:Regional intermediaries stocking standard reservoir and refillable configurations for European and Japanese hospital networks.
- Hospital Pharmacies:Institutional procurement for inpatient initiation and emergency replacement.
- Specialty Medical Stores:Retail access points for consumables and accessories.
- Online Pharmacies:Direct-to-consumer refill supplies with prescription verification.
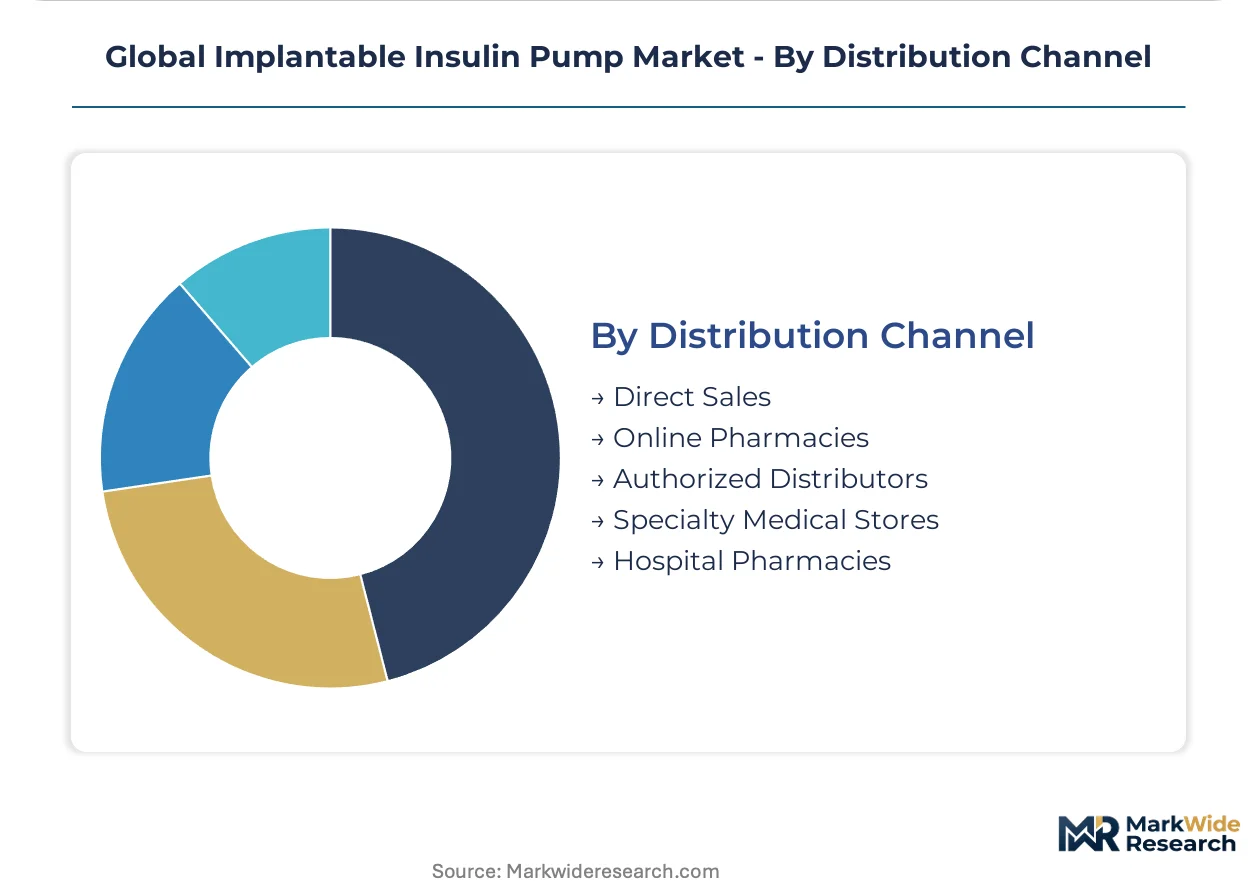
Transaction volume flows heaviest through Authorized Distributors; Direct Sales is expanding most quickly as algorithm complexity demands manufacturer-controlled onboarding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland's precision microfluidics manufacturing base supplies ceramic pressure sensors and dosing mechanisms that anchor the implantable pump supply chain across developed markets.
United States
Endocrinology centers in Boston and the San Francisco Bay Area drive closed-loop algorithm adoption for adolescent Type 1 diabetes populations. FDA premarket approval pathways enforce clinical evidence thresholds that compress development timelines for software-integrated systems. The Minneapolis-St. Paul corridor concentrates Medtronic's vertically integrated sensor-pump ecosystem manufacturing.
Germany
Statutory health insurance funds now cover next-generation implantable systems under Diagnosis-Related Group carve-outs, expanding patient access beyond private payers. EMA MDR compliance demands expanded biocompatibility testing that elevates development costs for European market entry. The Baden-Württemberg region anchors Ypsomed's automated fill-finish manufacturing capacity.
Japan
METI reimbursement incentives for closed-loop systems in patients over 65 create concentrated demand pools underserved by current algorithm calibration protocols. PMDA consultation procedures for novel active implantable devices shape commercialization timelines distinct from FDA pathways. The Kansai region around Osaka hosts specialized component suppliers for long-term implantable reservoirs.
Switzerland
Captive manufacturing of precision dosing mechanisms concentrates among specialized suppliers in the Jura Arc microtechnology cluster, creating single-source vulnerability for ceramic pressure sensors. Swissmedic maintains alignment with EMA MDR implementation timelines while preserving distinct notified body relationships. The Lake Geneva region supplies microfluidic pumps to multiple implantable device manufacturers.
Netherlands
Academic medical centers in Amsterdam and Rotterdam pilot hybrid closed-loop configurations with machine learning-enabled predictive glucose algorithms. CE marking technical documentation burdens under EMDR strain mid-cap manufacturer quality assurance bandwidth for market access. The Eindhoven Region's health technology cluster supports algorithm validation engineering talent pipelines.
Global Implantable Insulin Pump Market Competitive Landscape
Strategic partnerships dominate the current landscape as algorithm complexity demands collaborative software-hardware integration. The vendor base separates into three tiers: diversified multinationals with vertically integrated ecosystems, mid-cap specialists with captive component manufacturing, and emerging algorithm-first developers. Two strategic archetypes predominate: sensor-pump ecosystem integrators and software-centric platform builders. Competitive positioning hinges on backward integration into precision dosing mechanisms and geographic expansion through authorized distribution networks.
Within the diversified multinational tier, Medtronic plc and Johnson & Johnson exemplify ecosystem-integrated players with broad device portfolios spanning multiple diabetes management modalities. Tandem Diabetes Care Inc. and Insulet Corporation occupy positions as algorithm-first developers competing through software differentiation and tubeless form factor innovation. Ypsomed Holding AG represents the European manufacturing specialist archetype with automated production capacity. F. Hoffmann-La Roche Ltd anchors the diagnostics-integrated segment through glucose monitoring infrastructure. These groupings illustrate how competitive positioning stratifies across hardware integration depth, software capabilities, and regional manufacturing footprints.
| Leading Market Players |
|---|
| Medtronic plc |
| F. Hoffmann-La Roche Ltd |
| Tandem Diabetes Care Inc. |
| Insulet Corporation |
| Johnson & Johnson |
| Diabeloop SA |
| SOOIL Developments Co. Ltd. |
| Apex Medical |
| Ypsomed Holding AG |
| Others |
Supply & Pricing Matrix
Captive manufacturing of precision dosing mechanisms anchors both supply security and pricing power for implantable pump manufacturers, as backward integration into ceramic pressure sensors and microfluidic pumps insulates tier-one players from component volatility while justifying premium positioning against outsourced competitors.
Pricing Analysis
Warranty and algorithm calibration service bundling separates premium-tier implantable systems from unbundled hardware-only transactions. Three-tier pricing structure across premium closed-loop systems, standard programmable pumps, and economy reservoir configurations reflects FDA premarket approval tier and ISO 14155 clinical validation depth. Cost compression in standard-tier programmable pumps is intensifying because patch pump substitution erodes addressable volume. Type 2 diabetes populations with residual beta-cell function exhibit highest price sensitivity, while Type 1 patients at academic endocrinology centers absorb premium positioning for closed-loop integration.
Supply Chain Analysis
Dual-sourcing mandates from notified bodies and GPO contracts force manufacturers to qualify secondary suppliers for ceramic pressure sensors and titanium reservoir chambers. Component manufacturing concentrates in Switzerland, Japan, and Germany, with the Jura Arc microtechnology cluster feeding precision dosing mechanisms to multiple OEMs. Raw material dependencies span medical-grade titanium, biocompatible ceramics, and long-life battery chemistries. Single-source vulnerability for Swiss-manufactured microfluidic pumps creates structural supply risk. Distribution runs through authorized distributor networks for European hospital procurement, with direct sales channels dominating high-acuity programmable system placement in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cost-of-compliance dynamics under EMA MDR and FDA premarket approval pathways erect barrier-to-entry moats that favor incumbent players with established quality management systems and clinical evidence portfolios.
For Market Incumbents: Deepen backward integration into ceramic pressure sensor manufacturing to neutralize Swiss single-source vulnerability. Expand automated fill-finish capacity in Germany to capture statutory insurance reimbursement carve-outs. Algorithm-first entrants threaten hardware-centric positioning; software validation engineer scarcity demands aggressive talent pipeline investment.
For New Entrants and Emerging Players: Begin with dual-hormone pump development targeting hypoglycemia unawareness populations in Japan's METI-incentivized over-65 segment. Direct-to-patient refill subscription models bypass endocrinology center margin capture. Partner with academic medical centers in the Netherlands for machine learning algorithm validation.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified medtech conglomerates seeking closed-loop ecosystem integration. Five-to-ten year viability hinges on software-as-a-medical-device revenue scaling. Watch FDA software pre-certification pathway expansion as inflection signal for algorithm-first valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Technical Documentation Buildout | CE marking readiness under risk-class III standards secures European market access against mid-cap competitors. |
| Closed-Loop Algorithm Partnership | Continuous glucose monitor protocol integration compresses proprietary ecosystem moats around sensor-pump combinations. |
| Japan PMDA Consultation Engagement | Early regulatory dialogue shapes distinct commercialization timelines for aging demographic closed-loop systems. |
| Direct-to-Patient Refill Infrastructure | Subscription-based transcutaneous port maintenance captures recurring revenue outside endocrinology center channels. |
| Dual-Hormone Pump Development | Glucagon micro-dosing integration addresses hypoglycemia unawareness and opens premium pricing tiers. |
Research Methodology
Independent corroboration across endocrinology center purchasing committees, biomedical engineers at academic medical centers, and GPO contracts managers underwrites the qualitative findings. Primary interviews with regulatory affairs specialists and continuous glucose monitor integration technicians combined with secondary validation from FDA 510(k) and PMA filings, EMA MDR technical documentation databases, and ISO 14155 clinical investigation registries. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring to historical implantable pump placement volumes and reimbursement code utilization established the forecast baseline. The projection horizon spans product type segmentation across reservoir, patch, and catheter-based architectures; therapy area stratification by Type 1, Type 2, and gestational diabetes; and end-user channel modeling across endocrinology centers, home healthcare providers, and hospital systems. CAGRs derive from algorithm adoption curve analysis and statutory reimbursement expansion trajectories. Closed-loop integration penetration rates and dual-hormone pump development timelines feed scenario-weighted outputs.
Regulatory pathway delays, reimbursement code consolidation between implantable and external pump categories, and algorithm validation engineer scarcity are the dominant revision risks. Deviation in FDA software pre-certification pathway implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Global Diabetic Ulcers Treatment Market