
 Cast Removal Devices Market | 2026-2036
Cast Removal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cast Removal Devices Market Outlook
Modular blade-and-motor configurations is decoupling capital expenditure from consumable commitments, giving procurement teams flexibility to unbundle maintenance contracts from initial hardware purchases. Stryker Corporation leverages its orthopedic ecosystem to bundle cast removal tools with trauma fixation systems, while Smith & Nephew plc anchors its position through specialized training programs for surgical technicians. De Soutter Medical differentiates via compact, battery-powered designs that occupy premium space in mobile surgical units.
Cast removal devices are motorized or hand-held instruments engineered to cut orthopedic casts and splints without contacting underlying skin, typically operating at blade speeds below 3,000 oscillations per minute with integrated thermal guards to prevent patient burns. Their primary purpose is to enable safe, efficient removal of synthetic and plaster immobilization materials in clinical and emergency settings. Oscillating saw systems dominate hospital capital budgets due to proven reliability and broad material compatibility, while laser cutter technology captures fastest-growing interest where precision and reduced thermal trauma justify higher per-procedure costs. Manual devices retain substantial volume in price-sensitive clinics and developing markets where electricity reliability constrains powered alternatives.
FDA 510(k) premarket notification requirements govern electrosurgical and powered cast removal systems in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance obligations on manufacturers distributing in European markets. ISO 13485 quality management certification has become a baseline threshold for supplier qualification by large hospital purchasing consortia. Stakeholders must monitor evolving MDR technical documentation requirements and FDA guidance on reusable device reprocessing as these frameworks increasingly determine competitive access and compliance cost structures.
Market Dynamics
Powered oscillating systems are displacing manual cast saws in hospital orthopedic departments, driven by throughput mandates and patient safety protocols that penalize thermal injury incidents.
Growth Catalysts
- FDA 510(k) Pathway:Streamlined premarket notification for electrosurgical cast cutters accelerates device commercialization timelines for innovators targeting US hospital systems.
- Ambulatory Surgical Centers:Expansion of outpatient orthopedic procedures generates replacement demand for compact, portable removal systems with rapid sterilization cycles.
- Sports Medicine Specialization:Dedicated athletic injury clinics in the United States prioritize powered cutting equipment to manage high patient turnover during seasonal peak periods.
Market Restraints
- Capital Intensity:Powered oscillating systems require substantial upfront investment in blade sterilization infrastructure and maintenance contracts that strain rural clinic budgets.
- Supply Concentration:Precision motor and blade assemblies concentrate among specialized German and Japanese component suppliers, creating vulnerability to logistics disruptions.
- Technical Limitation:Thermal guards on high-speed blades add weight and bulk that compromise maneuverability in pediatric applications where anatomical access is constrained.
Strategic Opportunities
- Battery-Powered Mobility:Untapped demand exists for cordless cast removal units in field hospital and disaster response deployments where electrical grid reliability is uncertain.
- Laser Cutter Convergence:Integration of fiber laser technology with thermal monitoring sensors addresses precision requirements in burn unit and dermatology-adjacent orthopedic settings.
- EU MDR Certification:Early compliance with strengthened clinical evidence requirements under the Medical Device Regulation creates preferential access to European purchasing consortia.
Industry Challenges
- Surgical Technician Training:Powered system adoption requires certified instruction programs that hospital systems struggle to staff amid workforce shortages in sterile processing departments.
- Reprocessing Validation:Reusable blade sterilization protocols demand extensive bioburden testing documentation that extends FDA compliance timelines for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cast Removal Devices Market |
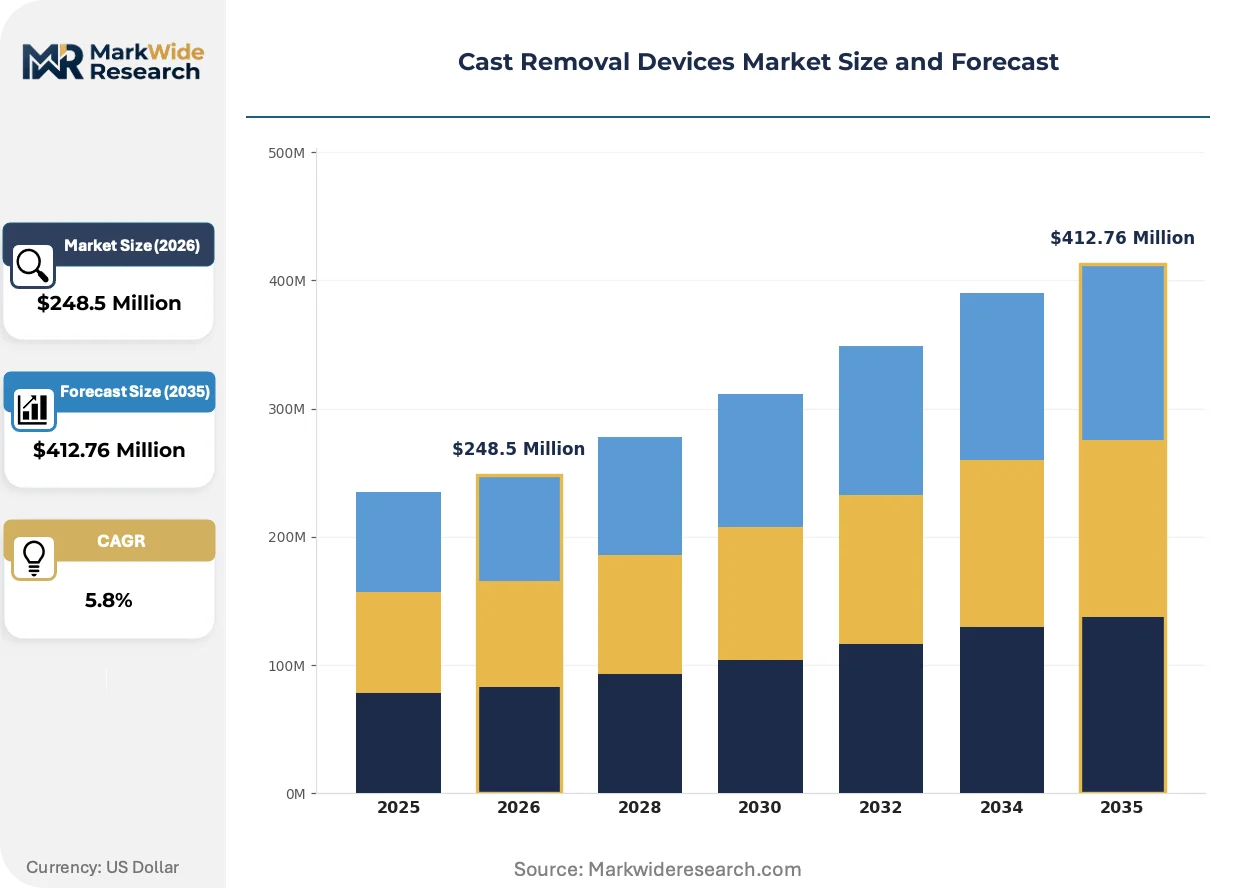
| Market Size in 2026 | $248.5 Million |
| Market Size in 2035 | $412.76 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oscillating Saw, Laser Cutter, Electrosurgical Unit, Manual Device Technology: Laser Technology, Powered Cutting, Static Cutting, Hybrid Method End User: Hospitals, Clinics, Orthopedic Centers, Patients Application: Trauma Care, Rehabilitation, Surgical Procedures, Emergency Services |
| Companies Covered | Stryker Corporation, De Soutter Medical, Smith & Nephew plc, Essity Aktiebolag, OSCIMED SA, Hanshin Medical Co., Ltd., Prime Medical Inc., Shanghai Bojin Medical Instrument Co., Ltd., HEBUmedical GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cast Removal Devices Market Strategic Shifts
Orthopedic device workflows are converging around integrated systems that bundle diagnostic imaging, fixation hardware, and removal tools into unified procurement frameworks.
Sensor-integrated cast cutters are automating blade speed modulation based on real-time thermal feedback, preventing patient burns during prolonged cutting sequences. Hospital orthopedic departments in the United States are adopting these systems fastest where malpractice exposure drives capital allocation toward safety-engineered equipment. This automation is compressing training requirements for surgical technicians while reducing procedure variance across shift changes.
The EU Medical Device Regulation imposes stricter post-market surveillance obligations on cast removal device manufacturers distributing in European markets. Clinical evidence documentation requirements now extend to reusable component reprocessing validation, increasing compliance costs for mid-tier suppliers. German and French hospital purchasing groups are responding by consolidating vendor lists around established ISO 13485-certified manufacturers with dedicated regulatory affairs teams.
After-sales service contracts are unbundling from initial hardware purchases as procurement teams seek modular blade-and-motor configurations. Ambulatory surgical centers in the United States are driving this shift, preferring per-procedure consumable pricing over capital-heavy ownership models. This behavioral change is most visible in Texas and Florida markets where ASC volume expansion has outpaced hospital infrastructure investment.
Cast Removal Devices Market Segmentation
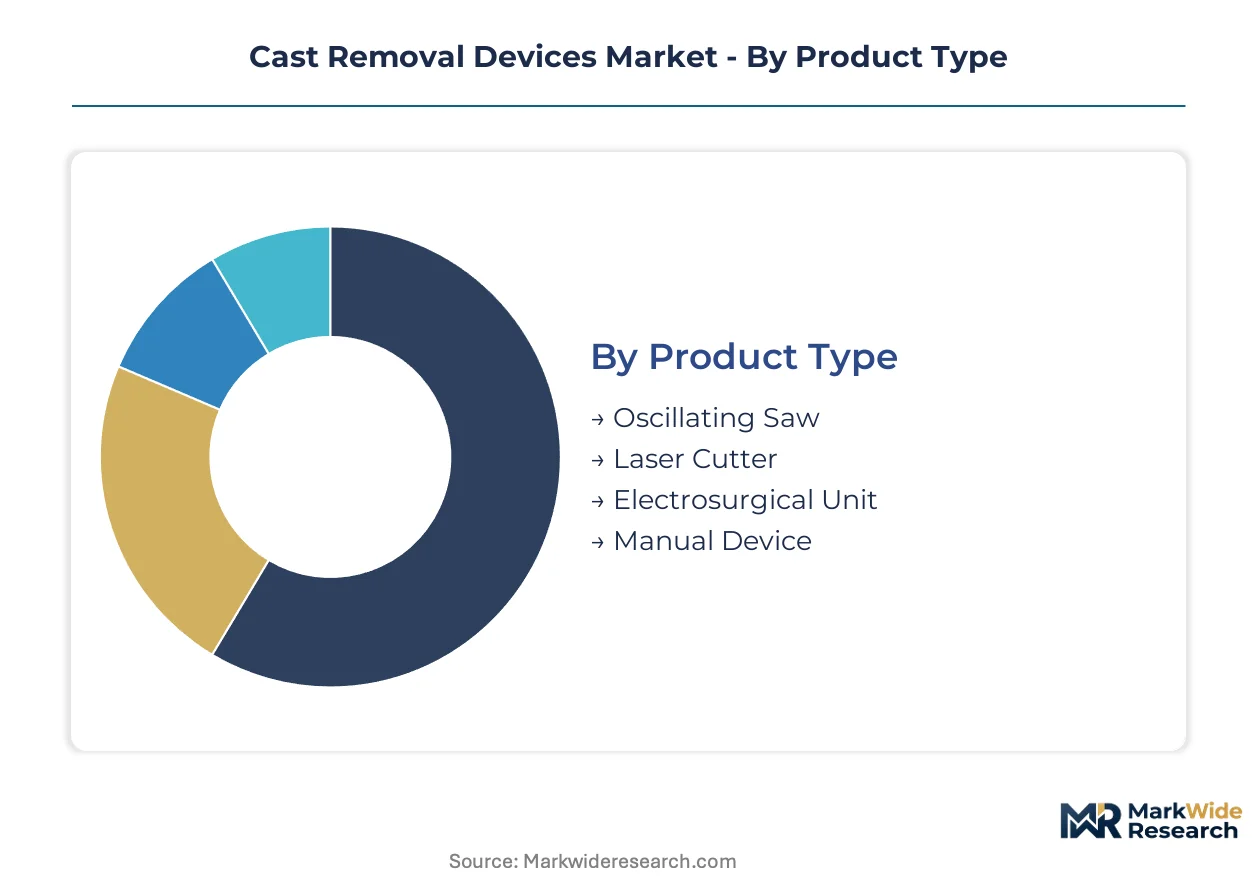
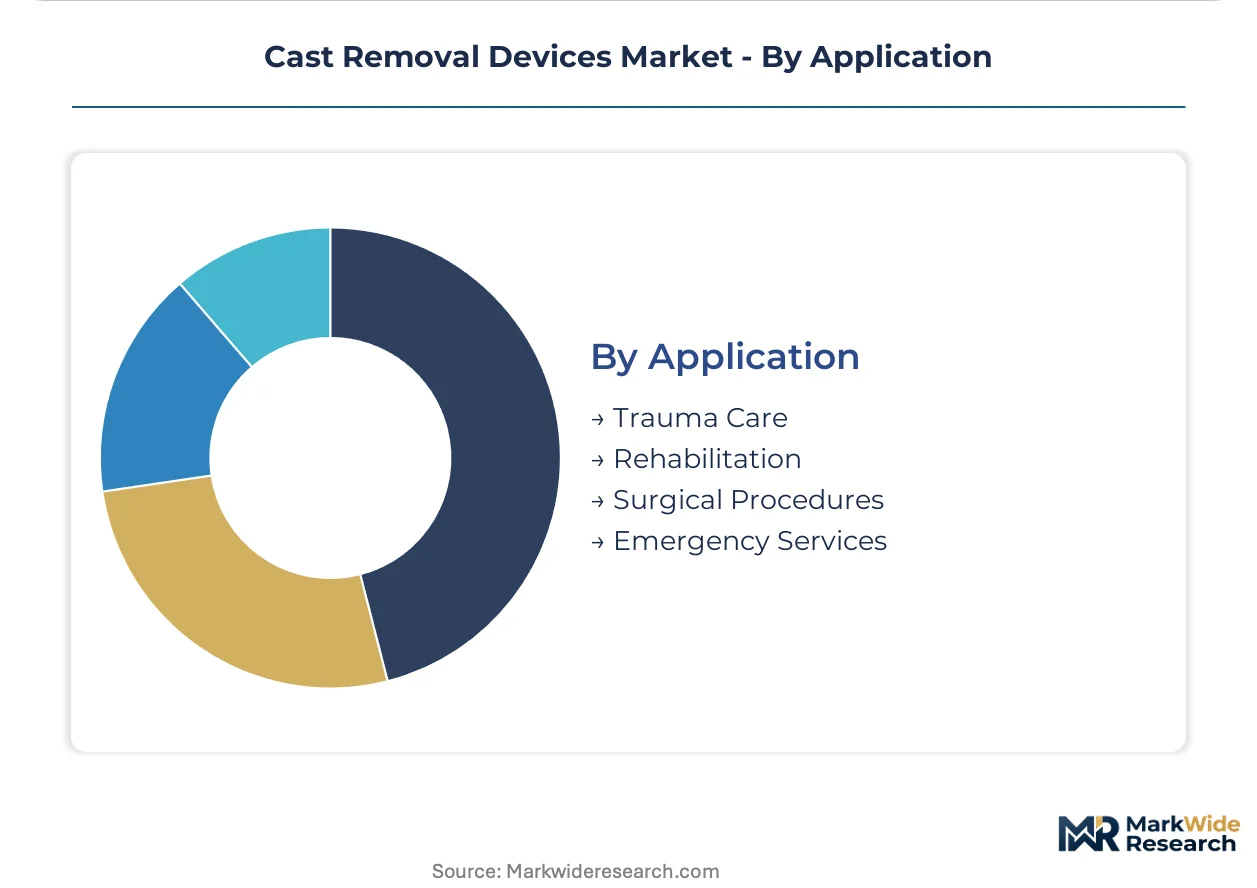
Cast removal device procurement varies sharply across clinical settings, with capital budgets, patient throughput requirements, and sterilization infrastructure determining technology choices. Understanding these segment boundaries helps suppliers align product configurations with specific buyer economics and regulatory constraints.
Product Type:
Replacement cycles diverge significantly across product categories, with powered systems requiring 5-7 year hardware refresh schedules versus indefinite manual device lifespans.
- Oscillating Saw:Motorized systems with reciprocating blades operating below 3,000 oscillations per minute, integrating thermal guards and vacuum ports for debris extraction. Hospital orthopedic departments in the United States concentrate procurement here, driven by malpractice exposure protocols that penalize thermal injury incidents.
- Laser Cutter:Fiber laser systems with real-time thermal monitoring sensors enabling precision cutting without blade contact. Demand concentrates in burn units and dermatology-adjacent orthopedic settings where reduced thermal trauma justifies higher per-procedure costs.
- Electrosurgical Unit:Radiofrequency-based cutting systems requiring FDA 510(k) clearance for commercialization in US markets.
- Manual Device:Hand-operated cast saws and spreaders retaining substantial volume in price-sensitive clinics and developing markets where electricity reliability constrains powered alternatives.
Oscillating Saw sits at the top of the volume ranking, with Laser Cutter climbing the fastest.
Technology:
Cost tier stratification separates premium sensor-integrated systems from basic motorized alternatives, with hybrid approaches capturing mid-market procurement flexibility.
- Powered Cutting:Electric motor-driven systems dominating hospital capital budgets through proven reliability and broad material compatibility with synthetic and plaster casts.
- Laser Technology:Precision cutting with automated thermal feedback modulation, expanding fastest where procedure volume justifies capital intensity.
- Static Cutting:Non-powered mechanical approaches retaining share in field hospital and disaster response deployments.
- Hybrid Method:Configurable systems allowing switching between powered and manual modes, appealing to ambulatory surgical centers seeking equipment versatility.
Powered Cutting commands the largest installed base, though Hybrid Method is gaining share fastest among ASC procurement teams.
End User:
Customer type determines pricing model preferences, with hospitals accepting capital-heavy ownership and clinics demanding per-procedure consumable structures.
- Hospitals:Large orthopedic departments with dedicated sterile processing infrastructure and certified surgical technician staffing, prioritizing safety-engineered equipment with automated thermal controls.
- Orthopedic Centers:Specialized facilities with high patient turnover during seasonal sports injury peaks, driving replacement demand for rapid-sterilization portable systems.
- Clinics:Price-sensitive settings where manual devices or basic powered systems dominate due to capital constraints and lower procedure volumes.
- Patients:Direct-purchase segment for home-based cast removal in remote or mobility-limited situations, representing minimal commercial significance.
Hospitals anchor procurement volume, while Orthopedic Centers show the steepest expansion trajectory in system deployments.
Application:
Application context dictates maneuverability requirements and thermal guard specifications, with pediatric and emergency settings imposing the most stringent constraints.
- Trauma Care:High-velocity injury management requiring rapid cast removal with minimal patient movement, driving demand for lightweight battery-powered units.
- Emergency Services:Pre-hospital and field deployment scenarios where electrical grid reliability is uncertain, creating untapped demand for cordless configurations.
- Surgical Procedures:Operating room settings with established sterilization protocols and trained surgical technician staff, favoring established oscillating saw platforms.
- Rehabilitation:Post-operative and long-term immobilization management with lower urgency requirements, accommodating heavier thermal-guard-equipped systems.
Trauma Care leads procedure volume, with Emergency Services expanding most quickly as field hospital capabilities modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powered cast removal technology originated in German surgical instrument workshops during the 1950s, with oscillating saw designs later refined by American orthopedic equipment manufacturers. Distribution now concentrates in advanced healthcare systems with established sterile processing infrastructure and malpractice liability frameworks.
United States
Ambulatory surgical centers in Texas and Florida drive replacement demand for rapid-sterilization portable systems. FDA 510(k) premarket notification requirements govern electrosurgical cast cutters entering commercial distribution. Hospital purchasing consortia in the Northeast Corridor prioritize safety-engineered equipment with automated thermal controls to reduce liability exposure.
Germany
Precision motor and blade assembly suppliers cluster in Baden-Württemberg and Bavaria, serving device manufacturers worldwide. EU Medical Device Regulation imposes strengthened clinical evidence and post-market surveillance obligations on manufacturers distributing in European markets. The Stuttgart industrial corridor hosts specialized component fabricators supplying oscillating saw mechanisms to global orthopedic equipment producers.
Japan
PMDA marketing approval pathways for powered surgical instruments maintain rigorous quality standards that filter market entrants. METI industrial policy supports domestic medical device manufacturing through targeted subsidy programs. The Chubu region around Nagoya concentrates precision machining capabilities for compact battery-powered surgical tools.
China
NMPA registration requirements for Class II medical devices create compliance barriers for foreign manufacturers seeking hospital procurement contracts. Shanghai Bojin Medical Instrument and similar domestic producers serve price-sensitive clinic segments with basic powered alternatives. The Yangtze River Delta manufacturing belt supplies manual cast removal devices to developing markets across Southeast Asia and Africa.
United Kingdom
Specialized training programs for surgical technicians anchor competitive positioning among established device suppliers. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR technical documentation standards. London-based orthopedic centers and Manchester trauma units concentrate procurement volume for premium oscillating saw systems.
Cast Removal Devices Market Competitive Environment
The competitive structure tilts toward diversified orthopedic conglomerates with integrated trauma fixation portfolios. Hospital purchasing consortia favor suppliers offering bundled diagnostic-to-removal workflow solutions. Three archetypes dominate: full-spectrum orthopedic platforms, specialized powered instrument specialists, and regional manual device fabricators. Strategic moves concentrate on M&A integration of blade sterilization technology and capacity expansion in battery-powered mobility segments.
Within the full-spectrum platform tier, Stryker Corporation and Smith & Nephew plc exemplify conglomerate positioning through orthopedic ecosystem breadth. De Soutter Medical occupies a specialist position among compact powered instrument designers. Among Asia-based fabricators, Hanshin Medical Co., Ltd. and Shanghai Bojin Medical Instrument Co., Ltd. represent regional manufacturing scale. HEBUmedical GmbH anchors German precision component supply. These five entities illustrate the geographic and strategic diversity spanning conglomerate, specialist, and regional manufacturing archetypes.
| Leading Market Players |
|---|
| Stryker Corporation |
| De Soutter Medical |
| Smith & Nephew plc |
| Essity Aktiebolag |
| OSCIMED SA |
| Hanshin Medical Co., Ltd. |
| Prime Medical Inc. |
| Shanghai Bojin Medical Instrument Co., Ltd. |
| HEBUmedical GmbH |
| Others |
Value Chain & Pricing Dynamics
Precision motor assemblies from Baden-Württemberg and Bavaria feed through three distinct pricing tiers before reaching hospital purchasing committees, with ISO 13485 certification status determining final contract positioning.
Pricing Analysis
Per-procedure consumable pricing with unbundled service contracts now dominates ambulatory surgical center procurement, replacing capital-heavy ownership models. Price differentiation separates FDA 510(k)-cleared systems with automated thermal controls from basic motorized alternatives lacking sensor integration. Pricing pressure stems from ASC procurement teams demanding modular blade-and-motor configurations that reduce upfront expenditure. Rural clinics exhibit highest price sensitivity, while hospital orthopedic departments in malpractice-exposed markets prioritize safety-engineered equipment regardless of cost premium.
Supply Chain Analysis
ISO 13485 certification gates supplier qualification for large hospital purchasing consortia, filtering component sourcing to established German and Japanese precision manufacturers. Oscillating saw mechanisms draw from Stuttgart industrial corridor fabricators, while compact battery systems source from Nagoya-area machining clusters. Single-source vulnerability concentrates in specialized blade steel and precision motor windings. Distribution runs through orthopedic equipment distributors with dedicated sterile processing support teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory milestones, with EU MDR clinical evidence requirements accelerating consolidation around established ISO 13485-certified manufacturers.
For Market Incumbents: Deploy training program expansion to anchor surgical technician relationships amid workforce shortages in sterile processing departments. Deepen backward integration into blade sterilization technology to capture reprocessing validation margins. Laser cutter convergence threatens oscillating saw dominance in burn unit settings. For New Entrants and Emerging Players: FDA 510(k) clearance pathway in the United States opens a window for electrosurgical cast cutter innovators targeting hospital system procurement. Battery-powered mobility for field hospital deployments represents the most penetrable white space. Pursue per-procedure consumable pricing models to bypass capital budget resistance at ASCs. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier suppliers lack dedicated regulatory affairs teams to absorb EU MDR compliance cost inflation. Acquisition targets include compact powered instrument specialists with proven PMDA or FDA submission track records. Watch for MDR technical documentation deadline extensions as inflection indicators for European vendor list consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates US hospital system commercialization timelines for electrosurgical innovators. |
| EU MDR Certification Pathway | Early clinical evidence compliance creates preferential access to German and French purchasing consortia vendor lists. |
| Hospital System Partnership | Bundled cast removal tools with trauma fixation systems mirror Stryker's orthopedic ecosystem integration strategy. |
| Software Companion Development | Sensor-integrated thermal feedback automation reduces training requirements for surgical technicians across shift changes. |
| Reimbursement Strategy | Outcome-based contracting alignment with ASC per-procedure pricing preferences captures replacement cycle volume. |
Study Parameters
Bottom-up hospital and ambulatory surgical center procurement modeling reconciled against top-down precision component supplier tracking forms the analytical core. Primary interviews with orthopedic department heads, hospital purchasing committee members, GPO contracts managers, and sterile processing directors combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and orthopedic equipment distributor sales data.
Historical trendline analysis of replacement cycle timing and capital budget allocation patterns across the projection horizon informed growth trajectory calibration. Segmentation modeling spanned product type, technology tier, end-user category, and application context with regional regulatory cluster overlays. CAGRs derived from procedure volume expansion rates cross-referenced against equipment penetration saturation curves and sports medicine clinic buildout pipelines.
Revisions become necessary when FDA guidance on reusable device reprocessing shifts materially or EU MDR clinical evidence requirements extend to additional device categories. Forecasts reflect assumptions about sterile processing infrastructure buildout rates and surgical technician certification program expansion. A model refresh is warranted upon material change in ambulatory surgical center volume growth trajectories in Texas and Florida markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Diabetes Devices Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Europe Medical Devices Market
Medical Devices
Mediastinoscope Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Elbow Fixators Market
Medical Devices
Medical Face Shield Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Global Cryotherapy Market
Medical Devices
Muscle Stimulator Market