
 Global Medical Suction Devices Market | 2026-2036
Global Medical Suction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Suction Devices Market Foresight
Modular suction system configurations is realigning buyer choice across acute care settings, as hospitals shift from standalone units toward interoperable platforms that integrate with wall-mounted vacuum infrastructure. Medela AG leverages its Swiss manufacturing base to sustain premium positioning in portable suction for neonatal and wound applications. Drive DeVilbiss Healthcare anchors North American distribution through durable medical equipment channels, while ATMOS MedizinTechnik GmbH & Co. KG competes on precision vacuum regulation for ENT and surgical suites.
Medical suction devices are electromechanical or manually operated systems that generate controlled negative pressure, typically between 80 and 550 mmHg, to evacuate fluids, secretions, or debris from patient airways, surgical sites, or wounds during clinical procedures. These systems employ rotary vane pumps, diaphragm mechanisms, or Venturi-based pneumatic drivers to maintain stable flow rates essential for patient safety in operating theaters and emergency response. Portable suction units lead volume demand due to their deployment flexibility across ambulatory surgical centers and emergency medical services fleets, while vacuum regulators capture concentrated margin pools in hospital retrofit projects. Battery-operated suction machines represent the fastest-growing product configuration, driven by field triage protocols and disaster preparedness mandates that require device mobility beyond fixed electrical supply.
The FDA governs Class II suction device clearances through 510(k) substantial equivalence reviews, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable suction accessories and sterilization validation. ISO 10079 establishes international performance benchmarks for suction source and collection system safety, directly shaping product design cycles for manufacturers seeking multi-jurisdiction market access. Stakeholders must monitor evolving MDR technical documentation deadlines and FDA digital health pre-certification pilots that could accelerate software-integrated suction platforms.
Market Dynamics
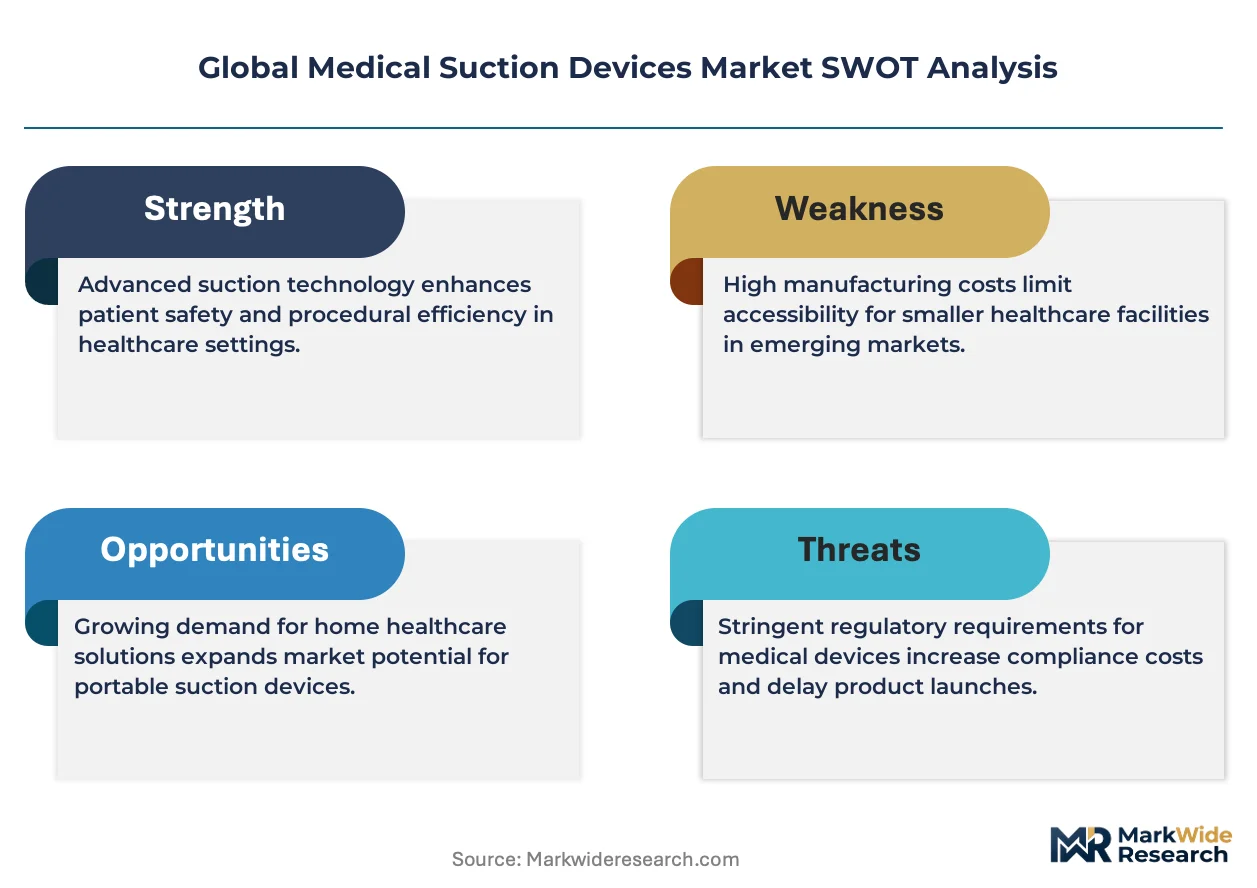
Modular suction architecture is consolidating previously fragmented procurement decisions, as hospital engineering departments prioritize vacuum infrastructure that integrates across OR suites, emergency bays, and ambulatory units rather than purchasing standalone devices.
Growth Catalysts
- Emergency preparedness mandates:Disaster response protocols in the United States now require battery-operated suction capacity in every mobile medical unit, forcing municipal health departments to expand fleet procurement beyond traditional hospital settings.
- ISO 10079 harmonization:The international standard's updated performance benchmarks for suction source safety are enabling manufacturers to design single platforms for multi-jurisdiction clearance, compressing time-to-market for pneumatic and electric systems.
- Trauma center expansions:India's Ministry of Health is funding tier-two and tier-three city hospital upgrades that specify electric suction systems in every emergency bay, creating concentrated demand clusters outside metropolitan cores.
Market Restraints
- Stainless steel and medical-grade polymer input costs:Volatility in nickel pricing and specialized polymer feedstocks is compressing margin structures for reusable suction canister manufacturers operating on fixed hospital supply contracts.
- EU MDR clinical evidence requirements:The Medical Device Regulation's stricter documentation demands for sterilization validation of reusable suction accessories are extending clearance timelines and raising compliance costs for European market entry.
- Single-use disposable substitution:Closed-system suction liners and disposable collection canisters are displacing traditional reusable components in infection-sensitive settings, threatening aftermarket revenue streams for established equipment suppliers.
Strategic Opportunities
- Software-integrated suction platforms:FDA digital health pre-certification pilots are creating pathways for devices that log vacuum pressure, flow duration, and maintenance cycles, enabling predictive service models and usage-based contracting.
- Neonatal and wound care specialization:Precision vacuum regulation below 100 mmHg for fragile tissue applications represents an underdeveloped segment where Swiss and German engineering standards command premium positioning.
- Durable medical equipment channel expansion:Home healthcare reimbursement codes in the United States are expanding coverage for portable suction units, opening patient-direct distribution outside institutional procurement.
Industry Challenges
- Biomedical engineering talent scarcity:Hospital in-house technical staff capable of maintaining integrated wall-vacuum systems and troubleshooting electromechanical pump failures are concentrated in tertiary centers, leaving secondary facilities dependent on manufacturer service contracts.
- Legacy infrastructure interoperability:Retrofitting modular suction platforms into aging hospital vacuum pipe networks requires custom adapter fabrication and pressure-balancing engineering that extends installation timelines and complicates project budgeting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Suction Devices Market |
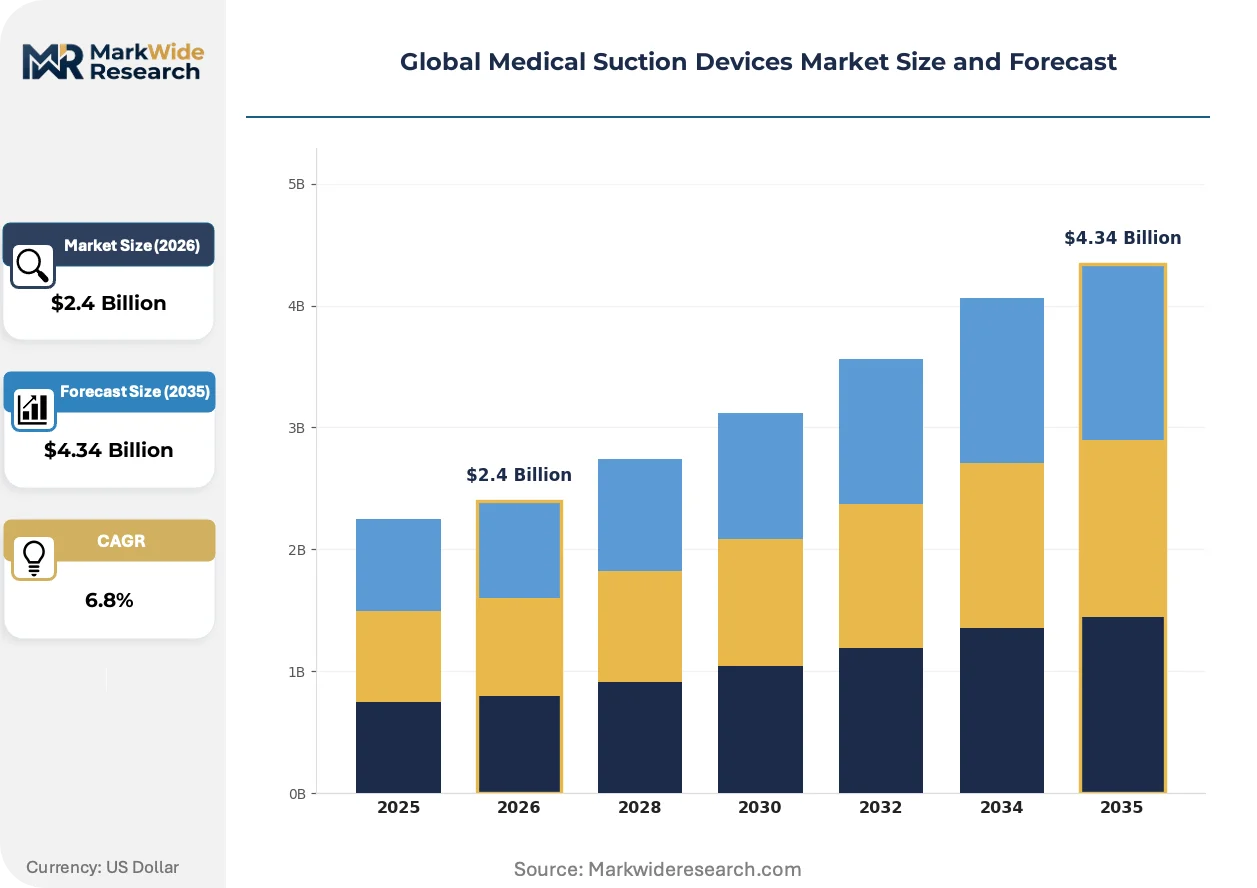
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Suction Units, Stationary Suction Devices, Battery-operated Suction Machines, Vacuum Regulators Application: Surgical Procedures, Emergency Care, Respiratory Therapies, Dental Treatments, Wound Management End User: Hospitals, Ambulatory Surgical Centers, Emergency Medical Services, Dental Clinics, Home Care Providers Technology: Electric Suction, Manual Suction, Pneumatic Suction, Hydrodynamic Suction |
| Companies Covered | Medela AG, Precision Medical, Inc., ZOLL Medical Corporation, Drive DeVilbiss Healthcare, Olympus Corporation, Allied Healthcare Products, Inc., ATMOS MedizinTechnik GmbH & Co. KG, Laerdal Medical, Amsino International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Suction Devices Market Shifts & Advancements
Battery-operated suction systems are expanding their addressable market beyond traditional emergency medical services into surgical subspecialties and home care, while regulatory frameworks on both sides of the Atlantic are accelerating clearance pathway divergence that shapes competitive positioning.
Brushless DC motor technology is expanding into portable suction unit designs, replacing older brushed motor architectures with sealed, maintenance-free drive systems that sustain consistent negative pressure across battery discharge curves. Ambulatory surgical centers in Germany and the United States are specifying these platforms for outpatient procedures requiring reliable aspiration without wall vacuum dependency. The technology is expanding into product categories previously dominated by pneumatic drivers, compressing the addressable market for compressed-gas-dependent systems in mobile applications.
The FDA's updated 510(k) substantial equivalence framework for Class II respiratory devices is streamlining clearance pathways for manufacturers with established predicate devices, while simultaneously tightening cybersecurity documentation requirements for software-integrated platforms. Pneumatic and battery-operated suction systems with digital logging capabilities face expanded premarket submission burdens that favor larger manufacturers with regulatory affairs infrastructure. Startups and mid-cap specialists are responding by partnering with FDA consulting firms to navigate digital health pilot programs rather than pursuing traditional clearance routes.
Hospital procurement departments are consolidating suction device purchasing into centralized capital equipment committees that evaluate total cost of ownership across installation, maintenance, and consumable streams rather than prioritizing acquisition price. Group purchasing organizations in the United States are negotiating multi-year sole-source agreements for integrated wall-vacuum and portable platforms, displacing the previous model of department-level discretionary purchasing. This concentration is most visible in Southeast Asian hospital systems undergoing privatization, where new ownership structures import centralized supply chain discipline from multinational healthcare operators.
Global Medical Suction Devices Market Segmentation
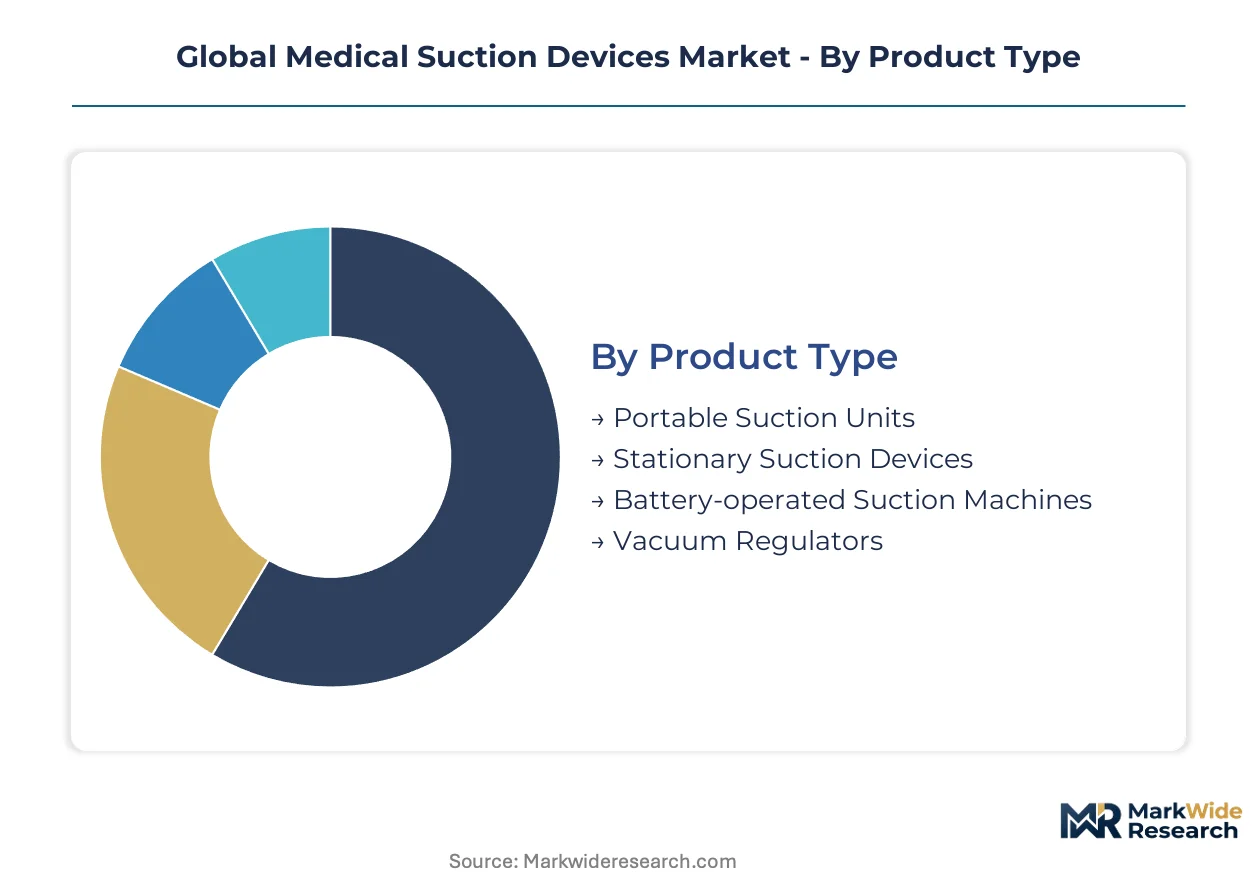
Medical suction device procurement divides sharply between fixed infrastructure investments and mobile platform acquisitions, with each segment carrying distinct regulatory burdens and service revenue profiles. Hospital engineering departments evaluate these categories against total cost-of-ownership models that weigh installation complexity against clinical flexibility.
Product Type:
Supply concentration for electromechanical pump assemblies favors manufacturers with in-house motor winding and vacuum chamber fabrication capabilities, compressing margins for assemblers dependent on outsourced drive components.
- Portable Suction Units:Battery-integrated platforms with rotary vane or diaphragm pumps generate negative pressure between 80-550 mmHg for field deployment. Demand concentrates in United States municipal emergency fleets responding to federal disaster preparedness mandates requiring mobile aspiration capacity in every medical unit.
- Stationary Suction Devices:Wall-mounted vacuum systems with centralized pump houses serve operating theaters and intensive care bays through fixed pipe networks. India's tier-two and tier-three hospital upgrades under Ministry of Health trauma center expansions are accelerating procurement of these integrated platforms.
- Battery-operated Suction Machines:Lithium-ion powered units with brushless DC motor architecture are displacing pneumatic alternatives in ambulatory settings.
- Vacuum Regulators:Precision control valves for wall-mounted infrastructure capture concentrated margins in hospital retrofit projects.
Stationary suction devices absorb the bulk of installed capacity; battery-operated suction machines are expanding most quickly.
Application:
Reimbursement coding variations across clinical settings create sharp price tiering, with inpatient surgical procedures commanding premium pricing against outpatient or emergency applications.
- Surgical Procedures:Operating theater suction systems require sustained high-flow aspiration for fluid and debris evacuation during open and minimally invasive interventions. German and Swiss hospital systems prioritize precision vacuum regulation below 100 mmHg for tissue-sensitive subspecialties.
- Emergency Care:Rapid-deployment suction for airway clearance in trauma bays and pre-hospital settings demands battery reliability across temperature extremes. Southeast Asian privatized hospital chains are standardizing portable unit specifications across emergency bay networks.
- Respiratory Therapies:Secretion clearance for ventilated patients requires closed-system configurations with bacterial filtration.
- Dental Treatments:Compact suction for oral evacuation operates at lower pressure ranges with high-frequency cycling.
- Wound Management:Negative pressure wound therapy systems represent a specialized suction application with distinct regulatory pathways.
Surgical procedures account for the dominant share of suction device revenue; emergency care is climbing the fastest as disaster preparedness protocols expand beyond traditional hospital settings.
End User:
Procurement authority concentration varies dramatically by setting, with hospital group purchasing organizations wielding pricing leverage that fragmented dental and home care channels cannot replicate.
- Hospitals:Tertiary centers with in-house biomedical engineering staff maintain integrated wall-vacuum infrastructure across OR suites, ICUs, and emergency departments. United States health systems are consolidating suction device purchasing into centralized capital equipment committees evaluating multi-year total cost of ownership.
- Ambulatory Surgical Centers:Outpatient facilities in Germany and the United States specify brushless DC portable units to avoid wall vacuum dependency for shorter procedures.
- Emergency Medical Services:Municipal and private ambulance fleets require ruggedized battery systems with rapid recharge protocols.
- Dental Clinics:Smaller practice settings prioritize compact footprint and low noise emission over maximum flow capacity.
- Home Care Providers:United States reimbursement code expansions for durable medical equipment are opening patient-direct distribution channels outside institutional procurement.
Hospitals retain the largest installed base; home care providers are gaining share fastest as reimbursement frameworks adapt to post-acute care migration.
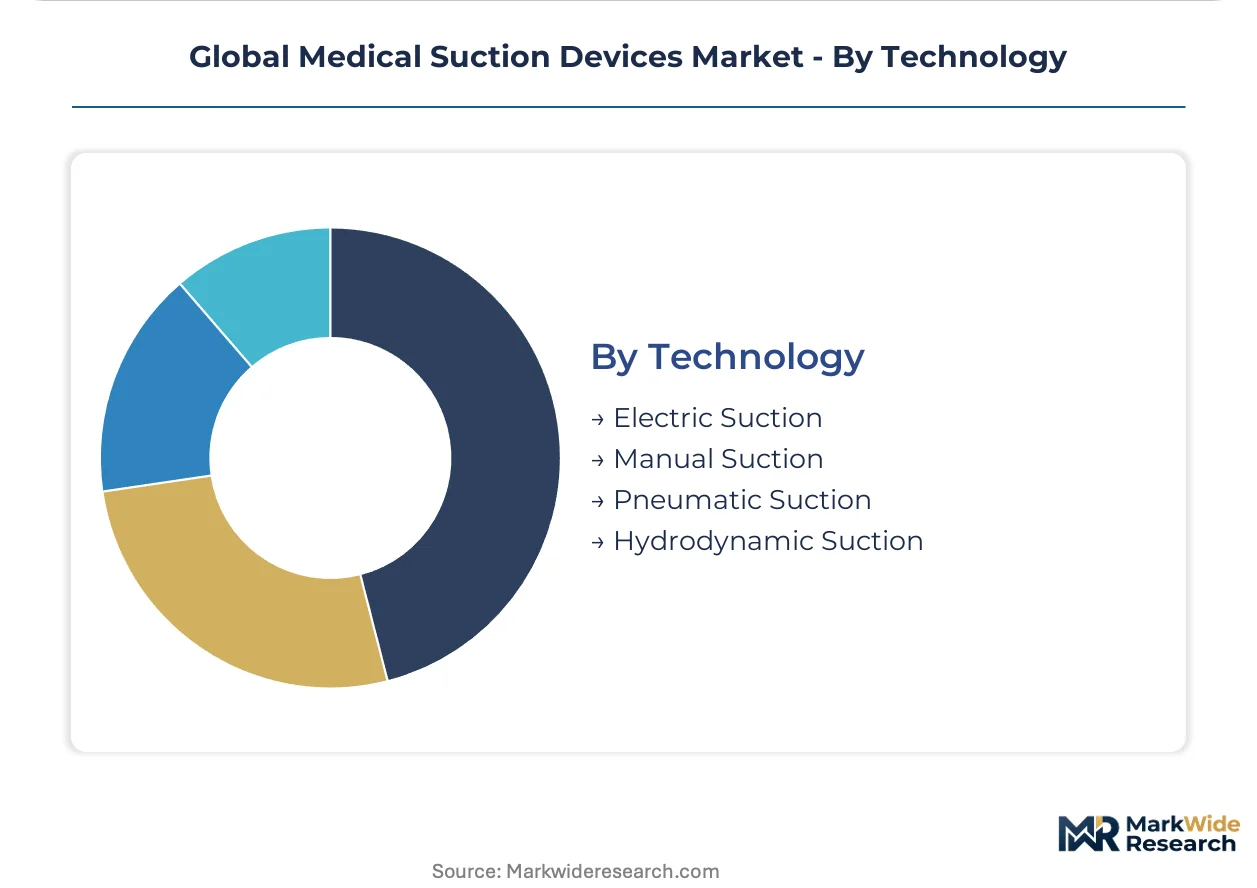
Technology:
Manufacturing process maturity for electric drive systems has compressed cost structures relative to pneumatic alternatives, though compressed gas systems retain niche advantages in explosive atmosphere or extreme field conditions.
- Electric Suction:Rotary vane and diaphragm pump architectures dominate clinical settings with reliable electrical supply, offering precise pressure control and maintenance-free operation over extended service intervals.
- Manual Suction:Hand-powered aspirators serve resource-constrained environments and backup scenarios where power availability cannot be guaranteed.
- Pneumatic Suction:Venturi-based systems driven by compressed gas or oxygen remain essential for hyperbaric and explosive atmosphere applications despite contracting mobile market share.
- Hydrodynamic Suction:Water-jet driven aspiration systems occupy specialized surgical niches requiring simultaneous irrigation and evacuation.
Electric suction commands the predominant technology share; pneumatic suction is experiencing steepest share erosion as battery platforms capture mobile applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of medical suction devices clusters in Switzerland, Germany, and the United States, while consumption growth concentrates in India's tier-two cities and Southeast Asian trauma centers. Supply chains bridge these zones through component sourcing in East Asia and final assembly in regulated jurisdictions.
United States
Federal disaster preparedness mandates require battery-operated suction capacity in every mobile medical unit, driving municipal fleet procurement beyond hospital settings. FDA's 510(k) substantial equivalence framework streamlines clearance for established predicate devices while tightening cybersecurity documentation for software-integrated platforms. Texas and Florida health systems anchor demand through centralized capital equipment committees evaluating multi-year total cost of ownership.
Germany
Ambulatory surgical centers specify brushless DC portable units to avoid wall vacuum dependency for outpatient procedures. EU MDR clinical evidence requirements for sterilization validation extend clearance timelines for reusable suction accessories. Bavarian and Baden-Württemberg hospital networks prioritize precision vacuum regulation below 100 mmHg for tissue-sensitive surgical subspecialties.
India
Ministry of Health trauma center expansions fund electric suction system deployment across tier-two and tier-three city emergency bays. CDSCO regulates device imports through licensing requirements that favor manufacturers with ISO 10079 certification. Maharashtra and Gujarat hospital upgrades concentrate procurement decisions in newly privatized health systems importing centralized supply chain discipline.
Switzerland
Swissmedic maintains stringent quality benchmarks that reinforce premium positioning for precision-engineered portable suction platforms. Domestic manufacturers leverage ISO 10079 harmonization to design single platforms for multi-jurisdiction clearance. Zurich and Basel industrial clusters sustain specialized production of neonatal and wound care suction systems commanding price premiums.
China
NMPA's updated medical device classification rules are compressing registration timelines for Class II respiratory devices including suction systems. Domestic manufacturers expand brushless DC motor production to supply portable unit assemblers serving Southeast Asian export markets. Yangtze River Delta and Pearl River Delta production hubs concentrate electromechanical pump component fabrication.
Global Medical Suction Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with respiratory device portfolios, though specialized suction manufacturers retain defensible positions in precision segments. Three archetypes dominate: integrated hospital infrastructure suppliers, portable device specialists, and precision-engineered niche players. Competitive moves concentrate on modular platform development and regulatory pathway optimization rather than price-based displacement.
Among Swiss and German precision-engineered specialists, Medela AG and ATMOS MedizinTechnik GmbH & Co. KG exemplify the premium-tier archetype anchored by manufacturing standards. Drive DeVilbiss Healthcare represents North American durable medical equipment channel dominance, while Laerdal Medical occupies emergency care positioning. These named entities serve as anchors for understanding how geographic manufacturing bases and regulatory compliance capabilities shape competitive differentiation rather than scale alone.
| Leading Market Players |
|---|
| Medela AG |
| Precision Medical, Inc. |
| ZOLL Medical Corporation |
| Drive DeVilbiss Healthcare |
| Olympus Corporation |
| Allied Healthcare Products, Inc. |
| ATMOS MedizinTechnik GmbH & Co. KG |
| Laerdal Medical |
| Amsino International, Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ISO 10079-compliant precision platforms and non-certified economy units manifests in both pricing power and supply chain sourcing, with Swiss and German manufacturers commanding premium positioning through captive motor production while Asian assemblers compete on component cost arbitrage.
Pricing Analysis
Margin tightening in economy-tier portable units reflects nickel price volatility and fixed-contract hospital procurement, while premium precision regulators sustain pricing power through Swissmedic-validated manufacturing. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and after-sales service bundling, with Indian government tenders showing highest price sensitivity and German ambulatory surgical centers accepting premium positioning for brushless DC reliability.
Supply Chain Analysis
Single-source vulnerability sits with Chinese brushless DC motor production for battery-operated platforms, though Swiss and German manufacturers maintain in-house vacuum chamber fabrication. Electromechanical pump assemblies draw from East Asian component clusters, with final assembly concentrating in regulated jurisdictions to satisfy FDA and EU MDR documentation requirements. Tariff exposure on medical-grade polymers and specialized nickel alloys threatens margin structures for reusable canister manufacturers, while distribution runs through hospital group purchasing organizations in the United States and privatized health system procurement committees in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-operated suction systems with brushless DC architecture are displacing pneumatic alternatives across emergency and ambulatory settings, creating technology-transition investment and competitive repositioning imperatives.
For Market Incumbents: Deepen backward integration into brushless DC motor production to defend margin position against component cost volatility, while accelerating FDA digital health pre-certification pathways for software-integrated platforms that log vacuum pressure and maintenance cycles. Incumbents must consolidate service revenue through predictive maintenance contracts as single-use disposable liners threaten aftermarket streams from reusable accessories.
For New Entrants and Emerging Players: Software-integrated suction platforms with predictive analytics capabilities offer the most penetrable wedge for new entrants, particularly in United States home care channels where reimbursement code expansions are opening patient-direct distribution outside institutional procurement. Target tier-two Indian cities where Ministry of Health trauma center funding concentrates demand for electric suction systems in emergency bays lacking integrated wall-vacuum infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with precision-engineered specialists possessing Swissmedic or EU MDR certification infrastructure given regulatory pathway divergence that favors established compliance capabilities over scale. Long-term viability hinges on software-integrated platform development and service revenue migration. Watch FDA digital health pilot program expansion as inflection signal for accelerated clearance timelines favoring regulatory affairs-capable mid-caps.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates clearance timelines for software-integrated suction platforms with predictive maintenance capabilities. |
| CE Marking Pathway under EU MDR | Enables multi-jurisdiction market access for sterilization-validated reusable suction accessories. |
| Hospital System Partnership | Secures multi-year sole-source agreements with group purchasing organizations evaluating total cost of ownership. |
| Software Companion Development | Creates predictive service revenue through vacuum pressure logging and maintenance cycle analytics. |
| Reimbursement Strategy | Expands durable medical equipment coverage for portable units in United States home care channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across hospital purchasing committees, biomedical engineers, GPO contracts managers, and emergency medical services fleet operators. FDA 510(k) substantial equivalence databases, EU MDR technical documentation filings, CDSCO import licensing records, and ISO 10079 certification registries provided device-level validation. Bottom-up unit shipment estimates triangulated against top-down healthcare expenditure models across the analysis window.
Segment-level granularity modeled product type, application, end user, and technology dimensions with regional production cluster and regulatory framework overlays. CAGRs derived from trend extrapolation of trauma center expansion funding, disaster preparedness mandate implementation, and brushless DC motor cost curves. Hospital procurement database analysis and GPO contract terms informed pricing trajectory assumptions throughout the projection horizon.
Several conditions sit outside the modeled scope, including sudden nickel price spikes exceeding historical volatility bands, EU MDR documentation deadline delays, and NMPA regulatory acceleration beyond current trajectory. Deviation in FDA digital health pre-certification pilot expansion timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Biopsy Punch Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
South Korea ECG Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Implantable Collamer Lens Market
Medical Devices
Artificial Cornea and Corneal Implant Market