
 Brazil Cardiovascular Devices Market | 2026-2036
Brazil Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Cardiovascular Devices Market Outlook
Software-defined monitoring and remote algorithm updates are shifting how cardiovascular device vendors capture recurring revenue. Medtronic leverages its service infrastructure to anchor long-term contracts with large hospital groups. Edwards Lifesciences differentiates through specialized transcatheter valve programs that sustain premium positioning in high-complexity centers. Abbott Laboratories competes on integrated diagnostic-interventional platforms that extend clinical utility beyond implantation.
Brazil cardiovascular devices comprise implantable and interventional instruments—typically fabricated from cobalt-chromium alloys, nitinol, or biocompatible polymers—engineered to restore or maintain cardiac function through mechanical, electrical, or pharmacological means. Drug-eluting stents and transcatheter valves command the dominant share of current revenue, while MRI-compatible pacemakers represent the fastest-expanding technology segment as imaging-integrated workflows become standard. Hospitals absorb the majority of device volume, though cardiology clinics are capturing growing share through ambulatory catheterization expansion.
ANVISA governs pre-market registration and post-market surveillance for all cardiovascular implants, while the Brazilian Ministry of Health's RENAME list determines reimbursement eligibility for public procurement. ANVISA's alignment with International Medical Device Regulators Forum standards is streamlining parallel submissions for multinational manufacturers. Stakeholders must monitor how ANVISA's forthcoming risk-based inspection schedules reshape competitive access timelines for new entrants.
Market Dynamics
Catheterization lab capacity expansion across São Paulo and Minas Gerais public hospital networks is compressing patient wait times and accelerating device procurement cycles for interventional cardiology suites.
Growth Catalysts
- ANVISA registration pathway modernization:Updated Class III implant approval timelines are reducing market entry friction for multinational manufacturers submitting parallel dossiers.
- Southeastern private clinic consolidation:Cardiology chain procurement centralization in São Paulo state is generating volume commitments that justify localized service infrastructure investment.
- MRI-compatible pacemaker technology maturation:Imaging-integrated cardiac workflows are eliminating device-exchange procedures previously required for diagnostic compatibility.
Market Restraints
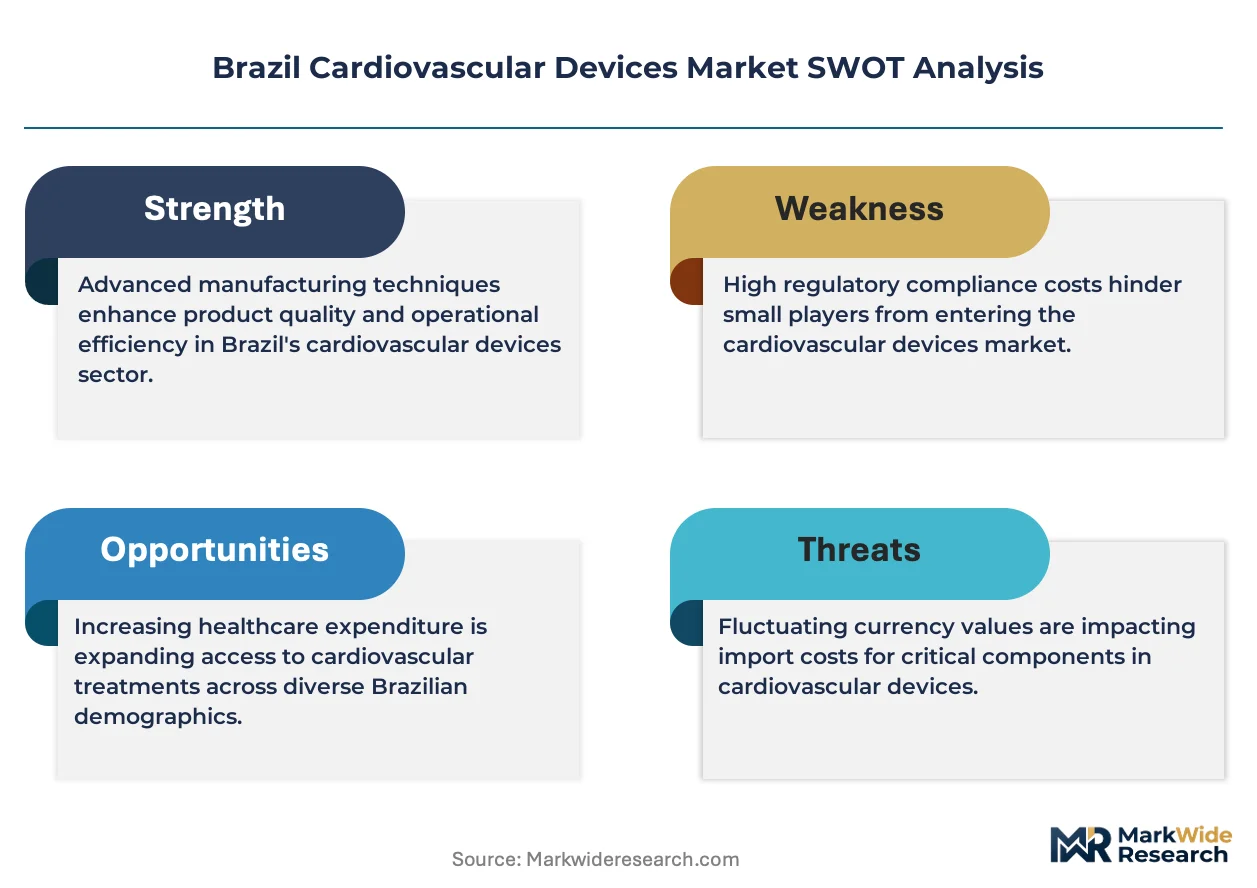
- Cobalt-chromium alloy supply concentration:Raw material sourcing dependence on limited specialty metal processors creates input cost volatility for stent and valve frame fabricators.
- RENAME list reimbursement lag:Brazilian Ministry of Health eligibility determinations for novel transcatheter devices trail ANVISA approval by 18-24 months, delaying public sector adoption.
- Bioresorbable scaffold technical limitation:Restenosis rates and mechanical integrity failures in coronary applications have stalled polymer-based stent platform commercialization.
Strategic Opportunities
- Northeastern Brazil geographic white space:Bahia and Pernambuco states show catheterization lab density at one-third southeastern levels, creating first-mover expansion potential for ambulatory intervention networks.
- Remote algorithm update service models:Software-defined cardiac monitors enable recurring revenue capture through subscription-based rhythm management optimization.
- Diagnostic-interventional platform convergence:Integrated electrophysiology mapping and ablation systems reduce capital footprint requirements for mid-tier hospital cath labs.
Industry Challenges
- Electrophysiologist training pipeline constriction:Fellowship program capacity limitations in Brazilian medical schools restrict complex ablation procedure volume growth despite installed device base expansion.
- Legacy pacemaker explant logistics:Device retrieval and safe disposal requirements for generator replacements impose operational complexity on clinic networks without dedicated reverse supply chain partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Cardiovascular Devices Market |
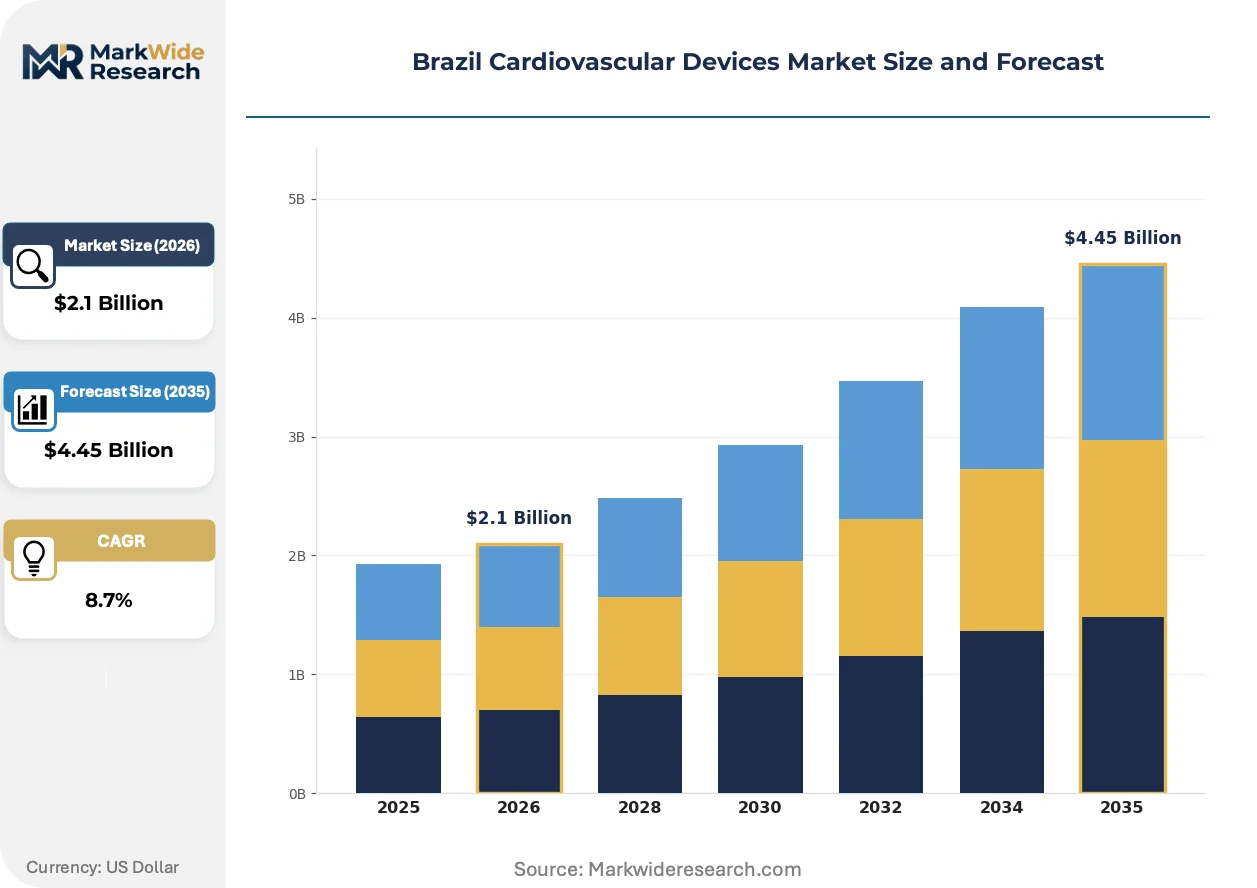
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Valves End User: Hospitals, Cardiology Clinics, Research Institutes, Home Care Delivery Mode: Invasive, Non-invasive, Transcatheter, Surgical Technology: Bio-absorbable, Superelastic, Drug-eluting, MRI-compatible |
| Companies Covered | Cardinal Health Inc, Edwards Lifesciences, Braile Biomedica Ltda, Boston Scientific Corporation, Medtronic, Terumo Corporation, Biotronik SE & Co KG, C R Bard Inc, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Cardiovascular Devices Market Strategic Shifts
Digital connectivity and miniaturization are transforming how cardiovascular devices deliver therapeutic value, shifting revenue models from episodic implant sales toward continuous clinical engagement platforms.
Nitinol shape-memory alloy engineering is rewriting transcatheter valve delivery system design. Self-expanding frame architectures now enable transfemoral placement through 14-French sheaths, expanding treatable patient anatomies previously excluded for vascular access reasons. High-complexity cardiac centers in São Paulo and Rio de Janeiro are adopting these platforms for intermediate-risk surgical candidates, compressing the addressable market for conventional surgical valve replacement.
ANVISA's alignment with International Medical Device Regulators Forum technical documentation standards is streamlining multinational submission strategies. Manufacturers can now leverage FDA and CE-marking dossiers with Brazil-specific clinical addenda rather than duplicative local trials. This regulatory convergence most benefits transcatheter valve programs, where global pivotal trial data satisfies ANVISA evidentiary requirements for Class III implant registration.
Ambulatory catheterization center networks are capturing coronary intervention volume previously concentrated in tertiary hospital settings. Freestanding cardiology clinics in Belo Horizonte and Curitiba now perform diagnostic angiography and elective PCI with same-day discharge protocols, displacing overnight hospital admissions. This channel migration is most pronounced in privately insured populations where cost-conscious health plans incentivize lower-acuity site selection.
Brazil Cardiovascular Devices Market Segmentation
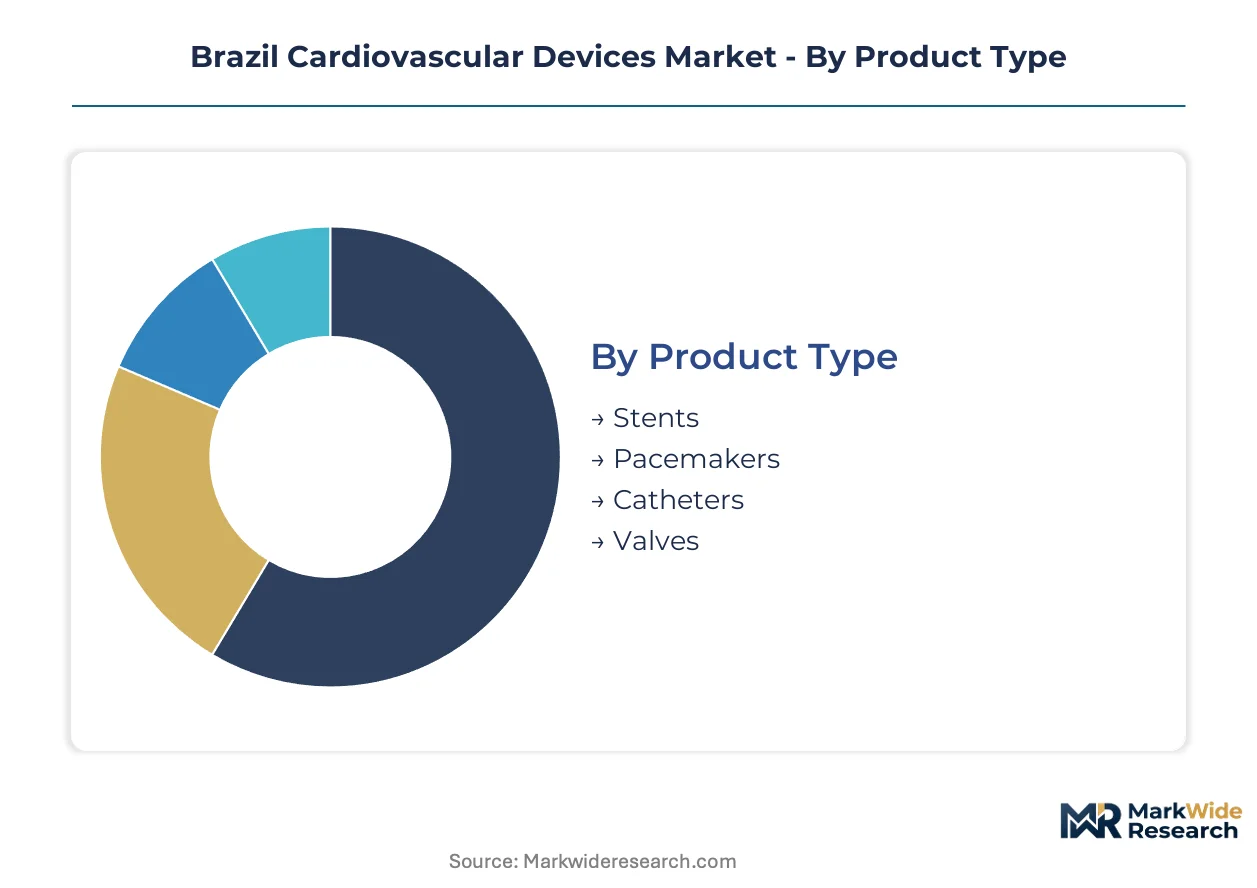
Cardiovascular device procurement in Brazil stratifies sharply between high-volume public hospital tenders and premium private clinic contracts. Understanding these segment boundaries reveals where manufacturers must deploy differentiated service infrastructure versus standardized distribution.
Product Type:
Drug-eluting stents and transcatheter valves absorb the majority of procurement value, while MRI-compatible pacemakers command expanding premium positioning.
- Stents:Fabricated from cobalt-chromium alloys or nitinol, these devices restore coronary patency through mechanical scaffolding. Demand concentrates in São Paulo's catheterization labs, where public hospital networks are expanding intervention capacity. ANVISA's streamlined Class III pathways are accelerating new platform introductions.
- Pacemakers:MRI-compatible generator technology is eliminating exchange procedures previously required for diagnostic imaging compatibility. Private cardiology chains in southeastern Brazil are prioritizing these devices to differentiate ambulatory service offerings.
- Catheters:Diagnostic and interventional delivery systems manufactured from biocompatible polymers.
- Valves:Self-expanding nitinol frames enabling transfemoral placement through reduced sheath sizes.
Mature deployment sits with stents. Newer deployment is concentrated in MRI-compatible pacemakers.
End User:
Hospital procurement centralization contrasts with clinic network fragmentation across Brazil's federated healthcare system.
- Hospitals:Tertiary cardiac centers in São Paulo and Minas Gerais perform complex interventions requiring full surgical backup. These institutions absorb the majority of transcatheter valve volume and dictate technology adoption timelines through fellowship training pipelines.
- Cardiology Clinics:Freestanding ambulatory centers in Belo Horizonte and Curitiba now execute elective PCI with same-day discharge protocols. Consolidating procurement within multi-site chains is generating volume commitments that justify localized technical service investment.
- Research Institutes:Academic medical centers conducting clinical trials for ANVISA registration.
- Home Care:Remote monitoring infrastructure for implantable cardiac devices.
Procedure volume concentrates in hospitals. Fastest expansion is occurring in cardiology clinics.
Delivery Mode:
Access route selection determines capital equipment requirements and reimbursement coding complexity.
- Transcatheter:Minimally invasive valve replacement and repair through femoral or apical access. São Paulo's high-complexity centers are adopting these platforms for intermediate-risk surgical candidates, compressing addressable volume for conventional sternotomy.
- Invasive:Surgical implantation requiring thoracotomy or sternotomy with cardiopulmonary bypass.
- Non-invasive:External cardiac monitoring and diagnostic imaging without device implantation.
- Surgical:Open-chest procedures for valve replacement and complex congenital repair.
Transcatheter approaches are gaining share fastest in valve interventions. Surgical delivery retains dominance in complex redo procedures.
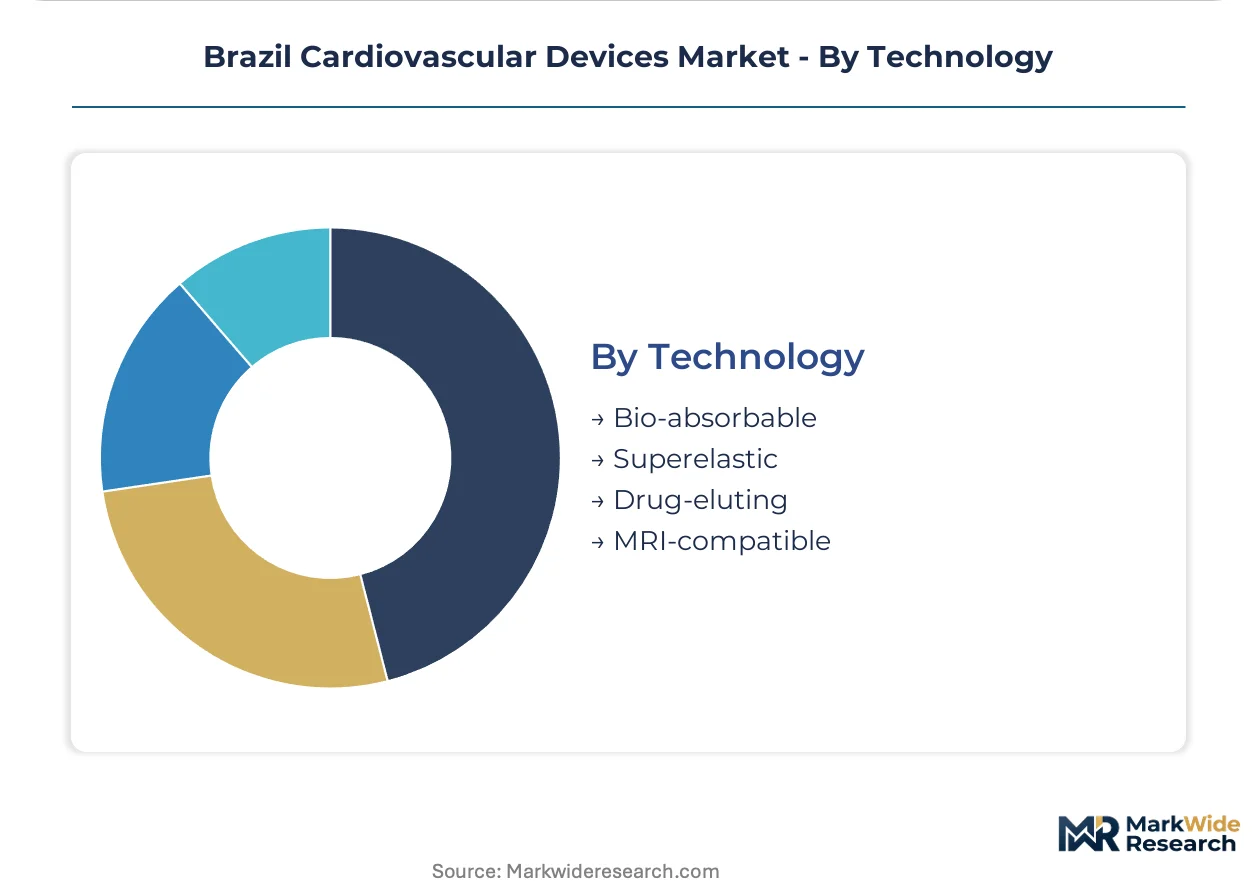
Technology:
Material science differentiation and imaging compatibility are reshaping competitive positioning.
- Drug-eluting:Polymer-based antiproliferative agent delivery reduces restenosis rates in coronary applications. These platforms command dominant revenue share in Brazilian stent markets despite bioresorbable scaffold technical limitations.
- MRI-compatible:Revised generator shielding and lead engineering enable safe magnetic resonance imaging. Imaging-integrated cardiac workflows in southeastern Brazil are making this capability standard for new implants.
- Bio-absorbable:Polymer scaffolds designed for complete vessel resorption.
- Superelastic:Nitinol shape-memory alloys enabling self-expanding device architectures.
Drug-eluting technology represents mature commercial deployment. MRI-compatible platforms are climbing the fastest as diagnostic integration becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's cardiovascular device production concentrates in southeastern industrial corridors, while consumption spreads across federated healthcare networks with pronounced regional disparities in cath lab density and reimbursement access.
São Paulo
São Paulo state's public hospital networks are expanding catheterization lab capacity at tertiary centers in the capital and Campinas corridor. ANVISA's streamlined Class III implant pathways accelerate device registration for manufacturers targeting these procurement tenders. The São Paulo metropolitan cluster absorbs the majority of transcatheter valve volume and anchors fellowship training pipelines that dictate national technology adoption timelines.
Minas Gerais
Minas Gerais public health authorities are compressing intervention wait times through Belo Horizonte cath lab network expansion. The state's alignment with federal RENAME reimbursement protocols determines which novel devices enter public sector formularies. Industrial device distribution hubs in Contagem supply southeastern clinic chains consolidating procurement across multi-site cardiology networks.
Rio de Janeiro
Rio de Janeiro's high-complexity cardiac centers are adopting self-expanding nitinol valve platforms for intermediate-risk surgical candidates. State-level health secretariat contracting practices influence device selection criteria for publicly insured populations. The Rio metropolitan corridor maintains specialized congenital repair capacity that sustains demand for surgical valve delivery systems alongside transcatheter alternatives.
Rio Grande do Sul
Rio Grande do Sul's aging demographic profile drives pacemaker generator replacement volume through Porto Alegre cardiology networks. State procurement consortiums aggregate demand across smaller municipalities to negotiate volume discounts with multinational manufacturers. The southern region's private insurance penetration exceeds national averages, accelerating MRI-compatible device adoption in ambulatory settings.
Bahia
Bahia exhibits catheterization lab density at one-third southeastern levels, creating geographic white space for ambulatory intervention network expansion. Federal Ministry of Health infrastructure investments are targeting Salvador and Feira de Santana for cath lab capacity additions. Northeastern demand concentration in these urban centers is attracting distributor partnerships from manufacturers seeking first-mover positioning outside the saturated southeast.
Brazil Cardiovascular Devices Market Competitive Environment
Top-tier vendors anchor premium transcatheter and electrophysiology segments, while mid-scale fabricators compete on stent platform cost positioning and regional service proximity. The vendor base stratifies across three functional tiers: integrated multinationals with full cardiac portfolios, specialized valve or rhythm management pure-plays, and domestic assemblers leveraging import substitution policies. Dominant competitive moves include cath lab service infrastructure localization and algorithm-enabled remote monitoring subscription models that convert implant sales into recurring revenue streams.
Within the multinational tier, Medtronic and Edwards Lifesciences occupy positions exemplifying divergent strategic archetypes—service-anchored long-term contracting versus premium high-complexity center specialization. Abbott Laboratories represents the integrated diagnostic-interventional platform approach. Among Brazil-based participants, Braile Biomedica Ltda anchors domestic manufacturing capabilities that benefit from ANVISA registration pathway familiarity and public procurement preference frameworks for locally produced devices.
| Leading Market Players |
|---|
| Cardinal Health Inc |
| Edwards Lifesciences |
| Braile Biomedica Ltda |
| Boston Scientific Corporation |
| Medtronic |
| Terumo Corporation |
| Biotronik SE & Co KG |
| C R Bard Inc |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
ANVISA's updated Good Manufacturing Practice certification requirements for Class III implant facilities gate qualified supply access and premium-tier pricing eligibility for multinational cardiovascular device manufacturers seeking Brazilian market entry. Cobalt-chromium alloy sourcing constraints and nitinol shape-memory supply concentration amplify input cost volatility, compressing margins for stent and valve fabricators while rewarding vendors with backward-integrated metal processing capabilities.
Pricing Analysis
Price erosion across standard-tier drug-eluting stents traces to consolidating procurement by São Paulo cardiology clinic chains extracting volume discounts through multi-year commitments. Three-tier pricing structure across premium MRI-compatible pacemakers, standard bare-metal platforms, and economy reimported devices reflects ANVISA registration tier and localized service bundling differentiation. Cost-down pressure on interventional catheters accelerates because Belo Horizonte ambulatory centers prioritize disposable cost-per-procedure over device longevity. Public hospital tenders exhibit highest price sensitivity; private high-complexity cardiac centers in Rio de Janeiro tolerate premium positioning for transcatheter valve programs with embedded technical training.
Supply Chain Analysis
ANVISA's domestic-content preference frameworks for public procurement are reshaping sourcing toward Brazilian assemblers like Braile Biomedica, though critical nitinol wire and cobalt-chromium tubing still draw from USA, Germany, and Japan specialty metal processors. Polymer catheter shaft materials and drug-eluting polymer matrices rest on pharmaceutical-grade resin supply from Switzerland and Netherlands chemical specialists. Single-source vulnerability concentrates in nitinol shape-memory alloy melting capacity, where three global processors dominate cardiac-grade material output. Distribution runs through Contagem industrial hubs supplying southeastern clinic networks, with northeastern expansion requiring new logistics partnerships given Bahia's infrastructure gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's cardiovascular device market operates as a supply-constrained environment where electrophysiologist training pipeline bottlenecks prop pricing power for complex ablation platforms despite stent commoditization.
For Market Incumbents: Anticipate margin compression in coronary stents by anchoring long-term contracts with São Paulo public hospital networks through catheterization lab service infrastructure localization. Defend transcatheter valve premium positioning by embedding specialized training programs within Rio de Janeiro high-complexity centers, creating switching costs that emerging nitinol platform competitors cannot replicate overnight. For New Entrants and Emerging Players: The premium-to-economy price gap in MRI-compatible pacemakers offers white-space entry for mid-tier manufacturers willing to absorb ANVISA registration timeline uncertainty. Northeastern Brazil's catheterization lab density deficit—one-third of southeastern levels—represents the most penetrable geographic expansion target for ambulatory intervention networks. Pursue distributor partnerships with Salvador-based cardiology groups before established vendors consolidate first-mover positioning. For Investors and Strategic Acquirers: ANVISA's alignment with International Medical Device Regulators Forum standards is the leading indicator that Brazilian registration data will gain reciprocal recognition value for global portfolio acceleration. Five-to-ten year viability favors specialized valve or rhythm management pure-plays with proprietary nitinol engineering capabilities over diversified commodity stent manufacturers facing pricing pressure. Monitor RENAME list reimbursement additions as the critical inflection signal for public sector volume accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Class III Registration Pathway | Accelerated approval timelines compress competitive entry barriers for multinational manufacturers submitting parallel FDA dossiers. |
| Hospital System Partnership | São Paulo public network cath lab expansion creates captive demand channels for interventional device vendors with localized technical service. |
| Software Companion Development | Remote algorithm update capabilities for cardiac monitors convert implant sales into recurring subscription revenue streams. |
| Reimbursement Strategy | RENAME list eligibility determination alignment with ANVISA approval reduces public sector adoption lag for novel transcatheter devices. |
| Geographic Expansion | Northeastern Brazil infrastructure investments in Bahia and Pernambuco enable first-mover positioning outside saturated southeastern markets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cardiovascular device market assessment, supplemented by structured primary interviews with cath lab directors, biomedical engineers, ANVISA regulatory affairs specialists, and GPO contracts managers at major Brazilian hospital systems. ANVISA registration databases, Brazilian Ministry of Health RENAME procurement records, and import-export statistics from the Secretariat of Foreign Trade provided volume and value triangulation points. Bottom-up device shipment modeling and top-down healthcare expenditure allocation were cross-validated to reconcile procurement flow estimates.
Granularity-level modeling captured product type splits across stents, pacemakers, catheters, and valves; end-user segmentation between tertiary hospitals and ambulatory cardiology clinics; and technology tiers distinguishing drug-eluting from bare-metal and MRI-compatible from conventional platforms. CAGRs across the projection horizon were derived from installed base expansion rates, procedure volume growth assumptions tied to cath lab capacity additions, and replacement cycle dynamics for generator and lead systems. Forecast inputs incorporated ANVISA approval pipeline visibility and RENAME reimbursement timeline assumptions.
Underlying measurement precision varies by segment; drug-eluting stent and transcatheter valve volume estimates carry tighter precision given public procurement transparency, while emerging MRI-compatible pacemaker adoption trajectories reflect greater uncertainty pending reimbursement confirmation. Forecasts reflect documented assumptions regarding cath lab buildout schedules, electrophysiologist training pipeline expansion, and nitinol supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Global Valvular Heart Disease Treatment Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market