
 Cardiac Resynchronization Therapy (CRT) Devices Market | 2026-2036
Cardiac Resynchronization Therapy (CRT) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Resynchronization Therapy (CRT) Devices Market Analysis
Modular device packaging is shifting buyer choice in the CRT devices landscape, as hospitals increasingly favor bundled solutions that combine generators, leads, and remote monitoring subscriptions over standalone component procurement. Medtronic plc leverages its integrated ecosystem to anchor premium positioning across implantable device and monitoring system categories. Abbott Laboratories differentiates through bi-ventricular pacing technology leadership, while Boston Scientific Corporation competes on manufacturing scale and electrophysiology lab channel control.
Cardiac Resynchronization Therapy (CRT) Devices are implantable or external systems that deliver timed electrical impulses to resynchronize ventricular contraction in heart failure patients, typically operating at 3-5 V output with pulse widths of 0.3-1.5 ms and incorporating adaptive algorithms that adjust pacing parameters based on real-time hemodynamic feedback. The primary commercial purpose is reducing hospitalization rates and mortality in patients with reduced ejection fraction and conduction abnormalities. Implantable Devices occupy the dominant margin pool given their recurring lead replacement cycles and generator upgrade pathways, while Remote Monitoring within the Delivery Mode dimension represents the fastest-growing structural segment as reimbursement codes mature for cloud-connected follow-up protocols.
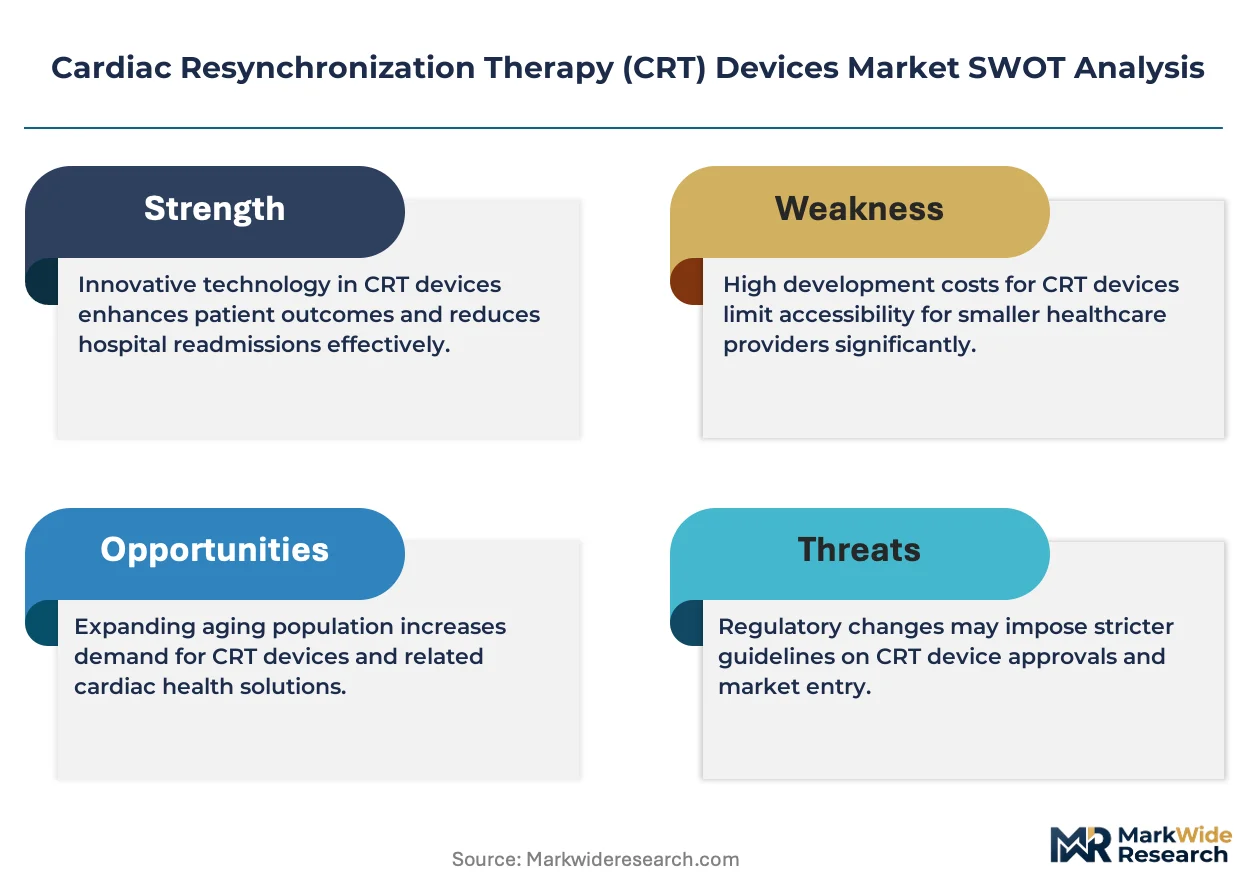
FDA premarket approval requirements and the EU MDR clinical evaluation standards are elevating barriers for new CRT device entrants while reinforcing incumbent data advantages. Japan's PMDA and China's NMPA maintain distinct testing protocols that shape regional product registration timelines and localization investments. Stakeholders must monitor adaptive algorithm regulatory classifications and evolving cybersecurity standards for networked cardiac implants as payers weigh outcomes-based contracting against traditional fee-for-service reimbursement.
Market Dynamics
Adaptive algorithm regulatory classifications and tightening cybersecurity mandates for networked cardiac implants are restructuring competitive positioning in the CRT devices market, as incumbents leverage accumulated clinical data assets while new entrants face elevated evidence thresholds.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced clinical evaluation requirements reinforce data advantages for established manufacturers with extensive patient registries, consolidating procurement decisions around proven systems.
- Electrophysiology lab expansion:Hospital systems in Germany, Japan, and the United States are building dedicated cardiac rhythm management infrastructure to accommodate procedural volume growth.
- Cloud-connected follow-up protocols:Reimbursement code maturation for remote monitoring is accelerating patient adherence and reducing clinical resource burden.
Market Restraints
- Lead replacement cycle economics:Generator longevity improvements are extending replacement intervals, compressing recurring revenue streams from implantable device portfolios.
- Supply concentration in semiconductor substrates:Critical pacing circuitry depends on specialized foundry capacity concentrated in East Asian manufacturing clusters.
- Bi-ventricular capture thresholds:Anatomical variability in coronary sinus anatomy limits lead placement success rates in specific patient phenotypes.
Strategic Opportunities
- Underpenetrated heart failure cohorts in China:NMPA pathway streamlining and domestic manufacturing incentives are opening procedural access beyond tier-one hospital networks.
- Convergence of CRT with subcutaneous ICD platforms:Combined device architectures reduce implant complexity and procedural site infection risk.
- Japan's PMDA adaptive approval frameworks:Real-world evidence collection protocols enable faster algorithm updates for AI-driven pacing optimization.
Industry Challenges
- Electrophysiologist training pipeline:Procedural complexity and fellowship duration constraints limit qualified implanter availability relative to addressable patient volumes.
- Legacy system interoperability:Hospital IT infrastructure fragmentation complicates seamless integration of cloud-based monitoring platforms with existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Resynchronization Therapy (CRT) Devices Market |
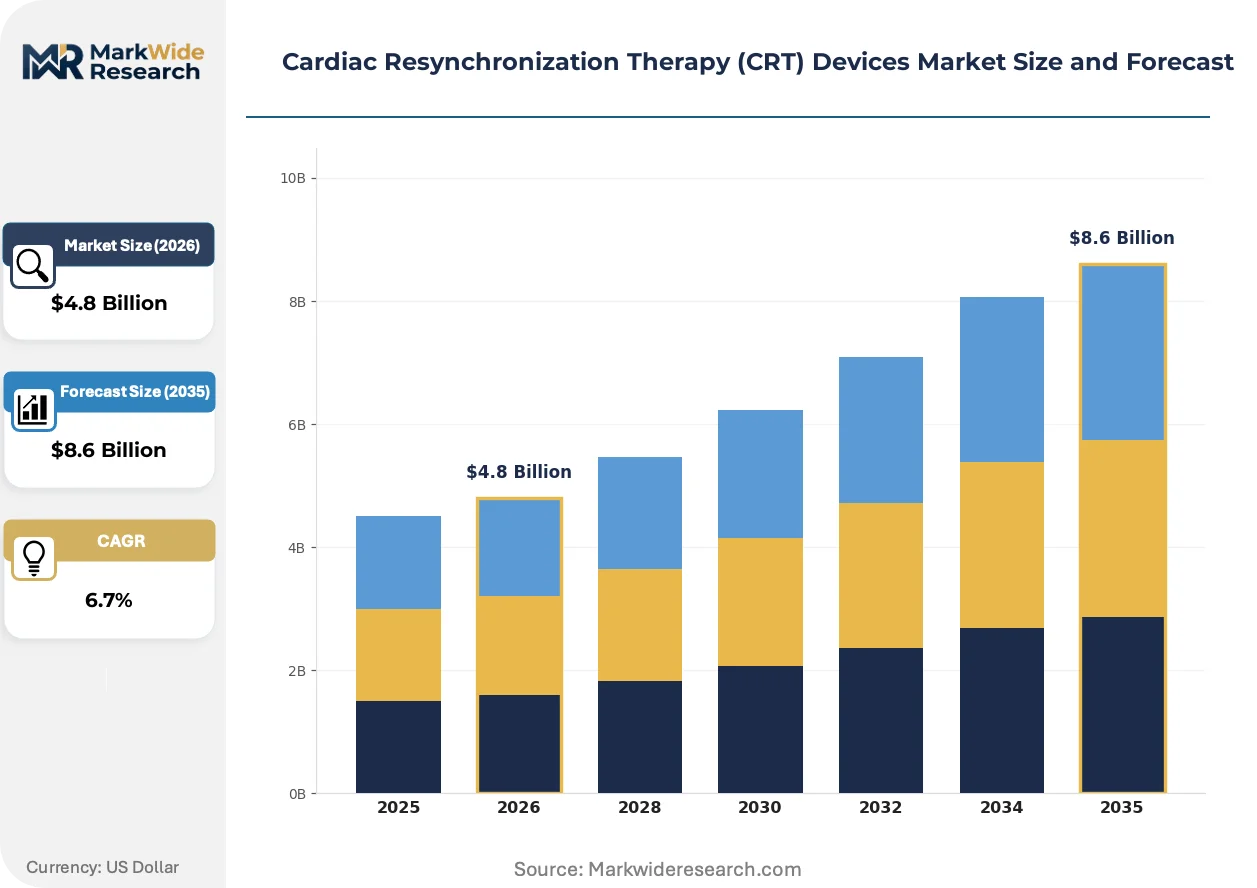
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, External Devices, Accessory Solutions, Monitoring Systems Technology: Electrical Stimulation, Bi-Ventricular Pacing, Adaptive Algorithms, Network Connectivity Delivery Mode: Invasive Procedures, Outpatient Care, Remote Monitoring, Rehabilitation Services End User: Cardiology Clinics, Hospitals, Outpatient Facilities, Specialized Treatment Centers |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, BIOTRONIK SE & Co. KG, MicroPort Scientific Corporation, LivaNova PLC, Medico S.p.A., Lepu Medical, OSCOR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Resynchronization Therapy (CRT) Devices Market Emerging Trajectories
Algorithmic personalization and networked device ecosystems are displacing standardized pacing protocols, while reimbursement structures evolve to capture longitudinal outcomes rather than discrete procedural events.
Multipoint pacing technology is converging with automated vector selection algorithms to optimize electrical synchrony in non-responder populations. Academic electrophysiology centers in the United States and Germany are adopting these configurations for refractory heart failure cases. The technology is converging with hemodynamic sensor inputs to enable closed-loop adjustment of pacing parameters, compressing the gap between implant and optimal therapy delivery.
FDA's evolving cybersecurity guidance for networked medical devices mandates premarket submission of software bill of materials and vulnerability management protocols. Device manufacturers must demonstrate continuous monitoring capabilities and patch deployment infrastructure across installed bases. Implantable device portfolios face the most intensive scrutiny, with PMA supplement requirements extending approval timelines for algorithm updates.
Hospital purchasing committees are consolidating vendor relationships around integrated generator-lead-monitoring bundles, displacing component-level procurement. Integrated delivery networks in the United States are negotiating multi-year service agreements that cap total cost of ownership across device lifecycle. Germany's hospital procurement cooperatives are most advanced in this transition, with outcome guarantees embedded in contractual frameworks.
Cardiac Resynchronization Therapy (CRT) Devices Market Segmentation
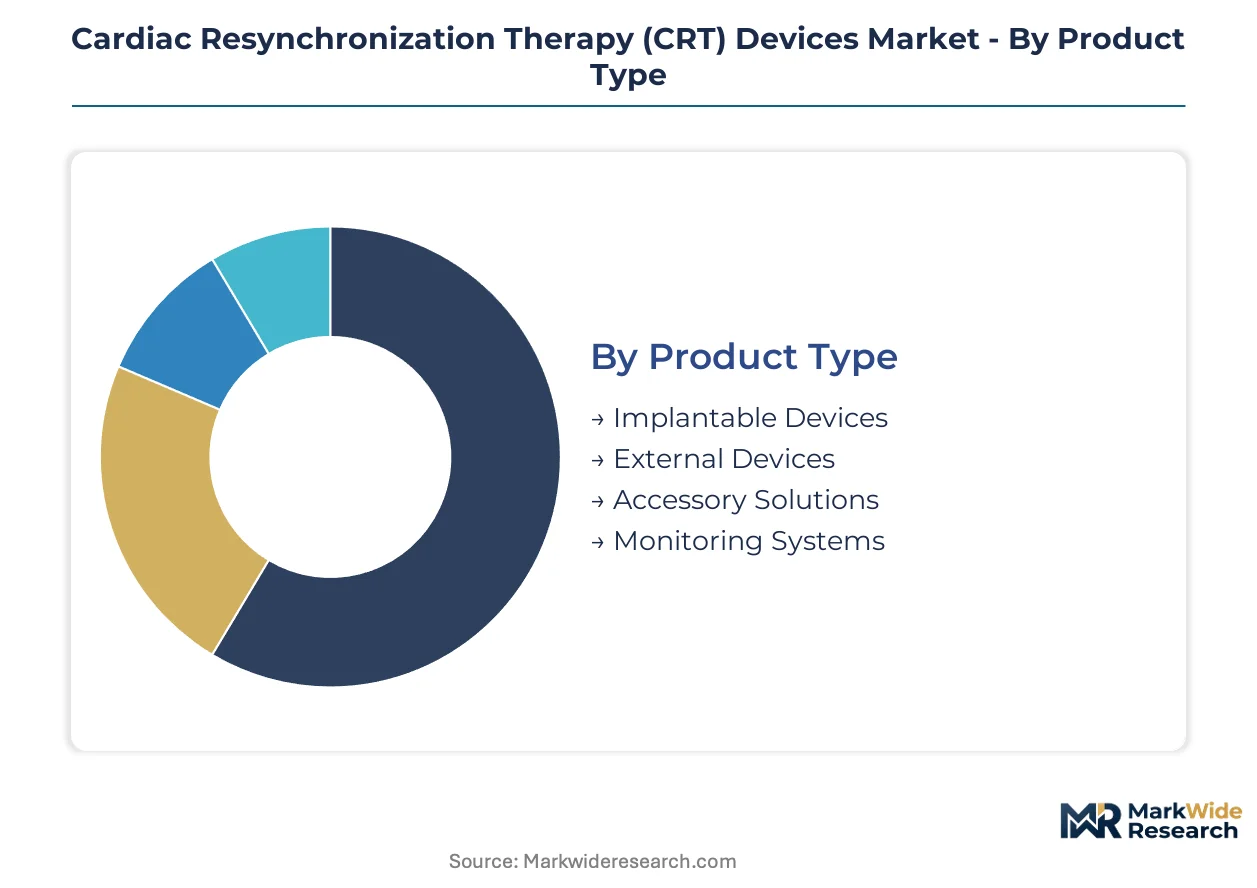
CRT device segmentation reveals how regulatory pathways, procedural settings, and care delivery models fragment commercial opportunity. Each dimension carries distinct certification burdens, reimbursement codes, and competitive dynamics that shape portfolio allocation decisions.
Product Type:
FDA PMA pathways govern implantable systems under the most stringent evidence requirements, while external and monitoring devices navigate 510(k) clearance or EU MDR Class IIa/IIb designations depending on patient contact duration.
- Implantable Devices:Pulse generators and transvenous leads delivering 3-5 V output with 0.3-1.5 ms pulse widths form the revenue core. Generator longevity improvements now exceed 10 years, compressing replacement cycles in Germany and Japan where device longevity directly influences procurement scoring.
- Monitoring Systems:Cloud-connected platforms transmitting hemodynamic data through cellular or Bluetooth protocols represent the steepest expansion trajectory. Reimbursement maturation for remote follow-up codes in the United States accelerates hospital adoption of subscription-based monitoring bundles.
- External Devices:Temporary pacing systems and non-invasive cardiac resynchronization units serve bridge-to-therapy or contraindicated patient populations.
- Accessory Solutions:Surgical tools, lead delivery systems, and programmer consoles complete implant workflows.
Leading the category by volume: Implantable Devices. Expanding most quickly: Monitoring Systems.
Technology:
Technology segments stratify by algorithm complexity and connectivity architecture, with adaptive systems requiring supplemental PMA submissions for software updates under FDA's evolving cybersecurity guidance.
- Adaptive Algorithms:Real-time hemodynamic feedback loops adjust pacing intervals based on sensor inputs. PMDA's real-world evidence frameworks in Japan enable faster algorithm iteration than FDA pathways, concentrating R&D investment in Tokyo-Osaka clinical corridors.
- Bi-Ventricular Pacing:Timed stimulation of left and right ventricles through coronary sinus lead placement. Anatomical variability in sinus anatomy limits capture success, driving demand for multipoint pacing configurations in academic electrophysiology centers.
- Electrical Stimulation:Foundational pacing waveforms and output modulation underlying all CRT modalities.
- Network Connectivity:Encryption protocols and cloud transmission infrastructure for implanted device data streams.
Highest margin concentration: Adaptive Algorithms. Fastest clinical adoption: Bi-Ventricular Pacing.
Delivery Mode:
Delivery mode segmentation tracks site-of-service economics, with invasive procedures commanding facility fees and remote monitoring capturing longitudinal reimbursement streams.
- Invasive Procedures:Transvenous lead implantation in electrophysiology labs or hybrid operating rooms. Hospital systems in the United States and Germany are expanding dedicated EP capacity to accommodate procedural volume growth and reduce wait times for heart failure cohorts.
- Remote Monitoring:Cloud-based follow-up protocols replacing in-office device interrogations. CMS reimbursement codes for remote monitoring reduce clinical resource burden while improving patient adherence in rural and underserved geographies.
- Outpatient Care:Clinic-based device checks and programming adjustments for stable patients.
- Rehabilitation Services:Post-implant cardiac conditioning and patient education programs.
Revenue concentration: Invasive Procedures. Gaining share fastest: Remote Monitoring.
End User:
End user segmentation reflects care setting consolidation, with integrated delivery networks in the United States and hospital procurement cooperatives in Germany driving vendor consolidation around bundled contracts.
- Hospitals:Tertiary centers with electrophysiology labs and heart failure programs anchor implant volumes. Reimbursement stability in the United States and Japan supports capital investment in dedicated cardiac rhythm management infrastructure.
- Cardiology Clinics:Community-based practices managing device follow-up and patient triage. Clinic networks in Germany leverage remote monitoring to extend geographic reach without proportional staffing expansion.
- Outpatient Facilities:Ambulatory surgical centers capturing low-complexity generator replacements.
- Specialized Treatment Centers:Academic medical centers handling non-responder optimization and lead extraction cases.
Volume leadership: Hospitals. Fastest structural growth: Cardiology Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CRT device manufacturing concentrates in specialized foundries serving medtech hubs, while procedural demand clusters in aging populations with established reimbursement frameworks. The United States, Germany, Japan, and China anchor both production ecosystems and implant volumes.
United States
Hospital systems in the United States are expanding electrophysiology lab capacity to accommodate rising CRT implant volumes among heart failure cohorts. FDA premarket approval pathways enforce stringent clinical evidence requirements that reinforce incumbent data advantages. The Minneapolis-St. Paul corridor hosts concentrated device engineering talent serving major manufacturers.
Germany
Germany's hospital procurement cooperatives are consolidating vendor relationships around integrated generator-lead-monitoring bundles. EU Medical Device Regulation clinical evaluation standards elevate barriers for new entrants while favoring established players with extensive patient registries. The Rhine-Ruhr and Bavarian medical technology clusters drive R&D investment in adaptive pacing algorithms.
Japan
Japan's aging demographic and stable reimbursement codes support procedural growth in cardiac rhythm management. PMDA adaptive approval frameworks enable faster algorithm updates through real-world evidence collection protocols. Tokyo-Osaka clinical corridors concentrate both implant volumes and manufacturer R&D facilities.
China
China's heart failure patient pool remains underpenetrated relative to epidemiological burden, creating expansion opportunity beyond tier-one hospital networks. NMPA pathway streamlining and domestic manufacturing incentives are accelerating local production capacity. The Yangtze River Delta and Pearl River Delta regions host growing device assembly operations serving regional demand.
United Kingdom
The United Kingdom's National Health Service procurement frameworks emphasize total cost-of-ownership metrics in CRT device selection. MHRA alignment with EU MDR standards maintains rigorous clinical evidence requirements post-Brexit. The Oxford-Cambridge-London arc anchors academic electrophysiology research influencing European pacing protocol development.
Cardiac Resynchronization Therapy (CRT) Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the CRT devices landscape, creating a tiered structure where scale advantages clash with technological agility. The vendor base stratifies into three archetypes: integrated ecosystem providers commanding premium positioning, bi-ventricular pacing technology specialists, and manufacturing-scale competitors with electrophysiology lab channel control. Consolidation pressure intensifies as hospital purchasing committees demand bundled solutions spanning generators, leads, and remote monitoring subscriptions.
Among diversified medtech conglomerates, Medtronic plc and Abbott Laboratories anchor the integrated ecosystem tier, while Boston Scientific Corporation occupies a position emphasizing manufacturing scale and procedural infrastructure partnerships. These three entities exemplify distinct competitive vectors: ecosystem breadth, pacing technology leadership, and channel density respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| BIOTRONIK SE & Co. KG |
| MicroPort Scientific Corporation |
| LivaNova PLC |
| Medico S.p.A. |
| Lepu Medical |
| OSCOR Inc. |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation around integrated generator-lead-monitoring bundles is forcing component suppliers to absorb integration costs or exit tier-one vendor lists, compressing margins at the subassembly tier while concentrating pricing power with ecosystem providers.
Pricing Analysis
Margin tightening in the implantable device tier reflects generator longevity improvements extending replacement intervals beyond ten years in Germany and Japan. Three-tier pricing structure across premium, standard, and economy levels stratifies by algorithm complexity and remote monitoring bundling, with FDA PMA-certified systems commanding sustained premiums. Cost-down pressure on standalone lead portfolios accelerates as hospital GPOs negotiate lifecycle cost guarantees. Community hospital systems exhibit highest price sensitivity, while academic electrophysiology centers prioritize capture optimization technology over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with specialized semiconductor foundry capacity concentrated in Taiwan and South Korea, where pacing ASIC fabrication depends on legacy process nodes. Critical inputs include lithium-iodine battery cells, platinum-iridium electrode alloys, and medical-grade silicone lead insulation. Tariff exposure on Chinese-sourced rare earth elements in magnet assemblies threatens generator cost stability. Distribution runs through manufacturer-direct field inventory systems with consignment stocking at electrophysiology labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRT device competition is becoming a vertical-integration race, with control over adaptive algorithm development and cloud monitoring infrastructure determining margin capture across the implant lifecycle.
For Market Incumbents: Hedge against semiconductor supply disruption by securing captive capacity or long-term foundry offtake agreements for pacing ASIC production. Fortify data moats through expanded patient registry participation to satisfy EU MDR clinical evaluation requirements and extend replacement cycle economics through predictive algorithm services. For New Entrants and Emerging Players: Telehealth-integrated remote monitoring platforms offer the lowest barrier to initial revenue, bypassing capital-intensive generator manufacturing. Target China's tier-two hospital networks where NMPA pathway streamlining and domestic manufacturing incentives reduce incumbent data advantages, leveraging outcome-based contracting to differentiate from established bundled offerings. For Investors and Strategic Acquirers: The window for entry favors algorithm-specialist firms with FDA-cleared adaptive pacing software and installed base integration capabilities. Long-term viability hinges on regulatory data assets rather than manufacturing scale alone. Watch PMDA real-world evidence protocol adoption rates as the signal for whether AI-driven pacing optimization will accelerate algorithm update cycles beyond FDA timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA submissions for adaptive algorithms require extensive patient registry data that reinforces incumbent positioning. |
| CE Marking Pathway | EU MDR clinical evaluation standards elevate evidence thresholds and consolidate procurement around proven systems. |
| Hospital System Partnership | Integrated delivery networks negotiate multi-year service agreements capping total cost of ownership across device lifecycle. |
| Software Companion Development | Cloud-based monitoring platforms with closed-loop hemodynamic feedback differentiate premium tier offerings. |
| Reimbursement Strategy | CMS remote monitoring code maturation accelerates subscription revenue and reduces clinical resource burden. |
Methodological Framework
FDA 510(k) and PMA filing databases, EU MDR notified body certificates, and hospital procurement contract disclosures formed the secondary backbone, cross-referenced with primary interviews with electrophysiologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Bottom-up implant volume estimates from electrophysiology lab capacity expansion announcements were triangulated against top-down market sizing from device manufacturer revenue segment disclosures.
Historical trendline analysis of procedural volumes, reimbursement code adoption curves, and generator replacement intervals informed the projection framework across the analysis window. Segmentation modeling incorporated product type, technology tier, delivery mode, and end-user facility category with regional regulatory cluster overlays. CAGR derivation weighted electrophysiology lab buildout timelines, PMDA adaptive approval framework utilization rates, and NMPA pathway streamlining progress.
The model holds under stable reimbursement codes and continued electrophysiologist training pipeline expansion; deviation in FDA cybersecurity guidance stringency or semiconductor supply disruption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding algorithm regulatory classification and remote monitoring penetration curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Cryoablation System Market
Medical Devices
Mexico Ophthalmic Devices Market
Medical Devices
Laryngoscopes Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Muscle Stimulator Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Breathing Circuits Market