
 Medical Device Coating Market | 2026-2036
Medical Device Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Coating Market Intelligence
North American specialty chemical producers is rebalancing capacity toward medical-grade polymer synthesis as OEM qualification timelines lengthen. DSM sustains broad resin formulation leadership across hydrophilic and antimicrobial platforms. SurModics Inc. anchors its position through FDA-master-filed coating technologies for coronary applications. Covalon Technologies Ltd. differentiates via dual-action antimicrobial and hydration barrier coatings for long-dwell catheters.
Medical device coatings are thin-film surface treatments, typically 1–50 micrometers in thickness, applied through dip-spin, spray, or vapor deposition processes to modify wettability, drug release kinetics, or biological response at the tissue-device interface. Their primary purpose is to reduce friction, prevent biofilm formation, or enable localized therapeutic delivery without altering bulk mechanical properties of the underlying substrate. Hydrophilic coatings dominate catheter and guidewire applications where lubricity directly impacts procedural outcomes, while antimicrobial formulations command premium positioning in indwelling devices despite higher validation burdens. Biodegradable platforms represent the fastest-growing technology cluster as orthopedic and cardiovascular OEMs pursue resorbable drug-eluting scaffolds that eliminate permanent implant residues.
FDA enforces biocompatibility testing under ISO 10993 guidelines, requiring exhaustive cytotoxicity and sensitization data for any coating contacting blood or tissue. EMA's Medical Device Regulation extends this scrutiny to drug-device combination products, forcing coating suppliers to maintain dual quality management systems. Japan's PMDA imposes additional local clinical evidence requirements for novel surface technologies. Stakeholders must monitor evolving regulatory convergence between pharmaceutical and device frameworks, as coating suppliers increasingly face inspection regimes historically reserved for drug manufacturers.
Market Dynamics
Coating suppliers face mounting pressure from FDA and EMA biocompatibility convergence, forcing dual quality system investments while OEM qualification timelines extend to 18-24 months.
Growth Catalysts
- ISO 10993-18 chemical characterization mandates:FDA's updated biocompatibility guidance drives validated coating platform demand among cardiovascular catheter manufacturers.
- Biodegradable polymer platforms:Orthopedic and coronary stent OEMs pursue resorbable drug-eluting scaffolds that eliminate permanent implant residues.
- Japan's aging demographic:PMDA clinical evidence requirements for novel surface technologies sustain premium pricing for qualified coating suppliers.
Market Restraints
- Medical-grade polymer supply concentration:DSM and specialty chemical producers in Germany and the United States control hydrophilic resin formulation capacity.
- Dual quality system overhead:EMA's Medical Device Regulation imposes pharmaceutical-grade inspection regimes on coating converters.
- Plasma treatment substitution:Surface modification without coating layers threatens low-value lubricity applications.
Strategic Opportunities
- Long-dwell catheter antimicrobial-hydration combinations:Dual-action coatings address unmet infection prevention in indwelling devices.
- India's domestic device manufacturing:CDSCO regulatory alignment with ISO standards opens qualification pathways for coating suppliers.
- Drug-device combination product convergence:Coating suppliers with pharmaceutical release kinetics expertise capture eluting scaffold contracts.
Industry Challenges
- Surface chemist talent scarcity:Polymer science PhDs with blood-contact biocompatibility expertise command premium compensation.
- Master file maintenance burden:FDA Device Master File updates require continuous toxicology data generation.
- Cleanroom coating capacity constraints:ISO Class 7 manufacturing space for validated medical coating lines faces 24-month construction timelines.
Report Scope
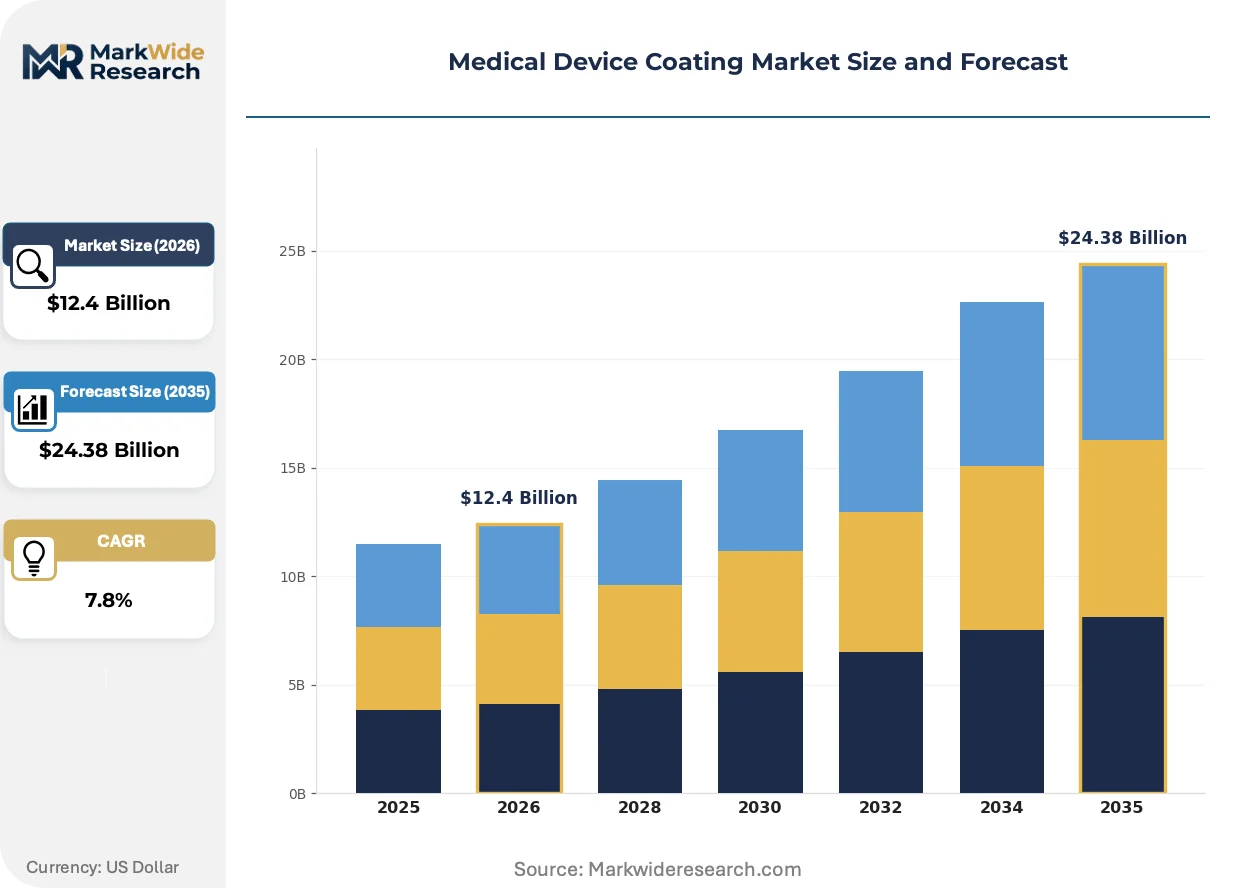
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Coating Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Stents, Catheters, Needle Devices, Surgical Instruments Coating Technology: Hydrophilic, Hydrophobic, Antimicrobial, Biodegradable End User: Hospitals, Outpatient Clinics, Surgical Centers, Research Laboratories Application: Cardiovascular, Orthopedic, Neurology, General Surgery |
| Companies Covered | Covalon Technologies Ltd., Harland Medical Systems Inc., SurModics Inc., AST Products Inc., DSM, Biocoat Inc., Sono-Tek Corp., Materion Corp., Hydromer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Coating Market Strategic Shifts & Innovations
Surface engineering is pivoting from passive lubricity toward active therapeutic delivery, with coating architectures integrating drug reservoirs and responsive release mechanisms. This shift redefines supplier capabilities and OEM partnership models.
Photocurable hydrophilic formulations are absorbing share from thermal-cure systems in high-throughput catheter manufacturing. Cardiovascular device producers in Minnesota and Massachusetts deploy UV-LED curing lines to compress coating cycle times. The technology is absorbing capital investment that previously supported solvent-based dip-coating infrastructure.
EMA's 2021 Medical Device Regulation extension to drug-device combinations forces coating suppliers to maintain pharmaceutical-grade batch records. Surface treatment providers now face notified body inspections historically reserved for API manufacturers. Coronary stent coating submissions require stability data packages matching drug product standards.
Hospital procurement consolidation in Germany and Japan is compressing qualified supplier lists to three coating platforms per device category. Original equipment manufacturers demand single-source accountability for coating performance failures. This concentration shifts pricing power toward converters with captive polymer synthesis and validated analytical methods.
Medical Device Coating Market Segmentation
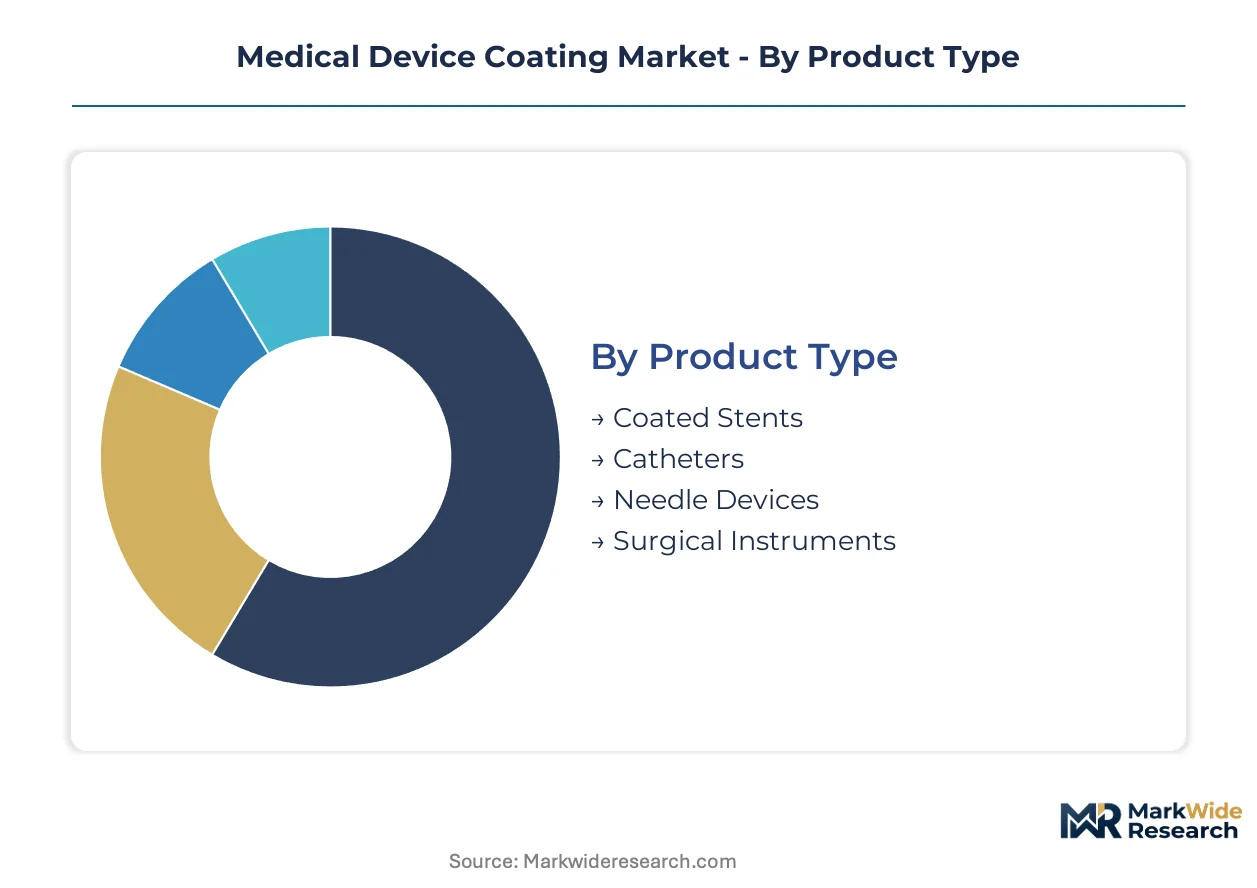
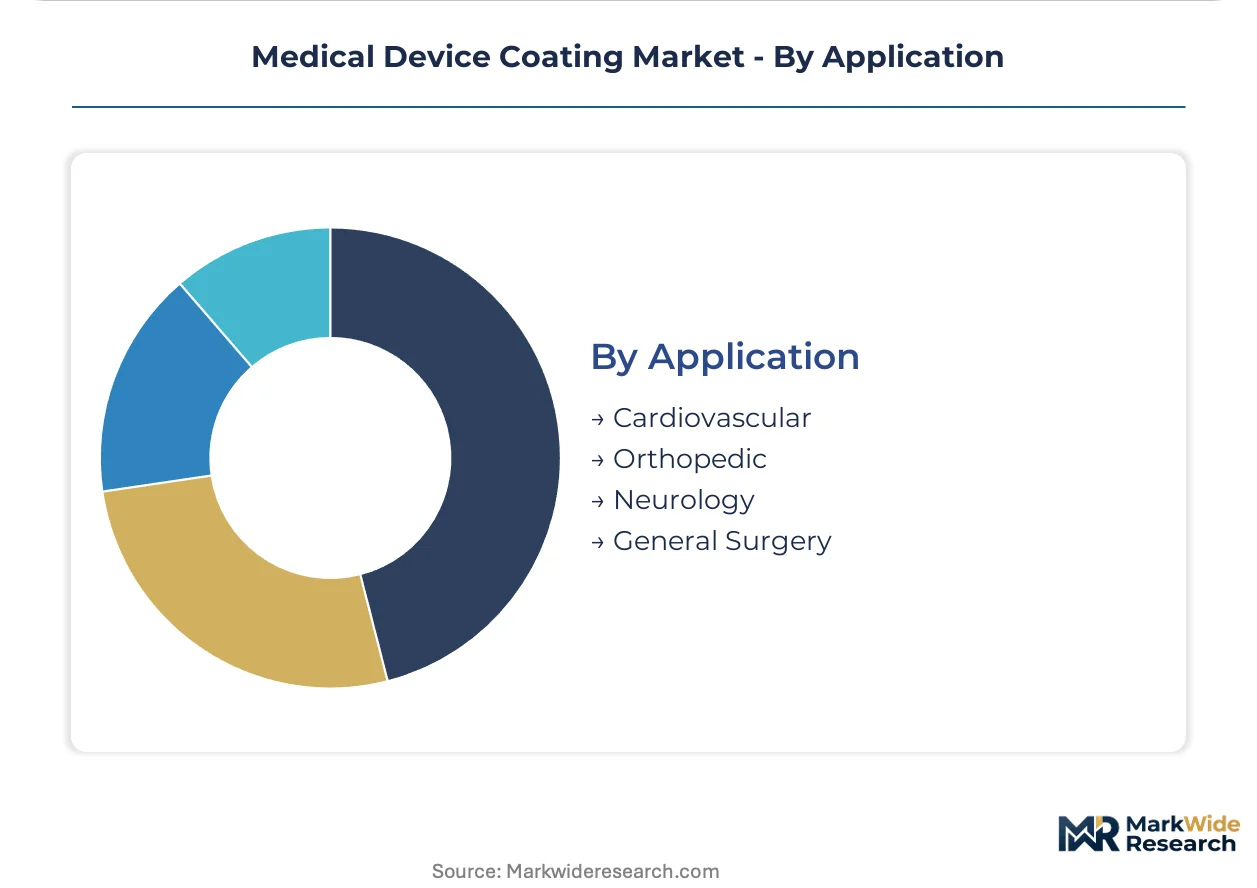
Coating specifications diverge sharply across device categories, with cardiovascular applications demanding blood-contact biocompatibility validation that general surgery surfaces rarely require. Understanding these technical boundaries determines supplier qualification pathways and pricing architecture.
Product Type:
Material-device interface requirements dictate coating thickness, adhesion chemistry, and sterilization compatibility across each product category.
- Coated Stents:Drug-eluting polymer matrices, typically 5-15 micrometers thick, enable controlled antiproliferative agent release at arterial lesion sites. Coronary OEMs in the United States and Germany concentrate procurement among suppliers with FDA Device Master Files and EMA notified body certifications, extending qualification timelines to 24 months.
- Catheters:Hydrophilic surface treatments reduce insertion friction by 60-90% compared to uncoated polyurethane substrates. Long-dwell central venous applications in Japan's aging patient population sustain premium pricing for dual-action antimicrobial-hydration formulations despite higher toxicology validation burdens.
- Needle Devices:Silicone-based lubricity coatings on hypodermic and biopsy needles minimize tissue penetration resistance.
- Surgical Instruments:Hard, low-friction ceramic coatings on forceps and scissors reduce tissue adhesion during electrosurgical procedures.
Catheters lead on scale; stents lead on momentum.
Coating Technology:
Functional performance specifications separate premium validated platforms from commodity surface treatments.
- Hydrophilic:Polyvinylpyrrolidone or polyethylene oxide networks absorb aqueous fluid to create low-friction surfaces for guidewire and catheter navigation. Cardiovascular procedural volume in the United States absorbs the majority of global hydrophilic coating capacity.
- Hydrophobic:Fluoropolymer or silicone chemistries repel moisture and biological fluids, finding application in endoscope lens surfaces and instrument handles.
- Antimicrobial:Silver ion, chlorhexidine, or antibiotic-loaded matrices prevent biofilm formation on indwelling devices. EMA's Medical Device Regulation imposes pharmaceutical-grade batch record requirements on antimicrobial coating converters, elevating compliance costs.
- Biodegradable:Poly(lactic-co-glycolic acid) and polycaprolactone platforms resorb within 30-180 days, eliminating permanent implant residues. Orthopedic and coronary stent OEMs are expanding biodegradable polymer synthesis capacity fastest.
Hydrophilic coatings dominate current volume; biodegradable platforms are expanding most quickly.
End User:
Procurement sophistication and regulatory exposure vary dramatically across care settings.
- Hospitals:Integrated delivery networks in Germany and Japan consolidate qualified supplier lists to three coating platforms per device category, demanding single-source accountability for performance failures.
- Outpatient Clinics:Lower procedural volumes favor standard hydrophilic catheter specifications over premium antimicrobial-hydration combinations.
- Surgical Centers:Ambulatory settings prioritize rapid turnover instrument coatings with validated steam sterilization resistance.
- Research Laboratories:Preclinical coating development for novel drug-device combinations requires ISO 10993-18 chemical characterization capabilities.
Hospitals anchor procurement volume; research laboratories drive specification evolution.
Application:
Biological environment determines coating functional requirements and regulatory scrutiny intensity.
- Cardiovascular:Blood-contact surfaces require thromboresistant chemistry and exhaustive hemocompatibility testing under ISO 10993-4 guidelines. FDA's updated biocompatibility guidance drives validated platform demand among catheter manufacturers in Minnesota and Massachusetts clusters.
- Orthopedic:Load-bearing implant coatings must balance osseointegration promotion with wear debris minimization on joint replacement surfaces.
- Neurology:Neural electrode coatings demand electrochemical stability and minimal inflammatory response at tissue interfaces.
- General Surgery:Suture and mesh coatings prioritize handling characteristics and knot security over long-term biocompatibility depth.
Cardiovascular commands the steepest expansion trajectory; general surgery offers volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping coating production geography as manufacturers seek jurisdictions with streamlined biocompatibility pathways. Cost-of-compliance gaps between FDA-dominated and emerging regulatory regimes are pulling contract manufacturing toward qualified Asian facilities.
United States
Cardiovascular catheter demand from Minnesota and Massachusetts medical device clusters absorbs the majority of hydrophilic coating capacity. FDA's updated ISO 10993-18 chemical characterization mandates extend OEM qualification timelines to 18-24 months. The Twin Cities corridor anchors captive coating operations for coronary stent manufacturers seeking Device Master File continuity.
Germany
Orthopedic OEMs in Baden-Württemberg and Bavaria drive biodegradable polymer platform adoption for resorbable implant scaffolds. EMA's Medical Device Regulation imposes pharmaceutical-grade batch record requirements on coating converters. The Stuttgart region concentrates specialty chemical producers rebalancing capacity toward medical-grade resin synthesis.
Japan
Aging demographics sustain premium pricing for long-dwell catheter antimicrobial-hydration combinations in Tokyo and Osaka metropolitan markets. PMDA clinical evidence requirements for novel surface technologies create qualification barriers for unvalidated suppliers. The Kansai region maintains tightly qualified coating supplier bases for indwelling device manufacturers.
India
Domestic device manufacturing expansion in Maharashtra and Gujarat opens qualification pathways for coating suppliers as CDSCO aligns with ISO standards. Cost-competitive contract research organizations in Hyderabad generate preclinical biocompatibility data packages. The Pune-Ahmedabad corridor attracts toll coating investments serving export-oriented stent and catheter producers.
Switzerland
Precision orthopedic and dental implant manufacturers in the Lake Geneva region demand validated coating platforms with Swissmedic quality system recognition. Dual-action antimicrobial coatings command premium positioning in alpine medical device clusters. The Basel-Zurich axis concentrates polymer science expertise supporting biodegradable scaffold development.
Medical Device Coating Market Key Industry Players
United States producers anchor the validated-platform tier; European specialists hold regulatory-certification advantages. The vendor base separates into consolidated resin formulators, mid-scale coating converters, and niche application specialists. Three archetypes dominate: captive polymer synthesis operations, FDA-master-filed technology licensors, and dual-action formulation innovators. Competitive moves center on pharmaceutical-grade quality system adoption and cleanroom capacity expansion.
Among North American technology licensors, SurModics Inc. and Harland Medical Systems Inc. occupy positions within the validated coronary application tier. DSM anchors the resin formulation segment through broad hydrophilic and antimicrobial platform leadership. Covalon Technologies Ltd. exemplifies the dual-action specialist archetype combining antimicrobial and hydration barrier functionalities. These three entities represent distinct competitive vectors: regulatory-filed technology, upstream material control, and combination therapy integration.
| Leading Market Players |
|---|
| Covalon Technologies Ltd. |
| Harland Medical Systems Inc. |
| SurModics Inc. |
| AST Products Inc. |
| DSM |
| Biocoat Inc. |
| Sono-Tek Corp. |
| Materion Corp. |
| Hydromer Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA-master-filed platforms and unvalidated commodity coatings manifests in both pricing architecture and procurement channel configuration. OEMs in Minnesota and Massachusetts absorb 40-60% price premiums for coronary stent coating platforms with Device Master File continuity, while catheter manufacturers in India source toll-coated hydrophilic layers at substantially lower validation burdens.
Pricing Analysis
Distributor margins on antimicrobial-hydration combination coatings compress direct-to-OEM pricing by 12-18% in European hospital procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-master-filed coronary platforms from validated catheter specifications and unvalidated general surgery surfaces. Cost compression in standard hydrophilic tiers intensifies as plasma surface modification substitutes for coating layers. Ambulatory surgical centers exhibit highest price sensitivity; coronary stent OEMs demonstrate lowest sensitivity due to liability exposure from coating failures.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cardiovascular catheter demand from United States and Germany device clusters. Raw material supply concentrates in Netherlands hydrophilic resin synthesis, German specialty chemical production, and Japanese polymer science operations. Coating converters draw from medical-grade polyvinylpyrrolidone, poly(lactic-co-glycolic acid), and silver-ion antimicrobial matrices. Single-source vulnerability pervades validated cleanroom coating capacity, where ISO Class 7 manufacturing space faces 24-month construction timelines. Distribution runs through captive OEM operations, qualified toll coaters, and regional contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical device coating market compounds steadily as cardiovascular procedural volume sustains hydrophilic platform demand and regulatory barriers protect qualified supplier margins.
For Market Incumbents: Cement FDA Device Master File leadership through continuous toxicology data generation and ISO 10993-18 chemical characterization capabilities. Expand captive polymer synthesis in Germany and United States to defend against DSM's resin formulation dominance. Plasma surface modification substitution threatens low-value lubricity applications; counter with dual-action antimicrobial-hydration combination platforms for long-dwell catheters. For New Entrants and Emerging Players: Begin with CDSCO-aligned regulatory pathways in Maharashtra and Gujarat domestic device manufacturing corridors. India's contract research organizations in Hyderabad generate preclinical biocompatibility data packages at cost-competitive rates. Target biodegradable polymer platform supply to orthopedic OEMs in Baden-Württemberg pursuing resorbable scaffolds. Lead with pharmaceutical release kinetics expertise to capture drug-device combination product contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where surface chemist talent scarcity meets extended OEM qualification timelines. Mid-scale coating converters with FDA-master-filed technologies and cleanroom capacity expansion pipelines represent prime acquisition targets. Watch EMA-FDA biocompatibility convergence as inflection indicator: pharmaceutical-grade inspection regime adoption signals sustainable margin protection for compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Device Master File Expansion | Coronary stent OEMs in Minnesota demand continuous toxicology data continuity. |
| CE Marking Pathway Investment | EMA's Medical Device Regulation imposes pharmaceutical-grade batch record requirements. |
| Hospital System Partnership | German integrated delivery networks consolidate qualified supplier lists to three platforms. |
| Backward Integration into Resin Synthesis | DSM's hydrophilic and antimicrobial platform leadership anchors material cost control. |
| Cleanroom Capacity Expansion | ISO Class 7 manufacturing space for validated coating lines faces 24-month construction. |
Research Approach
Bottom-up catheter and stent demand modeling reconciled against top-down coating converter capacity tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs directors at cardiovascular OEMs combined with secondary validation from FDA 510(k) filings, EMA notified body certifications, hospital procurement databases, and ISO 10993 biocompatibility standards. Triangulation between end-use volume estimates and supplier production disclosures ensures cross-verified output integrity.
Input-output matrices connect cardiovascular procedural volume, orthopedic implant placement rates, and catheter utilization patterns to coating thickness specifications and polymer consumption coefficients. Segmentation dimensions span product type, coating technology, application, and end-user procurement sophistication. CAGRs derive from regression analysis across historical qualification timeline data and OEM capacity expansion announcements. Drug-device combination product convergence and biodegradable scaffold adoption curves inform technology-specific growth differentials across the projection horizon.
Several conditions sit outside the modeled scope, including regulatory approval delays beyond standard ISO 10993 pathways, raw material supply disruptions from medical-grade polymer concentration, and plasma surface modification technology substitution rates. Forecasts reflect assumptions on OEM qualification timeline stability and EMA-FDA biocompatibility convergence trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Pen Needles Market
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Digital BTE Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Transportable Ventilator Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Global Intraosseous Devices Market