
 Pre-Owned Medical Devices Market | 2026-2036
Pre-Owned Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Owned Medical Devices Market Intelligence
Equipment leasing and asset-light procurement models is tilting competitive dynamics toward firms that can bundle financing with refurbishment capabilities. GE Healthcare leverages its captive service network to control post-sale revenue streams across imaging modalities. Siemens Healthineers anchors its position through proprietary refurbishment protocols that extend equipment lifecycle. Philips Healthcare competes by integrating remote diagnostics into its pre-owned device offerings.
Pre-owned medical devices encompass refurbished, recertified, and second-hand equipment that undergoes functional restoration to original manufacturer specifications, including replacement of worn components, calibration to IEC 60601 electrical safety standards, and software validation. These devices serve healthcare providers seeking diagnostic and therapeutic capability at reduced capital outlay. Imaging Equipment dominates transaction volume due to high replacement frequency of CT and MRI systems, while Patient Monitors represent the fastest-turning category as technology refresh cycles compress. Surgical Instruments concentrate margin pools in specialized orthopedic and laparoscopic sets where OEM refurbishment commands premium pricing.
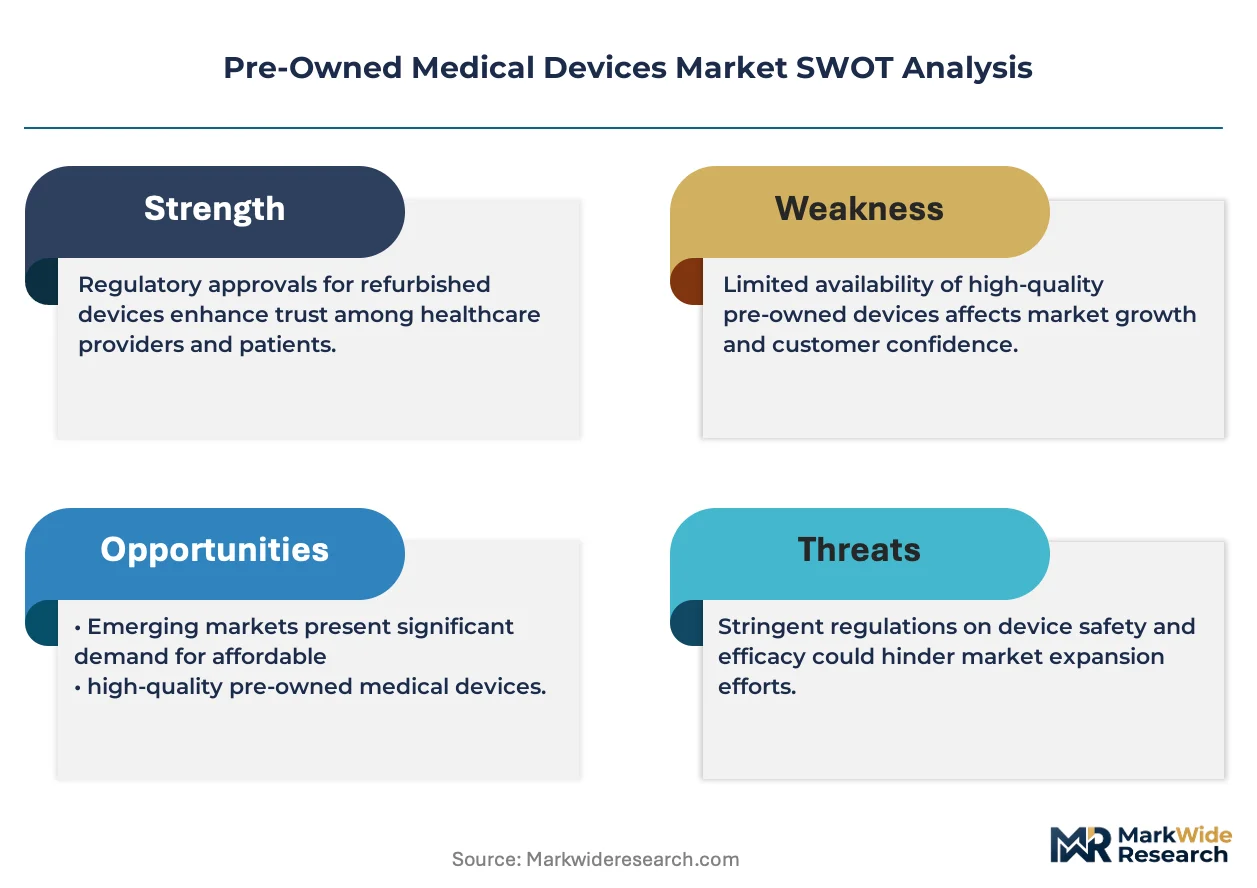
FDA enforces 510(k) clearance requirements for refurbished devices sold in the United States, while EU MDR mandates conformity assessment for recertified equipment entering European markets. India's CDSCO has tightened import registration for pre-owned diagnostic devices, redirecting regional supply flows toward certified refurbishers. Stakeholders must monitor evolving national equivalence agreements that determine whether refurbished devices qualify for public hospital procurement tenders.
Market Dynamics
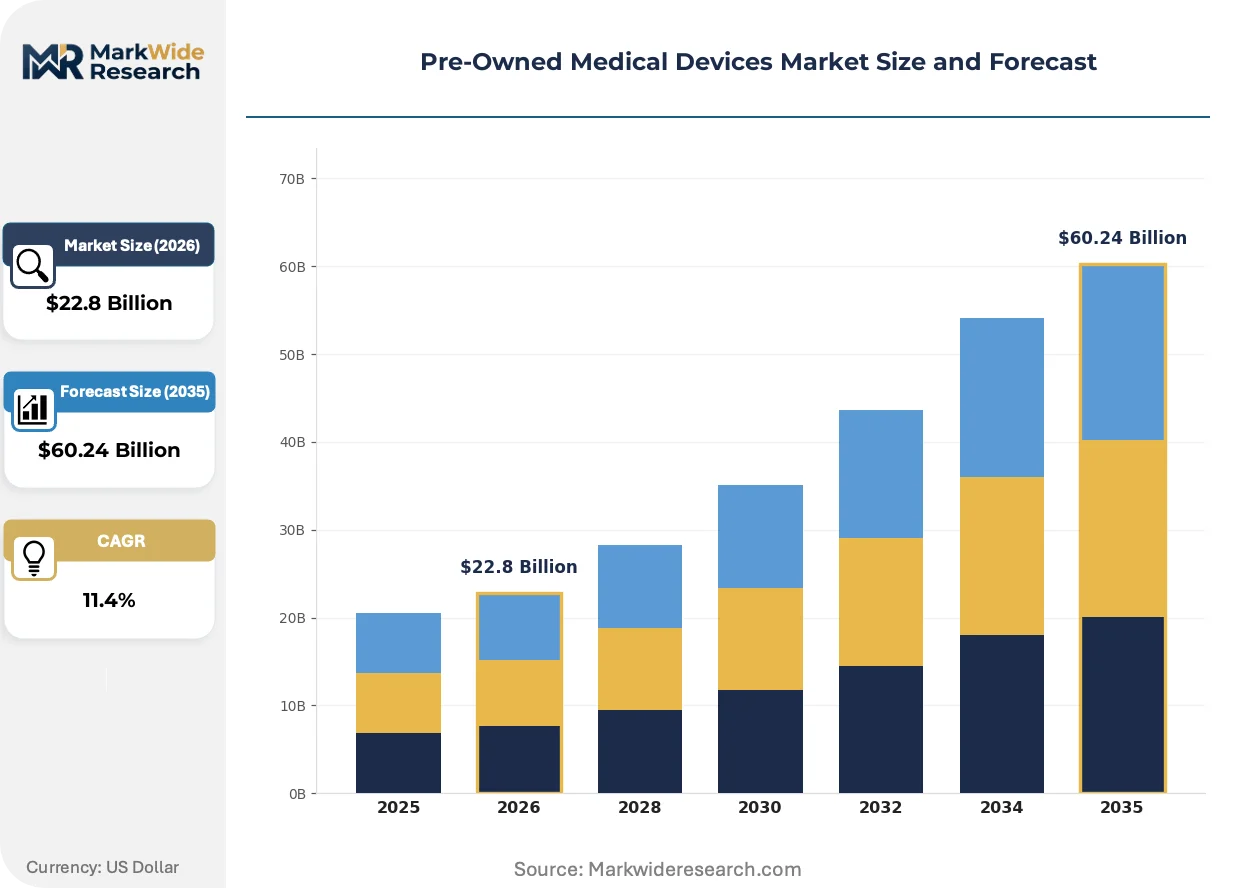
Capital constraints across public hospital systems are compressing replacement cycles for diagnostic imaging equipment, forcing procurement officers to evaluate refurbished alternatives against new capital purchases. This structural pressure is redistributing vendor relationships toward refurbishment specialists capable of delivering OEM-equivalent performance warranties.
Growth Catalysts
- CDSCO Import Registration Tightening:India's tightened import controls for pre-owned diagnostic devices are redirecting regional supply flows toward certified domestic refurbishers, creating captive demand pools for compliant vendors.
- Equipment Leasing Models:Asset-light procurement structures are expanding addressable markets among mid-tier hospitals previously excluded from imaging system ownership.
- CT and MRI Replacement Frequency:High obsolescence rates in diagnostic imaging are sustaining transaction velocity as healthcare providers balance capability refresh against budget freezes.
Market Restraints
- EU MDR Conformity Assessment:European regulatory requirements for recertified equipment create documentation burdens that extend time-to-market for refurbished device vendors.
- Specialized Component Sourcing:Concentrated supply of proprietary imaging detectors and gradient coils limits refurbishment scalability outside OEM-authorized networks.
- Software Validation Complexity:FDA 510(k) clearance requirements for refurbished devices with updated operating systems impose engineering costs that erode margin structures.
Strategic Opportunities
- Brazilian Public Hospital Tenders:Underpenetrated state procurement channels present volume opportunities for refurbishers establishing local certification partnerships.
- Remote Diagnostics Integration:Convergence of refurbished hardware with cloud-based predictive maintenance platforms is creating differentiated service bundles.
- Southeast Asia Hub Development:Singapore and Malaysia are emerging as regional refurbishment centers serving Indonesian and Vietnamese demand clusters.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortage of technicians trained in IEC 60601 electrical safety calibration and OEM-specific diagnostic protocols constrains refurbishment throughput.
- Legacy System Integration:Connecting refurbished imaging equipment to hospital information systems requires customized interface development that delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Owned Medical Devices Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $60.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Equipment, Surgical Instruments, Patient Monitors, Diagnostic Devices, Therapeutic Machines Application: Cardiology, Orthopedics, Neurology, Oncology, General Surgery End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Rehabilitation Clinics, Specialty Care Centers Sales Channel: Direct Sales, Distributors, Online Marketplaces, Refurbishers, Leasing Services |
| Companies Covered | Canon Medical Systems Corporation, Block Imaging International, GE Healthcare, Mindray Medical International, Avante Health Solutions, Siemens Healthineers, Soma Technology, Stryker, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Owned Medical Devices Market Strategic Shifts & Innovations
Refurbishment operations are converging with digital service platforms, compressing the traditional separation between equipment supply and ongoing technical support. This integration is redefining how hospitals evaluate total cost of ownership across extended asset lifecycles.
Artificial intelligence-based predictive maintenance software is digitizing refurbishment workflows by automating component failure forecasting and optimizing spare parts inventory positioning. Independent service organizations are adopting these platforms to match OEM service response times. The technology is digitizing competitive dynamics between authorized and third-party refurbishers by democratizing access to performance analytics previously captive to manufacturers.
EU MDR recertification pathways for refurbished medical devices are tightening documentation requirements around clinical evidence and post-market surveillance. The regulation is forcing refurbishment specialists to invest in quality management systems equivalent to OEM standards. High-risk device categories including implantable surgical instruments face the steepest compliance burdens, with vendors redirecting portfolio focus toward lower-classification diagnostic equipment.
Hospital procurement departments are consolidating vendor relationships through multi-year managed equipment service contracts that bundle refurbishment with maintenance and upgrade rights. This model is displacing traditional capital purchase cycles in European and North American health systems. The shift is most pronounced in Germany and the United Kingdom, where integrated care systems favor operational expenditure structures over upfront capital allocation.
Pre-Owned Medical Devices Market Segmentation
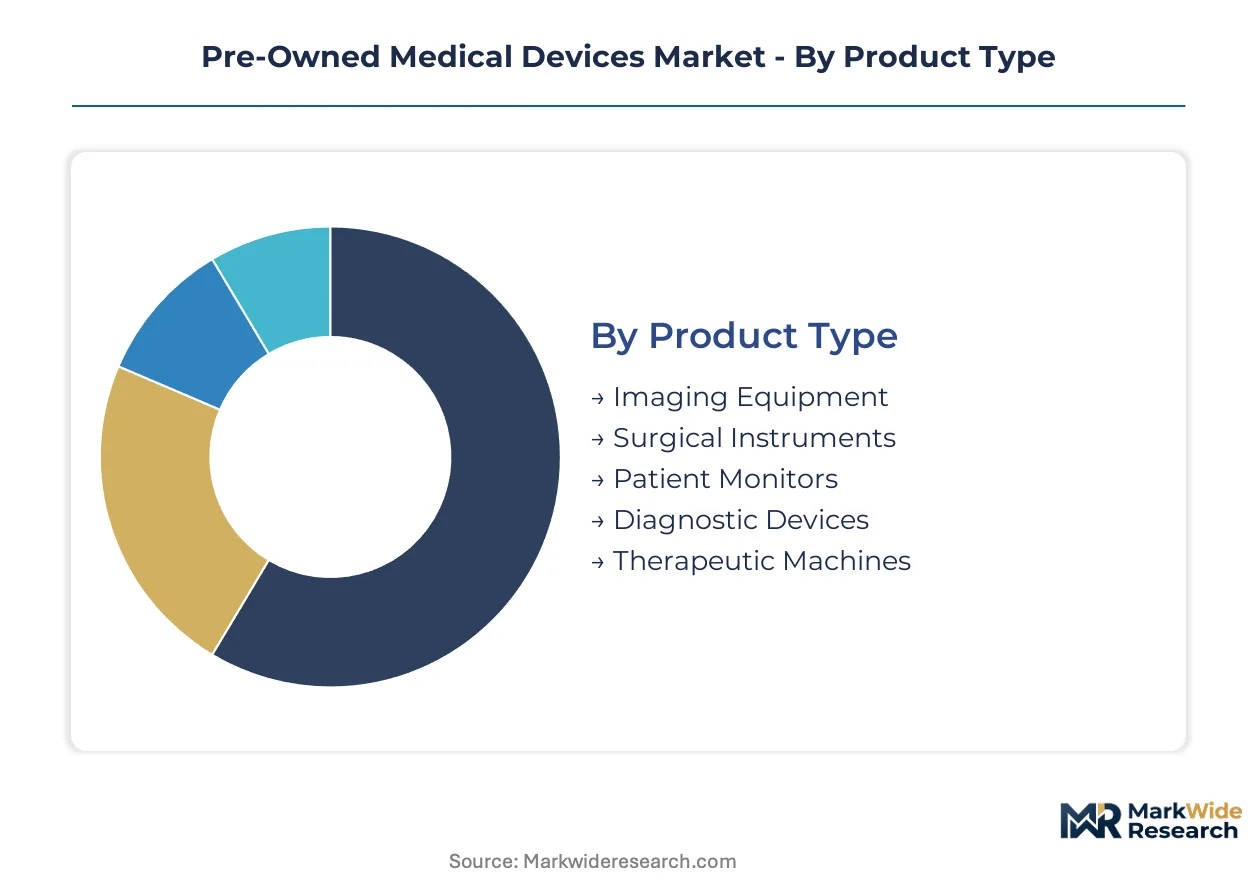
Segmentation in the pre-owned medical devices market reveals how procurement priorities diverge across equipment lifecycles, clinical applications, and capital availability. Understanding these divisions exposes where refurbishment economics outperform new equipment acquisition and which customer profiles sustain premium pricing for certified recertification.
Product Type:
Equipment categories span the full diagnostic and therapeutic spectrum, with capital intensity and technology obsolescence rates determining refurbishment viability.
- Imaging Equipment:CT scanners, MRI systems, and ultrasound machines undergo component replacement of gradient coils, detector arrays, and RF systems to restore OEM performance specifications. Demand concentrates in Indian public hospital systems where CDSCO import registration requirements favor certified domestic refurbishers with established FDA 510(k) equivalence documentation.
- Patient Monitors:Multi-parameter bedside units and telemetry systems feature compressed technology refresh cycles that accelerate secondary market velocity. Brazilian state procurement channels drive volume as SUS hospital networks prioritize operational expenditure models over capital purchases for monitoring infrastructure.
- Surgical Instruments:Specialized laparoscopic and orthopedic sets command premium recertification pricing due to precision tolerance requirements.
- Diagnostic Devices:Electrocardiographs, endoscopy systems, and laboratory analyzers serve decentralized testing expansion.
- Therapeutic Machines:Dialysis units and infusion pumps address chronic care equipment needs with extended depreciation schedules.
Established volume favors Imaging Equipment; emerging adoption favors Patient Monitors.
Application:
Clinical specialization dictates equipment performance requirements and regulatory scrutiny intensity across refurbishment protocols.
- Cardiology:Catheterization laboratory equipment and echocardiography systems demand IEC 60601 electrical safety recalibration and hemodynamic measurement validation. Southeast Asian diagnostic laboratories in Vietnam and Indonesia source refurbished cardiac imaging to bridge capability gaps against budget constraints.
- Oncology:Linear accelerators and PET-CT systems require the most stringent refurbishment documentation due to radiation safety protocols. Leasing services in Malaysia and Singapore are gaining share fastest by bundling radiotherapy equipment with technical support and upgrade pathways.
- Orthopedics:Arthroscopy towers and surgical navigation systems concentrate margin in specialized instrument refurbishment.
- Neurology:EEG systems and neuro-navigation equipment serve expanding functional diagnostics capacity.
- General Surgery:Standardized electrosurgical units and operating room tables offer highest refurbishment scalability.
Margin concentration anchors Oncology; volume expansion characterizes General Surgery.
End User:
Customer infrastructure and procurement authority determine contract structures and service bundling requirements.
- Hospitals:Acute care facilities with biomedical engineering departments manage complex imaging system integration and legacy HIS connectivity. India's tier-2 and tier-3 city hospitals redirect procurement toward certified refurbishers following CDSCO import registration tightening that eliminated uncertified cross-border supply.
- Ambulatory Surgical Centers:Focused procedure volumes and limited capital budgets favor equipment leasing with maintenance inclusion. Brazilian ambulatory networks in São Paulo and Minas Gerais represent expanding demand clusters for surgical instrument refurbishment with rapid deployment timelines.
- Diagnostic Laboratories:High-throughput testing operations prioritize analyzer uptime and reagent compatibility.
- Rehabilitation Clinics:Therapeutic device needs emphasize durability over cutting-edge capability.
- Specialty Care Centers:Concentrated clinical focus enables standardized equipment configurations.
Contract complexity peaks with Hospitals; procurement velocity favors Ambulatory Surgical Centers.
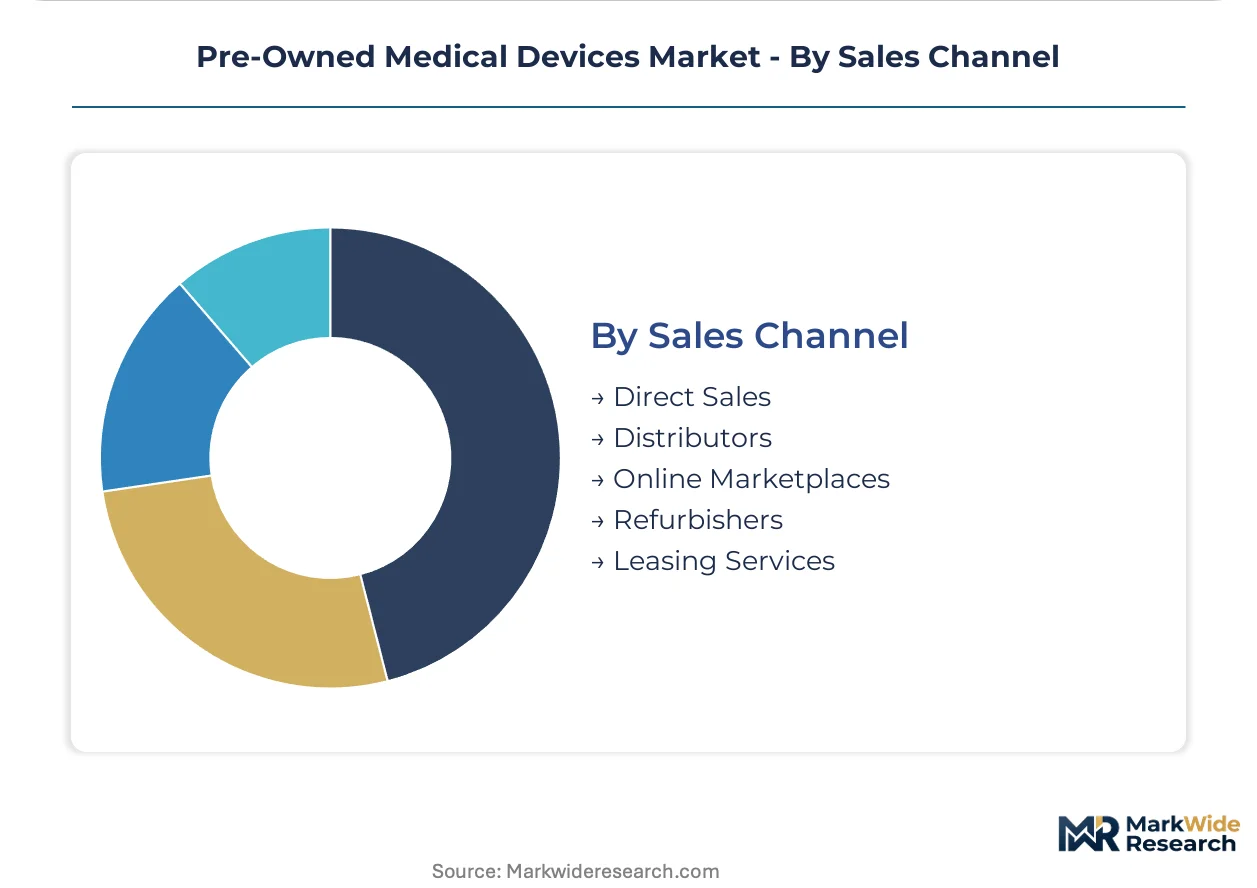
Sales Channel:
Channel structure determines warranty accountability, financing availability, and regulatory documentation custody.
- Refurbishers:OEM-authorized and independent refurbishment specialists control quality certification and FDA 510(k) clearance documentation for imaging systems. Malaysian and Singaporean refurbishment hubs serving Indonesian demand clusters differentiate through EU MDR conformity assessment capabilities that unlock European re-export opportunities.
- Leasing Services:Asset-light procurement models bundle equipment access with maintenance, upgrade rights, and end-of-term disposition. Leasing penetration is climbing the fastest in German and United Kingdom integrated care systems where operational expenditure structures displace capital allocation cycles.
- Direct Sales:Manufacturer-controlled secondary markets preserve service revenue attachment.
- Distributors:Regional inventory positioning reduces delivery timelines for standardized equipment.
- Online Marketplaces:Price transparency platforms serve low-risk device categories with limited regulatory burden.
Quality accountability concentrates with Refurbishers; financing innovation centers on Leasing Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and United Kingdom integrated care systems where operational expenditure contracts displace capital purchases, while Indian and Brazilian public hospital systems extract value through certified domestic refurbishment channels constrained by import registration requirements.
United States
FDA 510(k) clearance requirements for refurbished imaging systems sustain OEM-authorized refurbishment networks against independent competitors. Hospital procurement consolidation across IDNs redirects volume toward vendors bundling equipment with multi-year service contracts. The Cleveland Clinic and Mayo Clinic anchor demand for recertified diagnostic equipment with extended performance warranties.
Germany
EU MDR conformity assessment burdens extend time-to-market for recertified devices, favoring established refurbishers with equivalent quality management systems to OEM standards. Integrated care systems in Bavaria and North Rhine-Westphalia displace capital allocation with operational expenditure structures for imaging equipment. Berlin-based refurbishment specialists serve radiotherapy equipment demand across Central European hospital networks.
India
CDSCO import registration tightening eliminates uncertified cross-border supply, redirecting regional flows toward certified domestic refurbishers. Tier-2 and tier-3 city hospitals in Maharashtra and Karnataka pivot procurement toward FDA 510(k) equivalence documentation holders. Hyderabad and Bengaluru clusters concentrate biomedical engineering talent for IEC 60601 electrical safety calibration.
Brazil
SUS hospital network capital constraints compress replacement cycles for CT and MRI systems toward refurbished alternatives. ANVISA regulatory pathways for recertified equipment create documentation requirements that favor local certification partnerships. São Paulo and Minas Gerais ambulatory surgical centers drive surgical instrument refurbishment with rapid deployment timelines.
Singapore
Regional refurbishment hub status serving Indonesian and Vietnamese demand clusters differentiates through EU MDR conformity assessment capabilities. Leasing services bundling radiotherapy equipment with technical support gain share fastest among Southeast Asian diagnostic laboratories. The Biopolis research corridor anchors predictive maintenance platform development for refurbished device integration.
Pre-Owned Medical Devices Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with concentrated supply of proprietary imaging detectors and gradient coils. Market structure tilts toward OEM-authorized networks controlling post-sale revenue streams through captive service infrastructure, while independent refurbishers compete on asset-light procurement bundling. Three archetypes dominate: imaging system OEMs with proprietary refurbishment protocols, independent service organizations adopting AI-based predictive maintenance platforms, and regional specialists leveraging local certification partnerships. Competitive moves concentrate on backward integration into spare parts inventory positioning and geographic expansion through hub-and-spoke refurbishment center networks.
Within the OEM-authorized tier, GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify platform integrators commanding system-tier refurbishment through proprietary protocols and captive service networks. GE Healthcare occupies a position anchored to FDA 510(k) equivalence documentation and multi-year managed equipment service contracts. Siemens Healthineers exemplifies the archetype extending equipment lifecycle through proprietary refurbishment protocols integrated with remote diagnostics. Philips Healthcare represents convergence of refurbished hardware with cloud-based predictive maintenance platforms, differentiating service bundles across European and North American operational expenditure procurement structures.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Block Imaging International |
| GE Healthcare |
| Mindray Medical International |
| Avante Health Solutions |
| Siemens Healthineers |
| Soma Technology |
| Stryker |
| Philips Healthcare |
| Others |
Cost & Logistics Intelligence
Single-source dependency on proprietary imaging detectors and gradient coils from OEM-authorized networks compresses margin spreads across premium-certified, standard-refurbished, and economy-tier secondary equipment while simultaneously forcing supply chain consolidation around FDA 510(k) equivalence documentation holders.
Pricing Analysis
Hospital procurement officers anchor pricing stratification across premium, standard, and economy tiers based on OEM certification grade and bundled after-sales service intensity. Price differentiation separates FDA 510(k) cleared systems with full performance warranties from CDSCO-registered domestic refurbishments with limited coverage. Cost compression in the economy tier intensifies as Indian tier-3 hospitals prioritize capital outlay reduction over extended service contracts. Ambulatory surgical centers in Brazil exhibit highest price sensitivity, while German integrated care systems demonstrate lowest sensitivity due to operational expenditure procurement structures.
Supply Chain Analysis
Extended payment terms from GE Healthcare, Siemens Healthineers, and Philips Healthcare tether independent refurbishers to captive financing facilities that preserve OEM control over spare parts inventory positioning. Component sourcing concentrates in Malaysia, Singapore, and Germany for gradient coil rewinding and detector array recalibration. Supply chains draw from concentrated supplies of proprietary RF amplifiers, high-voltage generators, and imaging software licenses. Single-source vulnerability around OEM-authorized component access constrains third-party refurbishment scalability. Distribution runs through hub-and-spoke refurbishment center networks with regional certification partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-owned medical device markets fragment across certification-grade tiers, with CDSCO import registration tightening and EU MDR conformity assessment burdens creating protected niches for compliant domestic refurbishers.
For Market Incumbents: Pre-empt independent service organization encroachment by backward integration into predictive maintenance software platforms and spare parts inventory positioning in Hyderabad and Bengaluru. Accelerate FDA 510(k) equivalence documentation expansion to defend against emerging third-party refurbishers leveraging AI-based failure forecasting. Capture hospital procurement consolidation through multi-year managed equipment service contracts with embedded upgrade rights. For New Entrants and Emerging Players: Mid-tier diagnostic laboratories in Vietnam and Indonesia represent the most penetrable entry point for refurbished patient monitors with rapid deployment timelines and limited regulatory burden. Brazilian SUS hospital networks in São Paulo and Minas Gerais offer volume opportunities for surgical instrument refurbishment partnerships with ANVISA-authorized local certification. Target cloud-based predictive maintenance platform integration as the primary go-to-market differentiator against OEM-authorized networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional refurbishment specialists with established CDSCO, FDA 510(k), and EU MDR conformity assessment capabilities. Long-term viability hinges on captive access to proprietary component supply and biomedical engineering talent pools. Target acquisition archetypes include Malaysian and Singaporean hub operators serving Indonesian demand clusters. Monitor CDSCO import registration enforcement intensity and EU MDR documentation burden expansion as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Clearance documentation unlocks hospital procurement eligibility across IDN consolidation channels. |
| EU MDR Conformity Assessment Investment | Quality management system equivalence enables European re-export from Southeast Asian refurbishment hubs. |
| Hospital System Partnership | Multi-year managed equipment service contracts displace capital purchase cycles in German integrated care systems. |
| Predictive Maintenance Platform Development | AI-based component failure forecasting democratizes performance analytics previously captive to OEMs. |
| Regional Certification Partnership | ANVISA-authorized local partnerships accelerate Brazilian public hospital tender participation. |
Research Approach
The analysis maps imaging equipment, patient monitors, and surgical instrument refurbishment verticals, each validated through hospital procurement officers, biomedical engineering directors, GPO contracts managers, and refurbishment operations executives. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, CDSCO import registration records, EU MDR conformity assessment documentation, and hospital procurement tender databases. Bottom-up equipment transaction modeling triangulated with top-down market sizing across the projection horizon.
Assumptions held regulatory pathway timelines and certification burden intensity fixed while varying capital constraint severity across public hospital systems and technology obsolescence rates for diagnostic imaging. The analytical framework segmented by product type, application specialty, end-user infrastructure, and sales channel structure throughout the forecast period. CAGRs derived from equipment replacement frequency modeling, secondary market velocity indices, and leasing penetration curves across operational expenditure procurement transitions.
Practitioners should monitor CDSCO enforcement intensity, EU MDR documentation expansion, and AI-based predictive maintenance platform adoption rates for early signals of competitive repositioning. Forecasts reflect these documented assumptions; macroeconomic deviation in emerging market healthcare budgets, regulatory harmonization failure across national equivalence agreements, or proprietary component supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
China Ophthalmic Devices Market