
 Invasive SEEG Depth Electrodes Market | 2026-2036
Invasive SEEG Depth Electrodes Market Size, Share, and Industry Trends Forecast 2026-2036
Invasive SEEG Depth Electrodes Market Insights
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for invasive SEEG depth electrode manufacturers seeking CE marking. Ad-Tech Medical leverages its long-standing FDA clearances to anchor North American distribution while navigating European conformity pathways. Integra LifeSciences sustains competitive positioning through in-house production of platinum-iridium electrode alloys. DIXI Medical specializes in microelectrode arrays for high-resolution cortical sampling.
Invasive SEEG depth electrodes are multi-contact platinum-iridium or stainless steel conductors, typically 0.8–1.3 mm in diameter with 5–18 recording contacts spaced at 3.5–10 mm intervals, designed for stereotactic implantation into mesial temporal structures and insular cortex to localize epileptogenic zones prior to resective surgery. Single-use electrodes dominate hospital procurement due to infection control protocols, while combination electrode configurations that integrate macroelectrode recording with microelectrode precision are capturing growing share in academic centers where functional mapping demands higher spatial resolution. Reusable electrode sterilization validation costs are shifting demand toward disposable alternatives across European and North American institutions.
FDA 510(k) pathways and EU MDR Class III implantable device requirements govern market access, with notified bodies demanding extended clinical follow-up data for novel electrode geometries. Germany's national reimbursement framework for presurgical epilepsy evaluation under the G-DRG system shapes hospital purchasing cycles and volume commitments. Stakeholders must monitor evolving FDA guidance on brain-computer interface peripherals, as SEEG electrode platforms increasingly serve dual diagnostic and therapeutic neurostimulation roles.
Market Dynamics
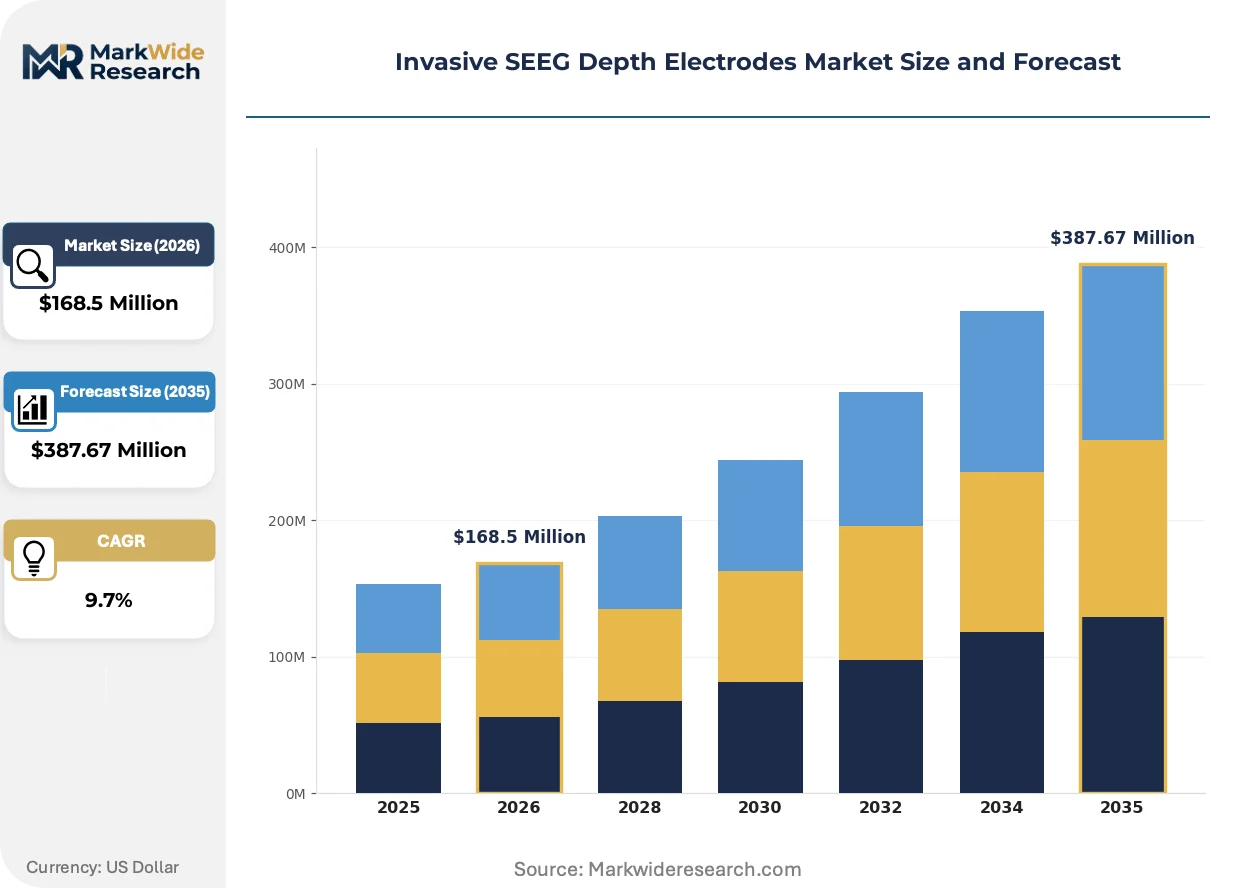
The EU MDR Class III implantable device framework is forcing manufacturers to restructure quality management systems and clinical evidence portfolios, compressing timelines for CE marking while academic medical centers accelerate SEEG protocol adoption.
Growth Catalysts
- Drug-resistant epilepsy protocols:Academic medical centers in Germany are institutionalizing stereoelectroencephalography as mandatory presurgical evaluation, creating procedural pull-through for multi-contact electrode configurations.
- Platinum-iridium microfabrication:Advances in laser-welded contact assembly enable 0.8 mm diameter electrodes with 18 recording sites, expanding access to deep mesial temporal structures previously unreachable with conventional designs.
- G-DRG reimbursement anchoring:Germany's diagnosis-related group system for presurgical epilepsy evaluation provides predictable hospital budgeting cycles that stabilize electrode procurement volumes.
Market Restraints
- Notified body capacity constraints:EU MDR designation bottlenecks for Class III neural implants extend conformity assessment timelines, freezing product launches for 18-24 months.
- Platinum group metal volatility:Iridium spot price fluctuations directly compress electrode manufacturing margins, with alloy feedstock representing 34-40% of unit production cost.
- Single-use sterilization validation burden:Reusable electrode reprocessing protocols face escalating FDA scrutiny, eliminating cost-recovery strategies for mid-tier hospitals.
Strategic Opportunities
- Brain-computer interface convergence:SEEG electrode platforms with integrated neurostimulation capability are integrating therapeutic closed-loop systems, opening dual-use reimbursement pathways.
- Microelectrode array penetration:High-resolution cortical sampling demand in functional mapping creates white space for hybrid macro-micro contact configurations in tertiary epilepsy centers.
- FDA 510(k) predicate leverage:Existing clearances for platinum-iridium conductors provide accelerated pathways for geometrically novel electrode designs targeting insular cortex access.
Industry Challenges
- Stereotactic neurosurgeon scarcity:SEEG implantation requires subspecialized surgical expertise concentrated in 40-50 US academic centers, constraining procedural volume scaling.
- Biocompatibility testing backlogs:Extended cytotoxicity and sensitization studies for novel polymer coatings delay product iterations by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Invasive SEEG Depth Electrodes Market |
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $387.67 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Use, Reusable, Retrievable, Non-Retrievable Technology: Electrode Array, Microelectrode, Macroelectrode, Combination Electrode End User: Hospitals, Research Institutions, Specialized Clinics, Academic Centers Application: Epilepsy Monitoring, Tumor Localization, Functional Mapping, Neurostimulation |
| Companies Covered | Ad-Tech Medical, Integra LifeSciences, DIXI Medical, PMT Corporation, Elekta AB, Natus Medical Incorporated, Micromed Group, Neurosoft, Cortec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Invasive SEEG Depth Electrodes Market Trends and Innovations
Active electrode design is compressing the boundary between diagnostic localization and therapeutic intervention, with hardware platforms absorbing neurostimulation functions that previously required separate device implantation.
Hybrid macro-micro electrode configurations are integrating precision recording contacts alongside standard clinical channels, enabling single-procedure acquisition of both epileptogenic zone delineation and functional cortical mapping. Academic centers in Germany and the Netherlands are piloting these arrays for insular and opercular investigations. The technology is integrating previously separate diagnostic workflows, reducing total implantation procedures per patient.
EU MDR technical documentation requirements for implantable neural devices are mandating extended clinical follow-up data for novel contact geometries, forcing manufacturers to maintain post-market surveillance registries. Notified bodies are rejecting predicate-based equivalence arguments for electrode designs with modified contact spacing or insulation materials. German manufacturers are responding by pre-submission engagement with BfArM to anchor conformity assessment expectations.
Hospital procurement for SEEG electrodes is consolidating under centralized neurosurgery supply agreements, displacing individual surgeon preference purchasing. Integrated delivery networks in the US are negotiating multi-year sole-source contracts that bundle electrodes with stereotactic planning software. This concentration is most visible in California and Texas health systems, where epilepsy surgery volumes justify direct manufacturer relationships over distributor intermediaries.
Invasive SEEG Depth Electrodes Market Segmentation
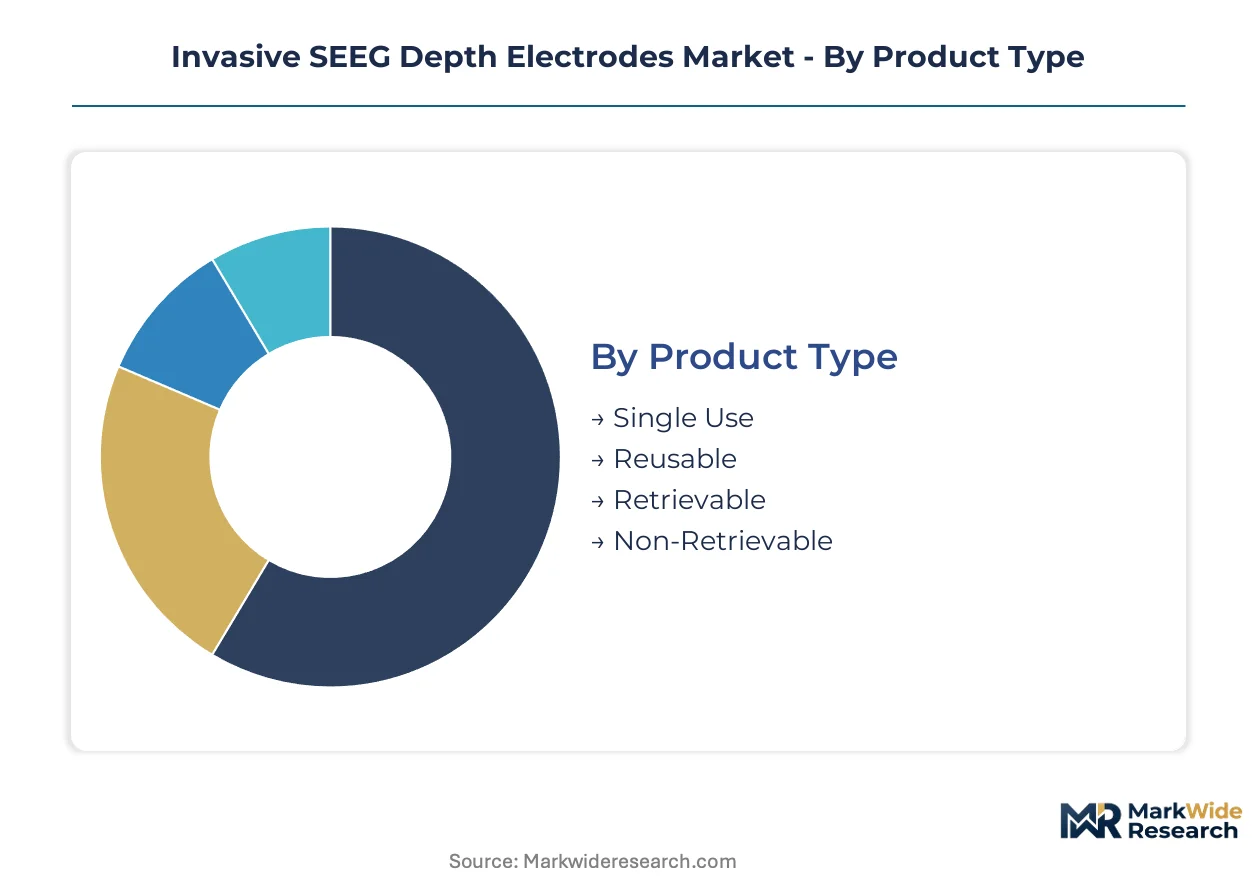
SEEG electrode procurement splits across clinical workflows, sterilization economics, and neurosurgical subspecialization. Manufacturers align product portfolios to infection control mandates, reimbursement tiers, and the procedural volume concentration at academic epilepsy centers.
Product Type:
Hospital procurement teams differentiate electrodes by total cost of ownership, balancing upfront unit price against sterilization validation, reprocessing labor, and liability exposure.
- Single Use:Polymer-insulated platinum-iridium conductors packaged for immediate implantation eliminate ethylene oxide validation cycles. German university hospitals under G-DRG budgeting favor disposables to compress procedural turnaround and avoid centralized sterile processing bottlenecks.
- Reusable:Stainless steel electrode sets withstand 50+ autoclave cycles but require documented bioburden testing per EU MDR post-market surveillance. Mid-tier US community hospitals pursued reusables to amortize capital costs until FDA scrutiny of reprocessing protocols eliminated margin advantages.
- Retrievable:Temporary implant designs with extraction tethers enable staged diagnostic protocols.
- Non-Retrievable:Permanent implant configurations for patients proceeding directly to resective surgery.
Single Use leads volumes today; Retrievable configurations are gaining share fastest as staged epilepsy protocols expand.
Technology:
Contact density and spatial resolution determine electrode selection for specific anatomical targets, with hybrid designs bridging diagnostic and therapeutic functions.
- Electrode Array:Linear multi-contact assemblies with 5-18 recording sites remain the clinical default for mesial temporal lobe coverage.
- Microelectrode:Ultra-fine 0.8 mm diameter conductors with sub-millimeter contact spacing capture single-unit activity for functional mapping. Academic centers in the Netherlands deploy microelectrodes for insular cortex investigations where standard macroelectrodes risk vascular injury.
- Macroelectrode:Robust 1.3 mm diameter designs with platinum-iridium contacts spaced at 10 mm intervals dominate deep structure implantation. German stereotactic protocols specify macroelectrodes for amygdalohippocampal coverage where mechanical stability outweighs resolution demands.
- Combination Electrode:Integrated macro-micro configurations merge clinical-grade channels with research-precision contacts in single implantation trajectories.
Macroelectrode platforms anchor current procedural volumes; Combination Electrode configurations are climbing the fastest as academic centers consolidate diagnostic workflows.
End User:
Site-specific regulatory compliance, case volume thresholds, and research affiliations shape electrode purchasing authority and technical specifications.
- Hospitals:General medical centers with epilepsy monitoring units purchase standard electrode configurations through group purchasing organizations. US integrated delivery networks in California and Texas negotiate sole-source contracts bundling electrodes with stereotactic planning software.
- Research Institutions:Neuroscience laboratories acquire specialized microelectrode arrays for electrophysiology studies outside clinical reimbursement pathways.
- Specialized Clinics:Standalone epilepsy centers focus on diagnostic monitoring without surgical capability.
- Academic Centers:University-affiliated programs combine clinical volume with research protocols demanding hybrid electrode technologies and extended follow-up registries.
Academic Centers lead volumes today; Specialized Clinics are expanding most quickly as regional epilepsy networks decentralize presurgical evaluation.
Application:
Clinical indication determines electrode contact count, implantation depth, and duration of monitoring, with emerging therapeutic uses extending hardware utility beyond pure diagnosis.
- Epilepsy Monitoring:Drug-resistant seizure localization consumes the majority of SEEG implantations. Germany's national framework for presurgical evaluation under G-DRG reimbursement stabilizes electrode demand across university hospitals.
- Tumor Localization:Eloquent cortex mapping prior to glioma resection employs similar stereotactic approaches with modified electrode trajectories.
- Functional Mapping:Cortical stimulation for language and motor localization during awake procedures.
- Neurostimulation:Therapeutic closed-loop systems repurposing diagnostic electrodes for responsive stimulation delivery.
Epilepsy Monitoring dominates current utilization; Neurostimulation applications are expanding most quickly as hardware platforms absorb therapeutic functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stereotactic neurosurgeon concentration in Germany anchors European procedural volumes, while US academic medical centers concentrate expertise in 40-50 tertiary epilepsy programs. Manufacturing and regulatory capabilities cluster in Switzerland, France, and the United States.
Germany
University hospitals in Berlin, Munich, and Heidelberg institutionalize stereoelectroencephalography protocols under G-DRG reimbursement for drug-resistant epilepsy evaluation. BfArM pre-submission engagement accelerates conformity assessment timelines for novel electrode geometries. The Rhine-Ruhr and Bavarian clusters concentrate platinum-iridium microfabrication capabilities serving domestic and export demand.
United States
Academic medical centers in California, Texas, and Massachusetts drive electrode utilization through expanding epilepsy surgery programs. FDA 510(k) pathways govern market access for platinum-iridium conductors, with predicate-based clearances enabling geometric innovation. Integrated delivery networks in the Southwest and Northeast negotiate sole-source contracts bundling electrodes with stereotactic planning software.
Switzerland
Swissmedic oversight of Class III implantable neural devices maintains stringent biocompatibility and traceability standards. The Zurich and Basel metropolitan areas host precision manufacturing for microelectrode arrays serving high-resolution cortical sampling applications. Research collaborations between university hospitals and device manufacturers accelerate hybrid macro-micro electrode development.
France
ANSM regulates post-market surveillance for implantable neural devices under EU MDR alignment, with Paris and Lyon academic centers advancing insular cortex investigation protocols. The Grenoble and Strasbourg clusters specialize in laser-welded contact assembly for reduced-diameter electrodes. National hospital procurement consolidation under regional health agencies standardizes electrode specifications across public institutions.
Netherlands
Academic centers in Amsterdam and Utrecht pilot hybrid electrode configurations for functional mapping during awake procedures. The national healthcare institute evaluates cost-effectiveness of staged diagnostic protocols using retrievable electrode designs. Eindhoven-region microfabrication facilities supply precision components to European electrode assemblers.
Invasive SEEG Depth Electrodes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the invasive SEEG depth electrode landscape. The vendor base stratifies into three tiers: diversified medical technology conglomerates with neurosurgery portfolios, mid-cap neurology device specialists, and regional fabrication houses serving niche academic contracts. Dominant competitive moves include strategic partnerships with stereotactic planning software vendors and backward integration into platinum-iridium alloy production.
Among US-based diversified manufacturers, Ad-Tech Medical and Integra LifeSciences exemplify the conglomerate archetype with established FDA clearances anchoring North American distribution. DIXI Medical, a French specialist, occupies a position within the pure-play tier focused on microelectrode arrays for high-resolution applications. These three companies represent contrasting strategic postures: regulatory leverage through predicate accumulation, in-house materials control, and specialized precision fabrication respectively.
| Leading Market Players |
|---|
| Ad-Tech Medical |
| Integra LifeSciences |
| DIXI Medical |
| PMT Corporation |
| Elekta AB |
| Natus Medical Incorporated |
| Micromed Group |
| Neurosoft |
| Cortec GmbH |
| Others |
Pricing and Supply Chain Analysis
Iridium spot price volatility cascades through platinum-iridium alloy feedstock costs, compressing electrode manufacturing margins and stratifying hospital procurement tiers across German G-DRG budgeting cycles and US integrated delivery network negotiations.
Pricing Analysis
Bundled contracts with stereotactic planning software vendors dominate academic center procurement, while unbundled per-unit pricing persists in mid-tier community hospitals. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platinum-iridium configurations from CE-marked alternatives and stainless steel economy electrodes. Price differentiation hinges on biocompatibility certification grade and volume scale commitments. Cost compression in standard-tier electrodes is intensifying because notified body capacity constraints extend conformity assessment timelines. Community hospitals exhibit highest price sensitivity; tertiary epilepsy centers prioritize contact density over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from US integrated delivery networks and German university hospital procurement offices mandate multi-supplier qualification for platinum-iridium conductors and polymer insulation materials. Manufacturing concentrates in Switzerland, France, and Germany for precision microfabrication, with secondary assembly in the United States. Feedstock draws from South African iridium mining operations and Russian platinum group metal refineries. Single-source vulnerability in laser-welded contact assembly equipment creates procurement bottlenecks. Distribution runs through specialized neurosurgery distributor networks and direct manufacturer relationships with high-volume academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in invasive SEEG depth electrodes rests on hybrid macro-micro electrode adoption shifting procurement toward premium-tier configurations, offsetting platinum group metal feedstock volatility through higher unit value capture.
For Market Incumbents: Anticipate FDA scrutiny of reusable electrode reprocessing protocols by accelerating single-use platform transitions and securing sole-source contracts with Southwest and Northeast US health systems before distributor displacement accelerates. Backward integration into platinum-iridium alloy production anchors margin control against spot price swings. Pre-submission engagement with BfArM secures CE marking pathway priority as notified body capacity constraints deepen. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms bypass established distributor relationships in California and Texas integrated delivery networks. White space concentrates in retrievable electrode configurations for staged diagnostic protocols and microelectrode arrays for insular cortex investigations. Target Netherlands and German academic centers piloting hybrid electrode technologies through research collaboration pathways rather than clinical reimbursement channels. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play microelectrode specialists possessing laser-welded contact assembly capabilities and existing BfArM rapport. Long-term viability centers on dual-use diagnostic-therapeutic hardware platforms absorbing neurostimulation functions. Watch FDA guidance on brain-computer interface peripherals as the inflection signal for reimbursement pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III designation secures German G-DRG reimbursement anchoring and university hospital procurement access. |
| Hospital System Partnership | Sole-source contracts with California and Texas integrated delivery networks displace distributor intermediaries and stabilize volume commitments. |
| Software Companion Development | Stereotactic planning software integration bundles electrode procurement with surgical navigation workflows. |
| Reimbursement Strategy | G-DRG coding alignment for presurgical epilepsy evaluation secures predictable hospital budgeting cycles in Germany. |
| Backward Integration | In-house platinum-iridium alloy production insulates margins from iridium spot price volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with stereotactic neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement registries, and CMS Medicare reimbursement data. Bottom-up electrode shipment triangulation against top-down epilepsy surgery procedural volume estimates anchored market sizing.
Historical reference periods spanning pre-MDR and post-MDR implementation phases anchored the forecast window to regulatory transition impacts. The analytical framework modeled segmentation across product type, technology configuration, end-user site classification, and application indication throughout the projection horizon. CAGRs derived from procedural volume elasticity to reimbursement policy changes and platinum-iridium alloy price trajectory assumptions. Forecast inputs incorporated stereotactic neurosurgeon training pipeline constraints and EU notified body capacity expansion timelines.
Notified body designation delays, iridium supply disruption, and FDA brain-computer interface guidance revision are the dominant revision risks to the outlook. Deviation in notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Pectus Bar System Market
Medical Devices
Conduction Vaporizers Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Trocars Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Prescription Goggles Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Feeding Tubes Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Global Infusion Pump Software Market