
 United Kingdom Ultrasound Devices Market | 2026-2036
United Kingdom Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Ultrasound Devices Market Analytics
The NHS net-zero supplier roadmap is repositioning procurement criteria toward energy-efficient imaging platforms. Siemens Healthineers AG leverages its installed base across NHS trusts to sustain service revenue streams. GE Healthcare anchors its position through R&D intensity in compact system architectures. Koninklijke Philips NV differentiates via AI-integrated workflow platforms that reduce scan times in high-throughput settings.
Ultrasound devices generate real-time anatomical images through piezoelectric transducers operating at frequencies between two and fifteen megahertz, with beamforming algorithms processing reflected acoustic echoes for diagnostic or therapeutic guidance. Cart-based systems dominate hospital radiology departments due to superior image resolution and multi-probe configurability, while handheld ultrasound is displacing traditional stethoscopes in emergency departments and ward-based triage where portability outweighs raw performance. Three-dimensional and four-dimensional imaging technologies command premium positioning in fetal monitoring and cardiac applications where volumetric data transforms clinical decision-making.
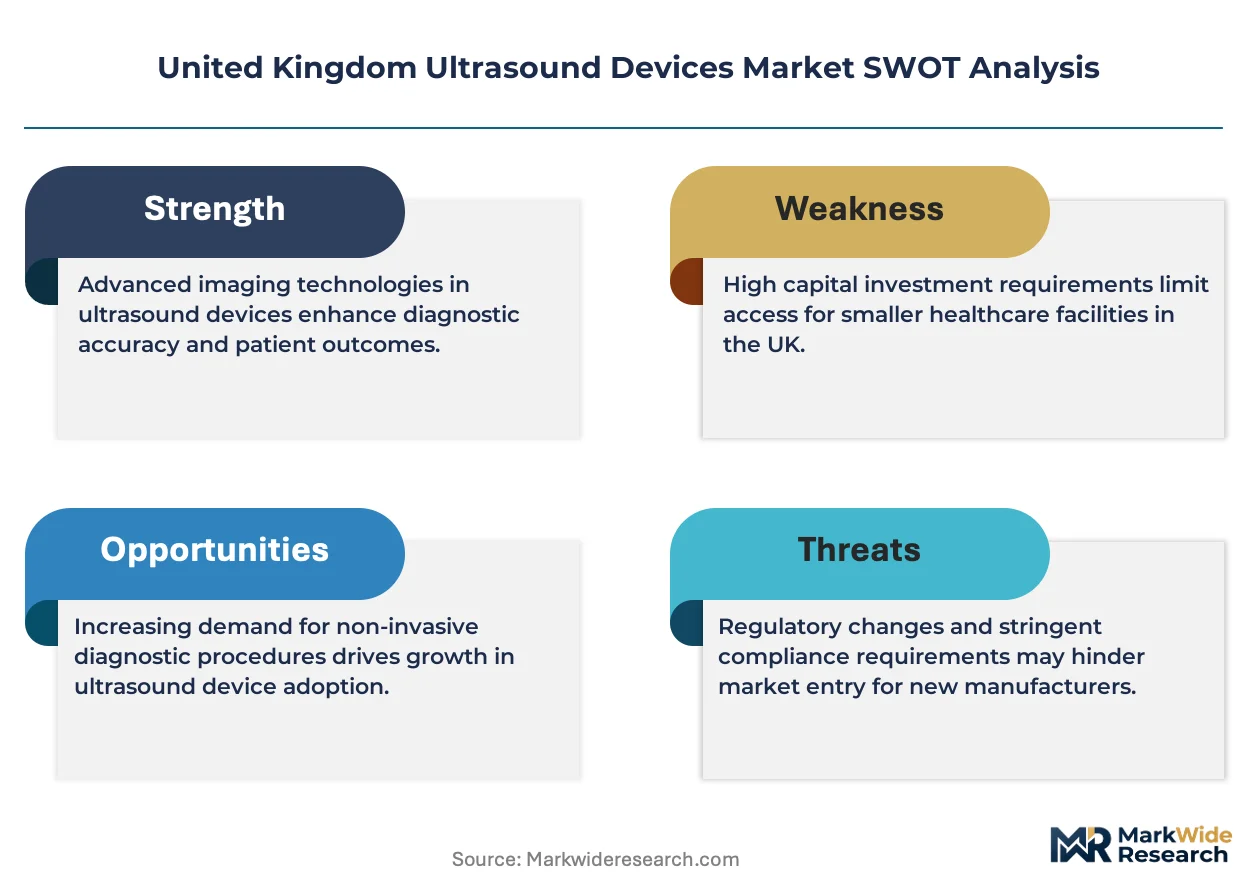
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements that determine market access for imported devices, while NHS England's clinical commissioning frameworks shape purchasing volumes and specification floors across integrated care systems. The Care Quality Commission's equipment safety standards mandate traceable maintenance records that extend vendor accountability beyond point-of-sale. Stakeholders must monitor how the UKCA-CE divergence timeline reshapes compliance costs for European manufacturers serving British healthcare providers.
Market Dynamics
NHS England's net-zero supplier roadmap is compressing capital equipment replacement cycles while redirecting procurement budgets toward energy-efficient imaging platforms that reduce operational carbon intensity.
Growth Catalysts
- Point-of-care expansion:Acute care trusts are deploying handheld systems in emergency departments and ward-based triage, displacing traditional stethoscopes where rapid anatomical assessment accelerates clinical decision-making.
- NHS net-zero targets:The supplier roadmap mandates carbon footprint disclosure for medical devices, creating preferential purchasing pathways for manufacturers with verified lifecycle emissions reductions.
- AI-integrated workflows:Machine learning algorithms embedded in beamforming systems are reducing scan times in high-throughput radiology departments across London and Greater Manchester health innovation clusters.
Market Restraints
- UKCA marking divergence:The Medicines and Healthcare products Regulatory Agency's phased transition from CE marking is elevating compliance costs for European manufacturers serving British healthcare providers.
- Transducer supply concentration:Piezoelectric crystal fabrication for high-frequency probes depends on specialized Asian component suppliers, exposing NHS trusts to extended lead times.
- Cart-based system obsolescence risk:Premium departmental installations face accelerated depreciation as compact architectures and handheld formats capture incremental clinical applications.
Strategic Opportunities
- Rural integrated care systems:Community hospitals in Cornwall and Cumbria remain underserved by advanced imaging, creating deployment opportunities for portable systems with teleradiology connectivity.
- Fetal monitoring specialization:Three-dimensional and four-dimensional volumetric imaging commands premium positioning in obstetrics where real-time anatomical reconstruction transforms prenatal diagnostic confidence.
- Service revenue unbundling:Maintenance contracts and probe replacement programs are separating from hardware sales, enabling recurring revenue models that extend vendor accountability beyond point-of-sale.
Industry Challenges
- Sonographer workforce constraints:Specialized training requirements for cardiac and musculoskeletal applications are limiting scan throughput in trusts without dedicated residency pipelines.
- Legacy PACS integration:Picture archiving and communication systems in older NHS facilities require costly middleware adaptation to accommodate AI-enhanced image formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Ultrasound Devices Market |
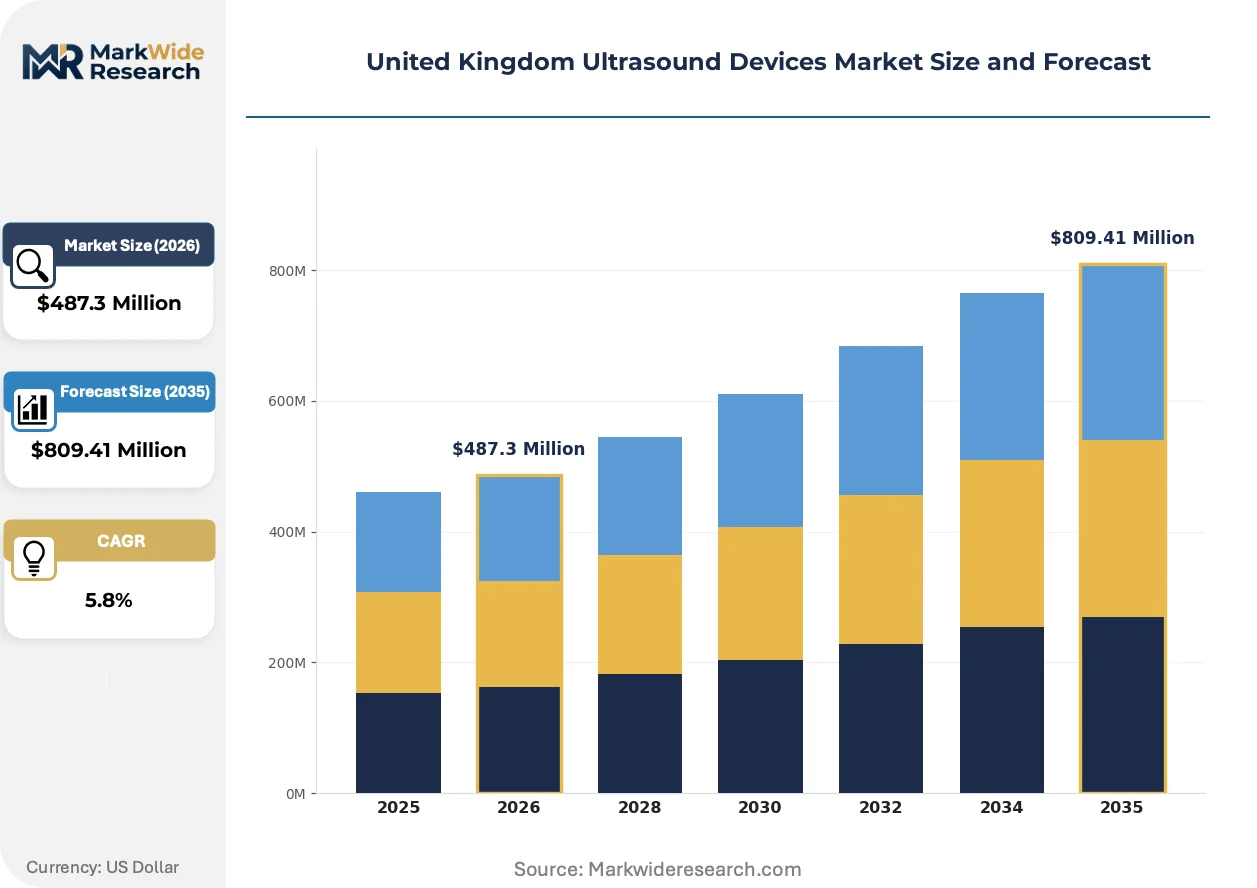
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Ultrasound, Cart-based Ultrasound, Portable Ultrasound, Trolley-based Ultrasound Technology: Doppler Ultrasound, 2D Ultrasound, 3D Ultrasound, 4D Ultrasound Application: Diagnostic Imaging, Therapeutic Applications, Fetal Monitoring, Cardiac Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Clinics |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips NV, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Mindray Medical International Limited, Samsung Electronics Co. Ltd, Esaote SpA, Hologic Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Ultrasound Devices Market Evolving Landscape
Workflow automation and miniaturization are converging to redefine where ultrasound examination occurs, collapsing the historical boundary between radiology departments and point-of-care settings.
Handheld ultrasound is overtaking cart-based systems in emergency medicine and primary care triage. These pocket-sized devices transmit images to hospital networks via secure wireless protocols. Acute care trusts in Birmingham and Leeds are standardizing ward-based deployment, compressing time-to-diagnosis for pleural effusion and deep-vein thrombosis.
NHS England's clinical commissioning frameworks are mandating energy efficiency metrics in capital equipment tenders. The Care Quality Commission's equipment safety standards now incorporate carbon disclosure requirements. High-throughput trusts in London are prioritizing systems with verified lifecycle assessments to meet integrated care system sustainability targets.
After-sales service unbundling is restructuring vendor-buyer relationships across integrated care systems. Hardware procurement teams now negotiate probe replacement and maintenance contracts through separate commercial frameworks. This bifurcation is most visible in Greater Manchester, where procurement consortia are consolidating multi-trust service agreements to extract volume-based pricing on consumables.
United Kingdom Ultrasound Devices Market Segmentation
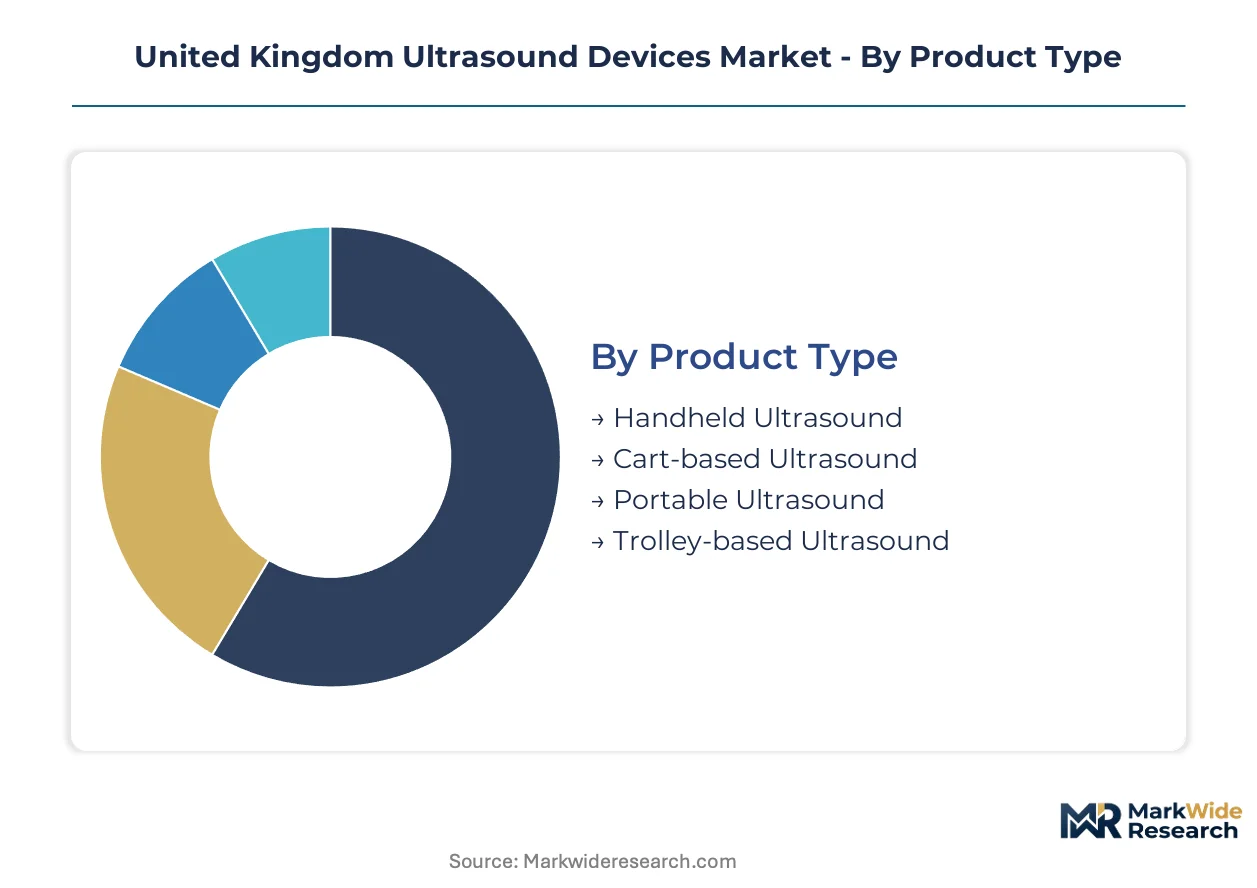
Segmentation in the United Kingdom ultrasound devices market reveals how capital allocation, clinical workflow requirements, and regulatory compliance intersect to shape procurement decisions across NHS trusts and private providers. Understanding these divisions exposes where technology transitions create displacement risk and where installed bases generate defensive revenue streams.
Product Type:
Capital intensity varies sharply across form factors, with cart-based systems demanding the highest upfront investment while handheld units restructure total cost of ownership through distributed deployment models.
- Cart-based Ultrasound:These systems integrate high-channel-count beamforming processors and multi-probe switching architectures that deliver diagnostic-grade resolution for radiology departments. NHS trusts in London concentrate procurement here for high-throughput abdominal and vascular imaging where image fidelity determines clinical confidence.
- Handheld Ultrasound:Pocket-sized transducer-processor units transmit images via secure wireless protocols to hospital networks. Acute care trusts in Birmingham and Leeds are standardizing ward-based deployment to compress time-to-diagnosis for pleural effusion and deep-vein thrombosis where portability outweighs raw performance specifications.
- Portable Ultrasound:Mid-size systems balance mobility with processing power for community hospitals and outreach clinics.
- Trolley-based Ultrasound:Compact wheeled units serve secondary diagnostic roles in smaller NHS facilities with constrained capital budgets.
Cart-based systems absorb the bulk of installed capacity across teaching hospitals and major acute trusts; handheld ultrasound is expanding most quickly through point-of-care standardization in emergency medicine.
Technology:
Technology tiers separate premium positioning from commodity functionality, with advanced volumetric imaging commanding price multiples that reflect specialized transducer arrays and computational reconstruction requirements.
- 4D Ultrasound:Real-time volumetric rendering captures moving anatomical structures through high-density matrix transducers and parallel processing architectures. Fetal monitoring units in Greater Manchester health innovation clusters prioritize these systems where real-time anatomical reconstruction transforms prenatal diagnostic confidence and supports complex intervention planning.
- Doppler Ultrasound:Frequency-shift detection algorithms visualize blood flow velocity and direction for cardiac and vascular assessment. Cardiology departments across integrated care systems deploy these capabilities for valvular function evaluation and shunt detection where hemodynamic data guides therapeutic decisions.
- 2D Ultrasound:Conventional B-mode imaging remains the workhorse modality for general diagnostic screening.
- 3D Ultrasound:Static volumetric acquisition supports reconstructive surgical planning and specialized obstetric applications.
2D systems retain the largest installed base across community settings; 4D ultrasound is climbing the fastest through obstetric specialization and premium service differentiation.
Application:
Application segmentation tracks how clinical use cases determine specification requirements and procurement authority, with therapeutic applications introducing capital equipment into interventional workflows previously served by disposable instruments.
- Diagnostic Imaging:General anatomical assessment across abdominal, pelvic, and superficial structures constitutes the foundational use case. Radiology departments in London and Greater Manchester concentrate scan volume here, with AI-integrated workflow platforms reducing examination times in high-throughput settings.
- Fetal Monitoring:Obstetric applications demand specialized transducer frequencies and safety protocols for repeated exposure. Three-dimensional and four-dimensional volumetric imaging commands premium positioning where real-time anatomical reconstruction transforms prenatal diagnostic confidence.
- Cardiac Imaging:Echocardiography requires phased-array transducers and specialized presets for chamber quantification and wall motion analysis.
- Therapeutic Applications:Image-guided intervention spans focused ultrasound ablation, needle guidance, and intraoperative navigation.
Diagnostic imaging absorbs the bulk of installed capacity through general radiology deployment; therapeutic applications are gaining share fastest as interventional radiology expands ultrasound-guided procedures.
End User:
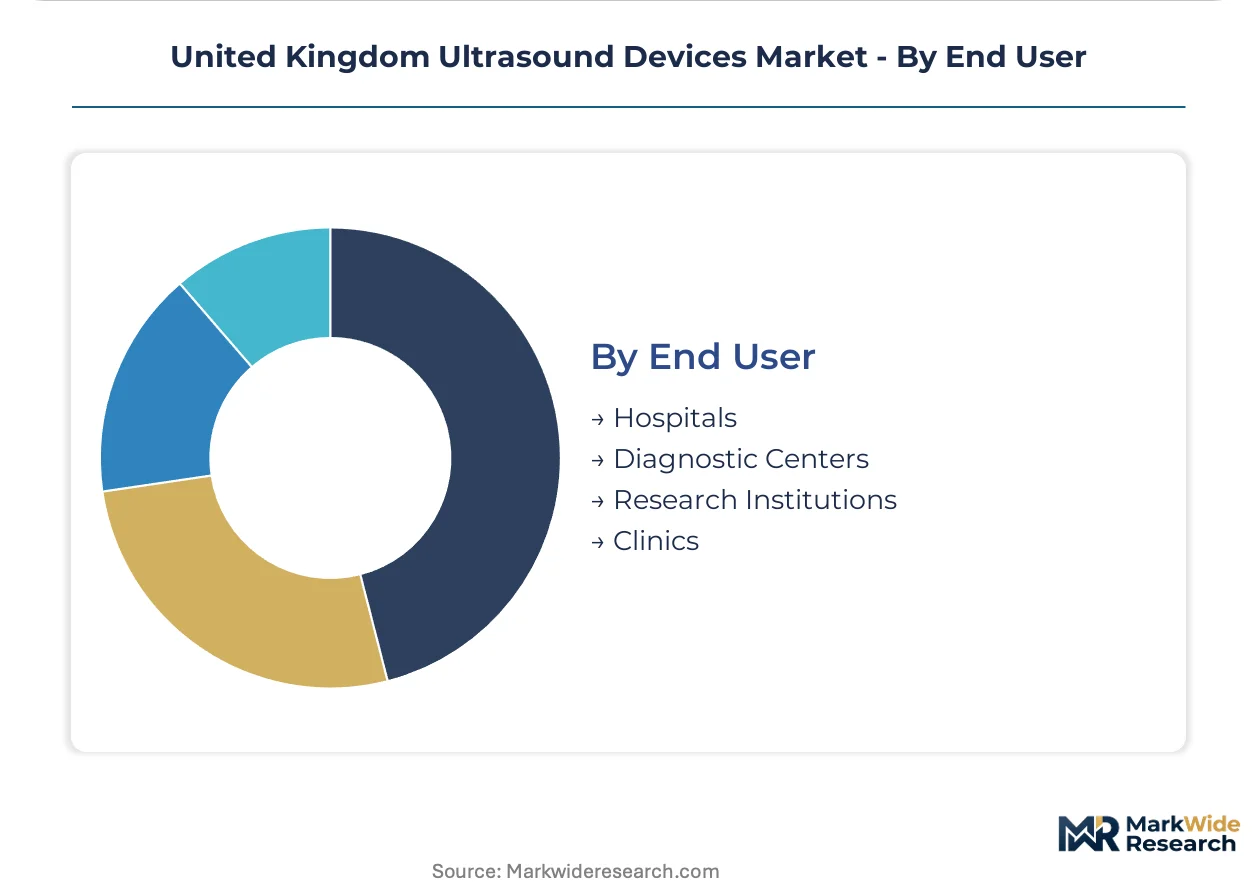
End-user categories reveal how purchasing authority, maintenance infrastructure, and utilization patterns fragment demand across facility types with diverging capital cycles and compliance obligations.
- Hospitals:Acute care trusts and foundation hospitals deploy the full spectrum of system tiers across radiology, cardiology, obstetrics, and emergency departments. NHS England's net-zero supplier roadmap is compressing capital equipment replacement cycles while redirecting procurement budgets toward energy-efficient imaging platforms.
- Diagnostic Centers:Independent imaging facilities and NHS community diagnostic hubs prioritize throughput optimization and teleradiology connectivity. These operators concentrate in urban corridors where population density justifies dedicated capital investment separate from hospital-based provision.
- Clinics:General practice and specialist outpatient settings increasingly adopt handheld systems for point-of-care triage.
- Research Institutions:Academic medical centers and translational research facilities drive early adoption of experimental imaging modalities and AI validation studies.
Hospitals retain the dominant share of capital deployment through consolidated procurement frameworks; diagnostic centers are expanding most quickly through NHS community diagnostic center expansion policy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London and the Greater Manchester health innovation cluster concentrate diagnostic imaging demand, while procurement patterns diverge across England's integrated care systems based on capital allocation and net-zero compliance timelines.
London and the Southeast
High-throughput radiology departments in London trusts prioritize AI-integrated workflow platforms that reduce scan times. NHS England's clinical commissioning frameworks mandate energy efficiency metrics in capital tenders, compressing replacement cycles for legacy cart-based systems. The Greater Manchester health innovation cluster drives adoption of four-dimensional volumetric imaging for fetal monitoring applications.
Midlands
Acute care trusts in Birmingham standardize handheld ultrasound deployment across emergency departments and ward-based triage. The Care Quality Commission's equipment safety standards enforce traceable maintenance records that extend vendor accountability. Leicester and Nottingham university hospitals anchor research validation studies for experimental imaging modalities.
North England
Integrated care systems in Leeds deploy portable systems with teleradiology connectivity to compress time-to-diagnosis for pleural effusion. NHS net-zero supplier roadmaps redirect procurement budgets toward energy-efficient platforms with verified lifecycle emissions reductions. Sheffield teaching hospitals maintain installed capacity for cardiac and vascular imaging.
Scotland
NHS Scotland's territorial health boards concentrate procurement through national frameworks that consolidate multi-trust service agreements. The country's medical device regulator enforces UKCA marking requirements that determine market access for imported devices. Edinburgh and Glasgow academic medical centers drive early adoption of point-of-care standardization in emergency medicine.
Wales and Northern Ireland
Community hospitals in rural integrated care systems remain underserved by advanced imaging, creating deployment opportunities for portable architectures. Welsh health boards negotiate probe replacement and maintenance contracts through separate commercial frameworks from hardware procurement. Belfast trusts face extended lead times for piezoelectric crystal components sourced from specialized Asian suppliers.
United Kingdom Ultrasound Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established service infrastructure. Siemens Healthineers AG, GE Healthcare, and Koninklijke Philips NV anchor the premium tier through installed base leverage and R&D intensity. Mid-scale specialists occupy portable and handheld segments where compact architectures displace departmental systems. Dominant competitive moves include after-sales service unbundling to extract recurring revenue and AI-integrated workflow differentiation to reduce examination times in high-throughput settings.
Among Germany-based diversified health technology groups, Siemens Healthineers AG occupies a position exemplifying installed base defense through service revenue streams. GE Healthcare, a US-domiciled conglomerate, anchors the scale-driven tier through compact system architecture development. Koninklijke Philips NV, a Netherlands-based technology group, represents AI-integrated workflow specialization that reduces scan times across London and Greater Manchester health innovation clusters.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Mindray Medical International Limited |
| Samsung Electronics Co. Ltd |
| Esaote SpA |
| Hologic Inc. |
| Others |
Value Network & Pricing Analysis
NHS England's net-zero supplier roadmap gates qualified supply access and premium-tier pricing power, compelling manufacturers to disclose verified lifecycle emissions reductions before tender participation while elevating procurement floors for energy-efficient imaging platforms across integrated care systems.
Pricing Analysis
Value-based pricing anchored to scan throughput and equipment uptime dominates procurement frameworks across NHS trusts. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated cart-based systems from compact portable units and handheld devices, with differentiation driven by UKCA certification tier and bundled after-sales service scope. Cost compression in the economy handheld tier is intensifying because of probe replacement commoditization and Asian component sourcing. Community diagnostic hubs exhibit highest price sensitivity due to constrained capital budgets, while London teaching hospitals prioritize performance specifications over unit economics.
Supply Chain Analysis
UKCA marking requirements enforced by the Medicines and Healthcare products Regulatory Agency gate market access for European manufacturers serving British healthcare providers. Piezoelectric crystal fabrication draws from specialized suppliers in China, Japan, and South Korea, creating concentrated dependency for high-frequency transducer arrays. Single-source vulnerability in ceramic substrate supply exposes NHS trusts to extended lead times for probe replacement programs. Distribution runs through authorized service networks that consolidate multi-trust maintenance contracts across integrated care systems in Greater Manchester and the Midlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom ultrasound devices market reads as a cost-of-compliance story where the UKCA-CE divergence timeline constructs a barrier-to-entry moat favoring manufacturers with established regulatory affairs infrastructure and verified lifecycle assessment capabilities.
For Market Incumbents: Extend service revenue unbundling to capture recurring maintenance and probe replacement contracts separate from hardware procurement, while accelerating AI-integrated workflow development to defend against handheld system displacement in emergency departments. Deepen backward integration into probe manufacturing to mitigate Asian component supply concentration risks. For New Entrants and Emerging Players: Enter via rural integrated care systems in Cornwall and Cumbria where community hospitals remain underserved by advanced imaging and procurement consolidation has lagged metropolitan clusters. Target portable systems with teleradiology connectivity as the most penetrable segment, leveraging direct sales to smaller trusts outside national framework concentration. For Investors and Strategic Acquirers: NHS England's publication of verified carbon disclosure thresholds for capital equipment tenders is the leading indicator that compliance infrastructure will separate viable acquisition targets from stranded asset risks across the projection horizon. Prioritize platforms with established UKCA technical documentation and service network density over pure technology plays.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Technical Documentation Investment | Accelerates market access for European manufacturers ahead of CE marking divergence deadlines enforced by MHRA. |
| AI-Integrated Workflow Platform Development | Reduces scan times in high-throughput London trusts where NHS clinical commissioning frameworks mandate efficiency metrics. |
| Probe Replacement Program Unbundling | Extracts recurring revenue from installed base across Greater Manchester multi-trust service agreements. |
| Handheld System Standardization | Captures point-of-care expansion in Birmingham and Leeds emergency departments displacing traditional stethoscopes. |
| Teleradiology Connectivity Integration | Enables deployment in rural Welsh and Northern Irish community hospitals with limited on-site specialist coverage. |
Research Methodology
Document review covered MHRA regulatory filings, NHS England procurement framework disclosures, and integrated care system capital equipment tender documents, complemented by interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and sonography department heads. Secondary validation drew from Care Quality Commission equipment safety standards, UKCA marking guidance publications, and trade customs data on piezoelectric component imports. Bottom-up trust-level procurement analysis triangulated against top-down manufacturer revenue segmentation across the United Kingdom.
Cross-referencing historical replacement cycle patterns with panel input from procurement consortia anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled encompassed product form factor, imaging technology tier, clinical application area, and end-user facility type alongside NHS net-zero compliance status as a qualifying filter. CAGRs were synthesized from equipment shipment trajectories and capital allocation trends reported through national health service financial disclosures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated UKCA divergence timelines or transducer supply chain disruptions originating from East Asian manufacturing concentration. Model assumptions reflect documented NHS net-zero supplier roadmap milestones and integrated care system consolidation patterns. A model refresh is warranted upon material change in MHRA regulatory enforcement posture or NHS England clinical commissioning framework restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
High Flow Ventilators Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Microdebrider Market
Medical Devices
Breathing Circuits Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Brachytherapy Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Europe Medical Devices Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Sialendoscopes Market
Medical Devices
Pediatric Home-Use Medical Devices Market