
 Antimicrobial Coated Medical Devices Market | 2026-2036
Antimicrobial Coated Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Coated Medical Devices Market Outlook
Modular coating platforms is shifting how hospitals evaluate antimicrobial device procurement, replacing single-product contracts with tiered service agreements that bundle coating validation, reprocessing protocols, and infection surveillance. BASF SE leverages its polymer science heritage to anchor high-volume catheter supply chains across European hospital networks. Covalon Technologies Ltd specializes in proprietary silver-alloy formulations that differentiate its portfolio in North American wound care channels. Koninklijke DSM NV competes through bioceramic coating R&D intensity, sustaining patent positions in orthopedic implant surface engineering.
Antimicrobial coated medical devices incorporate biocidal agents—silver ions, copper particles, or quaternary ammonium polymers—into thin-film surface layers applied via plasma deposition, dip coating, or spray processes, with coating thickness typically ranging from 50 nanometers to 50 micrometers depending on substrate geometry and release kinetics. These surfaces reduce biofilm formation on implants, catheters, and surgical instruments, directly lowering healthcare-associated infection incidence and associated mortality. Catheters represent the most mature revenue pool, while polymer-based coating technology captures the fastest growth as manufacturers seek alternatives to metal-ion systems facing environmental discharge scrutiny. Silver nano-coating retains dominant share in surgical instrument applications where rapid bactericidal action outweighs cost premiums.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards shape coating validation protocols, with notified bodies demanding extended biocompatibility testing under ISO 10993 series guidelines. EPA antimicrobial pesticide registration intersects with device regulation when coating claims extend to environmental surfaces, creating dual compliance burdens for manufacturers with broad product portfolios. Stakeholders must monitor evolving EPA FIFRA enforcement against unsubstantiated antimicrobial marketing claims, as this regulatory boundary increasingly determines market access for coating suppliers straddling device and disinfectant classifications.
Market Dynamics
Central line-associated bloodstream infection penalties under US Medicare reimbursement rules are compressing hospital procurement cycles, forcing catheter suppliers to bundle coating validation with device contracts rather than sell standalone hardware.
Growth Catalysts
- Silver-alloy surface engineering:Advanced ion-release kinetics in catheter coatings deliver rapid bactericidal action against multidrug-resistant organisms, accelerating replacement of legacy uncoated devices in US intensive care units.
- EU MDR technical documentation standards:Recertification timelines for Class III devices are shortening development cycles, pushing coating innovators toward modular platform architectures that streamline biocompatibility testing under ISO 10993 guidelines.
- Japan:METI infection control mandates in surgical settings are expanding procurement volumes for antimicrobial-coated orthopedic implants as aging demographics drive joint replacement volumes.
Market Restraints
- Plasma deposition equipment concentration:German and Japanese capital equipment suppliers control thin-film coating system supply, creating capex bottlenecks for mid-scale device manufacturers seeking in-house production capabilities.
- Environmental discharge scrutiny:Silver-ion leaching from coated instruments faces tightening EPA FIFRA enforcement, elevating compliance costs for manufacturers with broad surgical instrument portfolios.
- Bioceramic adhesion limitations:Hydroxyapatite-based coatings on titanium orthopedic substrates exhibit delamination risks under cyclic loading, restricting application to low-stress anatomical sites.
Strategic Opportunities
- Quaternary ammonium polymer systems:Metal-free coating chemistry is absorbing regulatory tailwinds from EU REACH substance restrictions, opening substitution pathways for manufacturers facing silver-ion environmental liabilities.
- Wound care channel expansion:Home healthcare settings in Germany represent underpenetrated demand for antimicrobial dressings as post-acute care shifts outside hospital walls.
- Bioceramic-therapeutic convergence:Integration of antibiotic-eluting layers with structural implant coatings enables localized drug delivery without systemic toxicity, creating premium positioning in revision surgery segments.
Industry Challenges
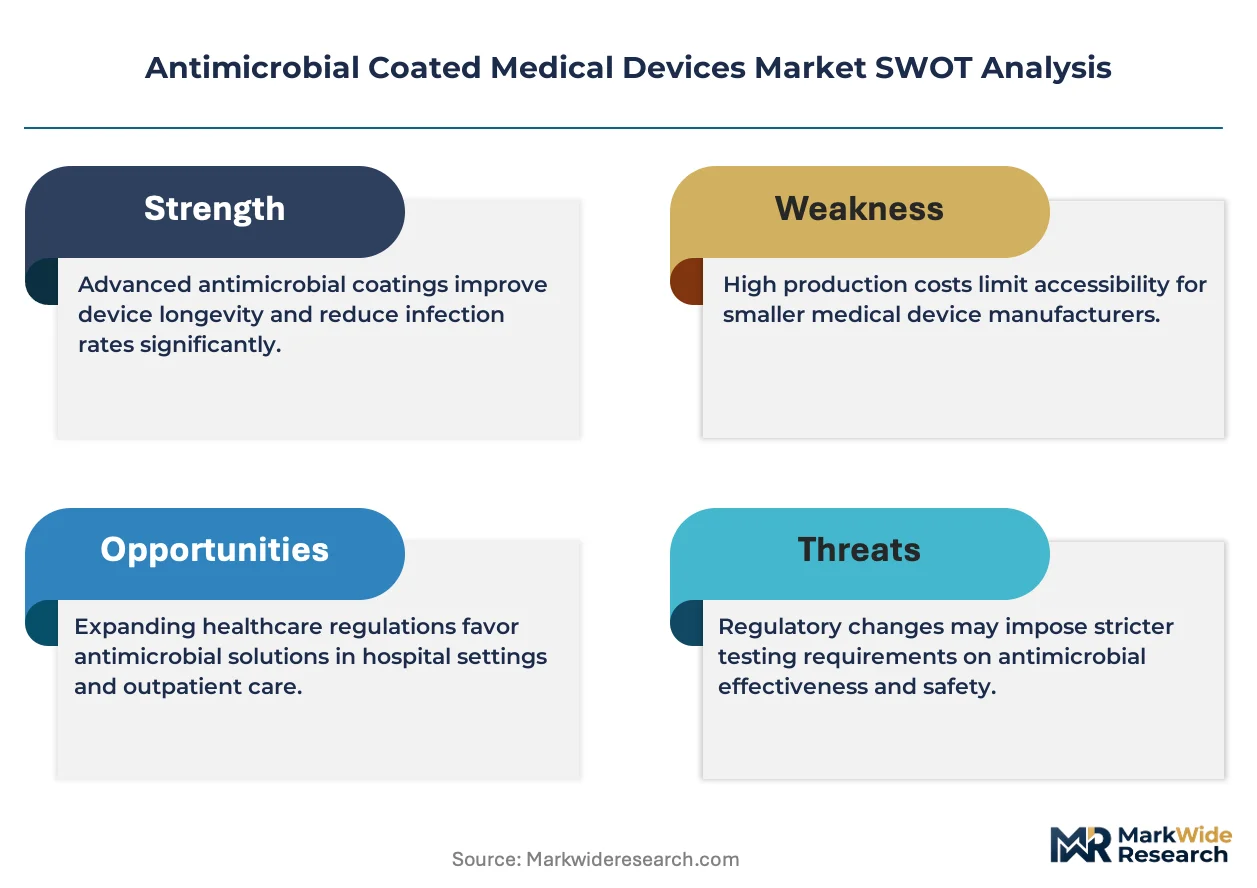
- Coating validation timeline compression:FDA 510(k) premarket notification requirements demand extended biocompatibility testing, stretching R&D calendars for novel surface chemistries.
- Cross-functional talent scarcity:Device manufacturers struggle to recruit specialists combining polymer science expertise with regulatory affairs fluency across dual EPA-FDA jurisdiction boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Coated Medical Devices Market |
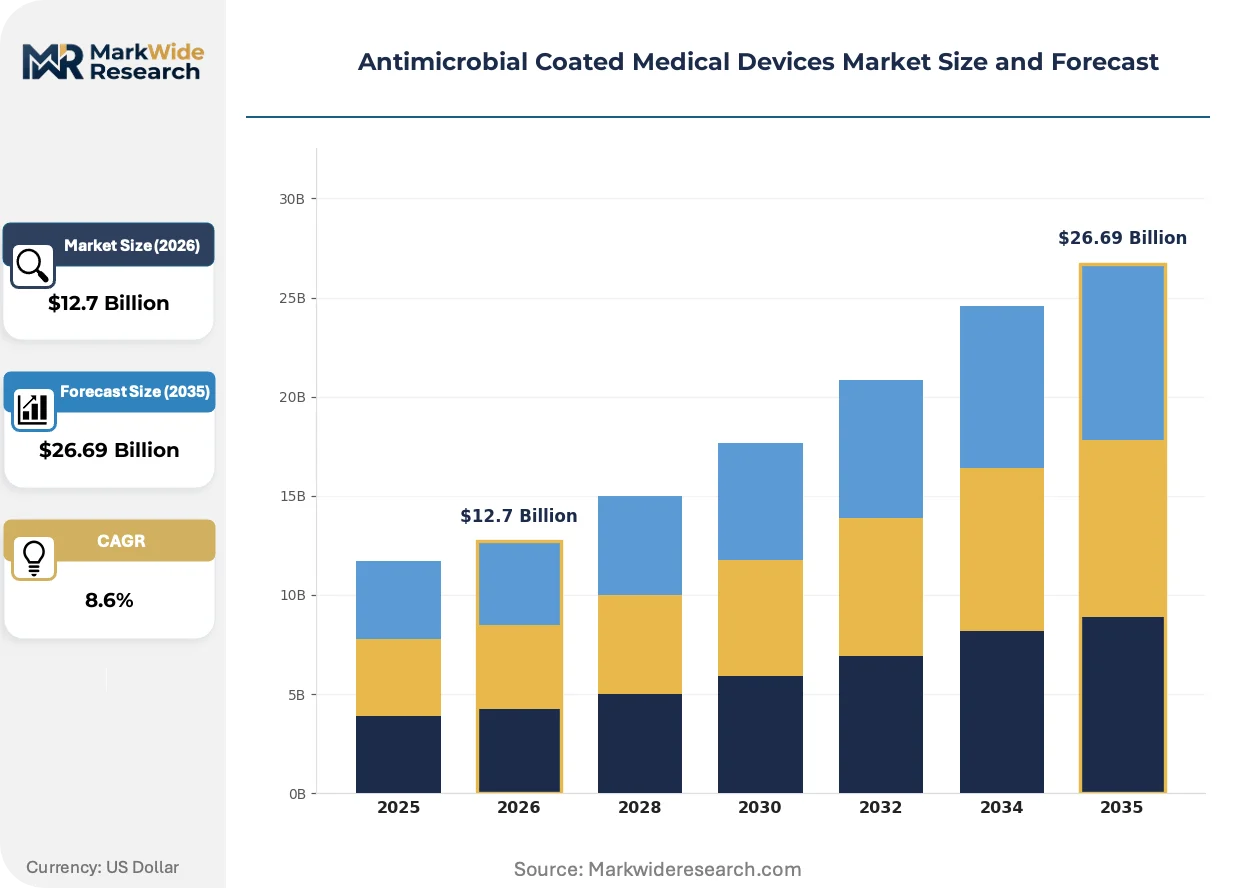
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Surgical Instruments, Catheters, Drapes End User: Hospitals, Clinics, Long-term Care Facilities, Home Care Application: Surgical Procedures, Infection Control, Wound Care, Diagnostics Technology: Silver Nano-coating, Copper Coating, Polymer-based Coating, Bioceramic Coating |
| Companies Covered | BASF SE, Covalon Technologies Ltd, Specialty Coating Systems Inc, AST Products Inc, PPG Industries Inc, Koninklijke DSM NV, Hydromer Inc, BioInteractions Ltd, Akzo Nobel NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Coated Medical Devices Market Strategic Shifts
Surface engineering is absorbing environmental compliance pressures while clinical evidence requirements intensify, reshaping how coating technologies prove value beyond initial bactericidal claims.
Quaternary ammonium polymer coatings are absorbing market share from metal-ion systems as REACH substance restrictions tighten silver discharge limits. European wound care manufacturers are accelerating formulation shifts toward cationic polymer chemistry. This transition is absorbing R&D investment that previously flowed into nano-silver particle refinement.
EU MDR recertification timelines are compressing coating validation protocols for legacy devices. Notified bodies now demand extended ISO 10993 biocompatibility testing for surface modifications. Catheter suppliers with modular platform architectures are absorbing compliance costs more efficiently than single-product competitors.
Hospital procurement teams are consolidating vendor relationships around tiered service agreements bundling coating validation, reprocessing protocols, and infection surveillance. This behavioral shift is absorbing smaller coating specialists into integrated supply chains. United States academic medical centers are absorbing the highest contract complexity as they pioneer outcome-linked reimbursement models.
Antimicrobial Coated Medical Devices Market Segmentation
Coating chemistry and substrate geometry determine reimbursement eligibility, regulatory pathway, and infection prevention efficacy across antimicrobial device procurement. Segmentation reveals how silver-ion release kinetics, implant loading conditions, and care setting workflow constraints reshape vendor competitive positioning.
Product Type:
Coating thickness specifications and substrate material compatibility define manufacturing complexity and clinical validation requirements across device categories.
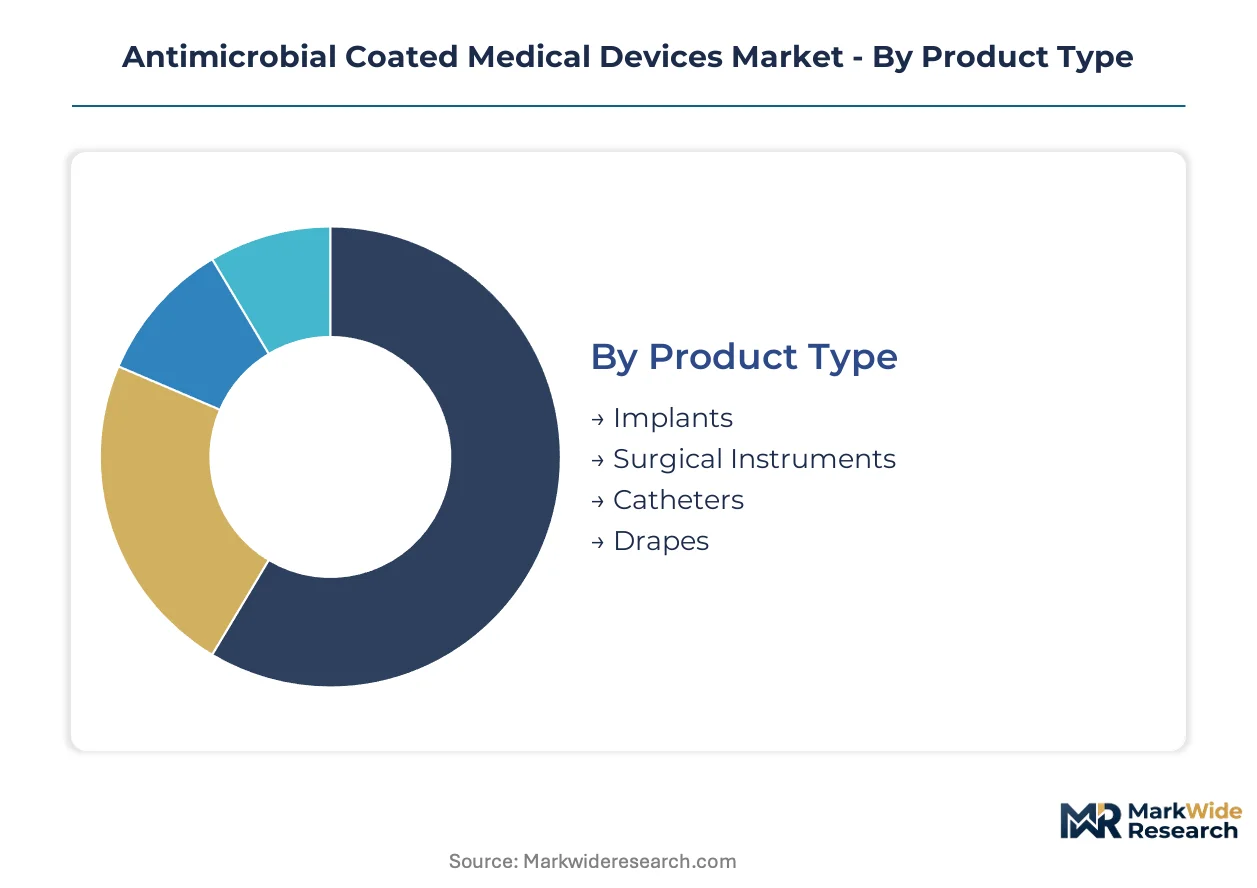
- Catheters:Central venous and urinary catheter coatings employ 50-200 nanometer silver-alloy layers with controlled ion-release profiles. US hospital procurement teams bundle coating validation with device contracts under Medicare CLABSI penalty frameworks. Catheters lead on scale; surgical instruments lead on momentum.
- Surgical Instruments:Scalpels, forceps, and retractors receive 10-50 micrometer quaternary ammonium polymer films or nano-silver depositions for rapid bactericidal action between sterilization cycles. German outpatient surgical centers drive replacement demand as EU MDR recertification accelerates legacy device turnover.
- Implants:Orthopedic and cardiovascular substrates require hydroxyapatite or titanium oxide interlayers to ensure bioceramic adhesion under cyclic mechanical loading.
- Drapes:Non-woven polypropylene fabrics incorporate cationic polymer surface treatments for intraoperative bacterial barrier protection.
Catheters lead on scale; surgical instruments lead on momentum.
End User:
Capital equipment budgets, infection surveillance infrastructure, and reprocessing protocol sophistication determine coating technology adoption thresholds across care settings.
- Hospitals:Academic medical centers in the United States deploy tiered service agreements bundling coating validation, reprocessing training, and CLABSI outcome reporting. Japan's tertiary hospitals absorb premium bioceramic-coated orthopedic implants under METI surgical infection mandates. Hospitals concentrate procurement volume; home care settings expand most quickly.
- Clinics:Ambulatory surgical centers prioritize polymer-based coatings for instrument reprocessing efficiency and EPA FIFRA compliance simplicity.
- Long-term Care Facilities:Skilled nursing facilities in Germany adopt antimicrobial urinary catheters for indwelling device populations with limited mobility.
- Home Care:Post-acute wound dressing applications absorb metal-free quaternary ammonium formulations as environmental discharge scrutiny tightens.
Hospitals concentrate procurement volume; home care settings expand most quickly.
Application:
Clinical endpoint measurement protocols and regulatory claim substantiation requirements differentiate coating performance validation across use cases.
- Surgical Procedures:Orthopedic and cardiovascular interventions demand coating systems with dual structural and antimicrobial functions. Implant surface engineering must demonstrate ISO 10993 biocompatibility under extended cyclic loading conditions. Surgical procedures anchor revenue concentration; wound care gains share fastest.
- Infection Control:Environmental surface coatings face dual EPA-FDA jurisdiction when device claims overlap with disinfectant registrations.
- Wound Care:Chronic wound dressings in German home healthcare settings absorb cationic polymer formulations as post-acute care shifts outside hospital walls.
- Diagnostics:Endoscope and biopsy device channels require thin-film coatings that maintain optical clarity and mechanical flexibility.
Surgical procedures anchor revenue concentration; wound care gains share fastest.
Technology:
Deposition method, release kinetics, and environmental fate determine regulatory pathway efficiency and manufacturing capital intensity.
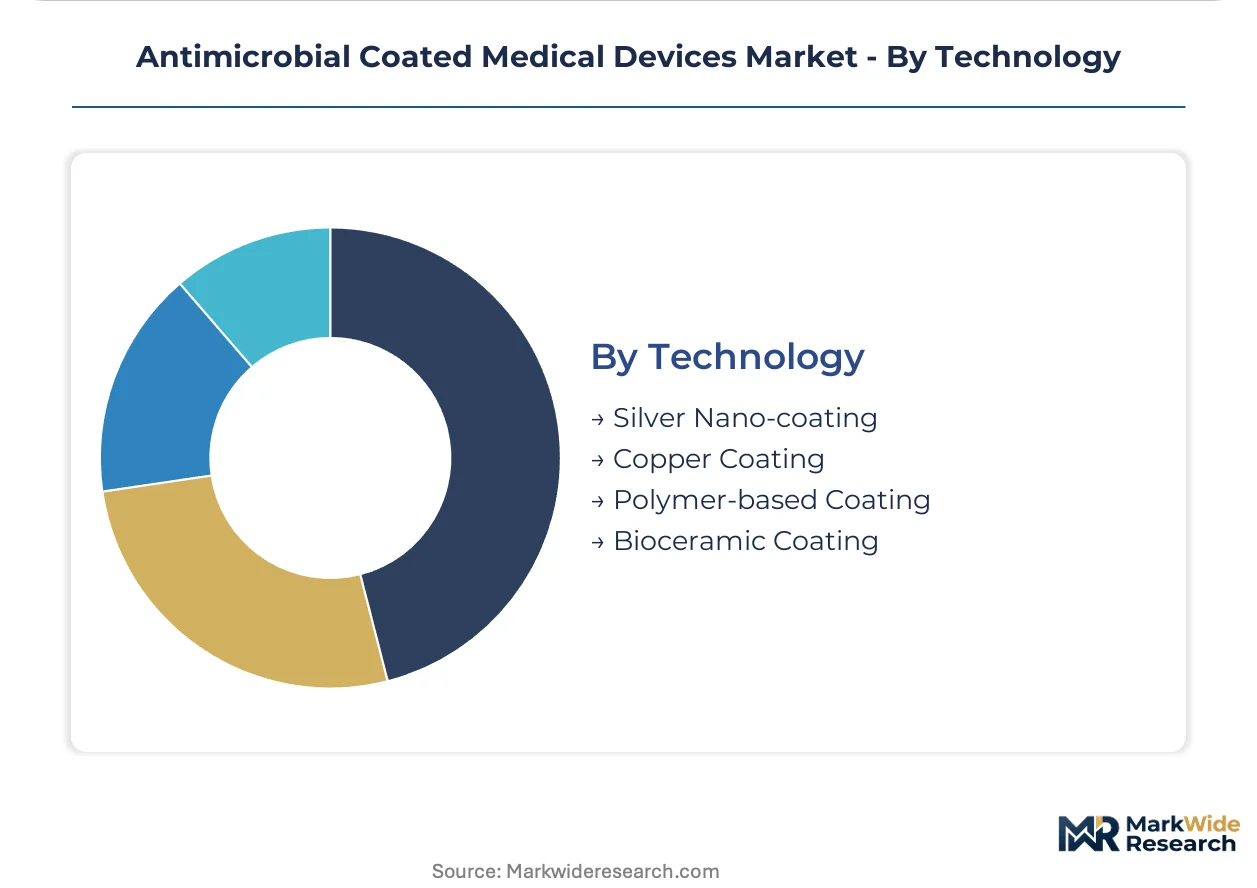
- Silver Nano-coating:Ion-release kinetics engineered through particle size distribution and matrix polymer density deliver rapid bactericidal action against multidrug-resistant organisms. US surgical instrument applications absorb the highest volume despite EPA FIFRA enforcement tightening on environmental discharge claims. Silver nano-coating dominates current share; polymer-based systems climb the fastest.
- Polymer-based Coating:Quaternary ammonium cationic polymers absorb regulatory tailwinds from EU REACH substance restrictions on metal-ion environmental liabilities. Formulation shifts in European wound care channels accelerate R&D investment migration from nano-silver refinement.
- Copper Coating:Bulk metallic copper and copper-alloy surfaces provide continuous biocidal action through contact-mediated ion release.
- Bioceramic Coating:Hydroxyapatite and titanium oxide interlayers on orthopedic substrates enable osseointegration while delivering localized antimicrobial protection.
Silver nano-coating dominates current share; polymer-based systems climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The antimicrobial coated medical devices industry traces its commercial scale to post-World War II polymer science advances in Germany and subsequent FDA regulatory frameworks established in the United States during the 1970s. These dual origins created divergent innovation pathways that persist in current regional competitive dynamics.
United States
Medicare's Hospital-Acquired Condition Reduction Program penalizes facilities with elevated central line-associated bloodstream infection rates, accelerating catheter coating procurement in academic medical centers. FDA 510(k) premarket notification requirements compress development timelines for surface engineering innovators. The Minneapolis-St. Paul corridor concentrates polymer coating R&D activity alongside major cardiovascular device manufacturers.
Germany
EU MDR technical documentation standards and notified body recertification protocols drive legacy device turnover in outpatient surgical centers. The country's chemical industry heritage anchors thin-film deposition equipment manufacturing and plasma coating system supply. The Rhine-Ruhr industrial cluster hosts specialized coating validation laboratories serving pan-European orthopedic implant manufacturers.
Japan
METI infection control mandates in surgical settings expand procurement volumes for bioceramic-coated orthopedic implants as aging demographics accelerate joint replacement procedures. PMDA regulatory harmonization with FDA standards streamlines coating validation for multinational device suppliers. The Kansai region around Osaka maintains concentration in precision instrument surface treatment facilities.
United Kingdom
NHS England's procurement frameworks increasingly bundle coating validation with device contracts, mirroring US reimbursement-driven purchasing behavior. MHRA post-Brexit regulatory autonomy creates parallel compliance pathways for coating innovators seeking UK market access. The Cambridge-Oxford arc sustains antimicrobial surface research tied to diagnostic device channels.
China
NMPA medical device registration reforms accelerate domestic coating technology substitution for imported catheter systems in tertiary hospitals. The country's dual carbon goals intensify scrutiny of metal-ion environmental discharge from surgical instrument reprocessing. The Yangtze River Delta around Shanghai concentrates contract manufacturing capacity for polymer-based coating formulations.
Antimicrobial Coated Medical Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across coating chemistry complexity and regulatory dossier sophistication. The vendor base stratifies into three tiers: diversified chemical conglomerates with polymer science heritage, specialized coating technology developers with proprietary formulation IP, and contract manufacturers serving private-label device brands. Consolidation pressure intensifies as hospital procurement teams reduce vendor counts through tiered service agreements bundling validation and surveillance.
Among diversified chemical conglomerates, BASF SE and Koninklijke DSM NV occupy positions leveraging materials science portfolios to anchor high-volume supply relationships. Covalon Technologies Ltd exemplifies the specialized coating developer archetype with focused expertise in proprietary surface formulations. These three entities represent distinct strategic postures: scale-driven chemical integration, modular platform specialization, and targeted clinical channel penetration.
| Leading Market Players |
|---|
| BASF SE |
| Covalon Technologies Ltd |
| Specialty Coating Systems Inc |
| AST Products Inc |
| PPG Industries Inc |
| Koninklijke DSM NV |
| Hydromer Inc |
| BioInteractions Ltd |
| Akzo Nobel NV |
| Others |
Value Chain & Pricing Dynamics
Modular coating platform adoption simultaneously compresses unit economics and concentrates procurement leverage among tiered service aggregators. Plasma deposition equipment scarcity in Germany and Japan elevates capital barriers for mid-scale manufacturers while hospital GPOs extract volume discounts from integrated suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared silver-alloy catheter systems from CE-marked polymer alternatives and uncoated legacy devices. Price differentiation hinges on ISO 10993 biocompatibility certification tier and bundled infection surveillance service depth. Pricing pressure stems from Medicare CLABSI penalty frameworks forcing hospitals toward outcome-linked contracts. Academic medical centers exhibit lowest price sensitivity; ambulatory surgical centers face acute budget constraints.
Supply Chain Analysis
Freight cost volatility for silver nitrate precursors and quaternary ammonium monomers elevates working capital requirements across coating formulation networks. Raw material sourcing concentrates in Germany, the United States, and Japan, with plasma deposition equipment manufacturing anchored in German and Japanese industrial clusters. Supply chain risk centers on single-source dependency for thin-film coating systems. Distribution runs through hospital GPO contracts and specialized wound care distributors serving post-acute channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial coated medical devices constitute a late-cycle quality story as infection prevention metrics harden into reimbursement gatekeepers. Hospital procurement teams now demand coating validation bundled with device contracts, elevating specification intensity.
For Market Incumbents: Extend modular platform architectures to absorb EU MDR recertification compliance costs more efficiently than single-product competitors. Deepen backward integration into silver-alloy precursor supply to defend margin position against environmental discharge scrutiny tightening under EPA FIFRA enforcement. Lock in tiered service agreements with US academic medical centers before outcome-linked reimbursement models mature. For New Entrants and Emerging Players: German home healthcare wound care settings represent an underserved buyer archetype absorbing metal-free quaternary ammonium formulations as post-acute care shifts outside hospital walls. Target ambulatory surgical centers in EU outpatient networks accelerating legacy device turnover under MDR timelines. Lead with EPA FIFRA compliance simplicity as the go-to-market wedge against silver-ion incumbents facing environmental liability. For Investors and Strategic Acquirers: Roll-up economics work for specialized coating technology developers because hospital procurement consolidation is absorbing smaller vendors into integrated supply chains. Focus acquisition screening on proprietary polymer formulation IP with modular platform potential. Watch FDA 510(k) clearance velocity for novel surface chemistries as the inflection signal for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Accelerates US market access for silver-alloy catheter coatings under CLABSI penalty frameworks. |
| EU MDR Technical Documentation Pathway | Compresses development cycles for coating innovators seeking Class III device recertification. |
| Hospital System Partnership | Secures tiered service agreements bundling validation, reprocessing, and infection surveillance. |
| Backward Integration into Precursor Supply | Defends margin position against silver-ion environmental discharge compliance cost escalation. |
| Software Companion Development | Enables real-time infection surveillance integration with coating performance monitoring systems. |
Study Parameters
Direct dialogue with hospital procurement committees, biomedical engineers, GPO contracts managers, and coating technology R&D directors grounded the qualitative foundation. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract repositories. Bottom-up device shipment modeling triangulated against top-down market sizing across coating chemistry and substrate geometry segments.
Segment-level value and volume estimates emerged from cross-referencing coating thickness specifications with ion-release kinetics data and hospital procurement contract values. The analytical framework spanned product type, end user, application, and technology dimensions across the analysis window. CAGRs derived from regression analysis against surgical procedure volume projections and regulatory enforcement intensity indicators. Forecast inputs incorporated METI infection control mandate implementation timelines and EPA FIFRA enforcement pattern shifts.
Underlying measurement precision varies by segment; catheter and surgical instrument coatings carry tighter precision than emerging bioceramic implant applications due to established procurement data availability. Forecasts reflect assumptions about regulatory timeline adherence and hospital capital budget trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Insufflation Devices Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Inversion Table Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
PET Injectors Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Germany Aesthetic Devices Market