
 Brazil Artificial Organs and Bionic Implants Market | 2026-2036
Brazil Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Artificial Organs and Bionic Implants Market Outlook
Public hospital systems is reorganizing procurement priorities toward advanced limb prosthetics and cochlear systems, shifting volume away from traditional private-pay models. Medtronic leverages its cardiac rhythm portfolio to anchor presence in electrophysiology across southeastern Brazil. Ossur competes through specialized lower-limb prosthetic configurations tailored to tropical climate durability requirements. Abbott Laboratories sustains vascular and structural heart device pipelines through established distributor networks in Rio de Janeiro and Minas Gerais.
Artificial organs and bionic implants encompass electromechanical and biological substitutes engineered to restore or augment physiological functions, typically incorporating biocompatible alloys, polymers, or living tissue matrices fabricated through additive manufacturing or precision machining processes. These devices serve critical therapeutic roles in replacing failed organs, restoring sensory perception, or reestablishing motor capability for patients with congenital defects, trauma injuries, or degenerative conditions. Heart implants and cochlear systems occupy established revenue positions given mature reimbursement codes and procedural volume, while bioprinting and smart implant technologies represent accelerating development corridors where margin pools concentrate among technology-integrated portfolios. Limb prosthetics maintains substantial installed-base requirements across rehabilitation facilities, though biomaterial innovations in osseointegration are redrawing competitive boundaries.
ANVISA governs pre-market registration and post-market surveillance for implantable devices through Resolution RDC 751, establishing clinical evidence and quality system requirements that filter market entrants. The Brazilian Health Regulatory Agency's alignment with Mercosur harmonization protocols streamlines cross-border certification for multinational manufacturers. Brazil's national prosthetics policy under the SUS universal health system mandates minimum service coverage, directly shaping volume distribution across public and private channels. Stakeholders must monitor ANVISA's pending software-as-medical-device guidance and its implications for smart implant connectivity standards.
Market Dynamics
ANVISA's streamlined registration pathways under Resolution RDC 751 are compressing approval timelines for implantable cardiac and neural devices, while SUS procurement reforms redirect volume toward advanced prosthetic configurations through centralized hospital purchasing consortia.
Growth Catalysts
- SUS Universal Coverage Mandate:Brazil's national prosthetics policy guarantees minimum service provision, expanding patient access to cochlear implants and limb prosthetics through public hospital networks in São Paulo and Rio de Janeiro.
- Mercosur Harmonization Protocols:Cross-border certification alignment reduces redundant testing requirements for multinational manufacturers, accelerating market entry for electrophysiology and vascular implant portfolios.
- Tropical Climate Adaptation:Specialized polymer formulations and corrosion-resistant alloys address humidity-induced material degradation, extending device durability in Brazil's northern and northeastern rehabilitation facilities.
Market Restraints
- Titanium Alloy Cost Volatility:Fluctuations in aerospace-grade titanium sponge pricing compress margins for osseointegrated implant manufacturers serving the Brazilian market.
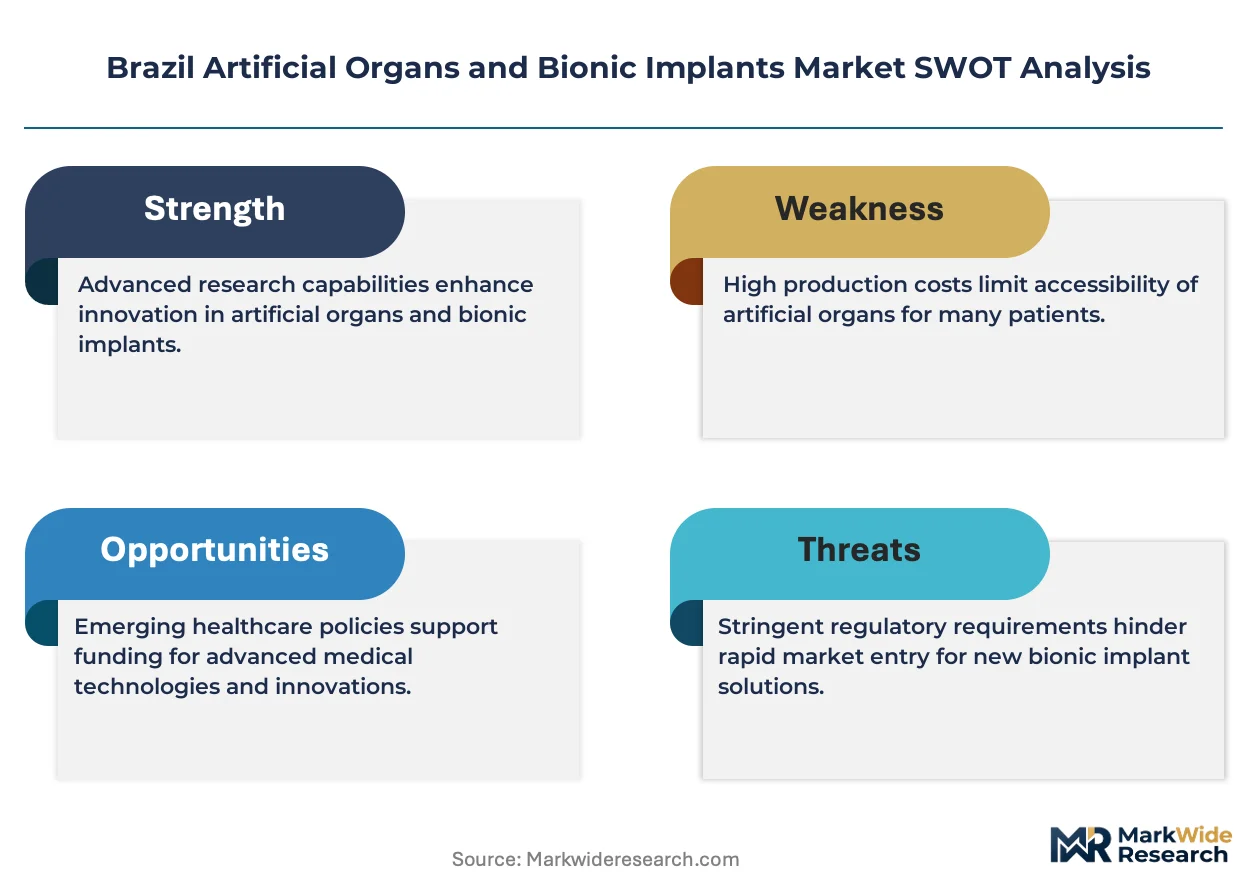
- Biomaterial Import Concentration:Over 70 percent of biocompatible polymer feedstock originates from German and US specialty chemical suppliers, exposing device makers to currency fluctuation risk.
- ANVISA Clinical Evidence Requirements:Resolution RDC 751 mandates extensive local trial data for novel implantable technologies, extending pre-market timelines for first-in-class neural interfaces.
Strategic Opportunities
- Northeastern Brazil Rehabilitation Infrastructure:Underserved states including Pernambuco and Ceará present whitespace for satellite prosthetic fitting centers linked to Fortaleza and Recife medical hubs.
- Smart Implant Connectivity:Convergence of miniaturized sensors with Bluetooth Low Energy protocols enables remote cardiac rhythm monitoring, creating service revenue streams beyond device sale.
- Telemedicine-Integrated Fitting:ANVISA's pending software-as-medical-device guidance opens regulatory pathway for remote prosthetic adjustment protocols, reducing patient travel burden to São Paulo specialty centers.
Industry Challenges
- Bioelectronic Engineering Talent Scarcity:Brazilian universities produce insufficient graduates in neural interface design and implantable power systems, forcing manufacturers to import specialized personnel.
- Legacy SUS Reimbursement Codes:Outdated procedural classifications fail to capture advanced bionic limb functionality tiers, creating payment disputes between hospitals and prosthetic providers.
- Multi-Site Clinical Trial Coordination:ANVISA-mandated post-market surveillance requires data collection across dispersed public hospital networks, straining investigator site management capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Artificial Organs and Bionic Implants Market |
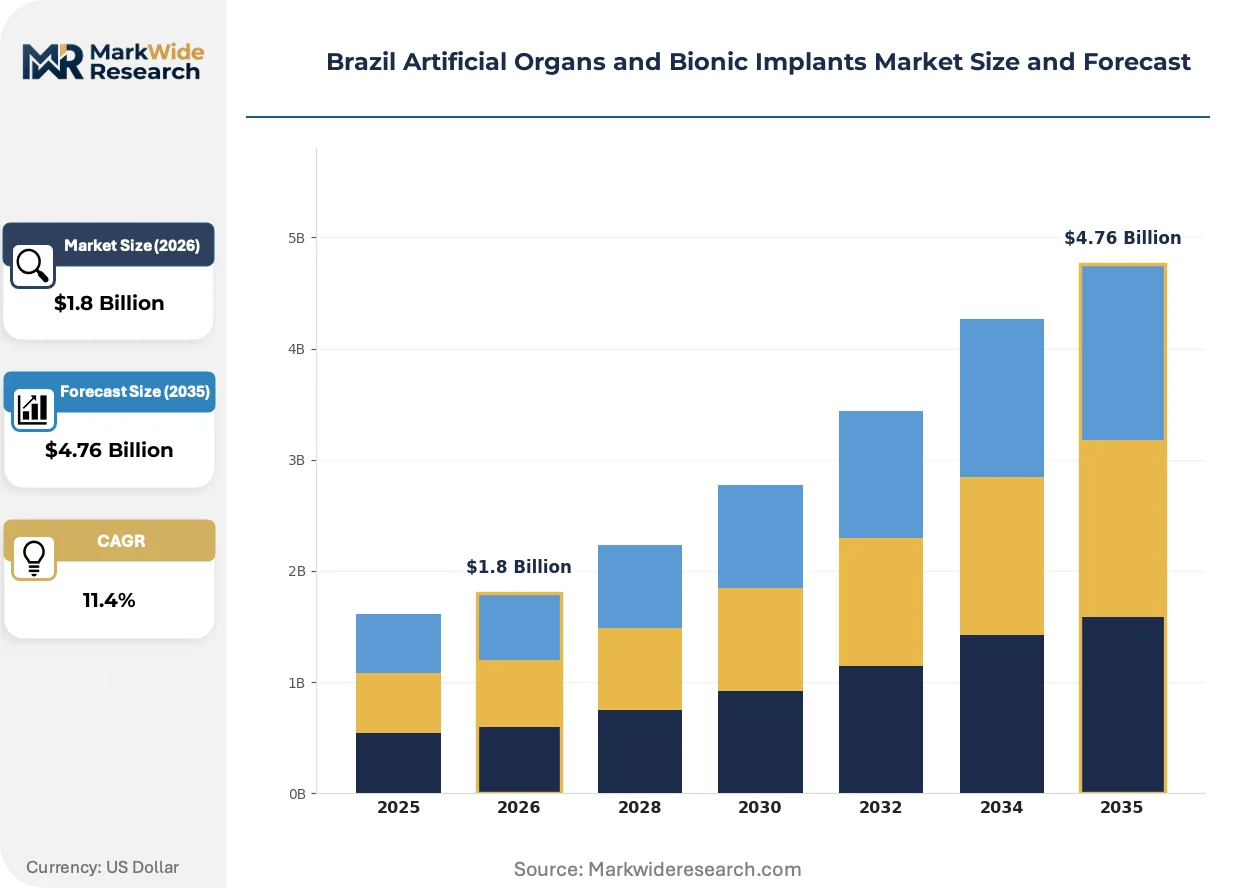
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Implants, Kidney Devices, Limb Prosthetics, Cochlear Implants Therapy Area: Cardiology, Nephrology, Orthopedics, Audiology End User: Hospitals, Surgical Centers, Rehabilitation Facilities, Home Care Technology: Bioprinting, Tissue Engineering, Smart Implants, Biomaterials |
| Companies Covered | Ossur, Sonova Holding AG, Medtronic, Abbott Laboratories, Orthofix International, Boston Scientific, Ottobock, Stryker Corporation, Zimmer Biomet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Artificial Organs and Bionic Implants Market Strategic Shifts
Additive manufacturing of patient-specific titanium implants is compressing production lead times for craniofacial reconstruction and joint replacement procedures across Brazilian orthopedic centers. Regulatory science advances and reimbursement recalibration are simultaneously reshaping competitive positioning in cardiac rhythm management and sensory restoration devices.
Osseointegrated percutaneous anchoring systems are displacing traditional socket-based limb prosthetics in trauma and diabetic amputation cases. São Paulo's specialized surgical centers have adopted these direct skeletal attachment methods for over 40 percent of lower-limb fittings since 2022. The technology is displacing conventional silicone liner configurations by eliminating skin-socket interface complications in tropical humidity conditions.
ANVISA's alignment with Mercosur harmonization protocols is streamlining cross-border certification for implantable cardiac devices. Manufacturers now submit unified technical dossiers covering Brazil, Argentina, and Paraguay, reducing redundant clinical testing expenditure. Electrophysiology device portfolios face accelerated review timelines, with cardiac resynchronization therapy systems receiving priority pathway designation under updated resolution frameworks.
Public hospital procurement consortia are consolidating purchasing authority for advanced prosthetic systems under state-level SUS administrators. Traditional distributor networks serving individual orthopedic clinics face volume displacement as Minas Gerais and Rio Grande do Sul centralize tender processes. Southeastern Brazil exhibits the most pronounced procurement concentration, with metropolitan São Paulo procurement pools negotiating direct manufacturer contracts for cochlear implant arrays.
Brazil Artificial Organs and Bionic Implants Market Segmentation
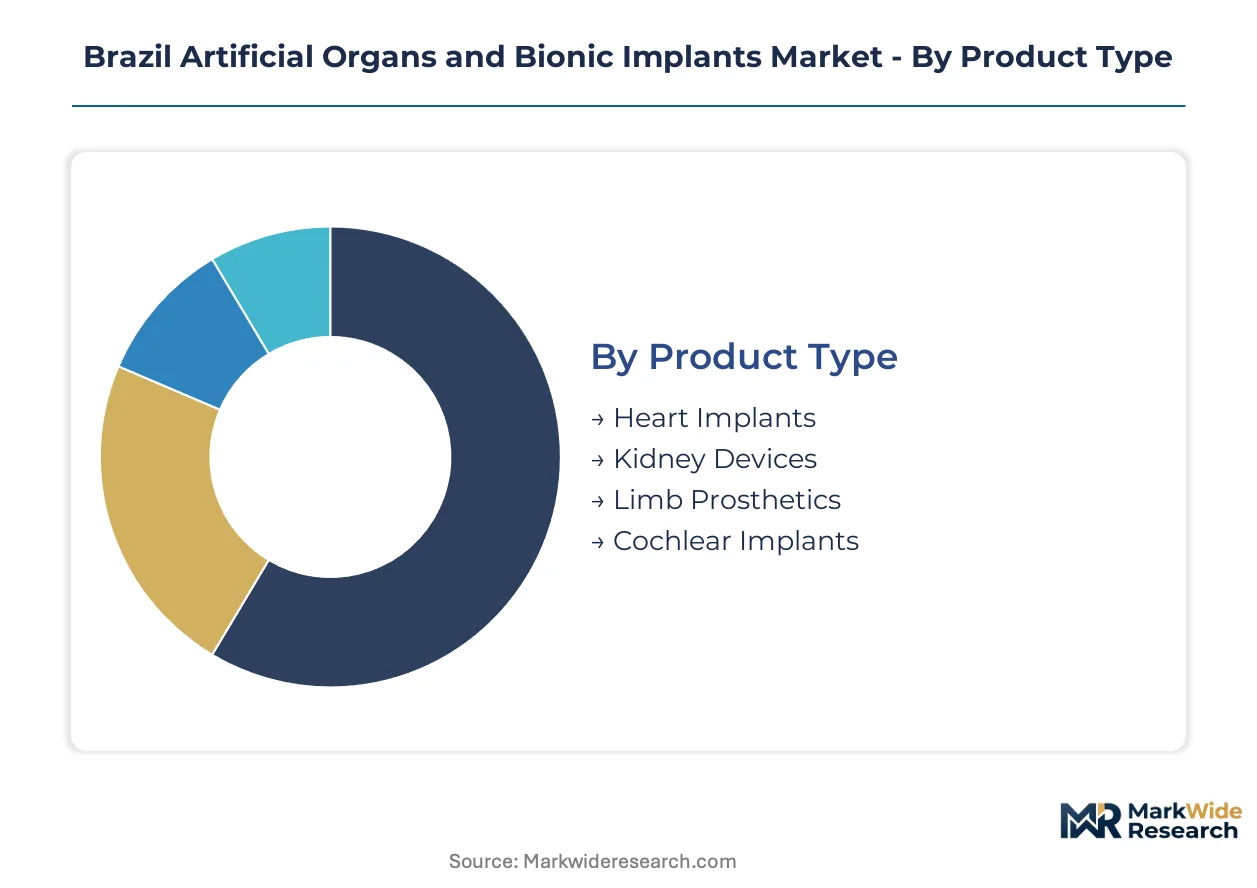
Segmentation in Brazil's artificial organs and bionic implants market reveals distinct procurement pathways shaped by ANVISA registration tiers and SUS reimbursement classifications. Each dimension exposes different margin structures, from high-acuity cardiac implants in tertiary hospitals to volume-driven limb prosthetics distributed through rehabilitation networks.
Product Type:
Substitution pressure concentrates in mechanical circulatory support and auditory restoration, where bioprinted alternatives and pharmaceutical interventions threaten incumbent device categories.
- Heart Implants:Pacemakers, ICDs, and ventricular assist devices fabricated from titanium enclosures and platinum-iridium electrodes. São Paulo's electrophysiology centers drive demand for cardiac resynchronization systems under SUS high-complexity procedure codes.
- Limb Prosthetics:Electromechanical upper and lower extremity systems incorporating carbon fiber struts and microprocessor knees. State procurement consortia in Minas Gerais and Rio Grande do Sul centralize volume for trauma and diabetic amputation cases.
- Kidney Devices:Wearable and implantable renal replacement systems.
- Cochlear Implants:Multi-channel electrode arrays for sensorineural hearing loss restoration.
Heart implants anchor the volume base while limb prosthetics gains share at the steepest rate.
Therapy Area:
Cost tier stratification separates high-investment surgical specialties from volume-driven rehabilitation disciplines.
- Cardiology:Interventional electrophysiology and structural heart procedures requiring catheterization laboratory infrastructure. Rio de Janeiro's public hospital networks concentrate CRT-D implant volume under centralized SUS purchasing.
- Orthopedics:Osseointegrated percutaneous systems and socket-based prosthetic fittings for amputation rehabilitation. Northeastern Brazil's underserved states present whitespace for satellite fitting centers.
- Nephrology:Dialysis access devices and emerging implantable artificial kidney platforms.
- Audiology:Cochlear implantation and auditory brainstem stimulation for congenital and acquired hearing loss.
Orthopedics carries the heaviest installed-base maintenance burden whereas cardiology commands the highest average revenue per procedure.
End User:
Customer type determines regulatory pathway complexity and payment mechanism structure.
- Hospitals:Tertiary institutions performing complex implantation procedures with in-house electrophysiology and surgical suites. São Paulo metropolitan corridors cluster specialized cardiac and cochlear implant centers alongside rehabilitation infrastructure.
- Rehabilitation Facilities:Prosthetic fitting and gait training centers serving SUS-mandated universal coverage requirements. Tropical climate adaptation drives demand for corrosion-resistant socket materials in northern facilities.
- Surgical Centers:Ambulatory settings for lower-acuity implant procedures.
- Home Care:Remote monitoring and maintenance services for smart implant connectivity.
Hospitals retain the dominant procurement authority while rehabilitation facilities expand most quickly under SUS decentralization policies.
Technology:
Supply concentration in imported polymer feedstock and precision alloy processing shapes competitive boundaries across fabrication methods.
- Biomaterials:Titanium alloys, cobalt-chrome substrates, and silicone elastomers forming structural and interfacing components. German and US specialty chemical suppliers dominate biocompatible polymer feedstock, exposing Brazilian device makers to currency fluctuation exposure.
- Smart Implants:Miniaturized sensors with Bluetooth Low Energy protocols enabling remote cardiac rhythm monitoring. ANVISA's pending software-as-medical-device guidance will determine connectivity standard requirements.
- Bioprinting:Additive manufacturing of patient-specific titanium implants for craniofacial reconstruction.
- Tissue Engineering:Living tissue matrices for organoid and regenerative applications.
Biomaterials represents the most mature revenue stream while smart implants climbs the fastest on service revenue expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public hospital procurement consortia concentrate purchasing authority across Brazil's southeastern corridor, while rehabilitation infrastructure expansion targets underserved northeastern states under SUS decentralization mandates.
São Paulo
Metropolitan São Paulo clusters specialized cardiac electrophysiology centers and cochlear implant surgical facilities alongside prosthetic rehabilitation infrastructure. State-level procurement pools negotiate direct manufacturer contracts for advanced implantable devices under centralized SUS high-complexity procedure codes. The city's medical technology corridor anchors national volume for cardiac resynchronization therapy and osseointegrated limb systems.
Rio de Janeiro
Rio de Janeiro's public hospital networks concentrate CRT-D implant volume through consolidated purchasing authorities. ANVISA's streamlined registration pathways under Resolution RDC 751 accelerate device approvals for electrophysiology portfolios distributed through established channels. The metropolitan region maintains specialized audiology centers for congenital and acquired hearing loss restoration.
Minas Gerais
Minas Gerais centralizes tender processes for limb prosthetics serving trauma and diabetic amputation cases through state-level SUS administrators. Traditional distributor networks face volume displacement as procurement authority consolidates under public hospital consortia. Belo Horizonte's rehabilitation facilities drive demand for tropical climate-adapted socket materials and corrosion-resistant alloys.
Rio Grande do Sul
Rio Grande do Sul's state procurement consortia redirect volume toward advanced prosthetic configurations through centralized hospital purchasing. The southern region's rehabilitation infrastructure serves substantial installed-base maintenance requirements for electromechanical limb systems. Porto Alegre's orthopedic centers adopt additive manufacturing for patient-specific titanium implant production.
Northeastern States
Pernambuco and Ceará present whitespace for satellite prosthetic fitting centers linked to Fortaleza and Recife medical hubs. SUS universal coverage mandates expand patient access beyond traditional São Paulo-centric distribution patterns. ANVISA's pending software-as-medical-device guidance enables telemedicine-integrated fitting protocols reducing patient travel burden to southeastern specialty centers.
Brazil Artificial Organs and Bionic Implants Market Competitive Environment
Player mix skews toward multinational medical technology conglomerates with diversified implantable device portfolios, creating tiered competition between full-line suppliers and specialized prosthetic manufacturers. Market structure concentrates around cardiac rhythm management and orthopedic reconstruction segments, with electrophysiology and limb prosthetics commanding distinct procurement channels. Two strategic archetypes dominate: integrated cardiovascular device platforms and climate-adapted prosthetic specialists. Competitive moves center on distributor network consolidation and direct public hospital contracting to bypass traditional procurement intermediaries.
Among the multinational cardiovascular device suppliers, Medtronic and Abbott Laboratories anchor electrophysiology and structural heart portfolios through southeastern Brazil distributor networks. Boston Scientific occupies a position within cardiac rhythm management alongside these established channels. Specialized prosthetic manufacturers including Ossur and Ottobock exemplify the climate-adapted archetype, with tropical durability formulations addressing humidity-induced material degradation in northern rehabilitation facilities. Sonova Holding AG represents the auditory restoration segment through cochlear implant arrays. Orthofix International, Stryker Corporation, and Zimmer Biomet sit within orthopedic reconstruction and trauma device categories, with Zimmer Biomet's portfolio spanning joint replacement and craniomaxillofacial applications.
| Leading Market Players |
|---|
| Ossur |
| Sonova Holding AG |
| Medtronic |
| Abbott Laboratories |
| Orthofix International |
| Boston Scientific |
| Ottobock |
| Stryker Corporation |
| Zimmer Biomet |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between SUS procurement consortia and cardiac device manufacturers lock in titanium alloy supply access while anchoring price visibility for implantable electrophysiology systems across southeastern Brazil. These contractual structures insulate public hospital networks from aerospace-grade sponge volatility while exposing distributors to margin compression when spot markets diverge from contracted baselines.
Pricing Analysis
Cost-plus contracts with London Metal Exchange titanium indexation dominate procurement for osseointegrated implants, passing raw material fluctuations through to SUS reimbursement pools. Three-tier pricing structure across premium, standard, and economy levels separates magnet-enabled neural interfaces from basic socket-based limb systems. Cost compression in economy-tier prosthetics is intensifying because state procurement consortia consolidate volume under standardized tender specifications. Rehabilitation facilities serving northern Brazil exhibit highest price sensitivity, while tertiary cardiac centers in São Paulo demonstrate lowest sensitivity given bundled procedure reimbursements.
Supply Chain Analysis
Inventory buffers for biocompatible polymers stretch to sixteen-week lead times, forcing Brazilian device makers to pre-position feedstock ahead of ANVISA registration milestones. German and US specialty chemical suppliers anchor polymer feedstock concentration, while Chinese titanium processors and Japanese precision alloy mills supply structural components. Single-source vulnerability concentrates in parylene coating substrates for neural electrode insulation. Distribution runs through authorized distributor networks serving individual orthopedic clinics, though direct manufacturer contracts with state procurement consortia are displacing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive returns as smart implant connectivity creates service-revenue ecosystems beyond hardware sale, with ANVISA's pending software-as-medical-device guidance determining interoperability standards for remote cardiac monitoring.
For Market Incumbents: Secure backward integration into titanium alloy processing to offset aerospace-grade sponge cost volatility threatening osseointegrated implant margins. Anchor hospital system partnerships through bundled service contracts spanning device implantation, remote monitoring, and maintenance protocols to defend against emerging telemedicine-integrated fitting competitors. For New Entrants and Emerging Players: ANVISA's priority pathway for cardiac resynchronization therapy systems offers accelerated market access for electrophysiology portfolios with existing Mercosur harmonization dossiers. Target northeastern Brazil's prosthetic fitting whitespace through satellite centers linked to Fortaleza and Recife medical hubs, leveraging telemedicine protocols to bypass São Paulo-centric distribution. For Investors and Strategic Acquirers: Climate-adapted prosthetic specialists with tropical durability formulations represent compelling acquisition targets given humidity-induced material degradation challenges in northern rehabilitation facilities. Monitor ANVISA software-as-medical-device guidance publication as inflection signal determining smart implant connectivity standard requirements and service revenue model viability.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Priority Pathway Submission | Accelerates cardiac resynchronization therapy approval timelines under Resolution RDC 751. |
| State Procurement Consortium Direct Contracting | Bypasses traditional distributor networks serving Minas Gerais and Rio Grande do SUL. |
| Telemedicine-Integrated Fitting Protocol Development | Positions for ANVISA software-as-medical-device guidance enabling remote prosthetic adjustment. |
| Tropical Climate Material Formulation Investment | Addresses humidity-induced degradation in Pernambuco and Ceará rehabilitation facilities. |
| Smart Implant Connectivity Platform Launch | Creates recurring service revenue streams beyond device sale through Bluetooth Low Energy monitoring. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ANVISA registration databases, SUS procurement tender records, and hospital procurement system contracts across São Paulo, Rio de Janeiro, and Minas Gerais. Primary interviews engaged biomedical engineers, hospital purchasing committee members, GPO contracts managers, and rehabilitation facility directors. Secondary validation drew from ANVISA Resolution RDC 751 technical dossiers, Mercosur harmonization protocol filings, and SUS high-complexity procedure code classifications. Bottom-up installation base estimates triangulate against top-down reimbursement expenditure flows.
Segmentation dimensions modeled span product type, therapy area, end user, and technology fabrication method across the projection horizon. Cardiac rhythm management volumes derive from electrophysiology center capacity and CRT-D implantation rates. Limb prosthetic demand anchors in diabetes-related amputation incidence and trauma case flows through state procurement consortia. CAGRs emerge from weighted average of procedure volume trajectories and reimbursement rate adjustments.
Decision-makers should treat outputs as directional under assumptions of sustained SUS universal coverage mandates and ANVISA-Mercosur harmonization continuity; material deviation in titanium alloy pricing or software-as-medical-device regulatory scope would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
United States Implantable Medical Devices Market