
 Transportable Ventilator Market | 2026-2036
Transportable Ventilator Market Size, Share, and Industry Trends Forecast 2026-2036
Transportable Ventilator Market Analytics
ICU-grade mobility specifications is bifurcating the competitive landscape between premium critical-care transport units and lighter emergency-response models. ResMed leverages its sleep-therapy R&D pipeline to extend sensor miniaturization into transportable platforms. Hamilton Medical anchors European hospital procurement through Swiss-engineered turbine-driven ventilation systems. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. competes on manufacturing scale, dominating cost-sensitive tenders across Asia-Pacific and Middle Eastern markets.
Transportable ventilators are self-contained mechanical respiratory support devices engineered to deliver controlled tidal volumes, positive end-expiratory pressure, and fractional inspired oxygen across pre-hospital, inter-hospital, and homecare settings, typically weighing under twenty kilograms with battery autonomy exceeding four hours. Their primary commercial purpose is sustaining gas exchange in patients during movement where fixed infrastructure is unavailable or impractical. Portable Ventilators occupy the deepest margin pools as hospitals prioritize bedside-to-ambulance continuity without device swapping, while Disaster Response represents the fastest-growing application segment driven by civil defense stockpiling and climate-event preparedness protocols. Microprocessor-Controlled technology leads unit shipments, though Hybrid Systems are gaining traction where pneumatic redundancy satisfies military and aeromedical reliability requirements.
FDA 510(k) clearance pathways and EU MDR Class IIa/IIb certification timelines shape product launch cadences and geographic rollout sequencing for manufacturers. ISO 80601-2-80 compliance for emergency and transport ventilators further constrains design architectures, particularly for software-controlled alarm systems and environmental resilience testing. Stakeholders must monitor evolving pre-hospital care reimbursement frameworks and national strategic stockpile specifications as these will determine which product configurations secure long-term purchase commitments.
Market Dynamics
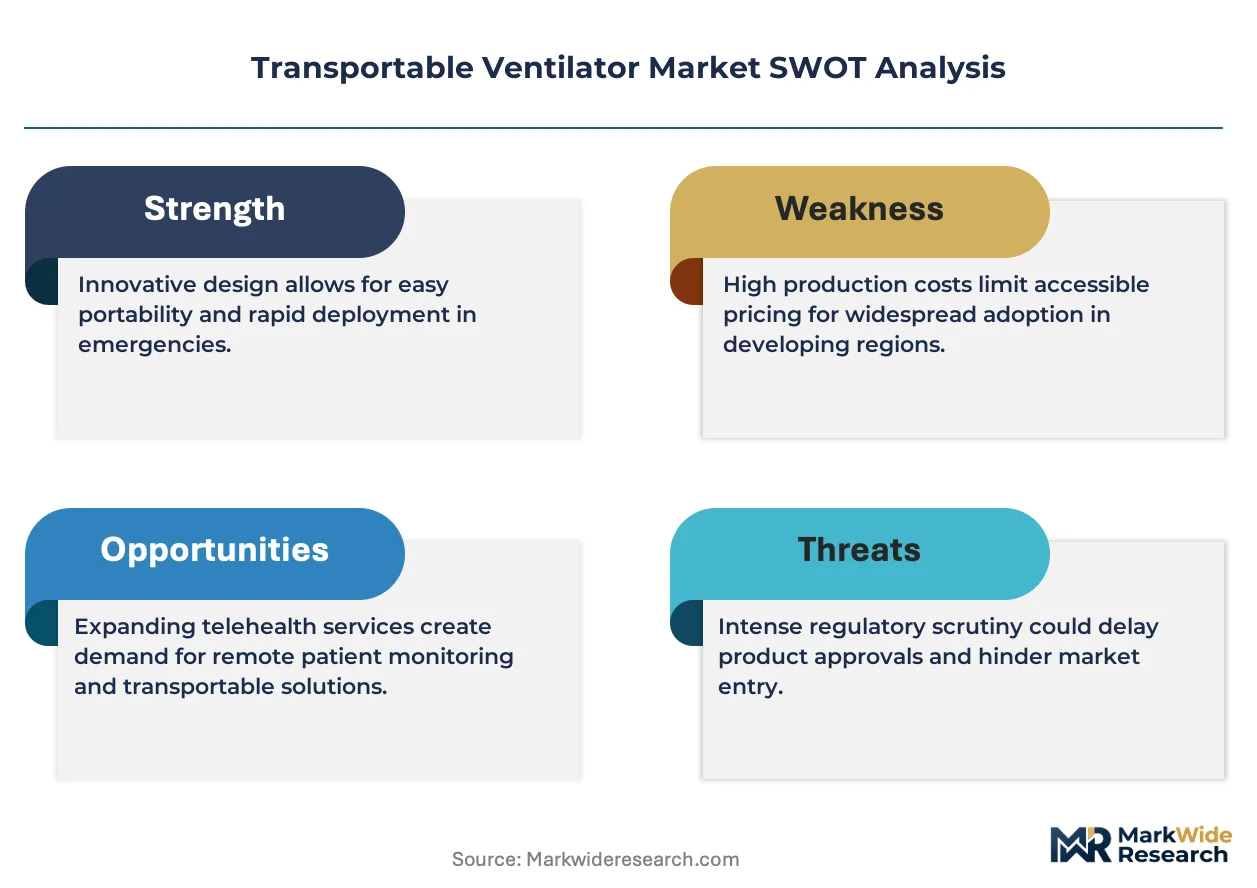
ICU-grade mobility specifications are splitting the transportable ventilator market into two distinct competitive arenas: premium critical-care units with full invasive ventilation capability and lighter emergency-response models optimized for rapid deployment. This bifurcation is forcing manufacturers to choose between engineering for clinical depth or logistical agility, reshaping R&D allocation and channel partnerships across the industry.
Growth Catalysts
- Hospital-at-home reimbursement expansion:CMS and equivalent payers in Germany and Japan are extending coverage for acute respiratory support outside traditional facilities, creating pull-through demand for battery-autonomous systems.
- EU MDR Class IIb certification harmonization:Streamlined conformity assessment pathways for emergency and transport ventilators are accelerating product launch cadences across European member states.
- Climate-event civil defense protocols:National stockpile specifications in the United States, Switzerland, and Australia now mandate mobile respiratory reserves for mass-casualty scenarios.
Market Restraints
- Lithium-ion battery supply concentration:Cell production for medical-grade power systems clusters in East Asian manufacturing hubs, exposing OEMs to geopolitical disruption and raw material cost volatility.
- ISO 80601-2-80 alarm system complexity:Software-controlled acoustic and visual warning architectures require extensive environmental resilience testing, extending development timelines and validation costs.
- Fixed infrastructure substitution:Stationary ICU ventilators with transport adapters satisfy intermittent mobility needs at lower capital outlay, constraining pure transportable unit penetration in budget-constrained health systems.
Strategic Opportunities
- Military aeromedical hybrid systems:Pneumatic redundancy specifications for battlefield evacuation are creating demand for dual-power architectures that civilian emergency services are now adopting.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing are opening cost-competitive sourcing alternatives for Middle Eastern and African procurement authorities.
- Tele-ICU integration:Convergence of transportable ventilation with remote patient monitoring platforms enables centralized respiratory management across distributed care networks.
Industry Challenges
- FDA 510(k) predicate device scarcity:Novel turbine-driven architectures often lack acceptable comparison units, triggering de novo review pathways that extend clearance timelines by twelve to eighteen months.
- Biomedical engineer specialization gaps:Cross-training requirements for both critical-care respiratory therapy and field-service electromechanical repair are outstripping vocational program output in key markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportable Ventilator Market |
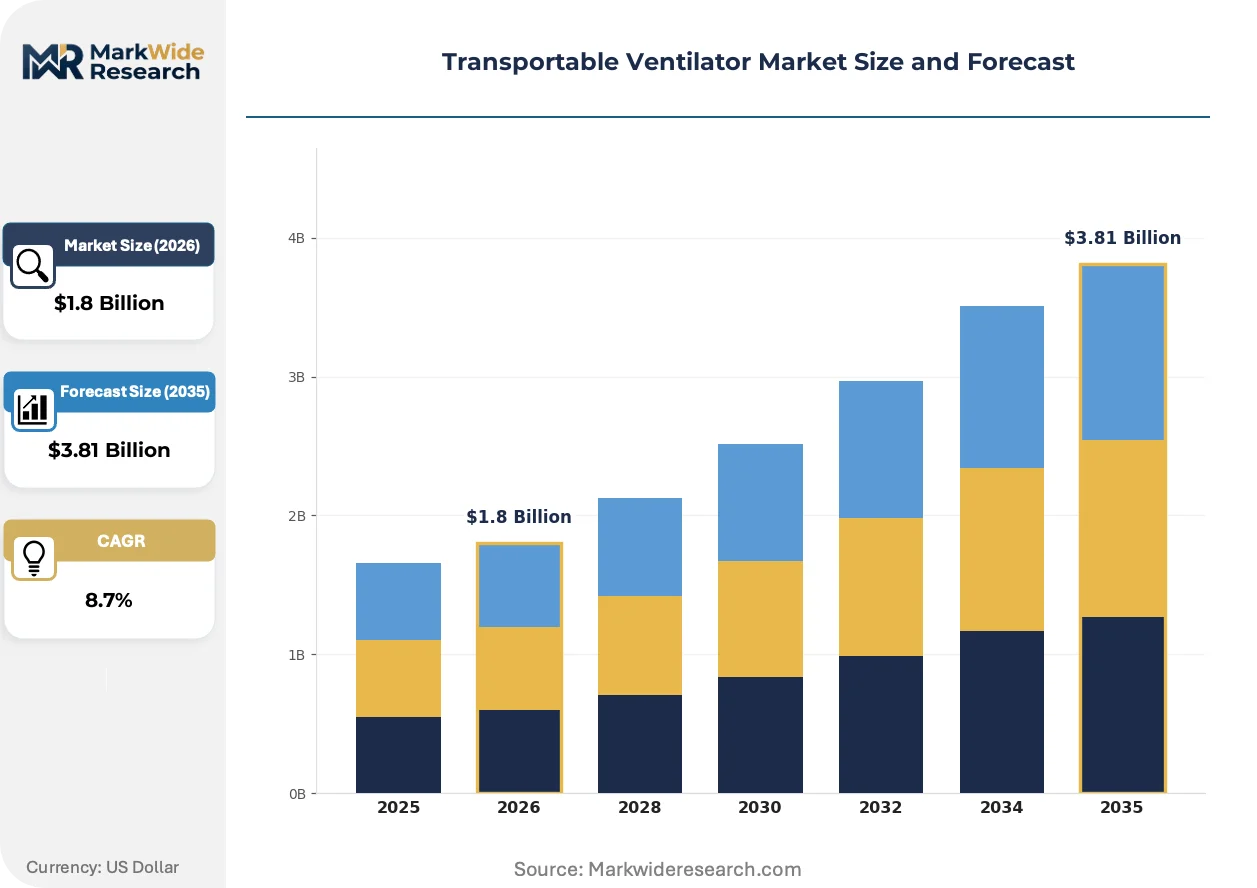
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ventilators, Transport Ventilators, Multi-use Ventilators, Inflatable Ventilators Application: Emergency Care, Critical Care, Home Care, Disaster Response End User: Hospitals, Clinics, Emergency Services, Homecare Providers Technology: Microprocessor-Controlled, Pneumatic, Electronic, Hybrid Systems |
| Companies Covered | ResMed, Getinge AB, Koninklijke Philips N.V., Drägerwerk AG & Co. KGaA, Medtronic, Vyaire Medical, GE Healthcare, Hamilton Medical, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportable Ventilator Market Evolving Landscape
Microprocessor-controlled ventilation is fragmenting into modular architectures where software-defined functionality replaces dedicated pneumatic circuits. This shift is compressing hardware differentiation and elevating algorithmic performance as the primary competitive battleground.
Turbine-driven blower technology is decomposing the traditional compressor-oxygen-blender hierarchy in transportable platforms. Emergency medical services in the United States and Germany are adopting these lighter, quieter systems for ground and rotor-wing evacuation. The structural consequence is a collapse in the premium attached to legacy pneumatic systems, forcing incumbent manufacturers to accelerate turbine R&D or cede mid-market share.
EU MDR post-market surveillance requirements are tightening real-world performance documentation obligations for Class IIb respiratory devices. Manufacturers must now maintain systematic clinical follow-up registries across deployed units, not just pre-market validation datasets. Swiss and German hospital procurement authorities are prioritizing vendors with established vigilance infrastructure, disadvantaging newer market entrants.
Ambulance fleet operators are unbundling device ownership from maintenance and consumable supply, shifting toward multi-year service contracts with uptime guarantees. This procurement model change displaces capital purchase tenders in United Kingdom and Australian emergency services. The shift is most visible in inter-hospital transfer networks where downtime penalties now exceed equipment lease costs.
Transportable Ventilator Market Segmentation
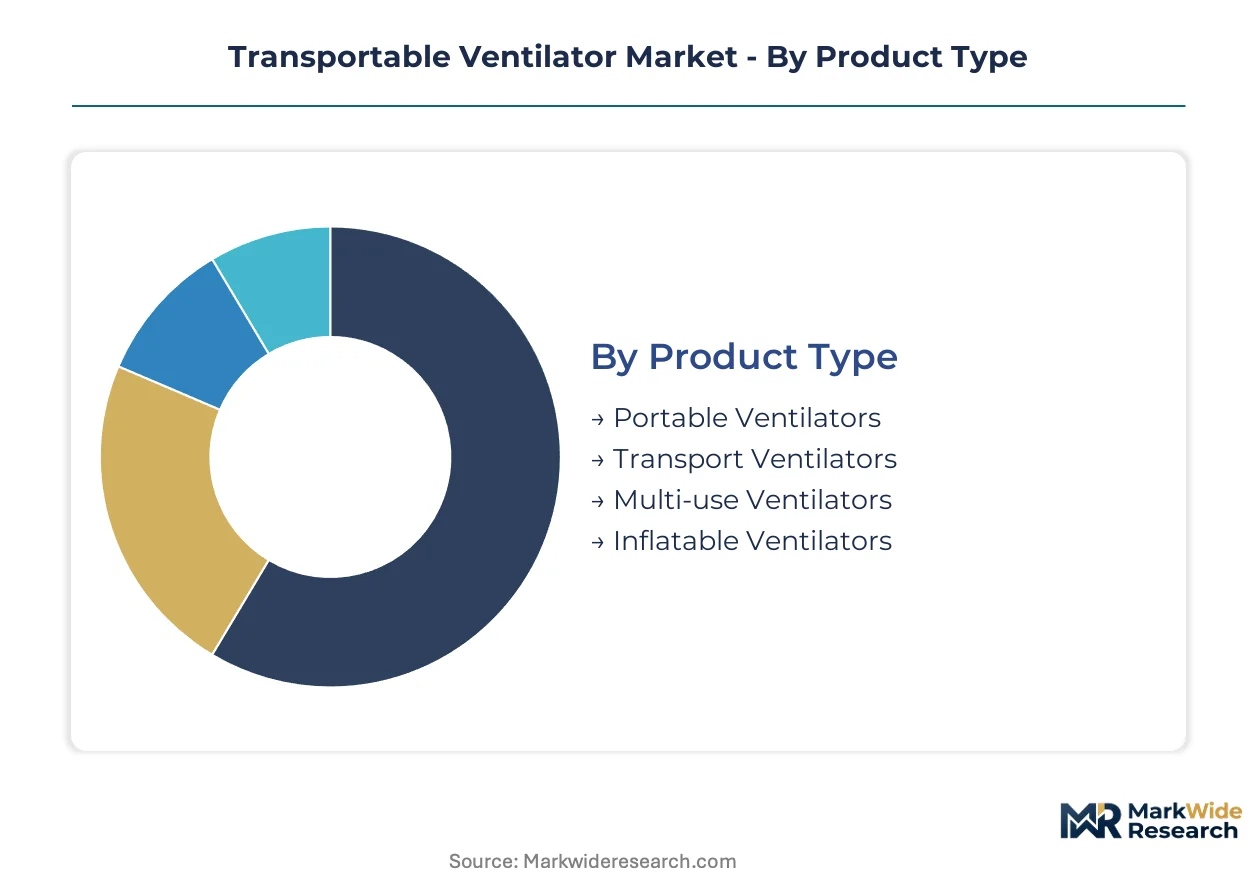
Transportable ventilator purchasing decisions split across clinical capability, mobility requirements, and reimbursement pathways. Manufacturers must align product architectures with the specific constraints of each segment to avoid substitution by stationary ICU units with transport adapters.
Product Type:
Portable Ventilators face the most intense substitution pressure from stationary units with mobility attachments, forcing differentiation through battery autonomy and weight reduction.
- Portable Ventilators:Battery-autonomous units under ten kilograms deliver non-invasive and limited invasive support for inter-hospital transfers and homecare. Demand concentrates in United States hospital-at-home programs where CMS reimbursement now covers acute respiratory support outside traditional facilities, though weight constraints limit tidal volume range.
- Transport Ventilators:Full invasive-capability systems between ten and twenty kilograms sustain gas exchange during ground and aeromedical evacuation. German emergency medical services prioritize these units for rotor-wing deployment, balancing clinical depth against payload restrictions.
- Multi-use Ventilators:Modular platforms reconfigure between bedside and transport modes through detachable battery modules.
- Inflatable Ventilators:Collapsible pneumatic systems deploy for mass-casualty scenarios where storage volume dominates procurement criteria.
Transport Ventilators anchors the volume base while Portable Ventilators gains share at the steepest rate.
Application:
Cost tier stratification separates premium critical-care applications from budget-constrained disaster preparedness procurement.
- Emergency Care:Pre-hospital settings demand rapid-deployment units with simplified interfaces for paramedic operation. United States ground ambulance fleets are consolidating procurement around multi-year service contracts with uptime guarantees rather than capital purchases, shifting vendor selection toward maintenance infrastructure.
- Critical Care:Inter-hospital transfers require full ICU capability including precise PEEP control and advanced monitoring. Swiss and German hospital networks specify turbine-driven systems for their quieter operation during patient transport.
- Home Care:Reimbursement expansion for acute respiratory support outside hospitals drives demand for patient-operable interfaces.
- Disaster Response:Civil defense stockpiling in Switzerland and Australia mandates mobile respiratory reserves for climate-event mass-casualty protocols.
Critical Care commands the premium pricing tier while Disaster Response shows the steepest volume expansion trajectory.
End User:
Customer type determines procurement complexity, with hospital systems demanding full validation documentation and emergency services prioritizing field durability.
- Hospitals:Academic medical centers in United States and Germany specify ISO 80601-2-80 compliance for alarm system resilience across environmental conditions. These buyers maintain systematic clinical follow-up registries to satisfy EU MDR post-market surveillance obligations.
- Clinics:Smaller facilities favor multi-use platforms that amortize capital across bedside and occasional transport applications.
- Emergency Services:Ground and aeromedical operators in United Kingdom and Australia are unbundling device ownership from maintenance, adopting performance-based contracts with downtime penalties.
- Homecare Providers:Durable medical equipment suppliers respond to CMS reimbursement expansion with rental fleet investments.
Hospitals anchor procurement volume while Emergency Services is expanding most quickly through contract restructuring.
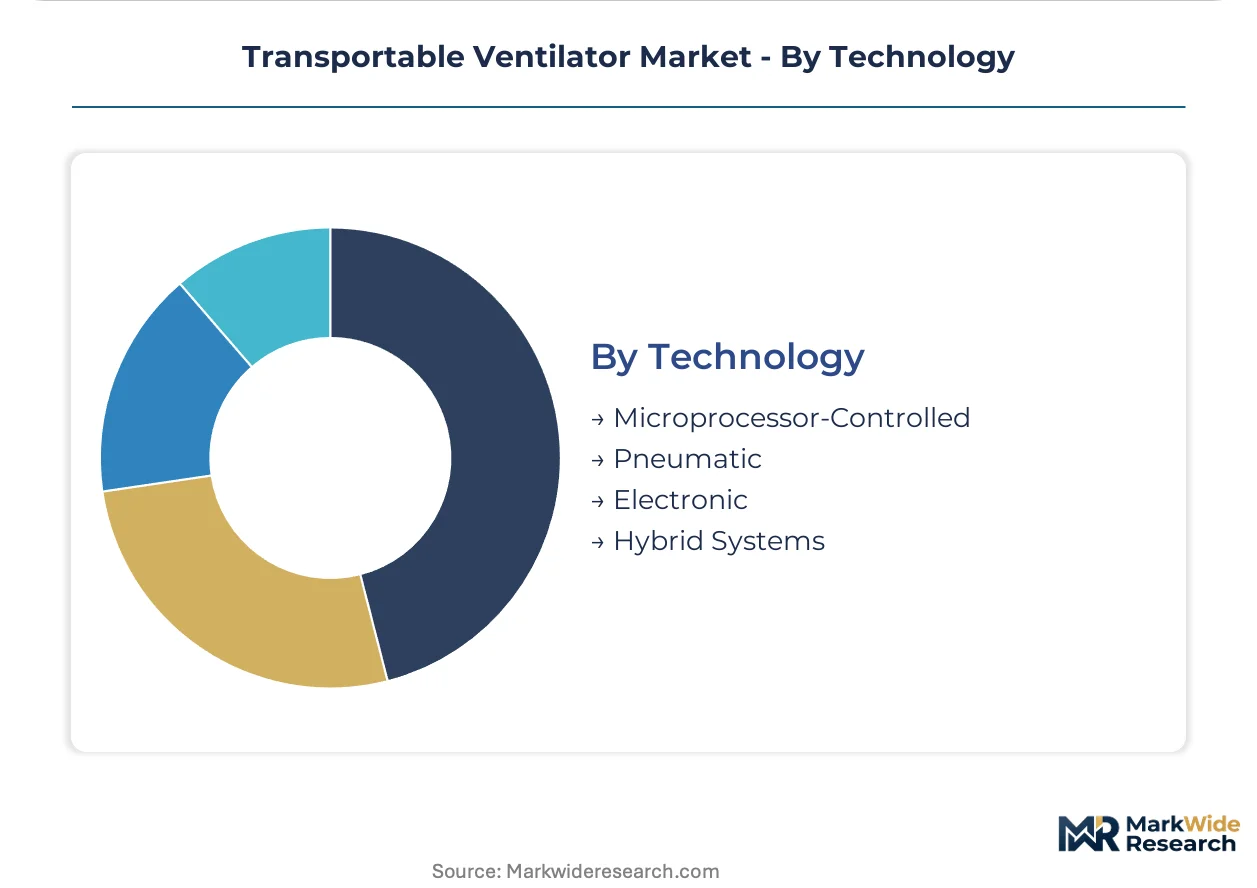
Technology:
Supply concentration in turbine manufacturing is compressing hardware differentiation and elevating algorithmic performance as the primary competitive battleground.
- Microprocessor-Controlled:Software-defined functionality replaces dedicated pneumatic circuits, enabling waveform customization and remote monitoring integration. These systems lead unit shipments as hospitals prioritize data connectivity for tele-ICU applications.
- Hybrid Systems:Dual-power architectures combine electronic control with pneumatic redundancy for military and aeromedical reliability requirements. United States battlefield evacuation specifications are creating demand that civilian emergency services now adopt.
- Pneumatic:Legacy compressor-oxygen-blender systems persist in cost-sensitive tenders where proven reliability outweighs weight penalties.
- Electronic:Simplified electronic controls serve basic emergency response without advanced ventilation modes.
Microprocessor-Controlled technology dominates current deployment while Hybrid Systems climbs the fastest on military-civilian technology transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian battery cell manufacturing concentrates supply chains for medical-grade power systems, while regulatory validation requirements diverge across FDA, EU MDR, and national emergency stockpile specifications.
United States
Hospital-at-home reimbursement expansion under CMS drives procurement of battery-autonomous transportable ventilators for acute respiratory support outside traditional facilities. FDA 510(k) clearance pathways and de novo review timelines for novel turbine-driven architectures extend product launch cadences by twelve to eighteen months. Boston and Minneapolis medical device clusters anchor development of software-controlled alarm systems for environmental resilience testing.
Germany
Emergency medical services prioritize rotor-wing deployment of full invasive-capability transport ventilators balancing clinical depth against payload restrictions. EU MDR Class IIb certification harmonization accelerates conformity assessment pathways across European member states. Baden-Württemberg and Bavaria host turbine-driven ventilation engineering centers supplying Swiss and German hospital networks.
Japan
Aging demographics and METI-supported hospital-at-home initiatives accelerate deployment of portable life-support equipment for elderly respiratory patients. PMDA regulatory frameworks align with ISO 80601-2-80 compliance requirements for mobile respiratory devices. Tokyo-Osaka medical technology corridors concentrate manufacturing partnerships for sensor miniaturization platforms.
Switzerland
Civil defense stockpile specifications mandate mobile respiratory reserves for climate-event mass-casualty protocols, creating institutional procurement commitments. Swissmedic vigilance infrastructure requirements prioritize vendors with established post-market surveillance registries for Class IIb respiratory devices. Zurich and Basel clusters specialize in dual-power hybrid architectures for military-civilian technology transfer.
China
Shenzhen-based manufacturing scale dominates cost-sensitive tenders across Asia-Pacific and Middle Eastern markets for transportable ventilation platforms. NMPA regulatory pathways and GB standards compliance shape product configurations for domestic hospital procurement. Yangtze River Delta and Pearl River Delta industrial zones concentrate lithium-ion battery cell production for medical-grade power systems.
Transportable Ventilator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Swiss and German engineering-focused manufacturers anchor premium critical-care transport segments through turbine-driven architectures and regulatory validation depth. East Asian scale manufacturers compete on production economics for cost-sensitive tenders. The dominant competitive moves are multi-year service contracts with uptime guarantees displacing capital purchases, and modular platform development enabling bedside-to-transport reconfiguration.
Among Swiss-engineered specialists, Hamilton Medical exemplifies turbine-driven ventilation leadership for European hospital procurement. ResMed represents sensor miniaturization expertise extending from sleep-therapy R&D into transportable platforms. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors the scale-driven tier, occupying manufacturing cost advantages for Asia-Pacific and Middle Eastern market penetration.
| Leading Market Players |
|---|
| ResMed |
| Getinge AB |
| Koninklijke Philips N.V. |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Vyaire Medical |
| GE Healthcare |
| Hamilton Medical |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Value Network & Pricing Analysis
East Asian battery cell manufacturing scale anchors cost floors across transportable ventilator tiers, compressing margins for OEMs without captive lithium-ion supply or long-term offtake agreements with South Korean or Japanese cell producers. This concentration elevates turbine and sensor miniaturization as the remaining vectors for premium pricing, while procurement authorities in Germany and Japan weight ISO 80601-2-80 certification heavily in tender evaluations.
Pricing Analysis
FDA 510(k) and EU MDR Class IIb certification tiers dictate the pricing structure across transportable ventilator procurement, separating premium turbine-driven systems with full invasive capability from standard pneumatic units and economy-grade emergency-response models. Price differentiation hinges on alarm system resilience validation and battery autonomy duration, with German hospital networks least sensitive to capital outlay and Middle Eastern tender authorities most responsive to per-unit cost. Cost compression in the economy tier intensifies as Shenzhen-based manufacturers expand capacity for basic transport platforms.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion cell production for medical-grade power systems, with the Yangtze River Delta and Pearl River Delta industrial zones feeding battery module assembly for ventilator OEMs. Turbine blower components draw from Swiss and German precision engineering clusters, while sensor miniaturization feeds from Tokyo-Osaka manufacturing partnerships. Single-source vulnerability concentrates in rare earth magnet supply for turbine motors. Distribution runs through hospital procurement committees in the United States and Germany, emergency services fleet operators in the United Kingdom and Australia, and government stockpile authorities in Switzerland and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transportable ventilator market rewards manufacturers who bridge biomedical engineering depth with field-service electromechanical repair capability, a skill combination that vocational programs in the United States and Germany currently undersupply relative to deployment growth.
For Market Incumbents: Shield premium positioning by deepening turbine R&D partnerships with Swiss and German engineering clusters while accelerating EU MDR post-market surveillance registry investments to satisfy procurement prequalification in Baden-Württemberg and Bavaria hospital networks. Vertical integration into battery cell supply through South Korean or Japanese offtake agreements mitigates lithium-ion cost volatility exposure. For New Entrants and Emerging Players: Lead with tele-ICU integration capabilities targeting United States hospital-at-home reimbursement expansion, where CMS coverage for acute respiratory support outside traditional facilities creates white-space demand for patient-operable interfaces with remote monitoring connectivity. India's PLI scheme for medical devices offers a cost-competitive manufacturing entry point for Middle Eastern and African procurement authorities. For Investors and Strategic Acquirers: Turbine-driven ventilation specialists with established FDA 510(k) clearance and EU MDR Class IIb certification represent the most defensible acquisition profile for portfolio exposure to hospital-at-home and aeromedical evacuation growth vectors. Watch for inflection in multi-year service contract penetration rates across United Kingdom and Australian emergency services as signal of procurement model permanence.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIb Certification Pathway | Accelerates conformity assessment timelines across German and Swiss hospital procurement cycles. |
| Hospital System Partnership | Secures long-term purchase commitments through bedside-to-ambulance continuity guarantees. |
| Software Companion Development | Enables tele-ICU integration for remote respiratory management across distributed care networks. |
| Reimbursement Strategy | Aligns product configurations with CMS hospital-at-home coverage expansion in United States. |
| Backward Integration into Battery Supply | Reduces exposure to East Asian lithium-ion cell production concentration and price volatility. |
Research Methodology
The analysis maps portable, transport, multi-use, and inflatable ventilator sub-sectors, each validated through biomedical engineers, hospital purchasing committees, emergency services fleet operators, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR conformity assessment databases, CMS Medicare reimbursement data, and hospital procurement registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the analysis window.
Cross-validation against external benchmarks ensured consistency across volume and value outputs. Segmentation modeling incorporated product type, application, end user, and technology dimensions throughout the forecast period. CAGRs derived from trend extrapolation of battery autonomy improvements, turbine adoption curves, and reimbursement expansion trajectories, with hospital-at-home program enrollment and civil defense stockpile specifications as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion, EU MDR harmonization maintenance, or lithium-ion supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory clearance timelines and procurement contract restructuring velocity. Recalibration cycles align with material shifts in FDA de novo review pathway volumes and national strategic stockpile specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Massage Equipment Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
External Defibrillator Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Surgical Devices Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Image-Based Cytometer Market