
 Global Intraosseous Devices Market | 2026-2036
Global Intraosseous Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intraosseous Devices Market Foresight
Emergency medicine physician training capacity is bifurcating market access between established hospital systems and expanding prehospital networks. Teleflex Incorporated leverages its military contract heritage to anchor premium positioning in NATO trauma supply chains. Becton, Dickinson and Company sustains broad hospital penetration through its integrated vascular access portfolio. PerSys Medical specializes in compact battery-powered designs that dominate air-medical and tactical evacuation platforms.
Intraosseous devices are rigid cannulation instruments engineered to penetrate cortical bone and deliver fluids or medications directly into the medullary cavity, typically using 15-gauge to 18-gauge needles with trocar tips and depth-limiting collars to prevent posterior wall perforation. Their primary purpose is to secure rapid vascular access when peripheral veins collapse during hemorrhagic shock, cardiac arrest, or severe dehydration. Spring-loaded devices lead procedural volume in civilian emergency departments due to speed and minimal training requirements, while battery-powered systems capture expanding share in military and prehospital settings where insertion success under duress determines outcomes. Manual needles retain cost-sensitive segments in developing health systems and pediatric applications where anatomical precision overrides speed.
FDA 510(k) clearance and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for intraosseous device manufacturers seeking commercial access. ISO 7864 needle performance standards and IEC 60601 electrical safety protocols govern battery-powered system design, creating compliance moats that favor established players with regulatory infrastructure. Stakeholders must monitor evolving battlefield trauma protocols and civilian mass-casualty preparedness mandates that will determine whether procurement centralizes under national stockpile programs or fragments across regional health systems.
Market Dynamics
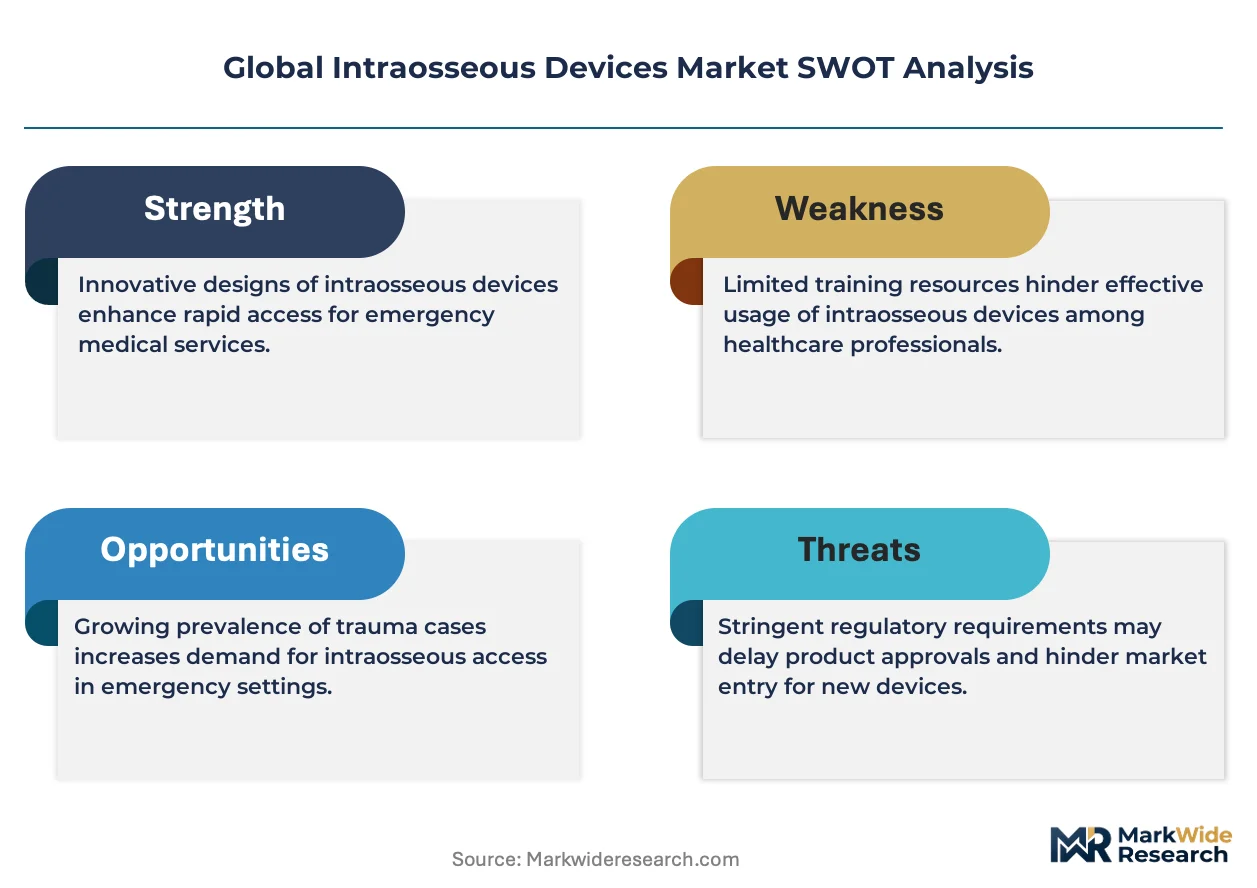
Emergency medical services expansion and EU MDR conformity tightening are bifurcating competitive access between established hospital systems and prehospital procurement networks. Powered insertion systems face elongated validation timelines while spring-loaded devices capture volume in civilian emergency departments.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for predicate-based submissions reduce time-to-market for iterative device designs, particularly benefiting battery-powered system developers seeking rapid commercialization.
- Military-civilian trauma network integration:NATO standardization protocols for vascular access training drive institutional procurement mandates across Germany, United States, and United Kingdom defense health systems.
- Prehospital protocol expansion:Emergency medical technician scope-of-practice revisions in multiple jurisdictions authorize intraosseous insertion by paramedic-level providers, extending addressable procedural volume beyond hospital settings.
Market Restraints
- Stainless steel needle cost volatility:Raw material price fluctuations for 15-gauge to 18-gauge cannula manufacturing compress margins for disposable device producers serving cost-sensitive health systems.
- EU MDR clinical evidence requirements:Conformity assessment body capacity constraints and expanded post-market surveillance obligations extend certification timelines by 12-24 months for powered insertion systems.
- Peripheral intravenous catheter residual preference:Established clinician familiarity with conventional vascular access methods slows protocol adoption in non-trauma emergency settings where time pressure is less acute.
Strategic Opportunities
- Air-medical platform specialization:Compact battery-powered designs tailored for helicopter emergency medical services and tactical evacuation units address vibration-resistant, one-handed operation requirements in Japan and Australia aeromedical networks.
- Pediatric anatomical precision segment:Depth-limiting collar customization for neonatal and infant applications opens underserved niches where manual needle control outweighs speed priorities.
- National stockpile centralization:Civilian mass-casualty preparedness mandates in United States and Germany create consolidated procurement channels through federal emergency management agencies rather than fragmented hospital purchasing.
Industry Challenges
- Insertion competency certification gaps:Procedural training standardization lags between emergency medicine physicians, paramedics, and combat medics, creating liability exposure and outcome variability across user tiers.
- ISO 7864 needle performance validation:Third-party testing laboratory bottlenecks delay regulatory submission packages, particularly for manufacturers lacking in-house metrology capabilities.
- Legacy electronic health record integration:Battery-powered device data logging functions require custom API development for documentation workflow compatibility with established hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intraosseous Devices Market |
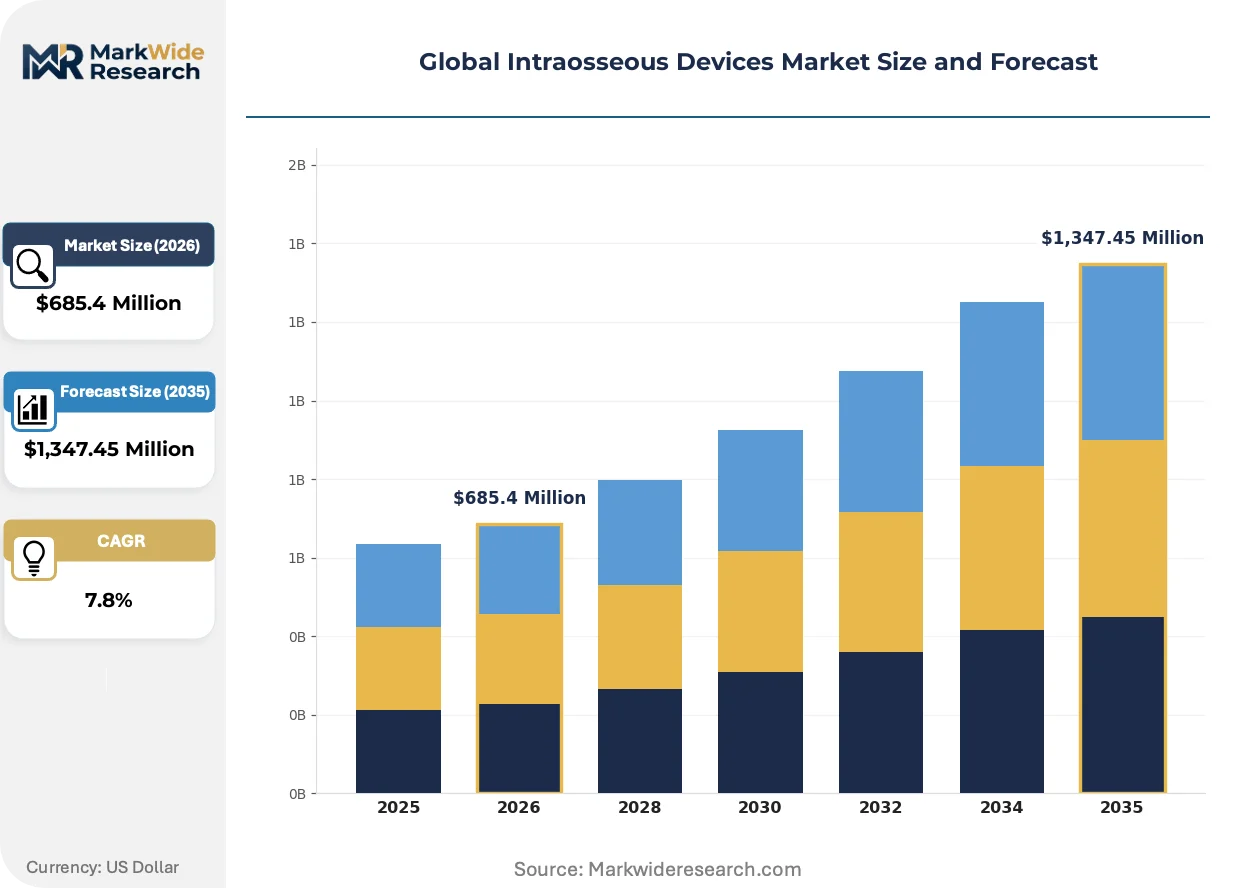
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Needles, Spring-Loaded Devices, Battery-Powered Devices, Semi-Automatic Needles Application: Emergency Medicine, Trauma Care, Military Medicine, Pediatric Resuscitation, Critical Care, Prehospital Care End User: Hospitals, Emergency Medical Services, Military Healthcare Providers, Ambulatory Care Centers Technology: Coated Needles, Stainless Steel, Plastic Components, Disposable Devices, Reusable Units |
| Companies Covered | Teleflex Incorporated, Becton, Dickinson and Company, Cook Group, Cardinal Health, Inc., SAM Medical, PerSys Medical, PAVmed Inc., BIOPSYBELL S.R.L., Argon Medical Devices, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intraosseous Devices Market Shifts & Advancements
Device miniaturization and powertrain efficiency gains are reconfiguring competitive positioning across military, aeromedical, and civilian emergency segments. Regulatory evidence requirements and procurement centralization are simultaneously compressing vendor margins and consolidating buyer power.
Spring-loaded mechanical insertion technology is decomposing the traditional trade-off between deployment speed and training burden. Emergency departments in United States trauma centers adopt these systems for cardiac arrest protocols where first-attempt success rates determine resuscitation outcomes. The technology is decomposing market segmentation between hospital-based and prehospital use cases by eliminating the skill differential that previously separated these environments.
EU MDR Article 10 clinical evaluation requirements are elevating post-market clinical follow-up obligations for powered intraosseous systems. Manufacturers must now generate real-world performance data through implantable device registries or comparable systematic collection methods. Class III device reclassification discussions affect battery-powered designs most severely, forcing portfolio prioritization decisions among mid-cap specialists with limited regulatory affairs bandwidth.
Hospital purchasing consortiums are consolidating vascular access procurement decisions under centralized supply chain functions. Group purchasing organizations negotiate multi-year sole-source agreements that displace fragmented departmental-level ordering. This concentration is most visible in United States health systems where integrated delivery networks capture 60-70 percent of acute care admissions and standardize device formularies across affiliated facilities.
Global Intraosseous Devices Market Segmentation
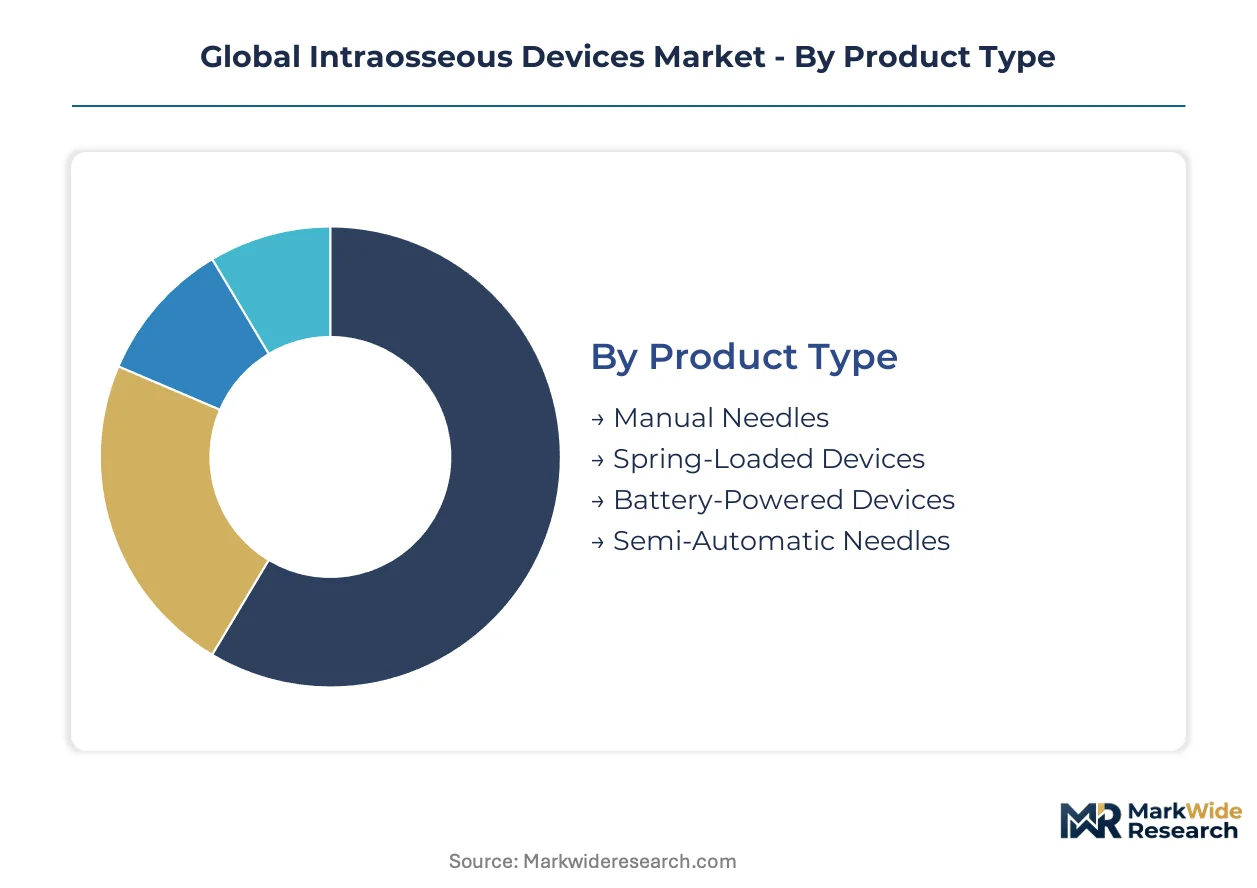
Segmentation in the intraosseous devices market reveals distinct procurement patterns across military-civilian trauma networks and emergency care tiers. Product design priorities diverge sharply between hospital systems seeking standardized protocols and prehospital operators demanding portable, battery-dependent solutions.
Product Type:
Spring-loaded devices concentrate manufacturing in United States and German facilities serving NATO defense health systems, while battery-powered designs flow from Japanese and Israeli exporters targeting aeromedical platforms.
- Spring-Loaded Devices:Mechanical insertion systems deploy trocar-tipped needles through calibrated spring mechanisms. Depth-limiting collars prevent posterior cortical perforation. Demand clusters in United States civilian emergency departments where cardiac arrest protocols mandate first-attempt success. Training burden minimization drives procurement in high-turnover clinical environments.
- Battery-Powered Devices:Motorized insertion systems utilize lithium-ion powertrains to penetrate cortical bone with controlled torque. Compact form factors dominate Japan and Australia helicopter emergency medical services where vibration-resistant, one-handed operation proves essential. Military-civilian trauma network integration in Germany and United Kingdom accelerates field deployment.
- Manual Needles:Hand-driven stainless steel cannulas with fixed depth stops retain cost-sensitive health system share in developing markets and pediatric applications requiring anatomical precision.
- Semi-Automatic Needles:Hybrid designs combining manual positioning with assisted insertion mechanics occupy intermediate price-performance positioning for mid-tier hospital procurement.
Spring-loaded devices command the established base. The steepest expansion runs through battery-powered systems.
Application:
Cost tier differentiation separates high-acuity trauma protocols from routine emergency department workflows, with reimbursement rates determining technology allocation across care settings.
- Emergency Medicine:Hospital-based resuscitation protocols for cardiac arrest and shock states. Spring-loaded systems dominate United States trauma centers where standardized training programs reduce outcome variability.
- Prehospital Care:Paramedic and emergency medical technician scope-of-practice expansions in multiple jurisdictions authorize field insertion. This segment is expanding most quickly as civilian mass-casualty preparedness mandates consolidate procurement through federal emergency management channels.
- Trauma Care:Hemorrhagic shock management in level I and II trauma centers. Institutional protocol standardization favors disposable device formularies.
- Military Medicine:Combat casualty care and tactical evacuation platforms. NATO standardization protocols drive interoperability requirements across Germany, United States, and United Kingdom defense health systems.
- Pediatric Resuscitation:Neonatal and infant anatomical applications requiring depth-limiting collar customization. Manual needle control outweighs speed priorities in this underserved niche.
- Critical Care:Intensive care unit vascular access backup when central line placement fails. Integration with electronic health record documentation workflows creates vendor selection criteria.
Emergency medicine anchors volume concentration. Prehospital care delivers the fastest climb.
End User:
Customer type fragmentation produces divergent purchasing behaviors, with consolidated hospital networks negotiating multi-year agreements against fragmented emergency medical service district procurement.
- Emergency Medical Services:Ground and air ambulance operators in United States, Germany, and Japan. Battery-powered designs capture expanding share as prehospital protocols extend vascular access authorization to paramedic-level providers.
- Hospitals:Integrated delivery networks standardizing device formularies across affiliated facilities. Group purchasing organization concentration captures sixty to seventy percent of United States acute care admissions.
- Military Healthcare Providers:Defense health systems under NATO standardization protocols. Teleflex military contract heritage anchors premium positioning in trauma supply chains.
- Ambulatory Care Centers:Freestanding emergency facilities and urgent care networks. Cost sensitivity favors spring-loaded mechanical systems over powered alternatives.
Hospitals retain procurement volume leadership. Emergency medical services posts the steepest trajectory.
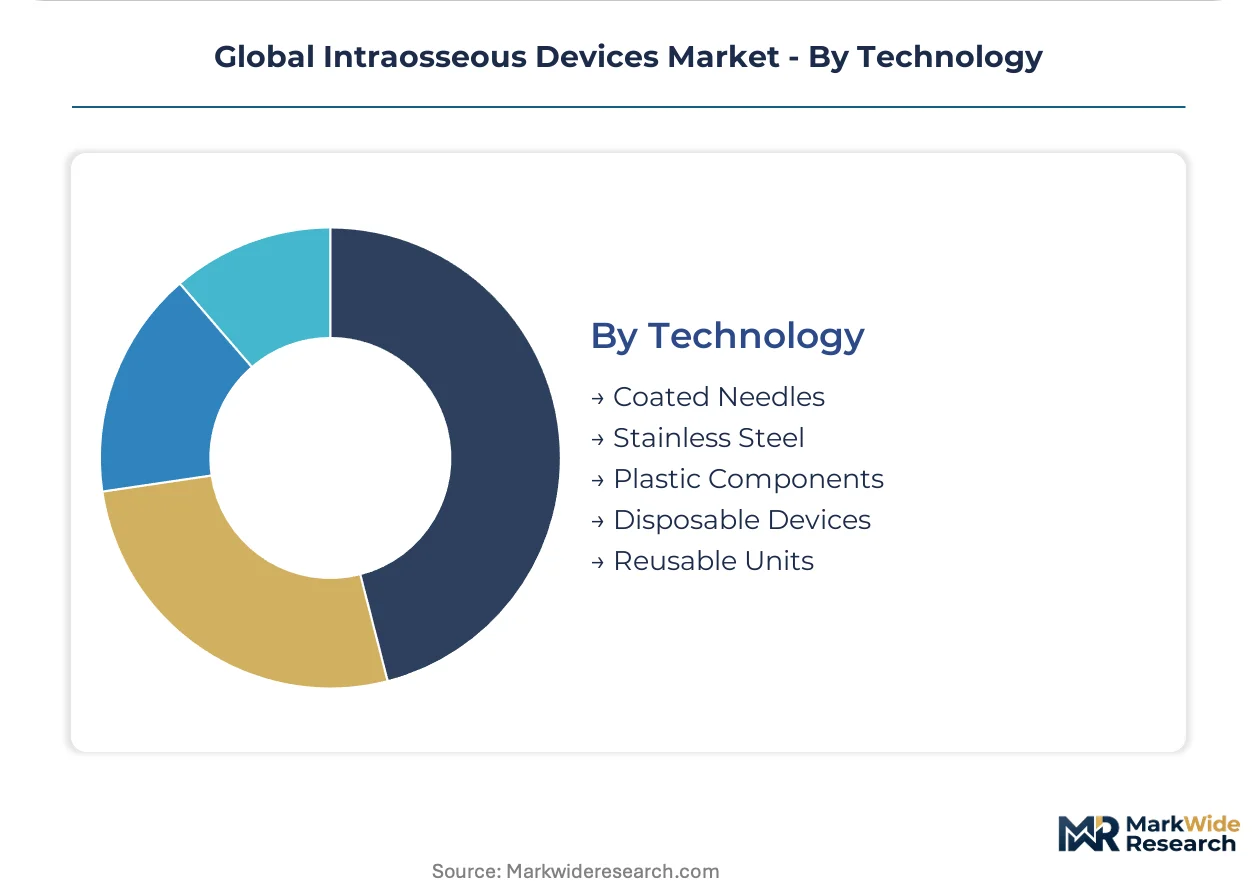
Technology:
Supply concentration in stainless steel needle manufacturing and disposable device assembly shapes margin structures across cost tiers.
- Disposable Devices:Single-use sterile packaging eliminates cross-contamination risk. dominates hospital procurement under infection control protocols.
- Stainless Steel:15-gauge to 18-gauge cannula material subject to raw material price volatility. Cost fluctuations compress margins for high-volume disposable producers.
- Coated Needles:Surface treatments reducing insertion friction and bone thermal injury. Premium pricing captures specialized trauma center share.
- Reusable Units:Battery-powered powertrain chassis with replaceable needle cartridges. Military and aeromedical platforms favor lifecycle cost economics.
- Plastic Components:Depth-limiting collars and ergonomic grips molded from medical-grade polymers. Cost reduction strategy for developing health system segments.
Disposable devices command the installed base. Reusable units climb fastest in military-aeromedical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the dominant geography, with military-civilian trauma networks and EU MDR tightening shaping procurement patterns across Germany and Japan.
United States
Emergency medical services expansion and cardiac arrest protocol standardization drive institutional procurement. FDA 510(k) pathway streamlining accelerates iterative device designs through predicate-based submissions. Military-civilian trauma networks in Texas and California concentrate defense health system integration.
Germany
NATO standardization protocols for vascular access training consolidate procurement mandates across defense health systems. EU MDR conformity assessment extends certification timelines for powered insertion systems. Medical device clusters in Baden-Württemberg and Bavaria host precision manufacturing for spring-loaded mechanical systems.
Japan
Helicopter emergency medical services networks generate demand for vibration-resistant, one-handed operation designs. METI industrial standards govern battery-powered system safety protocols. Aeromedical platforms in Tokyo and Osaka metropolitan areas standardize compact form factors for tactical evacuation.
United Kingdom
Paramedic scope-of-practice revisions authorize field intraosseous insertion, extending procedural volume beyond hospital settings. NHS supply chain centralization favors multi-year sole-source agreements under integrated delivery networks. Trauma research clusters in London and Birmingham anchor clinical evidence generation.
Australia
Air-medical platform specialization addresses remote and rural emergency access requirements. TGA conformity assessment aligns with ISO 7864 needle performance standards for regulatory submission packages. Aeromedical networks in New South Wales and Queensland standardize battery-powered designs for helicopter emergency services.
Global Intraosseous Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the intraosseous devices market. Established hospital systems favor integrated vascular access portfolios while prehospital networks prioritize portable, battery-dependent solutions. Three archetypes dominate: military-contract heritage players anchoring NATO supply chains, diversified medtech conglomerates with broad hospital penetration, and compact design specialists capturing aeromedical share. Competitive moves concentrate on regulatory infrastructure investment and procurement centralization through group purchasing organization consolidation.
Within the military-contract tier, Teleflex Incorporated exemplifies premium positioning through defense health system relationships. Becton, Dickinson and Company represents the diversified conglomerate archetype with integrated portfolio breadth. PerSys Medical occupies the compact specialization position for air-medical and tactical evacuation platforms.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Becton, Dickinson and Company |
| Cook Group |
| Cardinal Health, Inc. |
| SAM Medical |
| PerSys Medical |
| PAVmed Inc. |
| BIOPSYBELL S.R.L. |
| Argon Medical Devices, Inc. |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance pathways and EU MDR conformity assessments gate both supplier qualification and price differentiation simultaneously, compressing margins for unvalidated entrants while rewarding established players with regulatory infrastructure. Stainless steel needle cost volatility and battery powertrain component pricing feed directly into tiered product positioning across emergency medical services and hospital procurement channels.
Pricing Analysis
United States pricing for spring-loaded devices sits 15-25% above German equivalents, with Japanese battery-powered systems commanding premium positioning in aeromedical networks. Three-tier pricing structure across premium, standard, and economy levels separates NATO defense contract tiers from civilian hospital procurement and developing health system segments. Cost compression in manual needle categories is intensifying because stainless steel raw material volatility squeezes disposable device producers. Emergency medical services districts exhibit highest price sensitivity, while military healthcare providers prioritize performance reliability over unit economics.
Supply Chain Analysis
Inventory lead times for lithium-ion powertrain components have extended from 8 to 14 weeks, constraining battery-powered device assembly schedules. Manufacturing concentrates in United States and Germany for spring-loaded mechanical systems, Japan and Israel for compact powered designs, and China for stainless steel cannula forging. Supply chains draw from medical-grade polymer molding, precision spring fabrication, and lithium battery cell production. Single-source vulnerability in 15-gauge needle trocar tip manufacturing creates qualification bottlenecks for new entrants. Distribution runs through group purchasing organization networks in United States integrated delivery networks, direct defense procurement in NATO countries, and specialized aeromedical equipment distributors in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prehospital protocol expansion represents an early-cycle penetration story, with paramedic scope-of-practice revisions extending addressable procedural volume beyond traditional hospital settings.
For Market Incumbents: Compound regulatory infrastructure advantages by accelerating EU MDR post-market clinical follow-up data generation before Class III reclassification discussions conclude. Deepen backward integration into stainless steel cannula manufacturing to buffer raw material volatility. Anchor NATO trauma supply chain positioning through military-civilian network integration investments. For New Entrants and Emerging Players: Lead with pediatric anatomical precision applications where manual needle control requirements create white-space separation from established spring-loaded and battery-powered incumbents. Target helicopter emergency medical services in Japan and Australia where vibration-resistant, one-handed operation specifications favor compact design specialization. Pursue regulatory sandbox pathways through TGA and METI pilot programs before FDA submission. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compact design specialists holding aeromedical platform relationships but lacking hospital system breadth. Five-to-ten year viability hinges on procurement centralization through federal emergency management stockpile programs versus fragmented regional purchasing. Monitor civilian mass-casualty preparedness mandate implementation velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Accelerated predicate-based submissions reduce time-to-market for iterative battery-powered designs. |
| EU MDR Conformity Investment | Post-market clinical follow-up obligations elevate evidence requirements for powered insertion systems. |
| Hospital System Partnership | Integrated delivery network formulary standardization captures sixty to seventy percent of acute care admissions. |
| Military-Civilian Network Integration | NATO standardization protocols consolidate procurement mandates across Germany, United States, and United Kingdom. |
| Software Companion Development | Electronic health record API integration addresses documentation workflow requirements in critical care units. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with emergency medicine physicians, paramedic training directors, hospital purchasing committee members, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR notified body decisions, hospital procurement databases, and aeromedical equipment distributor records. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and technology dimensions.
Across the analysis window, volume and value outputs reflected segmented modeling of spring-loaded mechanical systems, battery-powered motorized designs, manual needles, and semi-automatic hybrid configurations. CAGRs derived from procedure volume elasticity, pricing trajectory assumptions, and penetration rate modeling for prehospital versus hospital-based settings. Military procurement forecasts incorporated NATO standardization protocol implementation timelines and defense health system budget allocation patterns.
The analysis sits within stated boundaries; outcomes outside FDA clearance timeline assumptions or EU MDR notified body capacity constraints would require recalibration. Forecasts reflect documented assumptions regarding stainless steel price stability and lithium battery supply availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Implantable Collamer Lens Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Global Defibrillators Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Disposable Lancets Market
Medical Devices
Autosamplers Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market