
 Midline Catheters Market | 2026-2036
Midline Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Midline Catheters Market Insights
Hospital procurement consortiums is rewriting how midline catheters reach end users, with group purchasing organizations now filtering vendor lists before products reach formulary committees. ICU Medical leverages its integrated infusion therapy portfolio to sustain contract renewals across major health systems. BD anchors North American supply through its broad vascular access manufacturing footprint. VYGON competes on European regulatory pedigree, extending its CE-marked product lines into Middle Eastern tenders.
Midline catheters are peripherally inserted vascular devices, typically 8 to 20 centimeters in length, designed for intermediate-term intravenous therapy lasting one to four weeks using polyurethane or silicone construction. These devices bridge the gap between short peripheral IVs and central venous catheters, reducing complication rates for patients requiring prolonged antibiotic, analgesic, or nutritional infusion. Antimicrobial-coated variants command premium positioning as infection control budgets harden across hospital end users. Ultrasound-guided insertion techniques represent the fastest-expanding procedural category, displacing anatomical landmark approaches in tertiary facilities where training infrastructure exists. Single-lumen configurations still occupy the highest volume tier, though double-lumen demand is accelerating in oncology and critical care settings where simultaneous incompatible infusions are required.
The FDA's infusion pump and vascular access device regulations, alongside the EU Medical Device Regulation's heightened clinical evidence requirements, are reshaping market access timelines and product development budgets for manufacturers seeking dual-territory approval. ISO 10555 standards for intravascular catheters provide the baseline technical benchmark that procurement committees reference during vendor qualification. Stakeholders must monitor how CMS reimbursement adjustments for outpatient parenteral therapy interact with hospital cost-containment mandates to determine whether midline adoption continues displacing central lines or faces procedural budget pressure.
Market Dynamics
Hospital group purchasing organizations are consolidating vendor qualification criteria around antimicrobial coating certifications and ultrasound-guided insertion compatibility, compressing the addressable supplier base for midline catheter manufacturers seeking formulary placement.
Growth Catalysts
- Outpatient Parenteral Antimicrobial Therapy (OPAT) expansion:United States hospital systems are scaling OPAT programs to reduce inpatient bed utilization, creating sustained demand for four-week dwell-time vascular access devices that bridge peripheral IV and central line functionality.
- FDA infusion therapy guidance updates:The agency's clarified predicate device pathways for polyurethane-based midlines are shortening 510(k) review timelines for manufacturers with established biocompatibility data packages.
- Ultrasound-guided insertion training:Tertiary care facilities are embedding point-of-care ultrasound certification into nursing competency frameworks, reducing anatomical landmark placement failures and expanding eligible patient populations.
Market Restraints
- Medical-grade polyurethane supply concentration:Three specialty chemical producers control approximately seventy percent of catheter-grade thermoplastic polyurethane resin, exposing device manufacturers to input cost volatility and allocation constraints during polymer production disruptions.
- EU MDR clinical evidence requirements:The regulation's heightened scrutiny of legacy device substantiation is extending recertification timelines and inflating regulatory affairs budgets for manufacturers seeking CE mark maintenance.
- Peripherally inserted central catheter (PICC) substitution:PICC lines retain reimbursement advantages in certain CMS outpatient payment classifications, limiting midline penetration in fee-for-service environments where procedural economics drive device selection.
Strategic Opportunities
- Home infusion pharmacy networks:Independent specialty pharmacies are building in-house vascular access capabilities, creating direct-to-provider distribution channels that bypass traditional hospital supply chain intermediaries.
- Double-lumen oncology configurations:Simultaneous incompatible infusion protocols in ambulatory cancer centers are accelerating demand for multi-lumen midlines that previously required central venous placement.
- Japan's aging vascular access patient population:METI's chronic care infrastructure investments are expanding intermediate-term infusion capacity in community hospitals with limited interventional radiology resources.
Industry Challenges
- Point-of-care ultrasound competency gaps:Rural and community hospitals lack the capital budgets and clinical educator bandwidth to train nursing staff on vessel visualization techniques, constraining adoption outside academic medical centers.
- ISO 10555-1 harmonization delays:Divergent national interpretations of dimensional tolerance testing are forcing manufacturers to maintain multiple validation protocols, inflating quality assurance overhead without improving safety outcomes.
- Antimicrobial coating durability verification:Extended shelf-life claims for chlorhexidine-silver sulfadiazine surface treatments require costly real-time aging studies that strain R&D timelines for product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Midline Catheters Market |
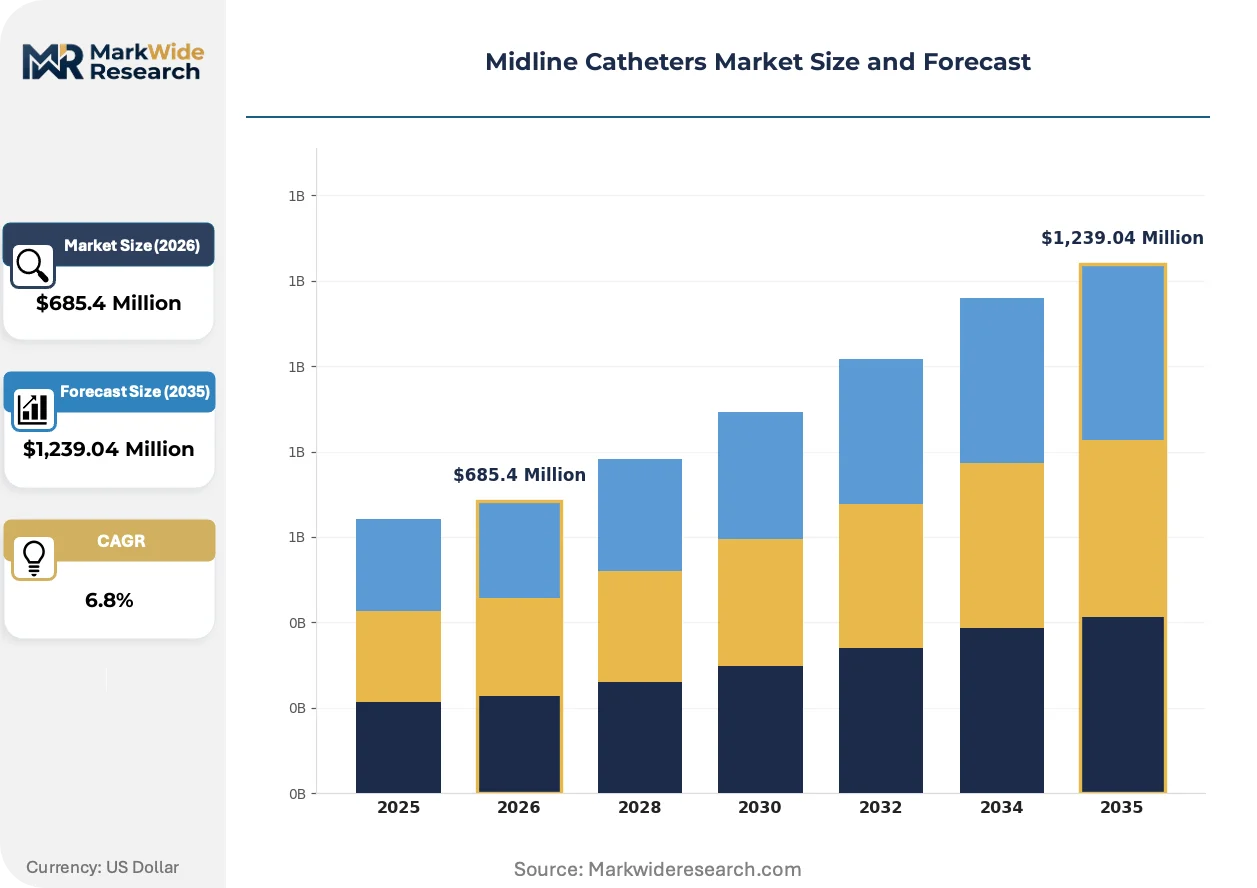
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Double-Lumen, Antimicrobial, Standard End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Material: Polyurethane, PVC, Silicone, Coated Materials Insertion Technique: Ultrasound-Guided, Anatomical Landmark, Fluoroscopy, Radial Approaches |
| Companies Covered | ICU Medical, VYGON, BD, Spectrum Vascular, Medcomp, Teleflex, Argon Medical Devices, Haolang Technology, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Midline Catheters Market Trends and Innovations
Material science advances and procedural technique standardization are compressing the functional gap between peripheral and central vascular access, reshaping how clinicians approach intermediate-term infusion therapy planning.
Polyurethane-silicone hybrid catheter construction is hybridizing material properties to optimize kink resistance and biocompatibility simultaneously. Academic medical centers in the United States are piloting these dual-durometer designs in oncology and critical care units where catheter durability directly impacts therapy completion rates. The convergence is compressing the historical trade-off between flexibility and tensile strength that forced clinicians to choose device types based on anatomical insertion site rather than therapeutic indication.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic implant registries for vascular access devices with dwell times exceeding seventy-two hours. Manufacturers must now fund prospective clinical follow-up studies or leverage existing hospital quality databases to demonstrate sustained safety profiles. German and French notified bodies are applying the most stringent interpretations, creating a two-tier approval landscape where MDR compliance depth varies by conformity assessment route.
Consolidated purchasing at integrated delivery networks is unbundling midline catheter procurement from traditional broadline distributor contracts. Large United States health systems are negotiating direct manufacturer agreements with price transparency provisions tied to utilization benchmarking data. This behavior is most visible in the Southeast and Midwest regions where hospital merger activity has created super-regional entities with sufficient volume to justify dedicated supply chain infrastructure.
Midline Catheters Market Segmentation
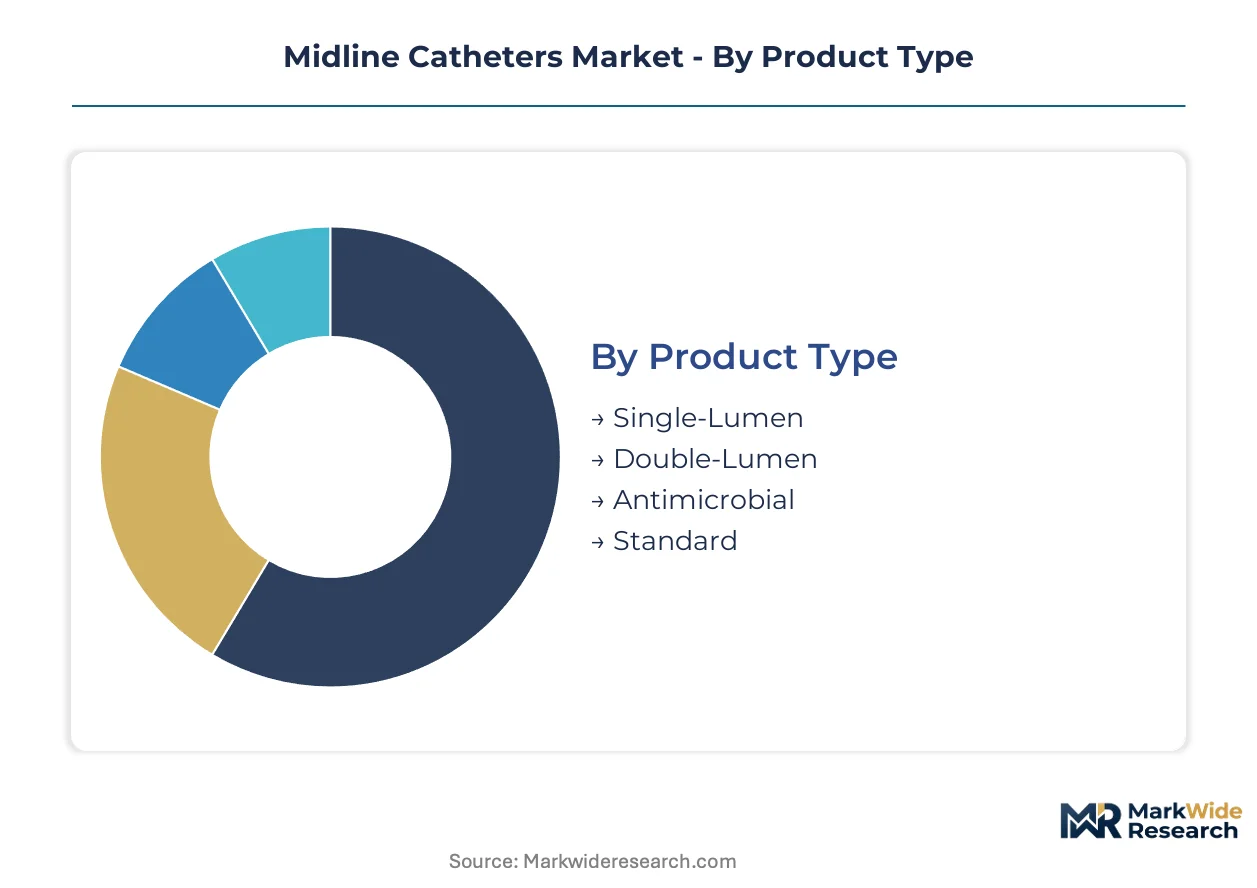
Midline catheter procurement varies sharply by clinical setting and therapeutic indication, with device specifications determining formulary placement across hospital systems. Manufacturers align product portfolios to distinct insertion protocols and antimicrobial requirements rather than pursuing undifferentiated volume strategies.
Product Type:
Use-case spectrum spans simple hydration to complex oncology protocols, with lumen configuration and surface treatment defining reimbursement eligibility and infection control compliance.
- Single-Lumen:Polyurethane construction dominates this category for antibiotic and analgesic infusions requiring sequential rather than simultaneous drug delivery. Hospital systems in the United States standardize on these devices for OPAT programs where cost containment intersects with four-week dwell-time protocols.
- Double-Lumen:Dual-channel construction permits incompatible infusion administration without central line placement, capturing demand in ambulatory cancer centers. Academic medical centers in tertiary facilities favor these configurations for patients requiring simultaneous chemotherapy and hydration protocols.
- Antimicrobial:Chlorhexidine-silver sulfadiazine surface coatings address CLABSI reduction mandates from CMS and Joint Commission auditors.
- Standard:Uncoated polyurethane devices serve price-sensitive procurement tiers in community hospital systems without dedicated infection control budgets.
Established volume favors Single-Lumen; emerging adoption favors Double-Lumen.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks controlling hospital purchasing while home infusion pharmacies build direct manufacturer relationships.
- Hospitals:Group purchasing organizations filter vendor lists before formulary committee review, with antimicrobial certification and ultrasound compatibility as gatekeeping criteria. Major health systems in the United States negotiate utilization-based pricing tied to benchmarking data.
- Home Care:Specialty pharmacy networks bypass traditional distributor contracts, creating direct-to-provider channels for patients discharged on parenteral therapy. Independent infusion providers in the Southeast and Midwest regions drive this segment's expansion.
- Clinics:Outpatient facilities with limited interventional radiology capacity favor midlines over PICC lines for intermediate-term access.
- Long-Term Care Facilities:Skilled nursing facilities face competency gaps in ultrasound-guided placement, constraining adoption to anatomical landmark techniques.
Hospital procurement maintains volume dominance; home care channels are climbing the fastest.
Material:
Supply concentration in medical-grade thermoplastic resins exposes manufacturers to input cost volatility and allocation constraints during polymer production disruptions.
- Polyurethane:Catheter-grade thermoplastic polyurethane from three specialty chemical producers supplies the majority of device construction. FDA 510(k) predicate pathways favor established biocompatibility data packages for this material.
- Silicone:Soft, low-durometer construction suits patients with fragile vasculature or extended dwell-time requirements in oncology settings.
- PVC:Cost-driven selection in emerging markets and budget-constrained procurement tiers where regulatory scrutiny of plasticizers remains limited.
- Coated Materials:Hybrid constructions combining polyurethane substrates with antimicrobial surface treatments command premium positioning.
Polyurethane anchors current supply; silicone variants are gaining share fastest in specialty applications.
Insertion Technique:
Procedural competency infrastructure determines adoption patterns, with capital equipment and clinical educator bandwidth creating divergence between academic and community settings.
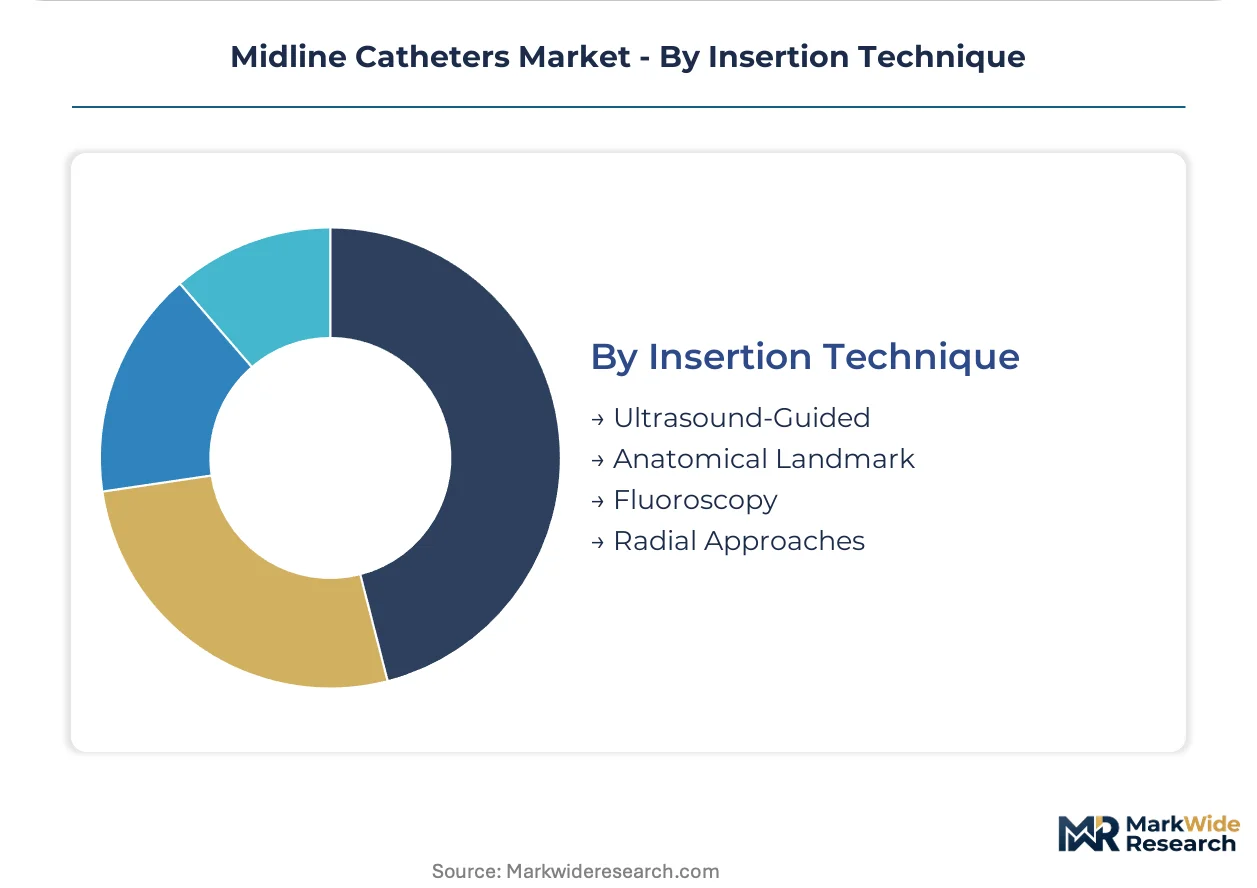
- Ultrasound-Guided:Point-of-care visualization reduces anatomical landmark placement failures and expands eligible patient populations. Tertiary care facilities embed this certification into nursing competency frameworks.
- Anatomical Landmark:Traditional surface anatomy approaches persist in rural and community hospitals lacking ultrasound capital budgets or training infrastructure.
- Fluoroscopy:Interventional radiology suite placement for patients with challenging vascular anatomy or failed peripheral access attempts.
- Radial Approaches:Distal upper extremity insertion sites reduce central line conversion rates in patients with upper arm vessel limitations.
Anatomical landmark retains procedural volume; ultrasound-guided methods show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics hub underwrites Europe's vascular access device distribution, while the Trans-Pacific trade lanes connecting Shanghai to Long Beach anchor Asia-North America supply chains for catheter-grade polymers.
United States
Outpatient parenteral antimicrobial therapy programs at Cleveland Clinic and Mayo Clinic networks are scaling four-week dwell-time protocols. FDA's updated 510(k) predicate pathways for polyurethane midlines compress review timelines for established manufacturers. Hospital procurement consortiums in the Southeast and Midwest are negotiating direct manufacturer agreements with utilization-based pricing provisions.
Germany
Notified bodies in Berlin and Munich are applying stringent MDR interpretations for vascular access device recertification, extending clinical evidence timelines. EU Medical Device Regulation's post-market surveillance mandates systematic implant registries for devices exceeding seventy-two-hour dwell times. The Rhine-Ruhr medical technology cluster hosts catheter manufacturers adapting quality systems to heightened notified body scrutiny.
Japan
METI's chronic care infrastructure investments are expanding intermediate-term infusion capacity in community hospitals with limited interventional radiology resources. The country's national pharmaceutical regulator maintains distinct biocompatibility testing protocols that parallel ISO 10555 standards. Osaka-based medical device distributors are building vascular access training programs for aging patient populations in Kansai region facilities.
China
NMPA's streamlined Class II device registration pathways are accelerating domestic manufacturer market entry for polyurethane catheters. The Yangtze River Delta medical device manufacturing belt in Jiangsu and Zhejiang provinces concentrates catheter-grade thermoplastic polyurethane processing capacity. Shanghai's hospital procurement platforms are piloting volume-based purchasing for midline devices in tertiary oncology centers.
United Kingdom
NHS England's infection control mandates are hardening formulary requirements around antimicrobial-coated vascular access devices. The national pharmaceutical regulator aligns with EMA guidance on chlorhexidine-silver sulfadiazine surface treatment substantiation. London's academic medical centers are embedding point-of-care ultrasound certification into vascular access nursing competency frameworks.
Midline Catheters Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the catheter supply chain. The market exhibits moderate consolidation around integrated infusion therapy portfolios, with three to four manufacturers controlling formulary placement at major United States health systems. Two strategic archetypes dominate: diversified medical device conglomerates leveraging broad vascular access manufacturing footprints, and vascular access specialists competing on regulatory pedigree and ultrasound-guided insertion compatibility. Competitive moves center on antimicrobial coating certification acquisition and direct-to-provider distribution channel development.
Within the diversified conglomerate tier, ICU Medical and BD exemplify platform integrators anchoring North American supply through integrated infusion therapy portfolios. VYGON occupies a position representing European regulatory pedigree, with CE-marked product lines extending into Middle Eastern procurement tenders. These three entities represent distinct competitive positioning vectors: integrated system breadth, manufacturing scale, and regulatory geographic reach.
| Leading Market Players |
|---|
| ICU Medical |
| VYGON |
| BD |
| Spectrum Vascular |
| Medcomp |
| Teleflex |
| Argon Medical Devices |
| Haolang Technology |
| Smiths Medical |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta manufacturing belt concentrates catheter-grade thermoplastic polyurethane processing capacity, with Jiangsu and Zhejiang provinces anchoring resin supply for device manufacturers. This geographic concentration grants specialty chemical producers substantial leverage over input costs, compressing margins for midline catheter producers while enabling volume-based pricing tiers for hospital procurement consortiums.
Pricing Analysis
Volume-discount tiering structures dominate hospital group purchasing negotiations, with antimicrobial-coated devices commanding premium positioning against standard polyurethane variants. Price differentiation stems from CE mark depth and ultrasound-guided insertion compatibility certifications. Pricing pressure intensifies as integrated delivery networks demand utilization-based pricing tied to benchmarking data. Community hospital systems exhibit highest price sensitivity, while academic medical centers prioritize infection control compliance over per-unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among three specialty chemical producers controlling catheter-grade thermoplastic polyurethane resin supply. Geographic supply anchors in China, Germany, and the United States. Raw material dependencies include medical-grade thermoplastic polyurethane, chlorhexidine-silver sulfadiazine coatings, and precision extrusion equipment. Single-source vulnerability in resin supply exposes manufacturers to allocation constraints during polymer production disruptions. Distribution runs through broadline medical distributors and direct-to-provider channels for home infusion pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as integrated infusion therapy portfolios displace standalone device procurement, with interoperability between vascular access devices and infusion pumps reshaping hospital formulary decisions.
For Market Incumbents: Entrench integrated system positioning by bundling midline catheters with infusion pump compatibility certifications and securing GPO contract renewals ahead of EU MDR recertification deadlines. Backward integration into catheter-grade polyurethane resin supply mitigates input cost volatility from specialty chemical producers. Prioritize antimicrobial coating durability verification to defend premium positioning against standard-device substitution.
For New Entrants and Emerging Players: Pursue direct-to-provider distribution partnerships with independent home infusion pharmacy networks in the Southeast and Midwest regions, bypassing consolidated hospital procurement channels. White-space concentration exists in double-lumen oncology configurations for ambulatory cancer centers lacking interventional radiology capacity. Lead with ultrasound-guided insertion training programs as differentiated go-to-market support.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core vascular access portfolios amid EU MDR compliance cost inflation. Long-term viability favors manufacturers with established FDA 510(k) predicate pathways and hospital system direct contracts. Monitor CMS reimbursement adjustments for outpatient parenteral therapy as inflection signal for midline versus PICC line substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Certification | CE mark depth under MDR and FDA 510(k) clearance determine formulary access at major health systems. |
| Ultrasound-Guided Insertion Training | Nursing competency programs expand eligible patient populations beyond academic medical centers. |
| Direct-to-Provider Distribution | Home infusion pharmacy partnerships bypass consolidated GPO channels and capture OPAT program volume. |
| Polyurethane-Silicone Hybrid Development | Dual-durometer construction addresses oncology and critical care durability requirements. |
| Hospital System Partnership | Integrated delivery network contracts with utilization-based pricing provisions lock in multi-year revenue. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body guidance, hospital procurement databases, and GPO contract disclosures. Primary interviews engaged vascular access nursing directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, ISO 10555 standards documentation, and trade customs records. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, material, and insertion technique segments.
Forecast inputs incorporate procedural volume trends, regulatory pathway timelines, and reimbursement policy shifts across the projection horizon. Segmentation dimensions modeled include lumen configuration, surface treatment, clinical setting, material composition, and geographic regulatory cluster. CAGRs derive from regression analysis of historical procedural adoption curves and elasticity estimates for OPAT program expansion. Industry-specific inputs include ultrasound-guided insertion training penetration rates and antimicrobial coating certification acquisition timelines.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or polymer resin pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and reimbursement stability. Quarterly review of FDA 510(k) clearance timelines and CMS outpatient payment classification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Steerable Needles Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
US Stethoscope Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Digital Phoropter Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Global Vein Finders Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
North America Ultrasound Probe Disinfection Market