
 Medical Carts and Workstations Market | 2026-2036
Medical Carts and Workstations Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Carts and Workstations Market Intelligence
Hospital leasing and subscription-based fleet financing is reshaping competitive dynamics in medical cart procurement. Midmark Corporation leverages its vertical manufacturing infrastructure to sustain cost advantages across plastic and metal workstation lines. Capsa Healthcare anchors its position through specialized medication delivery cart configurations designed for acute care workflows. Ergotron, Inc. competes on ergonomic adjustability standards that differentiate its wall-mounted and mobile computing platforms.
Medical carts and workstations are mobile or fixed healthcare furniture systems engineered to support clinical computing, medication management, and equipment transport, typically incorporating antimicrobial surfaces, cable management systems, and load ratings between 75 and 200 pounds for integrated devices. Their primary purpose is to position technology and supplies at the point of care while minimizing nurse fatigue and infection transmission risk. Workstations on wheels command the largest installed base across hospitals due to their flexibility in supporting both patient monitoring and medication delivery applications. Procedure carts represent the fastest-expanding category as surgical centers invest in specialized storage for sterile instrument sets and anesthesia supplies. Metal-framed units retain premium positioning where durability and infection control protocols justify higher capital outlays.
The FDA regulates medical carts supporting diagnostic or therapeutic devices under device classification frameworks, while IEC 60601 and ISO 13485 standards govern electrical safety and quality management for powered workstation configurations. These requirements create compliance barriers that favor established manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving cybersecurity guidelines for networked carts and assess whether backward integration into power system components offers sustainable margin protection as component costs fluctuate.
Market Dynamics
Hospital fleet standardization programs are consolidating vendor relationships and compressing purchasing cycles across health systems, favoring manufacturers with modular platform architectures and rapid configuration capabilities.
Growth Catalysts
- Acute care capacity expansion:Hospital construction in the United States and Germany is driving fleet purchases of mobile computing workstations for emergency departments and intensive care units.
- IEC 60601-1 third edition:Electrical safety mandates for powered medical equipment are accelerating replacement cycles for aging cart fleets in accredited facilities.
- Antimicrobial copper alloys:Surface material innovations are opening specification opportunities in infection-sensitive departments including oncology and transplant units.
Market Restraints
- Aluminum and steel price volatility:Metal-framed workstation production faces margin pressure from commodity input swings that manufacturers cannot fully pass through under multi-year hospital contracts.
- Castor and wheel assembly concentration:Supply bottlenecks from specialized mobility component suppliers in Taiwan create lead time uncertainty for cart OEMs.
- Powered cart battery substitution:Lithium iron phosphate systems are displacing sealed lead-acid configurations, forcing capital retooling for legacy power system integrators.
Strategic Opportunities
- Ambulatory surgical center underpenetration:Freestanding surgery facilities in the United States represent unserved demand for specialized procedure and anesthesia cart configurations.
- Modular power system convergence:Hot-swappable battery architectures combined with wireless charging pads are enabling continuous-use workflows in 24-hour clinical environments.
- Leasing channel innovation:Equipment-as-a-service models through healthcare finance intermediaries are lowering capital barriers for mid-size hospital systems.
Industry Challenges
- Cybersecurity certification timelines:FDA guidance on networked medical device security is extending product validation cycles for smart cart configurations with embedded computing.
- Legacy EMR integration complexity:Health systems with decade-old electronic medical record infrastructure require custom mounting and connectivity adaptations that fragment production scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Carts and Workstations Market |
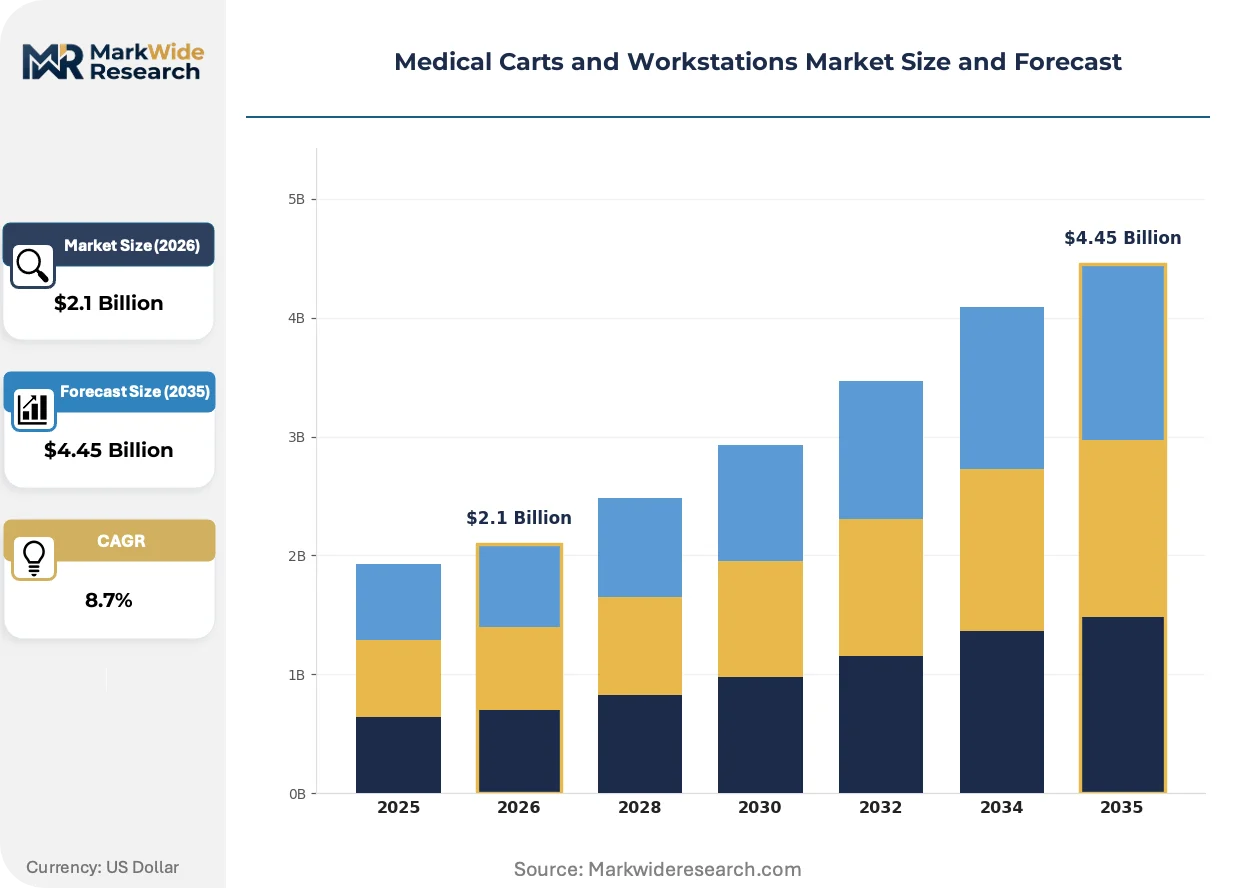
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Carts, Mobile Carts, Workstations on Wheels, Procedure Carts End User: Hospitals, Clinics, Emergency Rooms, Surgical Centers Material: Metal, Plastic, Wood, Composite Materials Application: Medication Delivery, Patient Monitoring, Equipment Storage, Surgical Support |
| Companies Covered | Midmark Corporation, Capsa Healthcare, Ergotron, Inc., The Harloff Company, Bergmann Group, Enovate Medical, Altus Inc., ITD GmbH, AFC Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Carts and Workstations Market Strategic Shifts & Innovations
Workstation engineering is pivoting from hardware durability to intelligent asset management, embedding sensors and connectivity that transform carts into networked clinical infrastructure rather than passive furniture.
Single-battery hot-swap architectures are collapsing the operational distinction between powered and non-powered cart categories. Acute care nurses now expect continuous runtime without workflow interruption for charging. This convergence is collapsing the premium pricing gap that historically separated basic medication carts from full-computing workstations.
The FDA's cybersecurity premarket guidance for networked medical devices is tightening validation requirements for carts with embedded PCs and wireless connectivity. Manufacturers must now document threat modeling and software bill of materials submissions. Powered computing cart segments face the steepest compliance cost escalation as they fall under both device and cybersecurity regulatory frameworks.
Subscription-based fleet management is displacing capital purchase models among consolidated health systems. Third-party logistics providers now handle preventive maintenance, battery replacement, and technology refresh cycles. This shift is most visible in United States multi-hospital networks where procurement centralization favors operational expenditure structures over depreciable asset ownership.
Medical Carts and Workstations Market Segmentation
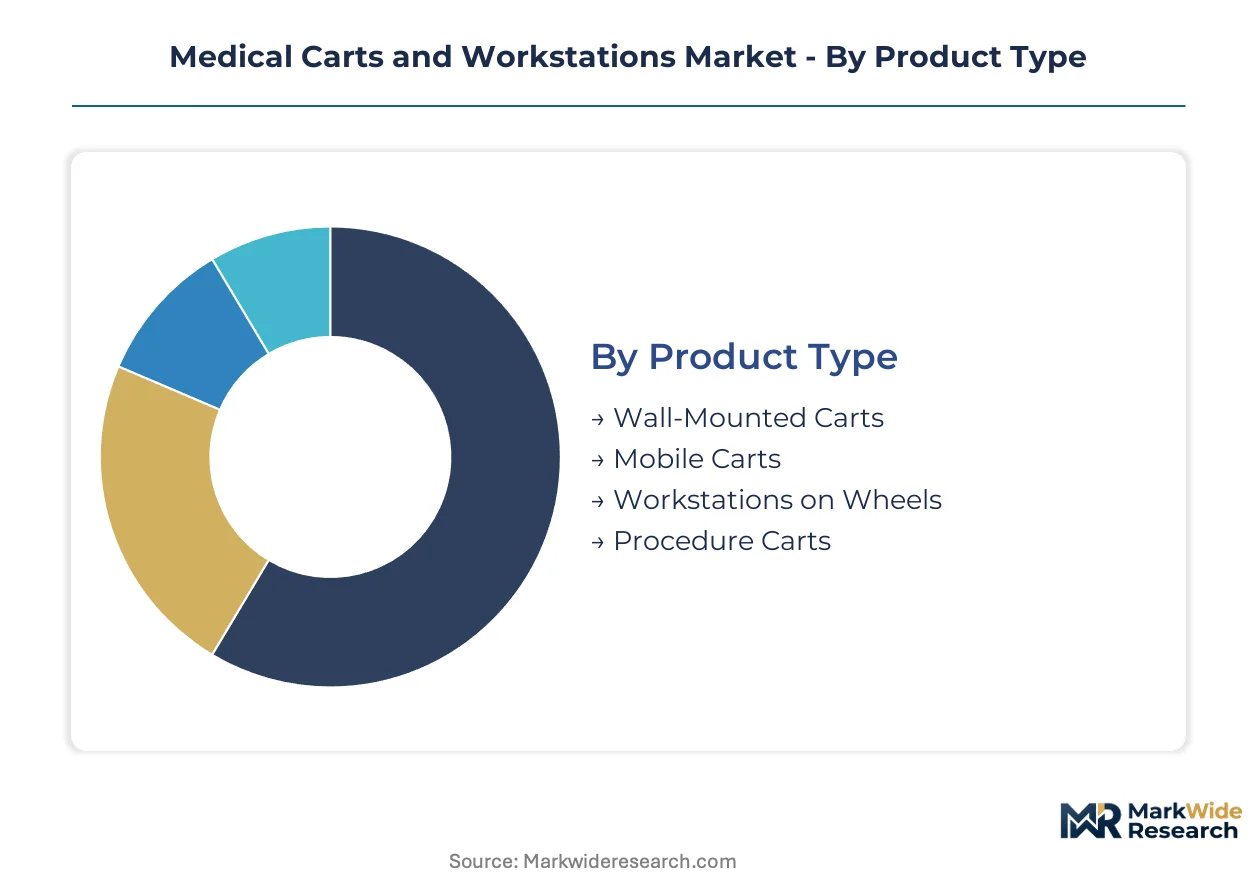
Segmentation in medical carts and workstations determines procurement patterns across health systems with divergent clinical workflows and capital constraints. Hospital fleet standardization programs increasingly favor modular platforms that span multiple product configurations and end-use settings.
Product Type:
After-sales service intensity varies sharply across product categories, with powered mobile units requiring battery replacement programs and preventive maintenance contracts that non-mobilized configurations do not.
- Workstations on Wheels:These mobile computing platforms integrate height-adjustable surfaces, cable management systems, and hot-swappable power architectures for continuous clinical use. Demand concentrates in United States acute care hospitals expanding emergency department capacity, driven by nurse workflow efficiency mandates and IEC 60601 electrical safety compliance requirements for powered equipment.
- Procedure Carts:Specialized configurations feature modular drawer systems, antimicrobial surfaces, and sterile field compatibility for surgical instrument organization. United States ambulatory surgical centers are driving specification volume as freestanding facilities invest in dedicated anesthesia and instrument storage solutions that match hospital-grade infection control protocols.
- Mobile Carts:Transport-focused designs prioritize castor mobility and load ratings for device relocation between care zones.
- Wall-Mounted Carts:Fixed installations serve space-constrained environments with folding mechanisms for corridor clearance.
Workstations on wheels hold the largest share; momentum sits with procedure carts.
End User:
Capital allocation cycles differ materially across customer types, with consolidated health systems negotiating enterprise pricing while independent surgical centers prioritize lease-based acquisition structures.
- Hospitals:Multi-facility networks in the United States dominate fleet procurement through group purchasing organizations, standardizing on modular platforms that reduce spare parts inventory and technician training costs. German hospital construction programs are simultaneously expanding intensive care unit deployments of mobile computing workstations.
- Surgical Centers:Freestanding United States facilities represent underpenetrated demand for specialized procedure cart configurations with anesthesia supply integration and rapid sterilization turnaround features.
- Clinics:Outpatient settings prioritize compact footprints and basic medication delivery functionality over full computing integration.
- Emergency Rooms:Trauma-focused departments require crash cart configurations with defibrillator mounting and resuscitation supply organization.
Hospitals command the dominant procurement volume; surgical centers are climbing the fastest.
Material:
Input cost volatility and infection control certification requirements create divergent margin profiles across material categories, with metal-framed production exposed to commodity price swings that plastic and composite alternatives partially avoid.
- Metal:Aluminum and steel constructions retain premium positioning in oncology and transplant units where durability and antimicrobial copper alloy surface integration justify higher capital outlays. United States health systems specify metal-framed units for high-utilization departments despite aluminum price volatility compressing manufacturer margins under multi-year contract terms.
- Plastic:Polymer-based configurations offer weight reduction and corrosion resistance for basic medication delivery applications in non-critical care settings.
- Composite Materials:Hybrid constructions balance structural rigidity with weight optimization for specialized transport applications.
- Wood:Limited deployment in administrative and non-clinical environments where aesthetic considerations override infection control protocols.
Metal dominates premium specifications; plastic captures the steepest expansion trajectory in cost-sensitive procurement.
Application:
Workflow integration complexity varies by clinical function, with medication delivery requiring FDA device classification compliance for cart-mounted dispensing systems that equipment storage configurations do not trigger.
- Medication Delivery:Cart configurations integrate barcode scanning, automated dispensing interfaces, and controlled substance security for nurse-administered pharmaceutical workflows. United States hospitals are standardizing fleet purchases of powered medication carts with hot-swap battery architectures to eliminate charging downtime.
- Patient Monitoring:Mobile platforms support telemetry device transport and continuous vital sign display at the point of care.
- Surgical Support:Sterile field compatibility and rapid instrument accessibility define specifications for operating room integration.
- Equipment Storage:Basic supply organization functions prioritize drawer configuration flexibility over computing integration.
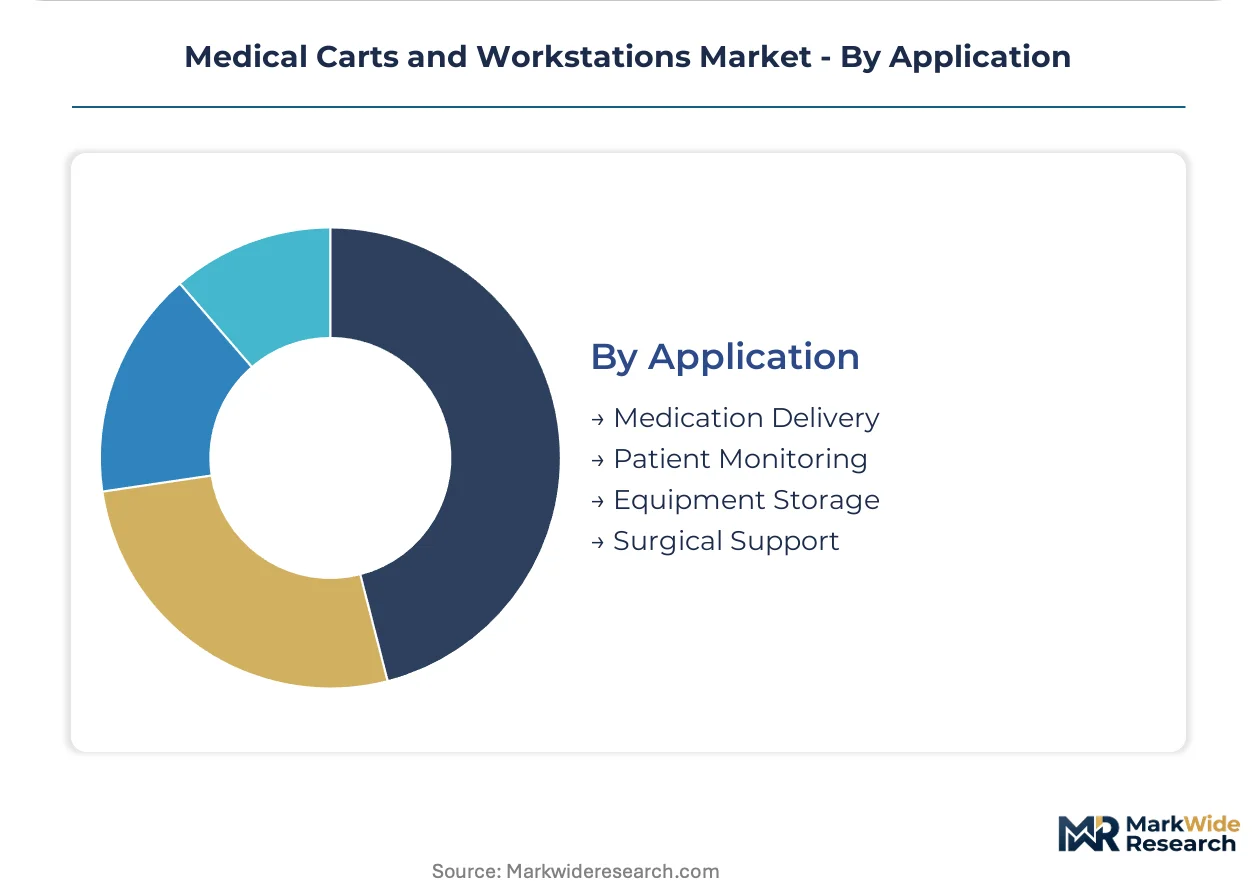
Medication delivery holds the largest share; surgical support is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device classification requirements and IEC 60601 electrical safety standards are elevating compliance costs for manufacturers across major markets. Demand is concentrating in the United States as health systems consolidate procurement through group purchasing organizations. Hospital construction programs in Germany are simultaneously expanding intensive care unit deployments of mobile computing workstations.
United States
Acute care hospitals are expanding fleet purchases of mobile computing workstations for emergency departments and intensive care units. HIPAA security requirements and FDA 510(k) clearance pathways govern powered cart configurations with embedded computing. Texas Medical Center in Houston anchors procurement concentration as multi-hospital networks standardize on modular platform architectures.
Germany
Hospital construction programs are driving fleet purchases of mobile computing workstations for intensive care unit capacity expansion. IEC 60601-1 third edition electrical safety mandates accelerate replacement cycles for aging cart fleets in accredited facilities. Baden-Württemberg manufacturing clusters around Stuttgart supply precision metal framing components for premium workstation lines.
United Kingdom
NHS procurement frameworks are consolidating vendor relationships across multi-site hospital trusts. MHRA device registration requirements and CE marking under EU MDR transitional provisions create compliance barriers for powered workstation configurations. London-based health systems are standardizing fleet purchases through NHS Supply Chain central procurement.
Japan
Metropolitan hospital networks are upgrading medication delivery cart fleets to support barcode scanning integration. PMDA medical device quality management requirements and JIS standards for electrical safety elevate validation costs for powered configurations. Osaka-based manufacturing clusters supply antimicrobial surface treatments for infection-sensitive department specifications.
Canada
Provincial health authorities are consolidating procurement for rural hospital network fleet standardization. Health Canada device licensing requirements and CSA electrical safety standards govern powered workstation configurations. Ontario manufacturing corridors around Toronto supply metal-framed units for high-utilization department specifications.
Medical Carts and Workstations Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered procurement structures. The vendor base clusters around three strategic archetypes: vertically integrated manufacturers with captive metal fabrication, ergonomic design specialists with certification depth, and modular platform architects with rapid configuration capabilities. Dominant competitive moves include strategic partnerships with healthcare finance intermediaries for equipment-as-a-service models and portfolio diversification into antimicrobial surface material integration.
Within the vertically integrated tier, Midmark Corporation and Capsa Healthcare represent manufacturers with dedicated regulatory affairs capabilities. Ergotron, Inc. exemplifies the ergonomic specialization archetype. These three companies anchor the competitive structure as hospital fleet standardization programs compress purchasing cycles and favor established players with IEC 60601 compliance documentation and FDA quality system infrastructure.
| Leading Market Players |
|---|
| Midmark Corporation |
| Capsa Healthcare |
| Ergotron, Inc. |
| The Harloff Company |
| Bergmann Group |
| Enovate Medical |
| Altus Inc. |
| ITD GmbH |
| AFC Industries |
| Others |
Cost & Logistics Intelligence
Baden-Württemberg's precision metal fabrication clusters supply structural framing components that anchor premium workstation pricing power in European and North American hospital procurement. Taiwanese castor and wheel assembly manufacturers concentrate mobility system supply, creating downstream cost transmission effects when component lead times extend.
Pricing Analysis
Certification level (FDA 510(k)-grade versus basic institutional-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates hospital fleet procurement, with metal-framed IEC 60601-compliant units commanding substantial premiums over plastic configurations. Cost compression in standard-tier medication carts is intensifying because aluminum price volatility compresses manufacturer margins under multi-year GPO contracts. Independent surgical centers exhibit highest price sensitivity, while consolidated United States health systems prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Extended payment terms from hospital procurement departments are forcing upstream working capital strain onto component suppliers and contract manufacturers. Supply concentrates in Germany for precision metal framing, Taiwan for castor and wheel assemblies, and China for lithium iron phosphate battery cells. Raw material dependencies span aluminum and steel for structural components, antimicrobial copper alloys for infection-sensitive surfaces, and specialized polymers for drawer systems. Single-source vulnerability in Taiwanese mobility component supply creates lead time uncertainty for cart OEMs. Distribution runs through group purchasing organizations and healthcare finance intermediaries offering equipment-as-a-service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at an inflection point where IEC 60601-1 third edition electrical safety mandates and FDA cybersecurity premarket guidance are simultaneously elevating compliance barriers and accelerating replacement cycles.
For Market Incumbents: Build regulatory affairs capability moats through dedicated FDA quality system infrastructure and IEC 60601 compliance documentation depth. Incumbents should anchor hospital fleet standardization programs with modular platform architectures that reduce spare parts inventory complexity for procurement committees. Battery system substitution toward lithium iron phosphate configurations threatens legacy power integrators; backward integration into hot-swappable power modules protects margin position. Channel control through strategic partnerships with healthcare finance intermediaries locks in subscription-based fleet management relationships. For New Entrants and Emerging Players: United States ambulatory surgical centers represent the most penetrable entry point for specialized procedure cart configurations with anesthesia supply integration and rapid sterilization turnaround features. Modular power system convergence combining wireless charging pads with continuous-use architectures offers white-space opportunity in 24-hour clinical environments. Go-to-market execution should leverage direct clinical workflow consultation rather than competing through GPO channel access that established players dominate. For Investors and Strategic Acquirers: Long-term, this sits as a healthcare infrastructure modernization play because hospital construction programs and electrical safety mandate compliance create durable replacement demand regardless of macroeconomic cyclicality. Acquisition targets should display vertical manufacturing infrastructure with captive metal fabrication and dedicated regulatory affairs teams. The signal to watch is FDA cybersecurity premarket guidance finalization timelines, which will extend validation cycles and favor established players with existing quality system infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 60601-1 Third Edition Compliance Investment | Electrical safety certification accelerates replacement cycles in accredited United States and German facilities. |
| Hot-Swappable Battery Architecture Development | Continuous-use workflows eliminate charging downtime and collapse premium pricing gaps between cart categories. |
| Antimicrobial Copper Alloy Surface Integration | Infection-sensitive oncology and transplant unit specifications open premium specification opportunities. |
| Equipment-as-a-Service Channel Partnership | Healthcare finance intermediaries lower capital barriers for mid-size hospital systems. |
| FDA Cybersecurity Premarket Submission |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, GPO contracts managers, acute care nurse managers, and cart OEM product development leads. Secondary validation drew from FDA 510(k) device classification filings, hospital procurement database aggregations, IEC 60601 certification registries, and group purchasing organization contract disclosures. Bottom-up unit demand modeling triangulated against top-down health system capital expenditure patterns.
Calibration against historical replacement cycle data and hospital construction pipeline disclosures anchored volume projections across the analysis window. Segmentation dimensions modeled include product type (workstation versus procedure versus mobile versus wall-mounted), end-user facility category, material construction, and clinical application workflow. CAGRs derived from weighted average of replacement-driven demand and capacity expansion-driven demand, with specific inputs from electrical safety mandate compliance deadlines and antimicrobial surface material adoption curves.
Practitioners should monitor FDA cybersecurity guidance finalization and lithium iron phosphate battery cost curves for early signals of competitive repositioning. Forecasts reflect assumptions regarding hospital consolidation trajectories and GPO procurement centralization. Macroeconomic deviation affecting health system capital budgets, regulatory timeline shifts, or battery technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Orthopedic Operating Tables Market
Medical Equipment
Centrifuge Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Global Platelet Incubator Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
US Durable Medical Equipment Market