
 South Africa Aesthetic Devices Market | 2026-2036
South Africa Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Aesthetic Devices Market Analytics
Dermatology clinics is consolidating as the dominant end-user channel across South Africa's private healthcare corridors. Alma Lasers leverages its fractional laser portfolio to anchor premium positioning in Gauteng's aesthetic centers. Galderma competes through injectable device ecosystems that extend beyond standalone hardware into consumable-linked revenue models. AbbVie (Allergan Inc.) dominates energy-based platform distribution through its consolidated medical aesthetics division, while Venus Concept specializes in radiofrequency-body contouring combinations that occupy the mid-market tier.
Aesthetic devices encompass electromechanical and optical systems engineered to deliver controlled thermal, acoustic, or light energy to cutaneous and subcutaneous tissue, typically operating at wavelengths between 532 nm and 10,600 nm depending on chromophore targeting. These systems serve commercial purposes across skin resurfacing, adipose tissue reduction, and follicular destruction, with treatment parameters calibrated to epidermal thickness and melanin density. Laser Systems lead device type revenue due to established reimbursement pathways and clinician training density, while Radiofrequency Devices represent the fastest-expanding category as multi-polar configurations reduce procedure downtime. Body Contouring applications command margin concentration because capital equipment bundling with disposable applicators creates recurring revenue streams that distributors favor.
SAHPRA governs medical device registration through risk-classification protocols that delay market entry for novel laser platforms without predicate equivalence. The South African Bureau of Standards (SBS) mandates electrical safety testing aligned with IEC 60601-1 for all energy-emitting aesthetic equipment sold through formal channels. Clinicians and procurement officers must monitor SAHPRA's evolving software-as-medical-device guidance, which will determine whether AI-guided treatment planning modules require separate regulatory clearance.
Market Dynamics
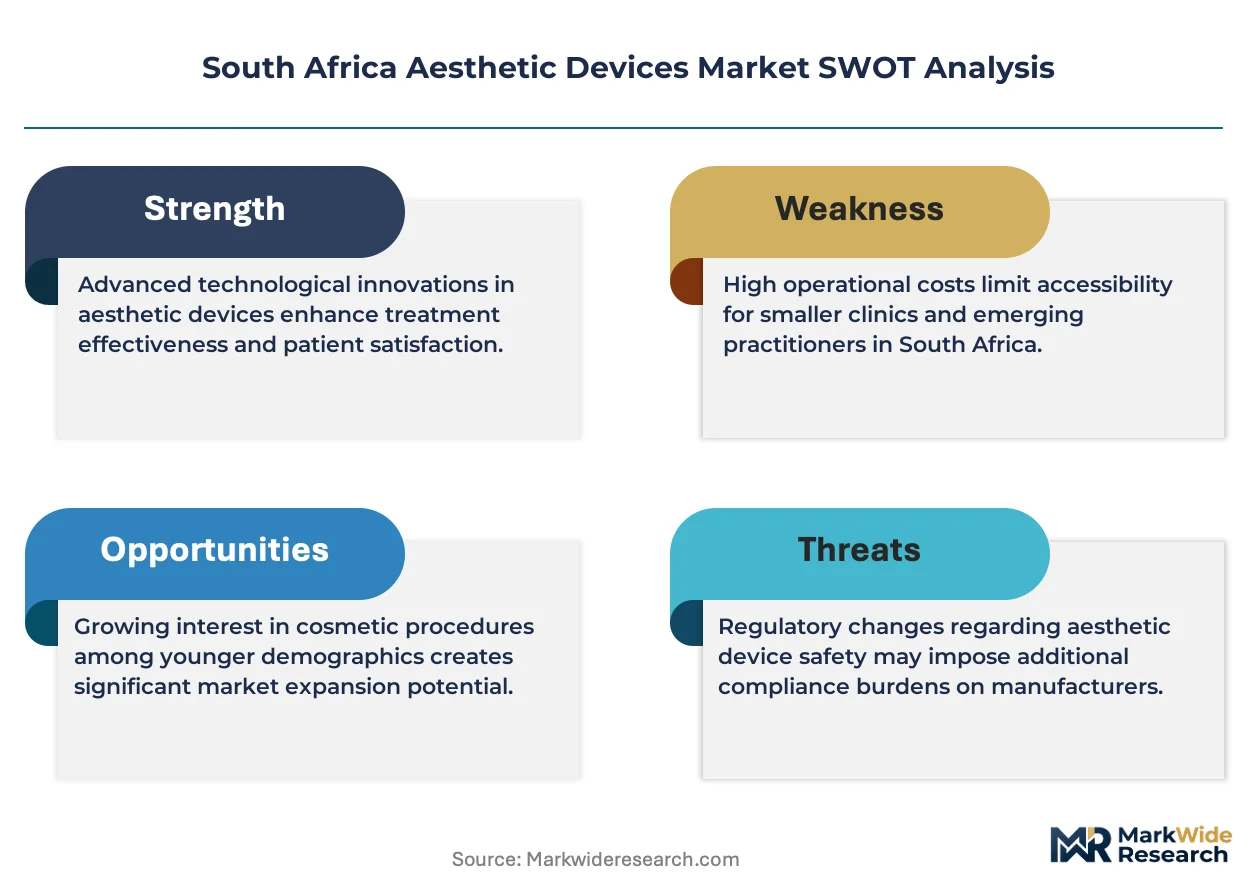
SAHPRA's tightened device registration requirements are compressing market entry timelines and forcing clinics toward pre-cleared CE-marked and FDA-cleared platforms, reshaping procurement patterns across Gauteng and Western Cape aesthetic networks.
Growth Catalysts
- Non-invasive body contouring protocols:Clinics in Johannesburg and Cape Town are consolidating capital expenditure around multi-modality platforms that combine radiofrequency with electromagnetic muscle stimulation, reducing per-procedure downtime and expanding patient throughput.
- SAHPRA risk-classification alignment:The regulator's predicate equivalence pathway for laser systems with established safety profiles accelerates clearance timelines for second-generation fractional devices, favoring incumbent platform upgrades over novel wavelength introductions.
- Private dermatology network expansion:Gauteng's vertically integrated aesthetic chains are standardizing device procurement across branch locations, creating volume concentration that reduces per-unit distributor margins while expanding installed base coverage.
Market Restraints
- Import duty structure on optical components:South Africa's tariff regime on laser diodes and RF generators manufactured outside SADC member states elevates landed equipment costs by 15-25% versus comparable Middle Eastern markets, compressing clinic ROI timelines.
- Disposable applicator supply concentration:Single-use cryolipolysis cups and RF electrodes rely on concentrated European manufacturing, exposing clinics to euro-denominated price volatility and extended replenishment cycles during logistics disruptions.
- Melanin-density treatment limitations:Nd:YAG wavelength platforms remain the sole safe option for Fitzpatrick skin types V-VI, restricting addressable procedure volumes for hair removal and vascular applications in South Africa's diverse patient population.
Strategic Opportunities
- KwaZulu-Natal private hospital corridor:Durban's underpenetrated aesthetic device density relative to Johannesburg presents first-mover positioning for radiofrequency-body contouring platforms targeting the province's medical tourism inflows.
- AI-guided treatment planning modules:Software-as-medical-device regulatory clarity from SAHPRA will determine whether automated parameter selection requires separate clearance, creating competitive differentiation for vendors with pre-validated algorithmic protocols.
- Consumable-linked financing structures:Equipment leasing bundled with minimum disposable purchase commitments aligns distributor cash flow with clinic utilization rates, reducing upfront capital barriers for mid-tier aesthetic centers.
Industry Challenges
- Clinical operator certification gaps:SAHPRA-mandated laser safety officer credentials remain scarce outside metropolitan centers, limiting device utilization rates in secondary cities and increasing liability exposure for multi-site operators.
- Legacy platform interoperability:Clinics with installed base fractional CO2 systems face integration friction when adding complementary radiofrequency modules, requiring duplicate patient management workflows and training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Aesthetic Devices Market |
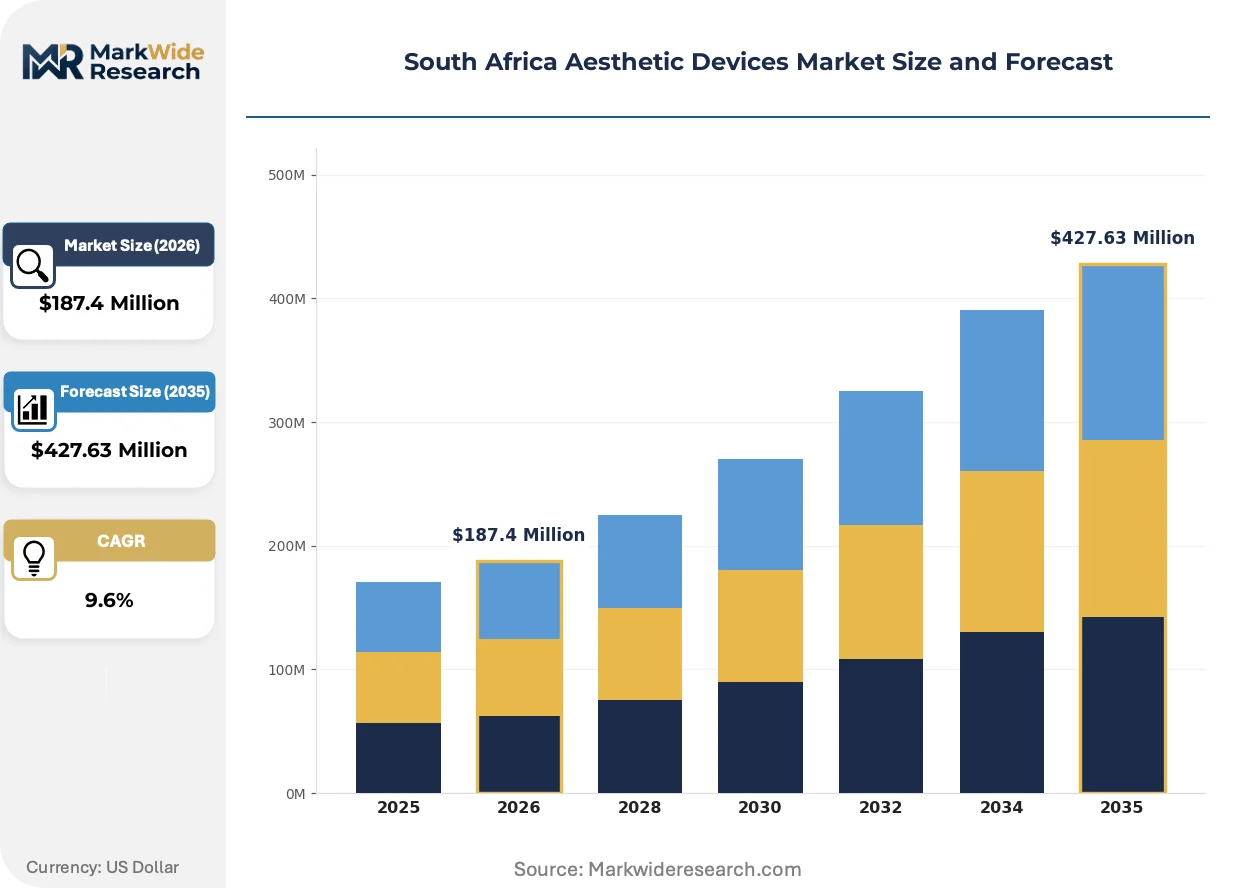
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Systems, Radiofrequency Devices, Ultrasound Devices, Light Therapy Devices Application Area: Skin Rejuvenation, Body Contouring, Hair Removal, Tattoo Removal End User: Dermatology Clinics, Beauty Salons, Hospitals, Aesthetic Centers Distribution Channel: Online Sales, Direct Sales, Distributors, Medical Representatives |
| Companies Covered | Alma Lasers, Galderma, AbbVie (Allergan Inc.), Venus Concept, Sciton Inc., Boston Scientific (Lumenis Inc.), Johnson & Johnson, Hitech Lasers, SternLaser, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Aesthetic Devices Market Evolving Landscape
Technology convergence between optical and electromagnetic modalities is compressing the capital equipment footprint while expanding treatable indications, forcing repositioning across South Africa's aesthetic device distribution tiers.
Multi-polar radiofrequency combined with pulsed electromagnetic fields is unifying adipose tissue disruption with muscle contraction protocols into single-platform delivery. Aesthetic chains in Sandton and Cape Town's Atlantic Seaboard corridor are adopting these systems at replacement-cycle pace. This convergence is compressing the addressable market for standalone cryolipolysis devices while elevating service bundling complexity for independent clinics.
SAHPRA's evolving software-as-medical-device guidance is forcing vendors to segregate AI-driven treatment planning modules from core hardware registrations. The industrial consequence is extended development timelines for algorithmic enhancements and parallel documentation requirements. Fractional laser platforms with embedded skin-type detection algorithms face the most pronounced compliance burden, prompting some distributors to delay feature rollouts pending regulatory clarity.
Patient acquisition economics are driving clinic consolidation toward subscription-based maintenance contracts that unbundle equipment servicing from capital purchase agreements. Independent aesthetic centers in Pretoria and Bloemfontein are migrating from ad-hoc technical support toward annual service retainers with guaranteed uptime clauses. This shift is most visible among mid-tier body contouring installations where downtime directly impacts monthly revenue targets.
South Africa Aesthetic Devices Market Segmentation
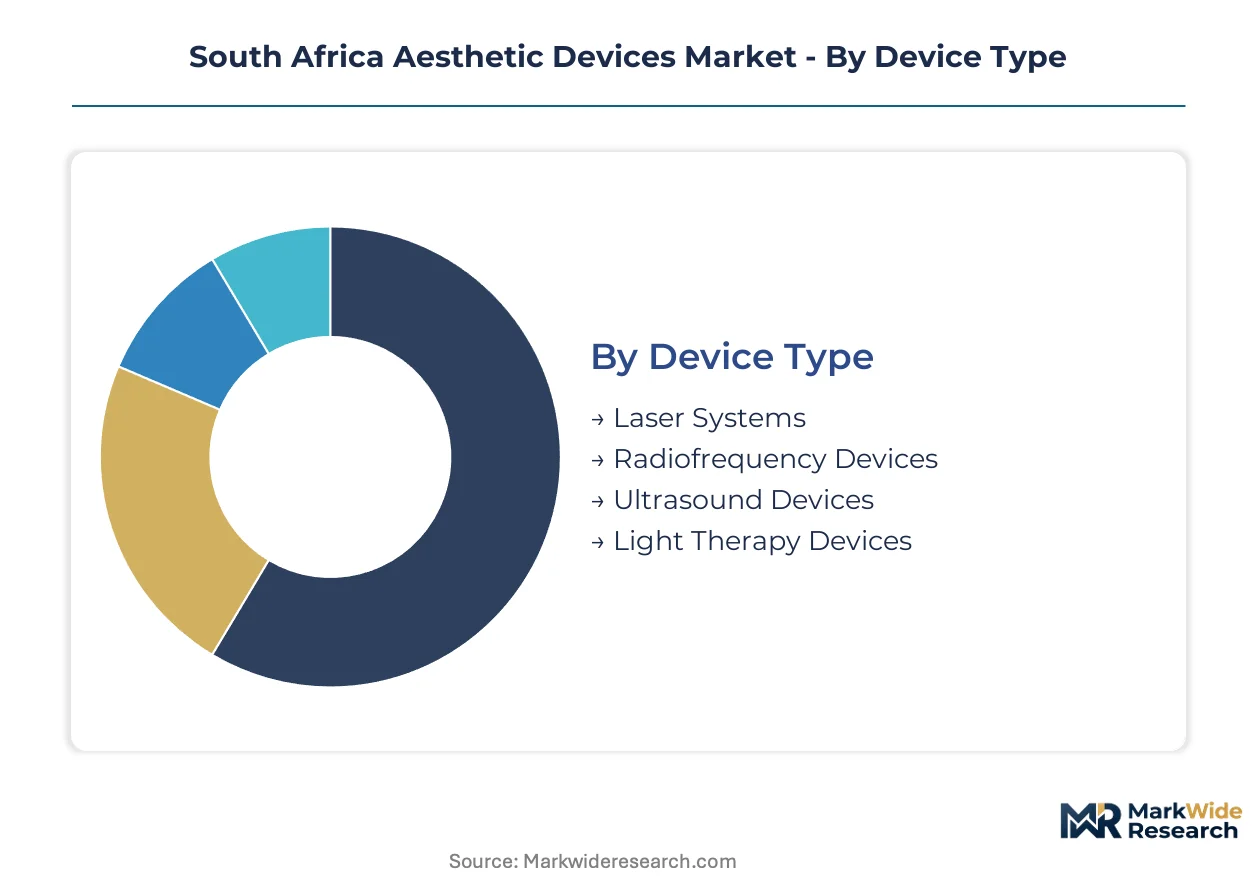
Device segmentation in South Africa's aesthetic market determines procurement patterns across Gauteng's private dermatology networks and Western Cape aesthetic chains. SAHPRA's risk-classification protocols create divergent clearance timelines that favor established device categories with predicate equivalence pathways.
Device Type:
Standalone optical platforms dominate capital expenditure in Johannesburg and Cape Town, while embedded multi-modality systems are displacing single-wavelength installations in newer clinic openings.
- Laser Systems:Solid-state and diode configurations operating between 532 nm and 10,600 nm deliver chromophore-selective thermal damage for resurfacing and vascular applications. Gauteng's vertically integrated dermatology chains standardize on fractional CO2 and Nd:YAG platforms to cover Fitzpatrick types I-VI across their branch networks. SAHPRA's predicate equivalence pathway accelerates clearance for second-generation devices with established safety profiles.
- Radiofrequency Devices:Multi-polar and monopolar configurations generate dermal heating through tissue impedance, with newer platforms integrating electromagnetic muscle stimulation. Cape Town's Atlantic Seaboard aesthetic centers prioritize these systems for body contouring protocols that reduce per-procedure downtime. The category climbs fastest as clinics replace standalone cryolipolysis units with combination platforms.
- Ultrasound Devices:High-intensity focused ultrasound systems target subcutaneous adipose tissue at depths between 1.3 cm and 2.0 cm.
- Light Therapy Devices:LED and IPL platforms serve lower-acuity applications in beauty salon channels outside metropolitan centers.
Volume placements concentrate in Laser Systems; the faster expansion belongs to Radiofrequency Devices.
Application Area:
Procedure economics and consumable attachment rates determine which applications justify capital equipment investment across South Africa's tiered clinic landscape.
- Skin Rejuvenation:Fractional ablative and non-ablative protocols address photodamage, acne scarring, and dyschromia through controlled thermal injury and remodeling. Johannesburg's Sandton aesthetic corridor generates concentrated demand for combination radiofrequency-laser platforms that layer treatment modalities in single sessions. Disposable tip requirements create recurring revenue streams that distributors prioritize.
- Body Contouring:Non-invasive adipose tissue reduction combines cryolipolysis, radiofrequency, and electromagnetic approaches with measurable circumference outcomes. Cape Town medical tourism inflows sustain premium pricing for multi-modality platforms that bundle muscle stimulation with fat disruption. Capital equipment bundling with single-use applicators elevates margin concentration for vendors with captive consumable supply.
- Hair Removal:Alexandrite and Nd:YAG wavelength platforms serve the addressable market, though melanin-density limitations restrict safe treatment for Fitzpatrick types V-VI.
- Tattoo Removal:Q-switched and picosecond laser systems target pigment fragmentation across amateur and professional ink compositions.
Skin Rejuvenation commands the largest installed base; Body Contouring exhibits the steepest expansion trajectory as clinics consolidate around multi-modality platforms.
End User:
Credential requirements and liability exposure stratify device deployment across South Africa's formal healthcare and adjacent wellness sectors.
- Dermatology Clinics:Physician-supervised facilities in Gauteng and Western Cape provinces concentrate demand for Class III and Class IV laser platforms requiring SAHPRA-mandated laser safety officer credentials. These installations favor CE-marked and FDA-cleared systems with established training infrastructure and predicate equivalence pathways.
- Aesthetic Centers:Standalone facilities in Durban's emerging private hospital corridor adopt mid-tier radiofrequency and light therapy devices with lower regulatory burden and faster operator certification.
- Hospitals:Academic and private hospital dermatology departments maintain limited aesthetic device portfolios focused on reconstructive applications.
- Beauty Salons:Unregulated channels outside metropolitan centers deploy lower-intensity LED and IPL systems with minimal SAHPRA oversight.
Dermatology Clinics anchor premium device procurement; Aesthetic Centers are gaining share fastest in KwaZulu-Natal's underpenetrated corridors.
Distribution Channel:
Equipment financing structures and service bundling arrangements determine channel preference across South Africa's fragmented clinic base.
- Distributors:Authorized medical device distributors with SAHPRA registration certificates dominate capital equipment placement, offering leasing structures bundled with minimum disposable purchase commitments that align cash flow with clinic utilization rates.
- Direct Sales:Manufacturer field teams serve large aesthetic chains in Johannesburg and Cape Town with standardized procurement across multiple branch locations.
- Online Sales:Restricted to lower-risk device categories and consumable replenishment given SAHPRA's emphasis on pre-sale technical training and installation validation.
- Medical Representatives:Detail-oriented promotion of consumable applicators and maintenance contracts to installed base accounts.
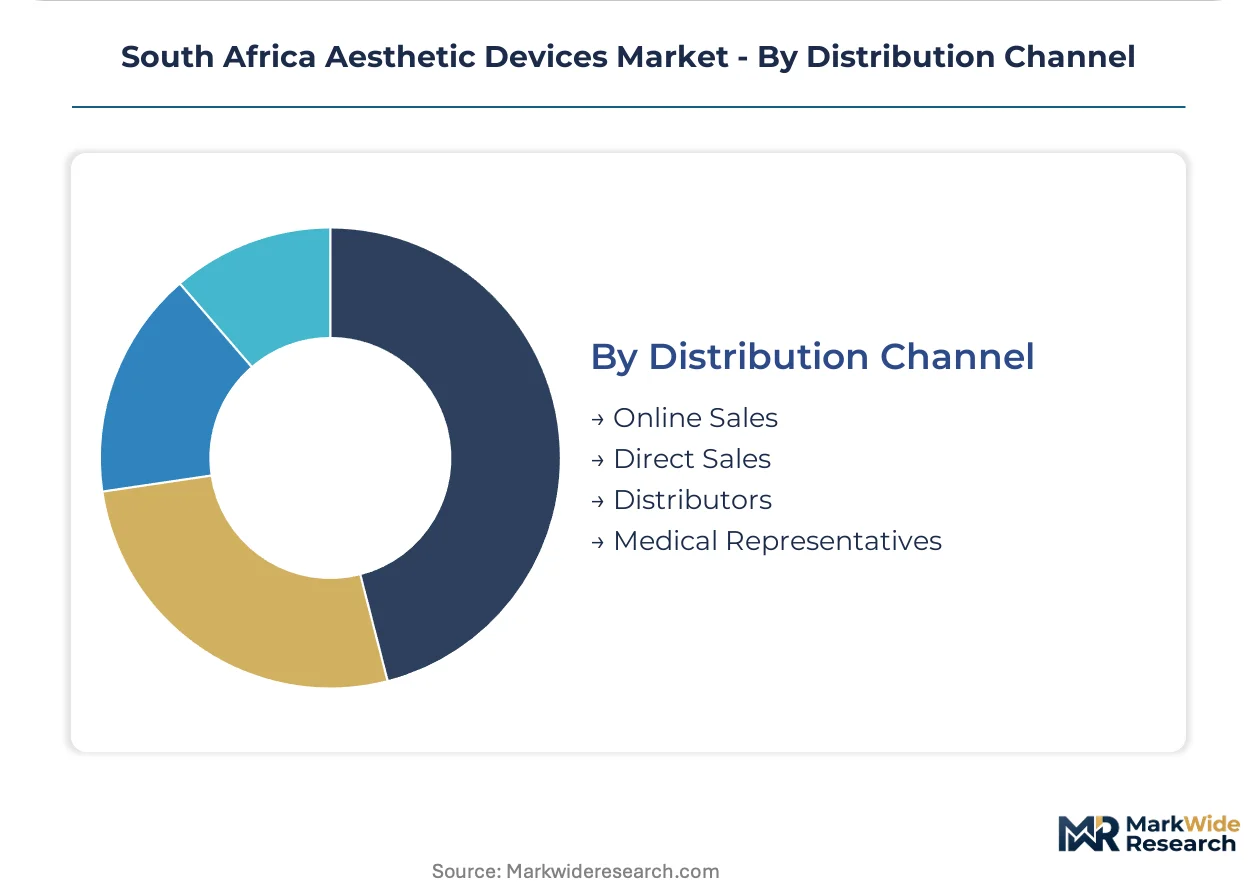
Distributors capture the majority of capital placements; Direct Sales channels are expanding fastest among consolidating multi-site operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Special Economic Zone in Coega anchors medical device manufacturing incentives, concentrating assembly operations near Port Elizabeth and reshaping distribution logistics for aesthetic equipment serving Eastern Cape private hospital networks.
Gauteng
Johannesburg's Sandton aesthetic corridor generates concentrated demand for fractional laser platforms and combination radiofrequency systems. SAHPRA's risk-classification protocols accelerate clearance timelines for predicate-equivalent devices, favoring incumbent platform upgrades. Pretoria's expanding private dermatology networks are standardizing procurement across branch locations, creating volume concentration that reduces per-unit distributor margins.
Western Cape
Cape Town's Atlantic Seaboard aesthetic centers prioritize multi-modality body contouring platforms that bundle muscle stimulation with fat disruption protocols. The Western Cape Department of Health's medical device procurement guidelines emphasize CE-marked and FDA-cleared systems for public-private partnership facilities. Stellenbosch's emerging medical tourism corridor is attracting first-mover positioning for radiofrequency-body contouring installations targeting international patient inflows.
KwaZulu-Natal
Durban's underpenetrated aesthetic device density relative to Johannesburg presents expansion opportunities for mid-tier radiofrequency platforms. The KwaZulu-Natal Department of Economic Development's healthcare investment incentives support private hospital corridor development in Umhlanga and Ballito. Aesthetic centers in these sub-regions are adopting leasing structures bundled with minimum disposable purchase commitments to reduce upfront capital barriers.
Eastern Cape
Port Elizabeth's Coega IDZ medical device assembly operations are reducing landed equipment costs for laser diodes and RF generators imported from SADC member states. The Eastern Cape Development Corporation's manufacturing incentives attract component suppliers serving Gauteng and Western Cape distribution networks. Gqeberha's private hospital expansion is creating secondary demand for lower-intensity LED and IPL systems in emerging aesthetic centers.
South Africa Aesthetic Devices Market Competitive Landscape
Top-tier vendors anchor premium positioning through established CE-marked and FDA-cleared platforms, while mid-market specialists occupy the radiofrequency-body contouring tier with combination modality systems. The vendor structure stratifies across three archetypes: multinational energy-based platform distributors with consolidated medical aesthetics divisions, regional laser specialists leveraging fractional portfolios, and injectable device ecosystem providers extending into consumable-linked revenue models. Competitive moves concentrate on multi-site operator direct sales expansion and consumable-linked financing structures that align distributor cash flow with clinic utilization rates.
Among the named participants, Alma Lasers and Venus Concept exemplify distinct positioning archetypes within South Africa's tiered market structure. Alma Lasers represents the regional laser specialist category, while Venus Concept occupies the mid-market radiofrequency-body contouring tier. AbbVie, operating through its Allergan Inc. medical aesthetics division, anchors the multinational platform distributor archetype with consolidated energy-based device distribution capabilities.
| Leading Market Players |
|---|
| Alma Lasers |
| Galderma |
| AbbVie (Allergan Inc.) |
| Venus Concept |
| Sciton Inc. |
| Boston Scientific (Lumenis Inc.) |
| Johnson & Johnson |
| Hitech Lasers |
| SternLaser |
| Others |
Value Network & Pricing Analysis
Captive supply of laser diodes and RF generators from SADC member states anchors both landed cost positions and distributor pricing power across South Africa's aesthetic device channels. Equipment vendors with backward integration into European consumable manufacturing command premium positioning against spot-market-dependent competitors.
Pricing Analysis
Short lead-time premiums attach to CE-marked and FDA-cleared platforms with established SAHPRA predicate equivalence, while spot inventory of legacy fractional CO2 systems trades at discount. Three-tier pricing structure across premium, standard, and economy levels separates bundled service contracts from bare equipment sales and refurbished installations. Cost compression in mid-tier radiofrequency devices is intensifying because import duty exposure on optical components elevates landed costs 15-25% above Middle Eastern benchmarks. Independent aesthetic centers in secondary cities exhibit highest price sensitivity; vertically integrated dermatology chains in Gauteng prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Workforce availability in German and Israeli precision optics manufacturing feeds the concentrated supply of fractional laser resonators and Q-switched pump assemblies serving South African distributors. Component sourcing draws from Chinese diode packaging facilities, South Korean RF generator foundries, and Italian medical-grade aluminum fabrication. Single-source vulnerability concentrates in European cryolipolysis cup manufacturing, exposing clinics to euro-denominated replenishment cycles. Distribution runs through SAHPRA-authorized medical device distributors with bundled leasing and disposable commitment structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's aesthetic device sector sits in a technology-transition phase, with multi-modality radiofrequency-electromagnetic platforms displacing standalone cryolipolysis and legacy laser installations.
For Market Incumbents: To counter margin compression from import duty structures on non-SADC optical components, prioritize backward integration into consumable applicator manufacturing and captive supply chain development. Anchor defensive positioning through exclusive service retainer contracts with guaranteed uptime clauses across Gauteng's consolidating multi-site operators. CE marking and FDA clearance maintenance accelerates SAHPRA predicate equivalence pathways for next-generation platform launches. For New Entrants and Emerging Players: Enter via KwaZulu-Natal's underpenetrated private hospital corridor, where Durban and Umhlanga aesthetic device density lags Johannesburg by substantial margin. Target mid-tier radiofrequency-body contouring platforms with leasing-structured go-to-market models that reduce upfront capital barriers for emerging aesthetic centers. Ballito's medical tourism inflow expansion presents first-mover positioning for combination modality systems. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational energy-based platform distributors seeking African market anchoring. Long-term viability hinges on consumable-linked revenue durability and SAHPRA software-as-medical-device regulatory clarity. Watch for AI-guided treatment planning module clearance decisions as inflection indicator for algorithmic differentiation value.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Software-as-Medical-Device Submission | Determines whether AI-guided parameter selection requires separate regulatory pathway. |
| Consumable-Linked Financing Structure | Aligns distributor cash flow with clinic utilization rates across mid-tier installations. |
| SADC Component Sourcing Agreement | Reduces landed equipment costs through preferential tariff treatment on laser diodes. |
| Multi-Site Operator Direct Sales Channel | Captures volume concentration from consolidating dermatology chains in Gauteng corridor. |
| Laser Safety Officer Training Certification | Addresses SAHPRA-mandated credential scarcity limiting device utilization in secondary cities. |
Research Methodology
Independent corroboration across aesthetic clinic procurement officers, biomedical engineers at private hospital networks, SAHPRA regulatory affairs specialists, and distributor sales directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through SAHPRA device registration databases, IEC 60601-1 electrical safety filings, and private hospital capex disclosure records. Bottom-up installed base enumeration and top-down market sizing triangulate volume estimates across the projection horizon.
Rate-of-change decomposition across device type, application area, end-user credential tier, and distribution channel structure informs the analytical framework. Segmentation dimensions modeled include laser wavelength configuration, radiofrequency polarity architecture, consumable attachment rates, and provincial regulatory enforcement intensity. CAGRs derive from procedure volume elasticity to private healthcare expenditure trends and replacement cycle timing for fractional platform generations.
Revisions become necessary when SAHPRA software-as-medical-device guidance materializes with unexpected algorithmic clearance requirements, or when SADC trade preferences shift on optical component classifications. Forecasts reflect documented assumptions on predicate equivalence pathway availability and disposable supply chain stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Contact Thermometer Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Power Smart Bed Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Organ Care Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
North America Pen Needles Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Pulse Lavage Market