
 Global Capnography Equipment Market | 2026-2036
Global Capnography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capnography Equipment Market Foresight
Mainstream infrared measurement accuracy is rotating the installed base toward higher-specification devices. Medtronic leverages its end-to-end airway management portfolio to bundle capnography with ventilator platforms. Masimo sustains technology leadership through its Signal Extraction pulse oximetry and capnography convergence. Drägerwerk AG anchors European hospital procurement through integrated anesthesia workstations with built-in capnometry modules.
Capnography equipment measures the concentration of carbon dioxide in exhaled breath, typically using infrared absorption spectroscopy at a wavelength of approximately 4.26 micrometers to enable real-time respiratory status monitoring during sedation, anesthesia, and mechanical ventilation. Portable monitors represent the fastest-expanding product category as point-of-care testing migrates beyond traditional operating room settings. Multi-parameter monitors capture the deepest margin pools by embedding capnography within broader patient monitoring ecosystems sold to hospital systems. Emergency care applications are displacing operating room dominance as pre-hospital and transport medicine protocols mandate continuous EtCO2 tracking.
FDA 510(k) clearance pathways and ISO 80601-2-55 standards govern electrical safety and performance validation for capnography devices sold into US and international markets. The EU MDR and CE marking requirements are extending clinical evidence demands for Class IIa respiratory monitors, reshaping market access timelines for manufacturers without robust quality management systems. Stakeholders must monitor how mainstream versus sidestream technology standards evolve under harmonized international frameworks.
Market Dynamics
Mainstream infrared capnography is miniaturizing rapidly, compressing form factors and enabling deployment across pre-hospital, transport, and home care settings that previously relied on clinical judgment alone. This hardware convergence with wireless telemetry is redrawing competitive boundaries between dedicated respiratory device manufacturers and multi-parameter monitoring platforms.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for predicate-based capnography submissions are shortening product launch cycles for manufacturers with established quality management systems.
- ICU ventilation protocol mandates:Critical care units across hospital systems are embedding continuous EtCO2 monitoring into mechanical ventilation standards, creating replacement demand for legacy pulse oximetry-only installations.
- Point-of-care testing migration:Emergency medical services and air ambulance operators are adopting portable capnography for intubation confirmation and perfusion assessment outside traditional operating theaters.
Market Restraints
- Indium antimonide detector supply concentration:Infrared sensor fabrication depends on specialized semiconductor foundries concentrated in East Asia, exposing manufacturers to input bottlenecks.
- EU MDR clinical evidence escalation:Class IIa respiratory monitor re-certification under the Medical Device Regulation is extending market access timelines by demanding expanded clinical performance data.
- Disposable sampling line cost structure:Recurring consumable expenses for sidestream configurations create procurement friction in budget-constrained municipal emergency services.
Strategic Opportunities
- India's hospital infrastructure expansion:Government-funded critical care capacity additions under national health mission programs are opening procurement windows for mid-range monitoring equipment.
- Capnography-pulse oximetry algorithm convergence:Integration of respiratory and perfusion indices into single-display decision support is enabling premium positioning against standalone competitors.
- Home-based respiratory monitoring:Post-acute care discharge protocols for chronic obstructive pulmonary disease are creating demand for patient-operated EtCO2 tracking outside institutional settings.
Industry Challenges
- ISO 80601-2-55 electrical safety validation:Respiratory gas monitor compliance testing requires specialized electromagnetic compatibility facilities that extend engineering timelines.
- Multi-parameter platform integration complexity:Embedding capnography modules into existing patient monitoring architectures demands firmware reconciliation across incompatible communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capnography Equipment Market |
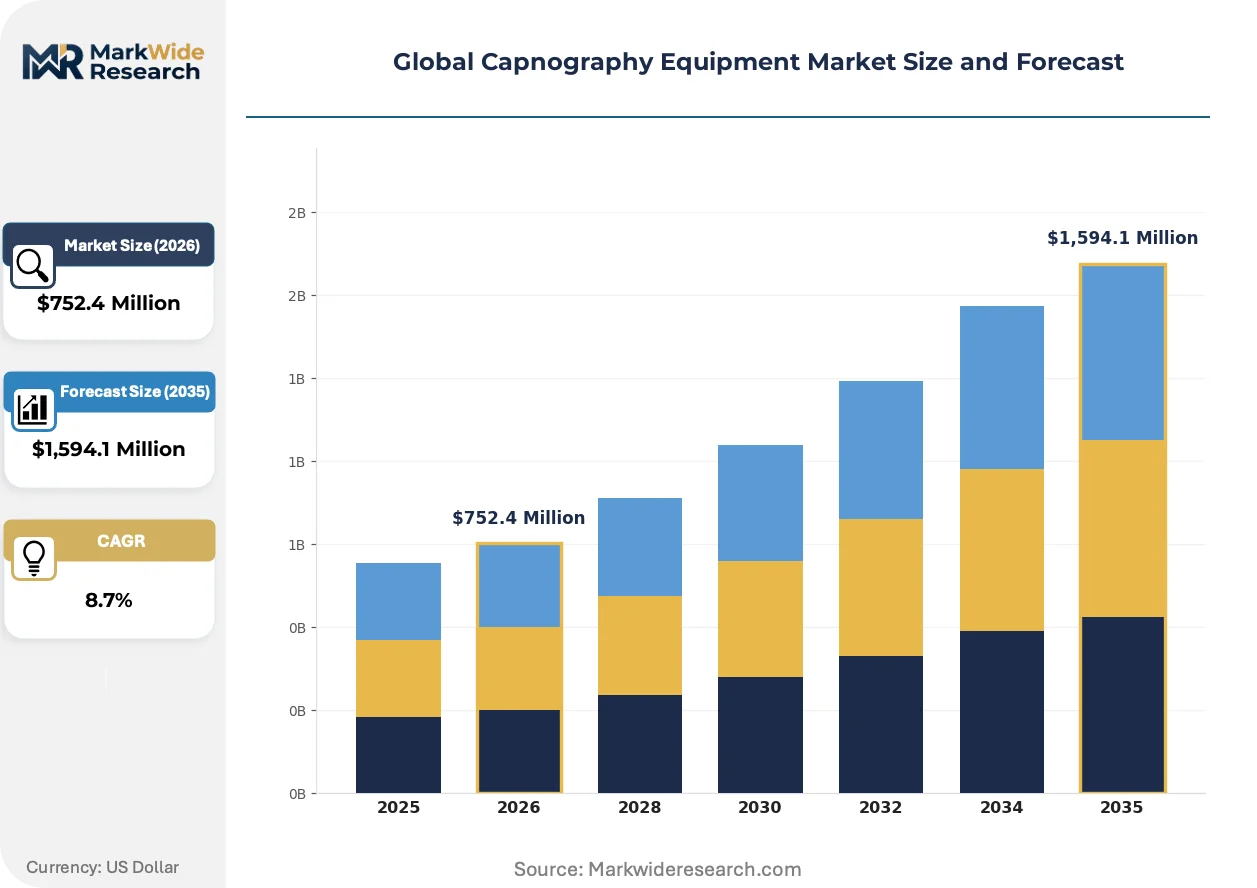
| Market Size in 2026 | $752.4 Million |
| Market Size in 2035 | $1,594.1 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Capnographs, Portable Monitors, Standalone Capnometers, Multi-parameter Monitors Application: Operating Rooms, Intensive Care Units, Emergency Care, Respiratory Therapy, Sleep Studies End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Laboratories Technology: Infrared Mainstream, Sidestream, Microstream, Chemoresistive Sensors |
| Companies Covered | Medtronic, Koninklijke Philips N.V., Masimo, Drägerwerk AG & Co. KGaA, Nihon Kohden Corporation, GE Healthcare, ICU Medical, Mindray, Hamilton Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capnography Equipment Market Shifts & Advancements
Microelectromechanical systems engineering is collapsing capnography into wearable form factors, while regulatory harmonization efforts and procurement centralization are simultaneously compressing vendor margins and consolidating purchasing authority. These intersecting forces are favoring platforms with end-to-end airway management portfolios over specialized device manufacturers.
Microstream technology is miniaturizing sidestream sampling into nasal cannula configurations weighing under 30 grams. Emergency medical technicians are adopting these configurations for continuous monitoring during ground and air transport. This form factor compression is enabling capnography deployment in ambulatory settings that previously excluded physiological monitoring entirely.
The EU MDR is extending clinical evidence requirements for Class IIa respiratory monitors beyond the previous Medical Device Directive thresholds. Manufacturers without robust post-market surveillance infrastructure face extended notified body review cycles. European hospital procurement consortia are responding by favoring suppliers with established quality management certifications over emerging entrants.
Hospital system procurement centralization is consolidating purchasing authority into regional supply chain offices. Independent anesthesiology groups and smaller surgical centers are losing negotiating leverage as integrated delivery networks standardize on single-vendor monitoring platforms. This concentration is most visible in United States metropolitan markets where health system mergers have collapsed independent hospital governance into corporate supply chain hierarchies.
Global Capnography Equipment Market Segmentation
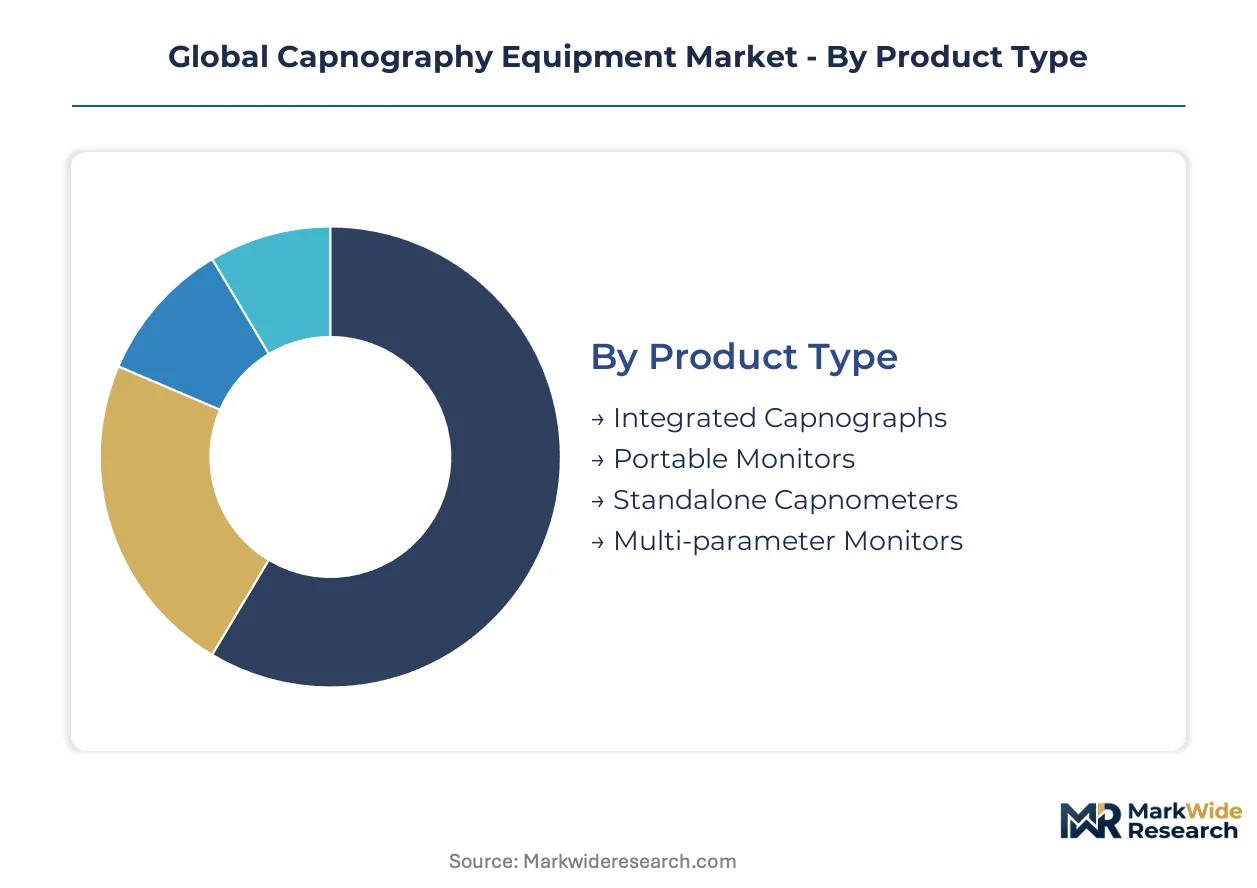
Capnography equipment segmentation reflects divergent regulatory pathways and reimbursement structures across clinical settings. Product qualification thresholds under FDA 510(k) and EU MDR reshape competitive positioning within each category, while end-user procurement centralization compresses vendor margins differently across hospital systems versus independent facilities.
Product Type:
FDA premarket notification requirements and ISO 80601-2-55 technical standards impose distinct validation burdens on fixed versus portable configurations, concentrating market access among manufacturers with established quality management systems.
- Multi-parameter Monitors:These systems embed capnography modules within broader patient monitoring ecosystems, integrating EtCO2 waveforms with pulse oximetry and hemodynamic parameters on unified displays. Hospital systems in the United States standardize on these platforms through corporate supply chain hierarchies, displacing standalone alternatives as integrated delivery networks consolidate purchasing authority.
- Portable Monitors:Miniaturized mainstream infrared devices weighing under 500 grams enable deployment across pre-hospital and transport settings previously excluded from physiological monitoring. Emergency medical services operators in Germany and air ambulance fleets in Australia mandate these configurations for intubation confirmation outside traditional operating theaters.
- Integrated Capnographs:Built-in modules within anesthesia workstations and ventilator platforms streamline perioperative workflows through unified data architecture.
- Standalone Capnometers:Dedicated single-parameter devices serve cost-constrained surgical centers and diagnostic laboratories with focused EtCO2 monitoring requirements.
Multi-parameter monitors handle the majority of throughput; portable monitors are the fastest mover on share.
Application:
Clinical evidence requirements under EU MDR and reimbursement coding structures in the United States concentrate investment toward settings with established continuous monitoring protocols.
- Emergency Care:Pre-hospital protocols in the United States and United Kingdom now mandate EtCO2 tracking for endotracheal intubation verification and cardiac output assessment during resuscitation. Municipal emergency services in Texas and Florida face procurement friction from disposable sampling line costs, accelerating adoption of mainstream infrared alternatives that eliminate consumable dependencies.
- Intensive Care Units:Mechanical ventilation standards across critical care units embed continuous capnography alongside pulse oximetry, creating replacement demand for legacy monitoring installations. Hospitals in California and New York embed these requirements into ICU accreditation protocols.
- Operating Rooms:Anesthesia safety guidelines in Switzerland and the Netherlands require continuous respiratory gas monitoring during procedural sedation.
- Respiratory Therapy:Pulmonary function laboratories deploy capnography for bronchodilator response assessment and ventilation-perfusion analysis.
- Sleep Studies:Polysomnography suites integrate EtCO2 monitoring for sleep-disordered breathing diagnosis.
Intensive care units anchor installed base value; emergency care applications are expanding most quickly into previously unserved settings.
End User:
Procurement scale and technical specification requirements fragment the customer base across institutional hierarchies with divergent negotiating leverage.
- Hospitals:Integrated delivery networks in United States metropolitan markets consolidate purchasing authority into regional supply chain offices, favoring vendors with end-to-end airway management portfolios. Academic medical centers in Massachusetts and Pennsylvania demand multi-parameter platforms with embedded decision support algorithms.
- Ambulatory Surgical Centers:Freestanding facilities in Florida and Arizona prioritize portable mainstream devices for moderate sedation protocols, constrained by capital budgets and space limitations.
- Clinics:Outpatient pulmonary practices in Ontario and British Columbia adopt sidestream microstream technology for office-based spirometry and ventilation assessment.
- Diagnostic Laboratories:Sleep study centers and cardiopulmonary testing facilities in Victoria and New South Wales specify standalone capnometers for focused respiratory gas analysis.
Hospitals command the dominant share of revenue; ambulatory surgical centers are climbing the fastest as procedural volume migrates from inpatient settings.
Technology:
Sensor fabrication dependencies and measurement accuracy specifications differentiate competitive positioning across infrared and alternative detection modalities.
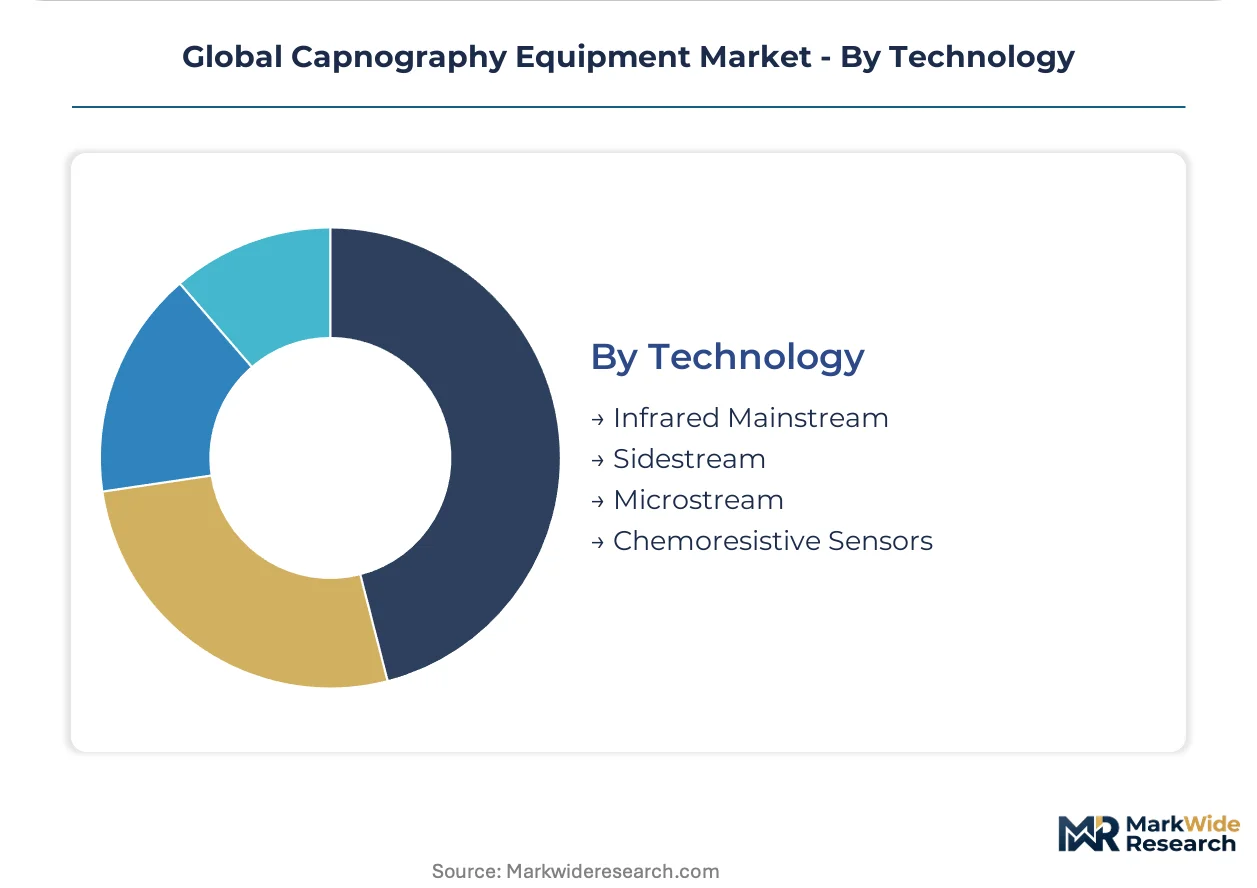
- Infrared Mainstream:Direct airway measurement at 4.26 micrometers wavelength eliminates sampling line consumables and delivers real-time waveform fidelity without transport delay. Critical care units in Bavaria and North Rhine-Westphalia specify these configurations for mechanical ventilation management.
- Microstream:Miniaturized sidestream sampling through nasal cannula configurations under 30 grams enables ambulatory monitoring during ground and air transport. Emergency medical technicians in Queensland and Western Australia adopt these for continuous perfusion assessment.
- Sidestream:Diverting gas sampling through disposable lines suits operating room environments with controlled airway access and established consumable supply chains.
- Chemoresistive Sensors:Solid-state detection alternatives target cost-sensitive applications where infrared component costs prove prohibitive.
Infrared mainstream technology dominates throughput volume; microstream configurations are gaining share fastest through form factor compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States imports specialized infrared detector components from East Asian foundries while exporting integrated monitoring platforms to European and Asia-Pacific hospital systems. Germany and Switzerland maintain trade surpluses in anesthesia workstation assemblies. China's domestic production of microelectromechanical sensors is displacing previous import dependence for portable device manufacturing.
United States
FDA 510(k) clearance pathways and anesthesia safety protocol mandates drive replacement demand across perioperative workflows. The IRA's hospital infrastructure provisions accelerate ICU ventilation equipment procurement in California and New York. Academic medical centers in Massachusetts demand multi-parameter platforms with embedded decision support algorithms.
Germany
Critical care units in Bavaria and North Rhine-Westphalia specify mainstream infrared configurations for mechanical ventilation management. EU MDR clinical evidence requirements extend notified body review cycles for respiratory monitor re-certification. Integrated anesthesia workstation production concentrates in Baden-Württemberg and Hamburg.
China
NMPA regulatory harmonization with ISO 80601-2-55 standards accelerates domestic device qualification timelines. Government-funded critical care capacity additions under national health programs open procurement windows in Shanghai and Beijing. Yangtze River Delta manufacturing clusters scale microelectromechanical sensor fabrication for portable monitors.
India
CDSCO medical device registration requirements and BIS electrical safety standards reshape import substitution patterns for respiratory monitors. National health mission programs fund critical care infrastructure expansion in Maharashtra and Karnataka. Hospital procurement in Delhi-NCR and Tamil Nadu favors mid-range monitoring equipment with localized technical support.
Australia
TGA conformity assessment procedures for Class IIa respiratory devices align with EU MDR evidence requirements. Air ambulance fleets in Queensland and Western Australia mandate portable capnography for intubation confirmation during transport. Procurement standardization across New South Wales and Victoria health networks consolidates purchasing authority.
Global Capnography Equipment Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates possessing end-to-end airway management portfolios. The vendor base stratifies across three tiers: integrated platform specialists, dedicated respiratory device manufacturers, and emerging regional suppliers. Strategic archetypes include anesthesia workstation integrators, multi-parameter monitoring platform providers, and portable device miniaturization specialists. Competitive moves center on technology convergence between pulse oximetry and capnography modules, plus supply chain regionalization to mitigate semiconductor foundry concentration risks.
Among diversified medical technology conglomerates, Medtronic and Koninklijke Philips N.V. exemplify platform integration archetypes. Masimo occupies a position within the monitoring convergence specialist tier. Drägerwerk AG & Co. KGaA anchors European anesthesia workstation supply. Nihon Kohden Corporation represents Japanese precision instrumentation heritage. These entities collectively illustrate how regulatory compliance scale and quality management certification depth determine market access velocity across FDA, EU MDR, and NMPA jurisdictions.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips N.V. |
| Masimo |
| Drägerwerk AG & Co. KGaA |
| Nihon Kohden Corporation |
| GE Healthcare |
| ICU Medical |
| Mindray |
| Hamilton Medical |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with East Asian semiconductor foundries lock in indium antimonide detector supply while capping price escalation for infrared sensor modules. These contractual structures tether pricing visibility to foundry allocation priority, compressing margin flexibility for manufacturers without established quality management certifications under FDA 510(k) pathways.
Pricing Analysis
Hospital system procurement offices anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade positioning under ISO 80601-2-55 validation, while economy configurations serve municipal emergency services with stripped-down functionality. Cost compression in the mid-tier segment is intensifying because integrated delivery networks leverage volume consolidation across multi-parameter platform deployments. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, whereas academic medical centers prioritize decision-support algorithm integration over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites semiconductor component flows from Taiwan, South Korea, and Japan toward assembly facilities in Germany and the United States. Infrared detector fabrication draws from indium antimonide substrates, germanium optical windows, and MEMS wafer processing capabilities concentrated in Yangtze River Delta clusters. Single-source vulnerability in specialized foundry capacity exposes manufacturers to allocation disruptions during demand surges. Distribution runs through regional hospital supply chain offices that consolidate purchasing authority across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capnography equipment sits in early-cycle expansion as point-of-care testing protocols extend EtCO2 monitoring into pre-hospital and transport settings previously excluded from physiological surveillance.
For Market Incumbents: Compound technology convergence advantages by integrating pulse oximetry and capnography algorithms into unified decision-support displays that emerging entrants cannot replicate without firmware reconciliation across incompatible communication protocols. Deepen backward integration into MEMS sensor fabrication to mitigate indium antimonide detector supply concentration risks from East Asian foundries. Prioritize CE marking pathway investments ahead of EU MDR clinical evidence escalation timelines. For New Entrants and Emerging Players: Anchor in India's hospital infrastructure expansion under national health mission programs, where mid-range monitoring equipment procurement windows favor localized technical support capabilities over premium-brand incumbents. Target emergency medical services operators in Germany and Australia with portable mainstream configurations under 500 grams that eliminate disposable sampling line dependencies. Pursue software companion development partnerships with regional distributors to bypass direct hospital system procurement hierarchies. For Investors and Strategic Acquirers: Capital is best deployed toward portable device miniaturization specialists possessing MEMS engineering capabilities and NMPA regulatory harmonization progress in China. Long-term viability hinges on algorithm convergence differentiation rather than hardware commodity positioning. Monitor FDA 510(k) clearance velocity for predicate-based submissions as the inflection indicator for competitive access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines compress product launch cycles for established quality systems. |
| CE Marking Pathway | EU MDR clinical evidence demands reshape market access timelines for respiratory monitor re-certification. |
| Hospital System Partnership | Integrated delivery network consolidation favors vendors with end-to-end airway management portfolios. |
| Software Companion Development | Algorithm convergence between pulse oximetry and capnography enables premium positioning against standalone competitors. |
| Reimbursement Strategy | ICU ventilation protocol mandates embedding continuous EtCO2 monitoring create replacement demand cycles. |
Research Methodology
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and anesthesia department heads anchors the qualitative findings against secondary validation from FDA 510(k) filings, ISO 80601-2-55 technical documentation, hospital procurement databases, and CMS Medicare reimbursement coding structures. Bottom-up triangulation across product type, application, technology, and end-user segmentation dimensions reconciles with top-down macroeconomic boundary conditions.
Sensitivity analysis across the projection horizon tests demand elasticity for portable versus multi-parameter configurations under alternative ICU ventilation protocol adoption scenarios. The analytical framework models technology substitution dynamics between mainstream infrared and microstream sidestream architectures, geographic procurement centralization patterns, and regulatory harmonization progress across FDA, EU MDR, NMPA, and CDSCO jurisdictions. CAGRs derive from installed base replacement cycles, point-of-care testing migration velocity, and semiconductor component supply constraints.
Material uncertainties — regulatory timeline slippage, foundry allocation disruptions, and reimbursement coding revisions — sit outside the modeled envelope. Forecasts reflect assumptions about protocol adoption rates and procurement centralization trajectories without claiming predictive certainty. Practitioners should keep alternative scenarios live as EU MDR notified body review cycles and East Asian semiconductor supply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Steam Autoclaves Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
Cryochambers Market