
 Centrifuge Market | 2026-2036
Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifuge Market Analysis
REACH compliance is consolidating the cost-of-entry calculus for European centrifuge suppliers, forcing smaller participants to absorb expensive material certifications or exit the market. GEA Group Aktiengesellschaft leverages its captive foundry network to manage alloy traceability costs internally. ANDRITZ anchors its position through R&D intensity in decanter centrifuge automation. KUBOTA Corporation dominates compact disc-stack designs for Asian food and beverage applications.
A centrifuge generates centrifugal force through rapid rotor rotation to separate heterogeneous mixtures by density, with industrial units typically achieving 1,000–15,000 G and ultracentrifuges exceeding 100,000 G for molecular separation. The equipment serves pharmaceutical purification, wastewater sludge dewatering, and blood component fractionation where gravitational settling proves impractical. Ultracentrifuges command premium margins due to precision tolerances and vacuum-system complexity, while refrigerated centrifuges capture expanding share from temperature-sensitive biologics processing. Fixed-angle technology leads clinical throughput volumes, though swinging-bucket configurations retain dominance in density-gradient protocols.
The FDA enforces 21 CFR Part 11 for electronic records in pharmaceutical centrifuge operations, while the EPA administers effluent standards that mandate solids-recovery efficiency in industrial wastewater applications. ISO 9001 and ISO 13485 certifications function as baseline procurement filters for laboratory and medical-device buyers respectively. Stakeholders must monitor evolving PFAS restrictions under REACH and state-level analogues, as fluoropolymer seals and coatings face substitution pressures that could disrupt established supply specifications.
Market Dynamics
Biopharmaceutical manufacturing scale-up is compressing centrifuge procurement cycles, as single-use bioreactor trains demand matched separation capacity with validated clean-in-place protocols. Contract manufacturers now specify rotor materials and surface finishes during early facility design phases.
Growth Catalysts
- 21 CFR Part 11:FDA electronic records enforcement in pharmaceutical operations mandates audit-trail capabilities in new centrifuge installations, creating replacement demand across GMP facilities.
- Cell therapy manufacturing:Autologous and allogeneic cell processing requires closed-system centrifugation with gentle acceleration profiles, expanding specialized equipment procurement.
- Rhine-Ruhr industrial cluster:Concentrated food and chemical processing around Cologne and Düsseldorf sustains regional demand for high-capacity decanter units.
Market Restraints
- Alloy traceability costs:REACH compliance for stainless steel and titanium alloys forces suppliers to absorb third-party certification expenses or pass through price increases.
- Foundry concentration:Precision rotor casting capacity concentrates among a handful of European and East Asian suppliers, creating single-source vulnerability for critical components.
- Ultracentrifuge vacuum complexity:Molecular separation applications require specialized turbomolecular pump systems with limited qualified service networks outside major metropolitan centers.
Strategic Opportunities
- Indian biopharma expansion:CDSCO's streamlined medical device regulations and PLI scheme incentives attract contract manufacturing investment, creating centrifuge demand in Hyderabad and Bengaluru clusters.
- PFAS substitution:REACH restrictions on fluoropolymer seals and coatings create first-mover advantage for suppliers with validated elastomer alternatives.
- Predictive maintenance convergence:Integration of vibration sensors with cloud analytics enables remote rotor balancing and bearing-life forecasting, shifting service revenue from reactive to subscription models.
Industry Challenges
- Metrology technician scarcity:Ultracentrifuge field service requires specialized vacuum and rotor dynamics expertise that outpaces vocational training pipeline output.
- ISO 13485 certification timelines:Medical device centrifuge manufacturers face 12-18 month approval cycles that delay product launches and compress revenue recognition windows.
- Legacy control system integration:Brownfield pharmaceutical facilities require costly PLC retrofits to connect new centrifuges to existing SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifuge Market |
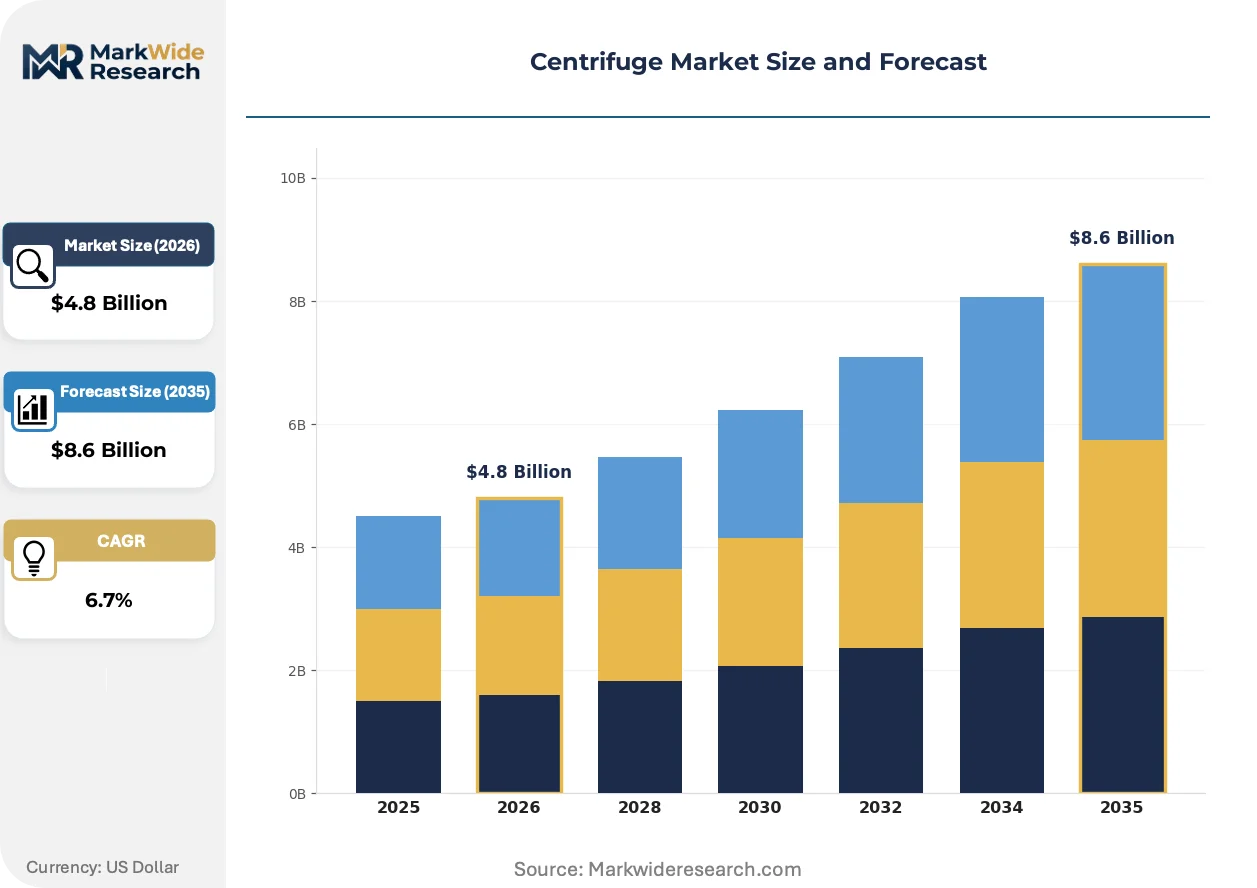
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcentrifuges, Ultracentrifuges, Refrigerated Centrifuges, Multipurpose Centrifuges Technology: Fixed-Angle, Swinging-Bucket, Benchtop, Floor-Standing End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Biotechnology Firms Application: Cell Separation, Protein Purification, DNA Extraction, Blood Component Separation |
| Companies Covered | ALFA LAVAL, GEA Group Aktiengesellschaft, ANDRITZ, FLSmidth A/S, KUBOTA Corporation, Flottweg SE, SPX FLOW, Inc., Mitsubishi Kakoki Kaisha, Ltd., Ferrum AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifuge Market Emerging Trajectories
Automation and materials science are restructuring competitive differentiation, as rotor dynamics simulation and additive manufacturing enable performance gains without proportional cost increases. Equipment suppliers now compete on total cost of ownership rather than capital expenditure alone.
Continuous-flow centrifugation is overtaking batch processing in commercial-scale cell harvesting, eliminating hold tanks and reducing contamination risk. Gene therapy manufacturers in Massachusetts and North Carolina are specifying these systems for 2,000-liter bioreactor trains. The technology is compressing facility footprints and enabling modular manufacturing architectures that can relocate between markets.
REACH's evolving PFAS restrictions are forcing reformulation of fluoropolymer seals and rotor coatings used in corrosive chemical processing. ECHA's 2023 restriction proposals target perfluoroalkyl substances in industrial equipment, compelling suppliers to validate perfluoroelastomer alternatives. German chemical processors are demanding material certifications 18 months ahead of enforcement deadlines to avoid supply disruption.
Service unbundling is fragmenting traditional OEM revenue models, as third-party maintenance providers capture rotor balancing and bearing replacement work. Pharmaceutical buyers in Switzerland and the Netherlands are separating equipment procurement from multi-year service contracts, pressuring manufacturer margins. This shift concentrates in markets with established independent metrology laboratories and qualified technician pools.
Centrifuge Market Segmentation
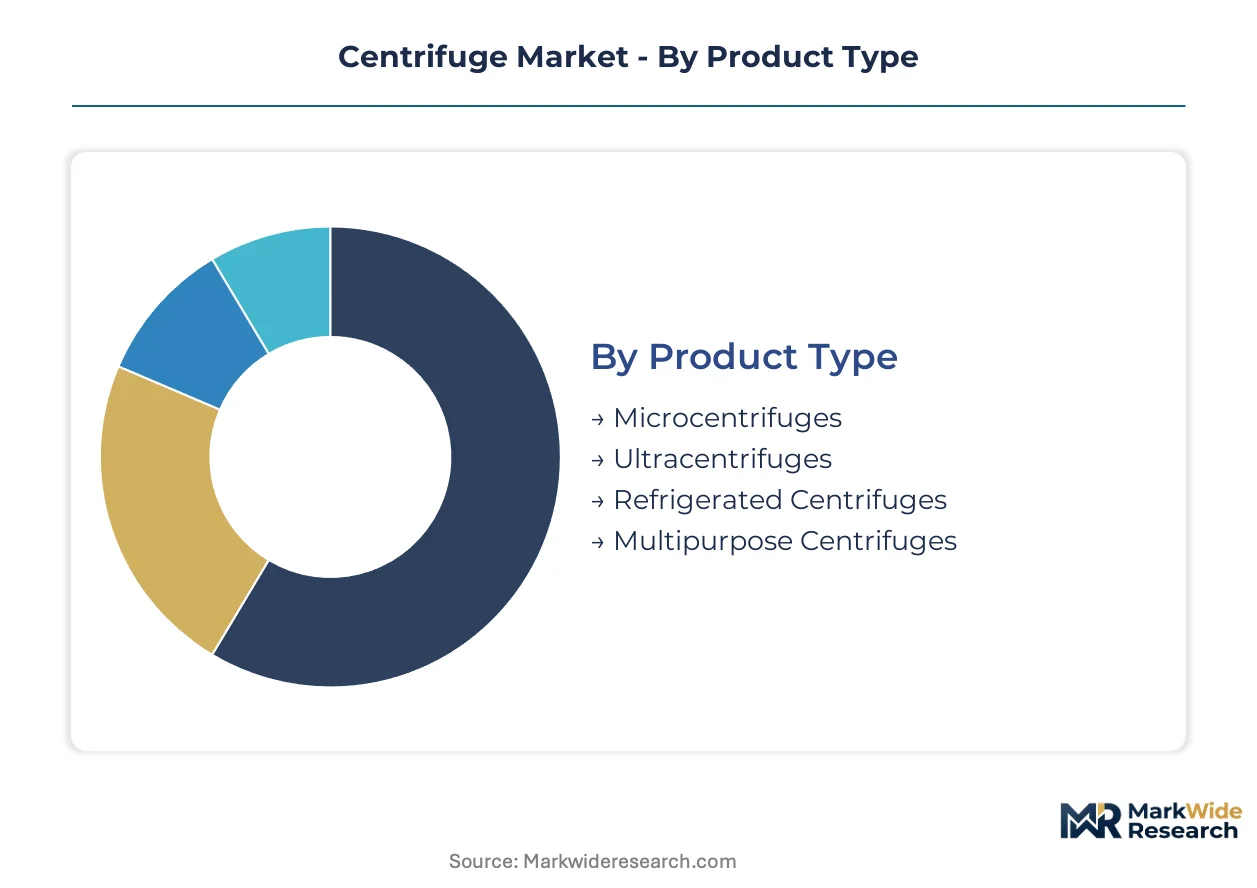
Centrifuge procurement decisions cascade through four interlocking dimensions that determine equipment specification, validation burden, and lifecycle economics. Buyers match rotor dynamics to sample volume, thermal sensitivity, and regulatory jurisdiction.
Product Type:
Standalone benchtop units dominate routine clinical workflows, while embedded ultracentrifuge systems integrate into multi-step purification trains for biopharmaceutical manufacturing.
- Microcentrifuges:Compact units process 0.2–2.0 mL tubes at 15,000–21,000 G for molecular biology workflows. Clinical diagnostic labs in Hyderabad and Bengaluru clusters specify these for PCR preparation volumes.
- Ultracentrifuges:Vacuum-enclosed systems exceed 100,000 G for virus particle isolation and lipoprotein fractionation. Gene therapy manufacturers in Massachusetts require validated rotor materials and surface finishes during early facility design phases.
- Refrigerated Centrifuges:Temperature-controlled units protect heat-sensitive biologics during separation.
- Multipurpose Centrifuges:Modular platforms accommodate multiple rotor configurations for shared-service research facilities.
Microcentrifuges lead volumes today; ultracentrifuges are gaining share fastest.
Technology:
Capital deployment patterns split between high-throughput fixed installations and flexible benchtop configurations that relocate with contract manufacturing migrations.
- Fixed-Angle:Rotors hold tubes at fixed inclination for rapid pelleting applications. Pharmaceutical purification facilities specify these for validated clean-in-place protocols in single-use bioreactor trains.
- Swinging-Bucket:Rotor buckets swing to horizontal during acceleration for flat-gradient separations. Density-gradient protocols in research institutions retain preference for this configuration.
- Benchtop:Self-contained units require no dedicated infrastructure.
- Floor-Standing:High-capacity systems anchor permanent installations.
Fixed-angle rotors dominate clinical throughput; swinging-bucket configurations climb fastest in cell therapy applications.
End User:
Procurement authority concentrates in quality-assurance functions for GMP facilities, while research buyers prioritize flexibility and multi-user accessibility.
- Clinical Laboratories:High-throughput diagnostic operations demand rapid turnaround and minimal maintenance intervals. Blood component fractionation drives replacement cycles as FDA 21 CFR Part 11 enforcement mandates audit-trail capabilities.
- Research Institutions:Academic and government labs balance capital constraints against protocol diversity. Density-gradient research and ultracentrifuge service networks outside major metropolitan centers constrain equipment selection.
- Pharmaceutical Companies:GMP-validated operations specify materials and surface finishes during facility design.
- Biotechnology Firms:Emerging cell therapy manufacturers require closed-system centrifugation with gentle acceleration profiles.
Clinical laboratories anchor installed base; biotechnology firms show steepest expansion trajectory.
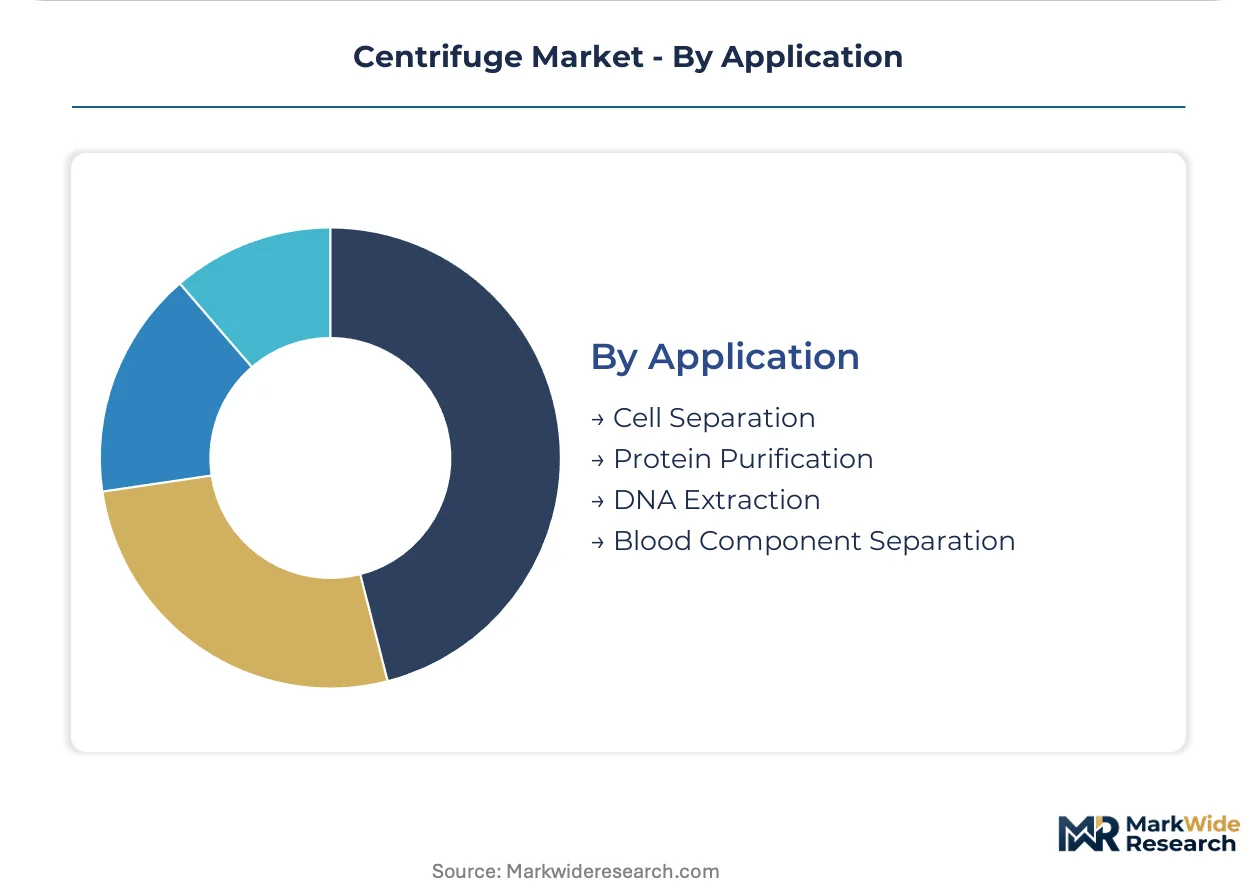
Application:
Process economics diverge sharply between diagnostic-scale separation and commercial biomanufacturing where contamination risk drives continuous-flow adoption.
- Cell Separation:Harvesting protocols for autologous and allogeneic therapies demand precise acceleration control. Continuous-flow centrifugation is displacing batch processing in 2,000-liter bioreactor trains around Cologne and Düsseldorf.
- Protein Purification:Ultracentrifuge-based density-gradient methods isolate recombinant proteins and viral vectors. ECHA's evolving PFAS restrictions force reformulation of fluoropolymer seals in corrosive chemical processing applications.
- DNA Extraction:Microcentrifuge workflows dominate nucleic acid preparation for sequencing.
- Blood Component Separation:Plasma and platelet fractionation sustains demand in transfusion medicine.
Cell separation commands premium pricing; protein purification shows strongest volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial centrifuge engineering during the late nineteenth century, establishing precision manufacturing traditions that persist in the Rhine-Ruhr corridor. The sector's geographic footprint now spans multiple regulatory jurisdictions with distinct compliance architectures.
Germany
Food and chemical processing around Cologne and Düsseldorf sustains demand for high-capacity decanter units. ECHA's REACH enforcement mandates alloy traceability documentation that smaller fabricators struggle to absorb. The industrial cluster anchors European procurement for validated GMP equipment serving biopharmaceutical manufacturing.
United States
Gene therapy manufacturers in Massachusetts and North Carolina specify continuous-flow systems for 2,000-liter bioreactor trains. FDA 21 CFR Part 11 enforcement mandates audit-trail capabilities that compress replacement cycles in existing facilities. The Boston-Cambridge biotechnology corridor concentrates specialized ultracentrifuge procurement for viral vector production.
India
Contract manufacturing investment in Hyderabad and Bengaluru clusters generates centrifuge demand for single-use bioreactor integration. CDSCO's streamlined medical device regulations and PLI scheme incentives attract pharmaceutical capital deployment. The Genome Valley biotechnology hub specifies closed-system centrifugation for autologous cell therapy processing.
China
Domestic biopharmaceutical scale-up drives procurement of refrigerated centrifuges for temperature-sensitive biologics. NMPA's evolving GMP alignment with international standards pressures foreign equipment suppliers to localize validation support. The Yangtze River Delta concentration of CDMO facilities concentrates demand for high-throughput fixed-angle rotor systems.
Japan
Precision equipment traditions in Osaka and Nagoya sustain domestic manufacturing of compact disc-stack designs for food and beverage applications. METI's industrial technology roadmaps emphasize predictive maintenance integration for export competitiveness. The Kansai region's machinery ecosystem supplies rotor dynamics expertise to Asian pharmaceutical markets.
Centrifuge Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive component supply. Tier-one positions concentrate among European and Japanese fabricators with integrated foundry networks or precision casting partnerships. Two strategic archetypes dominate: full-line separations specialists spanning decanter to disc-stack technologies, and focused ultracentrifuge precision manufacturers serving molecular biology applications. Consolidation pressure intensifies through alloy certification cost absorption and service network scale requirements.
Among diversified European industrial groups, GEA Group Aktiengesellschaft and ANDRITZ exemplify the full-line archetype with upstream control over critical manufacturing inputs. KUBOTA Corporation anchors the compact equipment segment from its Japanese manufacturing base. ALFA LAVAL represents the Scandinavian precision engineering tradition in separations technology. These three entities collectively illustrate how geographic industrial heritage shapes competitive positioning in rotor dynamics and materials science.
| Leading Market Players |
|---|
| ALFA LAVAL |
| GEA Group Aktiengesellschaft |
| ANDRITZ |
| FLSmidth A/S |
| KUBOTA Corporation |
| Flottweg SE |
| SPX FLOW, Inc. |
| Mitsubishi Kakoki Kaisha, Ltd. |
| Ferrum AG |
| Others |
Supply Flow & Price Mechanics
Alloy traceability certification costs cascade from European foundries through three distinct pricing tiers, with REACH-mandated material documentation compressing margins for standard-grade equipment while premium ultracentrifuge manufacturers absorb compliance overhead through captive supply networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects certification burden and rotor material grade differentiation. Premium ultracentrifuge systems command substantial markups based on vacuum-system complexity and validated FDA 21 CFR Part 11 audit-trail capabilities. Cost compression in standard benchtop units is intensifying because Indian and Chinese contract manufacturers are consolidating procurement volumes for fixed-angle rotor systems. Biotechnology firms show least price sensitivity due to GMP validation requirements, while academic research institutions face constrained capital budgets.
Supply Chain Analysis
Single-source vulnerability sits with precision titanium and stainless steel rotor casting capacity concentrated in Germany, Japan, and select East Asian suppliers. Critical component dependencies include high-performance bearings, turbomolecular vacuum pumps, and fluoropolymer seals facing REACH substitution pressures. Supply chain risk centers on regulatory restriction timelines for PFAS-containing materials that could force rapid reformulation of established seal specifications. Distribution runs through OEM-direct channels for GMP-validated pharmaceutical equipment and regional distributor networks for standard laboratory configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The centrifuge market functions as a stable compounder anchored by biopharmaceutical manufacturing expansion that sustains replacement cycles and technology upgrade demand across regulated facilities worldwide.
For Market Incumbents: Lock in rotor dynamics expertise through strategic foundry partnerships or backward integration into precision casting operations. Capture recurring service revenue by embedding predictive maintenance sensors and cloud analytics platforms before third-party metrology laboratories expand their technician networks. Prioritize PFAS-free seal validation to preempt regulatory enforcement deadlines.
For New Entrants and Emerging Players: Continuous-flow centrifugation systems for cell therapy manufacturing offer a technology-first wedge into a segment where incumbent validation timelines create temporary white space. Target Indian CDMO clusters in Hyderabad and Bengaluru where CDSCO streamlined regulations and PLI incentives are accelerating facility construction. Lead with modular equipment architectures that reduce facility footprint and enable contract manufacturing migration.
For Investors and Strategic Acquirers: Consolidation pressure builds where alloy traceability compliance costs exceed smaller fabricators' capital reserves, creating acquisition opportunities for service-network scale. Frame long-term viability around captive component supply and installed base service monetization rather than equipment shipment volumes. Watch ECHA PFAS restriction enforcement timelines as the critical inflection signal for material substitution investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Cloud-based rotor balancing shifts OEM revenue from reactive repair to subscription analytics. |
| PFAS-Free Seal Validation Program | ECHA restriction proposals force 18-month material certification ahead of enforcement deadlines. |
| Continuous-Flow System Scale-Up | Gene therapy manufacturers in Massachusetts specify these for 2,000-liter bioreactor trains. |
| Indian Manufacturing Footprint Expansion | CDSCO regulations and PLI incentives attract contract manufacturing investment in Hyderabad clusters. |
| Captive Foundry Network Integration | Internal alloy traceability management defends margin position against REACH certification cost pass-through. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged equipment procurement managers at pharmaceutical CDMOs, maintenance directors at clinical diagnostic laboratories, regulatory affairs specialists at GMP facilities, and aftermarket service heads at OEM distribution networks. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, ECHA REACH restriction proposals, ISO 13485 certification databases, and customs trade records for centrifuge equipment. Bottom-up equipment shipment estimates triangulated against top-down biopharmaceutical capital expenditure allocations.
Segment-weighting approaches distributed value across product type, technology configuration, end-user vertical, and application workflow dimensions. CAGRs were derived from regression analysis of historical shipment volumes against bioreactor capacity expansion and replacement cycle compression. Forecast inputs incorporated gene therapy manufacturing facility announcements, continuous-flow adoption rates in cell harvesting, and PFAS substitution timeline assumptions.
The model holds under steady biopharmaceutical capital deployment and REACH enforcement timelines; deviation in alloy supply disruptions or accelerated PFAS restrictions would shift equipment availability and pricing trajectories. Forecasts reflect documented assumptions about regulatory implementation schedules and manufacturing capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Cell Washer Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Fluoroscopy Equipment Market