
 Global Refrigerated Incubators Market | 2026-2036
Global Refrigerated Incubators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refrigerated Incubators Market Foresight
Aftermarket service revenue is rewriting profitability expectations across the competitive landscape. Thermo Fisher Scientific Inc. leverages its global service network to capture recurring calibration and validation contracts. Binder GmbH anchors its position through specialized climate chamber expertise and German engineering credibility. Eppendorf AG differentiates via deep integration with bioprocessing workflows and adjacent laboratory automation portfolios.
Refrigerated incubators are precision thermal control enclosures maintaining programmable temperature ranges, typically between minus ten and plus seventy degrees Celsius, utilizing compressor-based cooling and resistive heating systems for sample conditioning. Their primary purpose centers on supporting cell viability, microbial cultivation, and enzymatic stability across life science workflows. Benchtop configurations dominate installed base volumes due to laboratory space constraints and flexibility demands, while multi-chamber units command premium positioning where simultaneous protocol diversification matters. Forced-air circulation technology leads performance-tier differentiation by ensuring uniformity within plus-or-minus zero-point-five degrees Celsius across the chamber volume.
FDA quality system regulations and EU MDR conformity requirements shape product development roadmaps by mandating documented thermal validation and alarm traceability for clinical and pharmaceutical applications. ISO 9001 and IEC 61010 safety standards further constrain design choices and supplier qualification pathways across international procurement channels. Stakeholders must monitor evolving energy efficiency directives and refrigerant phase-down schedules as these will force compressor technology transitions and redesign cycles ahead of regulatory deadlines.
Market Dynamics
The refrigerated incubator market is experiencing structural pressure from refrigerant phase-down mandates under the EU F-Gas Regulation and EPA SNAP rules, forcing compressor technology transitions that compress product development cycles and elevate R&D intensity across equipment portfolios.
Growth Catalysts
- Biologics pipeline expansion:Pharmaceutical developers in Germany, the United States, and Japan are scaling cold-chain incubation capacity for cell and gene therapy manufacturing, driving demand for precision thermal control systems with documented validation protocols.
- EU MDR conformity requirements:The Medical Device Regulation mandates alarm traceability and thermal validation documentation for clinical applications, compelling healthcare procurement teams to upgrade legacy equipment with compliant certified units.
- Forced-air circulation technology:Enhanced uniformity specifications of plus-or-minus zero-point-five degrees Celsius are becoming standard in pharmaceutical quality systems, accelerating replacement cycles in precision manufacturing clusters.
Market Restraints
- Copper and aluminum input volatility:Compressor manufacturing and heat exchanger fabrication face raw material price swings that compress equipment margins and complicate long-term contract pricing.
- German engineering supply concentration:Specialized climate chamber expertise clusters around precision manufacturing regions in southern Germany, creating bottleneck risks for validation-critical procurement.
- Refrigerant transition timelines:The F-Gas Regulation phase-down schedule forces premature obsolescence of installed compressor architectures before full depreciation cycles complete.
Strategic Opportunities
- India biopharma infrastructure buildout:CDSCO regulatory alignment with ICH guidelines is accelerating investment in temperature-controlled equipment for domestic vaccine and biosimilar production.
- Cloud-connected validation systems:Integration of IoT sensors with laboratory information management systems enables remote monitoring compliance, opening service revenue streams in distributed research networks.
- Energy efficiency directives:The EU Green Deal and corresponding national efficiency mandates create procurement preference for variable-speed compressor designs that exceed baseline performance tiers.
Industry Challenges
- Thermal validation engineering scarcity:Documented IQ/OQ/PQ protocol execution requires specialized technicians that pharmaceutical equipment vendors struggle to recruit at scale.
- Multi-chamber integration complexity:Simultaneous protocol diversification demands create software and hardware compatibility friction with existing laboratory automation stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refrigerated Incubators Market |
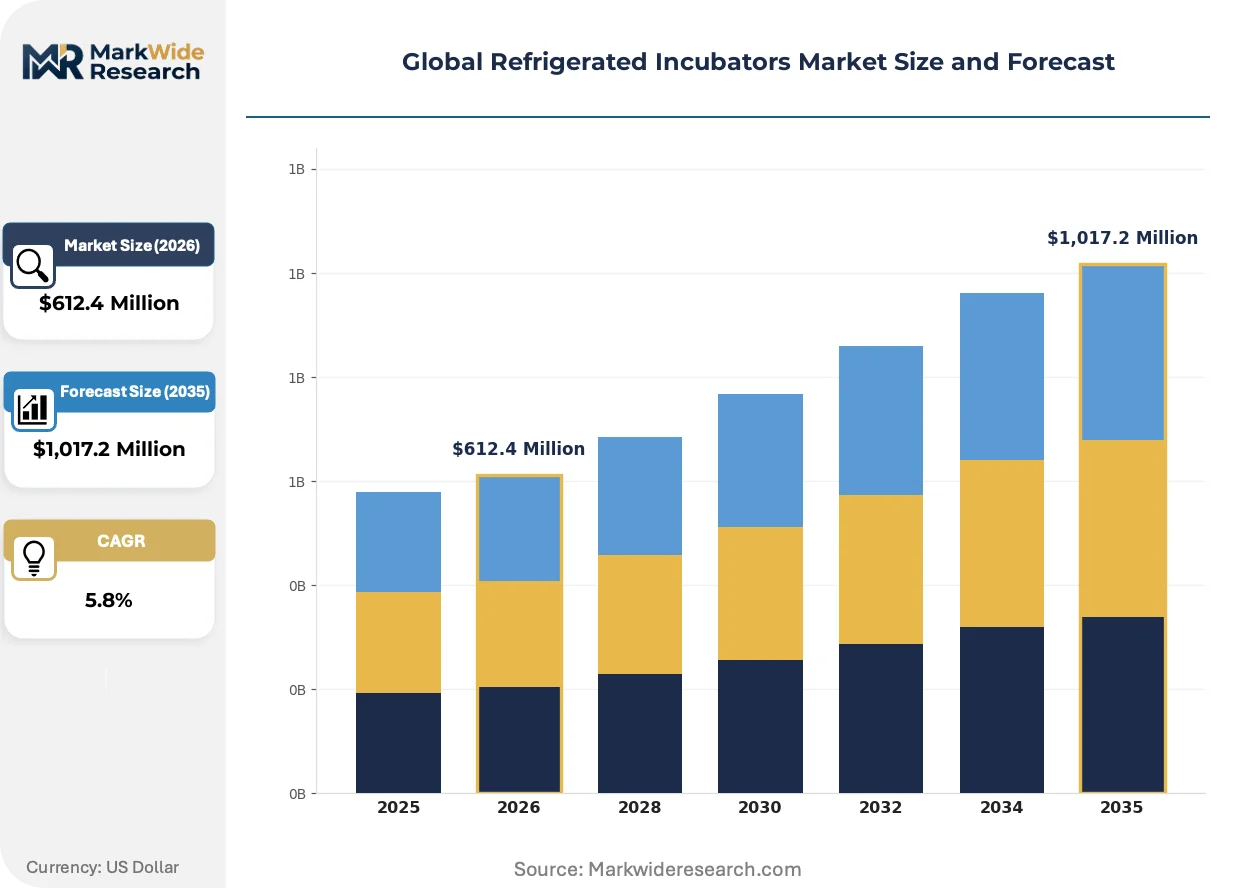
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Floor-Standing, Portable, Multi-Chamber Technology: Microprocessor Control, Digital Display, Analog Control, Forced-Air Circulation Application: Microbiology, Cell Culture, Pharmaceuticals, Biotechnology, Food Testing End User: Research Institutes, Clinical Laboratories, Pharmaceutical Companies, Biotech Firms |
| Companies Covered | Binder GmbH, Thermo Fisher Scientific Inc., PHC Holding Corporation, Eppendorf AG, Amerex Instruments, Inc., Sheldon Manufacturing, Inc., LEEC Ltd., Memmert GmbH + Co. KG, Benchmark Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refrigerated Incubators Market Shifts & Advancements
Digital integration and sustainability mandates are converging to redefine equipment specification criteria, with buyers prioritizing connected validation capabilities and refrigerant compliance alongside traditional performance metrics.
Variable-speed compressor technology with integrated IoT sensor arrays is digitizing thermal control workflows by enabling real-time uniformity monitoring and predictive maintenance scheduling. Pharmaceutical quality teams in the United States and Germany are adopting these systems at accelerated replacement cycles. This digitization is compressing the competitive advantage of traditional equipment vendors lacking cloud-native validation architectures.
The EU F-Gas Regulation phase-down schedule is forcing refrigerant transitions from hydrofluorocarbon blends to hydrofluoroolefin and natural refrigerant alternatives. Equipment manufacturers must redesign compressor architectures and thermal management systems to maintain performance under lower global warming potential constraints. Multi-chamber units for simultaneous protocol diversification face the steepest engineering challenges given complex heat load balancing requirements.
Service contract unbundling is fragmenting traditional equipment procurement relationships, with pharmaceutical buyers separating capital acquisition from calibration and validation service provision. Third-party metrology specialists in Japan and Switzerland are capturing recurring revenue streams that equipment OEMs previously controlled. This disintermediation is most visible in CDMO networks where audit-ready documentation requirements favor independent validation specialists over manufacturer-captive service teams.
Global Refrigerated Incubators Market Segmentation
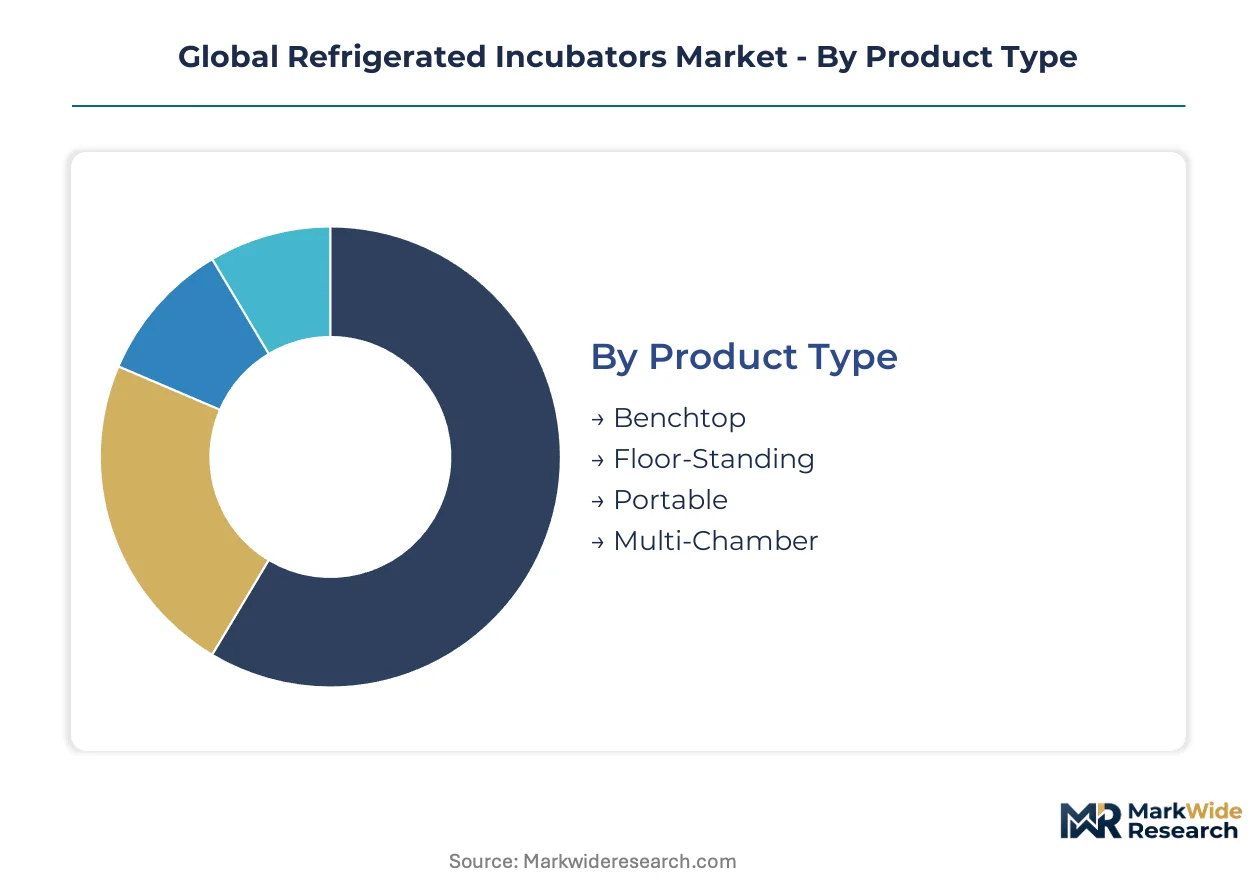
Segmentation in refrigerated incubators reflects divergent capital intensity, precision requirements, and facility constraints across life science workflows. Equipment specification varies sharply between high-throughput pharmaceutical manufacturing and distributed research environments. Understanding these divides enables targeted positioning against validation complexity and thermal performance tiers.
Product Type:
Cost tier determines procurement authority and replacement cadence across laboratory infrastructure investments.
- Benchtop:Compact compressor-based units designed for laboratory bench deployment with typical chamber volumes under 200 liters. Demand concentrates in academic research institutes and clinical laboratories across Germany and Japan where space constraints limit floor-standing alternatives. Pharmaceutical quality teams favor these for protocol development phases requiring rapid reconfiguration.
- Floor-Standing:High-capacity enclosures exceeding 400 liters with reinforced shelving for industrial-scale sample conditioning. Biologics manufacturers in the United States deploy these for cell therapy production workflows requiring documented thermal validation under FDA quality system regulations. The steepest capital expenditure per unit reflects integrated alarm traceability and multi-point sensor arrays.
- Portable:Lightweight units with battery backup options for field deployment and temporary capacity expansion.
- Multi-Chamber:Integrated systems enabling simultaneous temperature zones for protocol diversification in centralized facilities.
Benchtop configurations command the established base. The steepest expansion runs through floor-standing units serving biologics manufacturing scale-up.
Technology:
Application criticality dictates control precision investment, with pharmaceutical workflows demanding redundant validation architectures.
- Forced-Air Circulation:Turbine-driven airflow systems maintaining thermal uniformity within plus-or-minus zero-point-five degrees Celsius across chamber volume. Cell culture applications in Japanese pharmaceutical clusters require this specification for viability-sensitive mammalian lines. FDA and PMDA inspection protocols increasingly mandate documented uniformity mapping.
- Microprocessor Control:Programmable logic controllers enabling multi-step temperature profiles with data logging and remote alarm integration. Biotechnology firms in Germany adopt these for automated bioprocessing workflows requiring seamless laboratory information management system connectivity. Cloud-native architectures are displacing legacy standalone controllers.
- Digital Display:Touchscreen interfaces with real-time temperature visualization and audit trail generation.
- Analog Control:Electromechanical thermostat systems retained in cost-sensitive educational and basic research settings.
Forced-air circulation dominates pharmaceutical specification sheets. Microprocessor control is gaining share fastest through bioprocessing automation integration.
Application:
Volume concentration varies by regulatory exposure, with clinical-facing segments bearing heavier validation documentation burdens.
- Pharmaceuticals:GMP-compliant incubation for stability testing, cell line propagation, and fill-finish support in licensed manufacturing suites. Demand clusters in Massachusetts, Basel, and Osaka where biologics pipeline density drives cold-chain infrastructure investment. EU MDR and FDA quality system regulations mandate IQ/OQ/PQ protocol execution.
- Cell Culture:Mammalian and microbial cultivation requiring precise CO2 and humidity integration alongside thermal control. Contract development and manufacturing organizations across Switzerland and Singapore scale capacity for gene therapy vector production. Serum-free media transitions are elevating environmental control sensitivity.
- Microbiology:Bacterial and fungal cultivation for diagnostic and research purposes with moderate precision requirements.
- Biotechnology:Enzymatic stability assessment and fermentation process development across industrial and agricultural applications.
- Food Testing:Pathogen detection and shelf-life simulation for regulatory compliance in commercial laboratories.
Pharmaceutical applications anchor revenue concentration. Cell culture workflows are expanding most quickly through gene therapy manufacturing buildout.
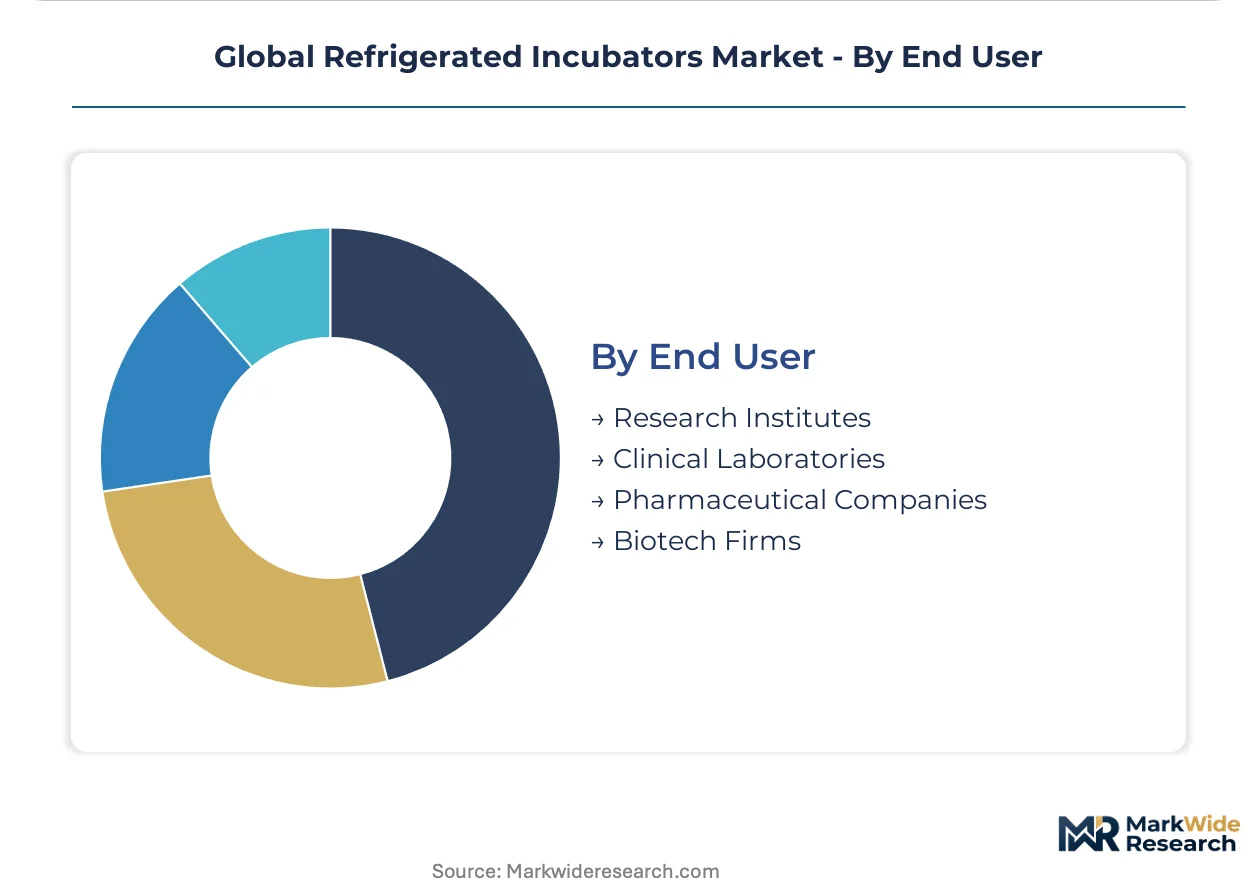
End User:
Customer type shapes service contract attachment rates and replacement cycle timing through capital availability and audit frequency.
- Pharmaceutical Companies:Integrated drug developers and contract manufacturers with dedicated metrology teams and preventive maintenance programs. Facilities in Germany and the United States negotiate enterprise pricing for standardized equipment fleets to simplify validation documentation. Recurring calibration contracts generate aftermarket revenue concentration.
- Research Institutes:University and government laboratories with fragmented procurement authority and grant-dependent capital cycles. Japanese national research centers maintain aging installed bases due to budget constraints, creating deferred replacement demand. Shared equipment cores favor benchtop flexibility over specialized configurations.
- Clinical Laboratories:Hospital-affiliated and independent diagnostic facilities with regulatory exposure through accreditation programs.
- Biotech Firms:Venture-funded development-stage companies with rapid scaling needs and limited historical validation infrastructure.
Pharmaceutical companies command the established base. The steepest expansion runs through biotech firms scaling from discovery into GMP manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement environments. Academic laboratories in Japan defer replacement cycles due to budget constraints, while pharmaceutical manufacturers in Germany and the United States absorb premium pricing for validated equipment without volume elasticity.
United States
Biologics manufacturing clusters in Massachusetts and North Carolina drive demand for floor-standing units with FDA-mandated alarm traceability. The EPA SNAP program accelerates refrigerant transition timelines, compressing product development cycles for domestic equipment vendors. Greater Boston anchors cell therapy production infrastructure where CDMOs scale GMP-compliant incubation capacity.
Germany
Precision engineering heritage sustains premium positioning for climate chamber specialists serving pharmaceutical quality teams. The EU F-Gas Regulation forces compressor redesigns ahead of full depreciation cycles, elevating R&D intensity for Baden-Württemberg-based fabricators. Basel-proximate manufacturing corridors in southern Germany concentrate validation-critical procurement for stability testing workflows.
Japan
PMDA inspection protocols mandate documented thermal uniformity mapping, accelerating replacement of aging analog-controlled units in Osaka pharmaceutical clusters. National research institutes under METI funding constraints maintain extended equipment lifecycles, creating deferred demand accumulation. Tokyo-Yokohama biotech corridors prioritize microprocessor-controlled systems for automated bioprocessing integration.
India
CDSCO regulatory alignment with ICH guidelines accelerates domestic vaccine and biosimilar production infrastructure investment. The PLI scheme for pharmaceuticals incentivizes temperature-controlled equipment procurement by contract manufacturers. Hyderabad and Bengaluru biotech clusters scale cold-chain incubation capacity for export-oriented biosimilar development.
Switzerland
Swissmedic oversight of gene therapy manufacturing elevates specification requirements for multi-chamber units in Basel and Zurich CDMO networks. Third-party metrology specialists capture service revenue streams through independent IQ/OQ/PQ protocol execution. The country's precision instrumentation ecosystem supports validation engineering scarcity mitigation for pharmaceutical equipment vendors.
Global Refrigerated Incubators Market Competitive Landscape
Capability concentration sits with specialized climate chamber engineers; scale advantage sits with diversified laboratory equipment conglomerates. The market structures around three tiers: German-engineered precision specialists, diversified life science platforms with global service networks, and regional fabricators competing on delivery speed. Consolidation pressure runs through calibration service unbundling and refrigerant transition R&D burdens. Strategic moves center on cloud-native validation architecture development and aftermarket contract capture.
Among German-engineered specialists, Binder GmbH and Memmert GmbH + Co. KG exemplify precision climate chamber expertise anchored in southern Germany's manufacturing corridor. Thermo Fisher Scientific Inc. occupies the diversified platform position, leveraging global service infrastructure for recurring validation contract capture. These three represent distinct competitive archetypes: specialized engineering credibility, integrated service scale, and precision fabrication heritage respectively.
| Leading Market Players |
|---|
| Binder GmbH |
| Thermo Fisher Scientific Inc. |
| PHC Holding Corporation |
| Eppendorf AG |
| Amerex Instruments, Inc. |
| Sheldon Manufacturing, Inc. |
| LEEC Ltd. |
| Memmert GmbH + Co. KG |
| Benchmark Scientific |
| Others |
Supply & Pricing Matrix
German precision engineering clusters in Baden-Württemberg and Bavaria anchor compressor and climate chamber fabrication, concentrating margin capture with specialized OEMs while downstream buyers in Massachusetts and Basel absorb premium pricing for validated equipment. Aftermarket service contracts now rival hardware margins as recurring calibration and validation revenue streams reshape profitability expectations across the competitive landscape.
Pricing Analysis
Aftermarket service tiers including multi-year calibration contracts and IQ/OQ/PQ validation packages now drive lifetime value for equipment vendors. Three-tier pricing structure across premium certified, standard compliant, and economy educational levels separates pharmaceutical GMP-grade units with FDA traceability from basic research configurations. Pricing pressure stems from refrigerant transition R&D burdens compressing development cycles for compressor redesigns. Academic laboratories in Japan exhibit highest price sensitivity due to METI funding constraints, while biologics manufacturers in Germany and the United States demonstrate volume inelasticity for validated systems.
Supply Chain Analysis
Export control regimes limiting dual-use compressor technology flows constrain component sourcing for precision thermal management systems. Manufacturing concentration centers on Germany, Japan, and the United States for specialized climate chambers, with copper and aluminum heat exchanger fabrication drawing from Chinese and Chilean raw material suppliers. Single-source vulnerability runs through specialized German engineering suppliers for validation-critical components. Distribution runs through direct OEM sales teams for pharmaceutical accounts and laboratory distribution networks for research institute procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with service contract unbundling and refrigerant transition timing, as regulatory deadlines create procurement windows for agile suppliers while legacy vendors absorb redesign costs. Cloud-connected validation capabilities and third-party metrology specialization are fragmenting traditional equipment-vendor relationships across CDMO networks.
For Market Incumbents: Pre-empt disintermediation by captive service teams through accelerated cloud-native validation architecture deployment and exclusive multi-year calibration contract capture with pharmaceutical enterprise accounts. Compressor technology transition timelines threaten premature obsolescence of installed bases; backward integration into refrigerant-compliant compressor sourcing secures supply continuity. Certification investment in EU MDR and FDA quality system documentation protocols reinforces switching costs against independent validation specialists. For New Entrants and Emerging Players: Mid-market biotech firms scaling from discovery into GMP manufacturing in India and Switzerland represent the most penetrable entry point for validated equipment without entrenched incumbent relationships. CDSCO regulatory alignment with ICH guidelines accelerates infrastructure buildout for domestic vaccine and biosimilar production, creating procurement windows before established vendor lock-in. Third-party metrology service provision offers a go-to-market angle with lower capital intensity than full equipment manufacturing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision instrumentation platforms lacking cloud-connected validation capabilities but holding established pharmaceutical customer relationships. Long-term viability over a five-to-ten year horizon rests on successful refrigerant transition execution and aftermarket revenue attachment rates. The signal to watch is CDMO procurement committee shifts toward independent IQ/OQ/PQ validation specialists versus manufacturer-captive service teams as an inflection indicator for vendor power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Validation Architecture Development | IoT sensor integration with laboratory information management systems enables remote compliance monitoring for distributed research networks. |
| Refrigerant-Compliant Compressor Redesign | EU F-Gas Regulation phase-down mandates force thermal management system transitions ahead of full depreciation cycles. |
| Aftermarket Service Contract Capture | Multi-year calibration and validation agreements generate recurring revenue rivaling hardware margins in pharmaceutical accounts. |
| Third-Party Metrology Capability Buildout | Independent IQ/OQ/PQ protocol execution captures service revenue streams from equipment OEMs in Swiss and Japanese CDMO networks. |
| India Biopharma Infrastructure Partnership | PLI scheme incentives and CDSCO regulatory alignment create procurement channels for temperature-controlled equipment in vaccine production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and equipment vendor disclosures across the analysis window. Primary interviews engaged equipment engineering directors, pharmaceutical quality assurance leads, laboratory procurement managers, and aftermarket service heads at climate chamber manufacturers and biologics developers. Secondary validation drew from FDA quality system guidance documents, EU MDR conformity assessment procedures, EPA SNAP refrigerant rulemakings, and ISO 9001 certification databases. Bottom-up segmentation modeling triangulated against top-down market sizing from industry association shipment data.
Forecast inputs incorporate product type adoption curves, technology replacement cycles, and application-specific regulatory compliance deadlines across the projection horizon. Segmentation dimensions modeled include equipment configuration, thermal control technology, end-use application, and customer type with geographic regulatory cluster overlays. CAGRs derive from installed base growth, replacement cycle compression, and premium tier mix shift assumptions. Refrigerant phase-down schedules and biologics pipeline expansion trajectories serve as primary demand-side forecast inputs.
Practitioners should monitor refrigerant transition cost pass-through, CDSCO inspection protocol evolution, and CDMO procurement committee composition shifts for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Europe Medical Automation Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Hospital Stretchers Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Operating Light Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Medical Suction Units Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Global Oxygen Flow Meters Market