
 Apheresis Equipment Market | 2026-2036
Apheresis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Apheresis Equipment Market Analysis
A shift from single-source equipment procurement to multi-vendor service contracts is realigning how hospital systems acquire apheresis capacity. Fresenius SE & Co. KGaA leverages its dialysis-installed base to cross-sell therapeutic apheresis platforms. Haemonetics Corporation anchors the North American donor collection segment through long-term blood center partnerships. Terumo BCT, Inc. competes on continuous flow centrifugation precision for stem cell harvest protocols.
Apheresis equipment comprises automated extracorporeal systems that separate blood components using centrifugal force or membrane filtration, operating at controlled flow rates of 50–70 mL per minute to isolate platelets, plasma, leukocytes, or red cells for therapeutic removal or collection. These systems serve critical roles in treating autoimmune disorders, harvesting hematopoietic stem cells, and supporting regenerative medicine cell therapy manufacturing. Platelet apheresis and plasma apheresis product types command the largest installed base, while leukapheresis generates premium margins through CAR-T cell therapy feedstock demand. Continuous flow technology dominates clinical throughput, though membrane separation is gaining traction in selective plasma filtration applications where protein specificity matters.
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) impose substantial clinical evidence burdens on apheresis system software updates and disposable kit modifications. The EMA's Good Manufacturing Practice standards for cellular therapy starting materials extend compliance obligations to equipment used in leukapheresis collections destined for commercial cell products. Stakeholders must monitor how evolving ISO 13485 quality management expectations and emerging WHO blood safety guidelines reshape validation protocols and regional market access timelines.
Market Dynamics
Automated apheresis systems face mounting software validation burdens as FDA 510(k) clearance pathways tighten for algorithm-driven blood component separation protocols, compressing product update cycles and elevating compliance costs across installed bases.
Growth Catalysts
- Therapeutic Plasma Exchange Expansion:Rising autoimmune disease prevalence in Germany, Japan, and the United States is expanding hospital apheresis program capacity.
- EU MDR Harmonization:Streamlined CE marking pathways for apheresis disposables are reducing regional market access friction for device manufacturers.
- Continuous Flow Centrifugation:Adoption of high-throughput cell separation platforms is accelerating stem cell harvest efficiency in academic medical centers.
Market Restraints
- Single-Source Disposable Dependency:Proprietary kit lock-in to specific device platforms creates switching costs and supply vulnerability for blood centers.
- Membrane Filtration Performance Ceiling:Protein selectivity limitations in membrane-based plasma separation constrain therapeutic applications requiring precise molecular targeting.
- EMA GMP Cellular Therapy Burden:Extended validation timelines for leukapheresis equipment used in commercial CAR-T feedstock production delay revenue recognition.
Strategic Opportunities
- India CDSCO Pathway Acceleration:Emerging blood banking infrastructure and rising thalassemia treatment demand create first-mover positioning for automated collection platforms.
- AI-Enabled Flow Rate Optimization:Machine learning integration with centrifugal separation systems promises real-time hematocrit adjustment and reduced operator intervention.
- Leukapheresis-to-Cell-Therapy Pipeline:Contract development and manufacturing organizations seek qualified equipment for GMP-compliant starting material collection.
Industry Challenges
- Perfusionist and Apheresis Technician Shortage:Specialized operator training requirements limit program expansion speed in community hospital settings.
- ISO 13485 Quality System Migration:Legacy device manufacturers face documentation gaps when adapting to updated risk management and post-market surveillance expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apheresis Equipment Market |
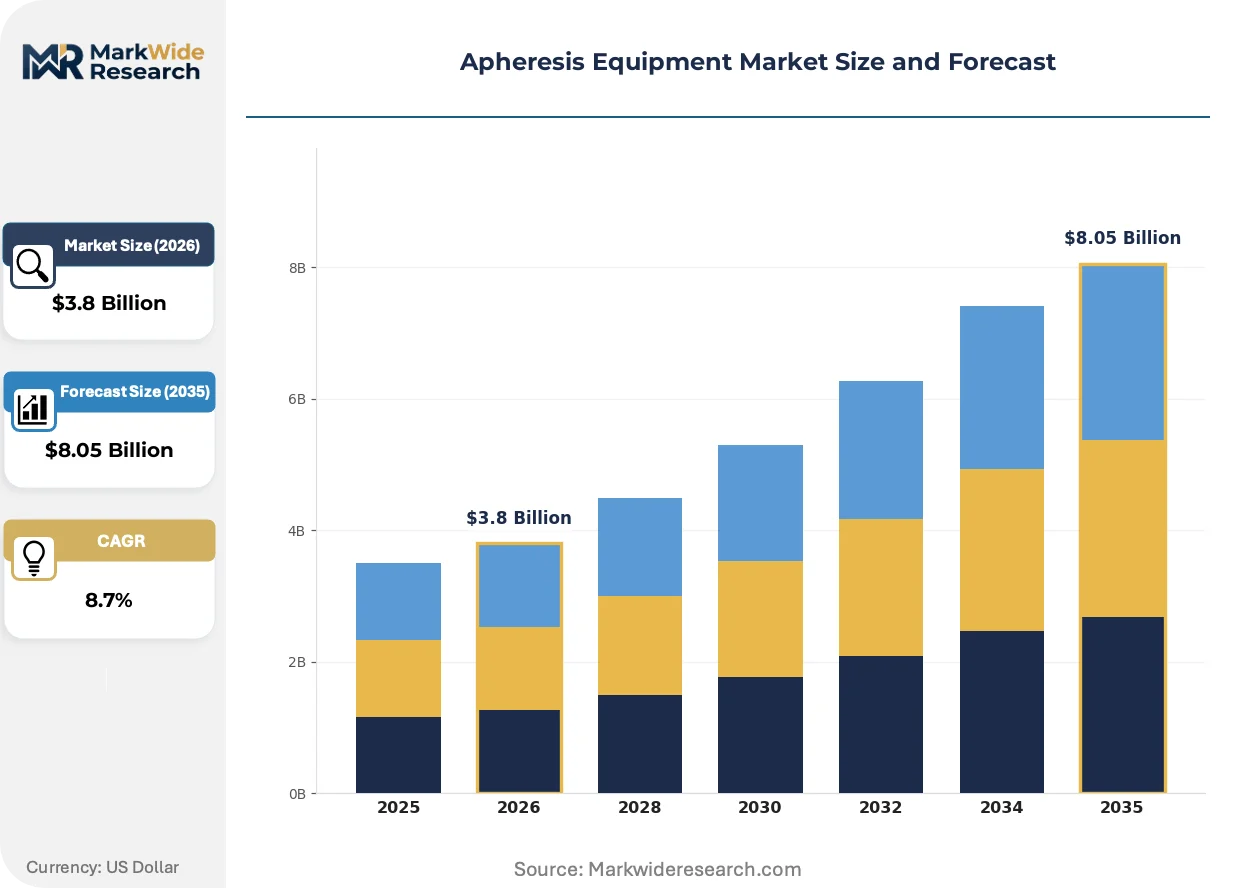
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platelet Apheresis, Plasma Apheresis, Leukapheresis, Red Cell Apheresis Technology: Continuous Flow, Intermittent Flow, Centrifugation, Membrane Separation End User: Hospitals, Blood Banks, Research Institutes, Dialysis Centers Application: Therapeutic Apheresis, Donor Apheresis, Cellular Therapy, Regenerative Medicine |
| Companies Covered | Haemonetics Corporation, Fresenius SE & Co. KGaA, Terumo BCT, Inc., Asahi Kasei Medical Co., Ltd., B. Braun SE, Cerus Corporation, NxStage Medical, Inc., Miltenyi Biotec, NIKKISO Medical Europe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apheresis Equipment Market Emerging Trajectories
Apheresis technology trajectories center on software-driven automation, evolving regulatory frameworks for cellular therapy starting materials, and restructured procurement relationships between device vendors and healthcare systems.
Membrane separation technology is converging with selective plasma filtration applications where protein specificity determines therapeutic efficacy. Academic medical centers in Switzerland and the Netherlands are piloting these systems for rare disease protocols. The structural consequence is compressing the addressable market for conventional centrifugal methods in niche therapeutic segments.
EMA's updated Good Manufacturing Practice standards for cellular therapy starting materials now explicitly cover apheresis equipment validation in commercial CAR-T manufacturing. This policy extension forces device manufacturers to generate clinical evidence packages previously reserved for pharmaceutical sponsors. European contract manufacturers are responding by consolidating supplier relationships to reduce audit complexity.
Hospital systems are unbundling equipment acquisition from disposable supply agreements, separating capital procurement from recurring revenue streams. Blood centers in the United States and Germany now negotiate multi-vendor service contracts rather than single-source equipment commitments. This behavioral shift is most visible in integrated delivery networks seeking operational flexibility across distributed apheresis programs.
Apheresis Equipment Market Segmentation
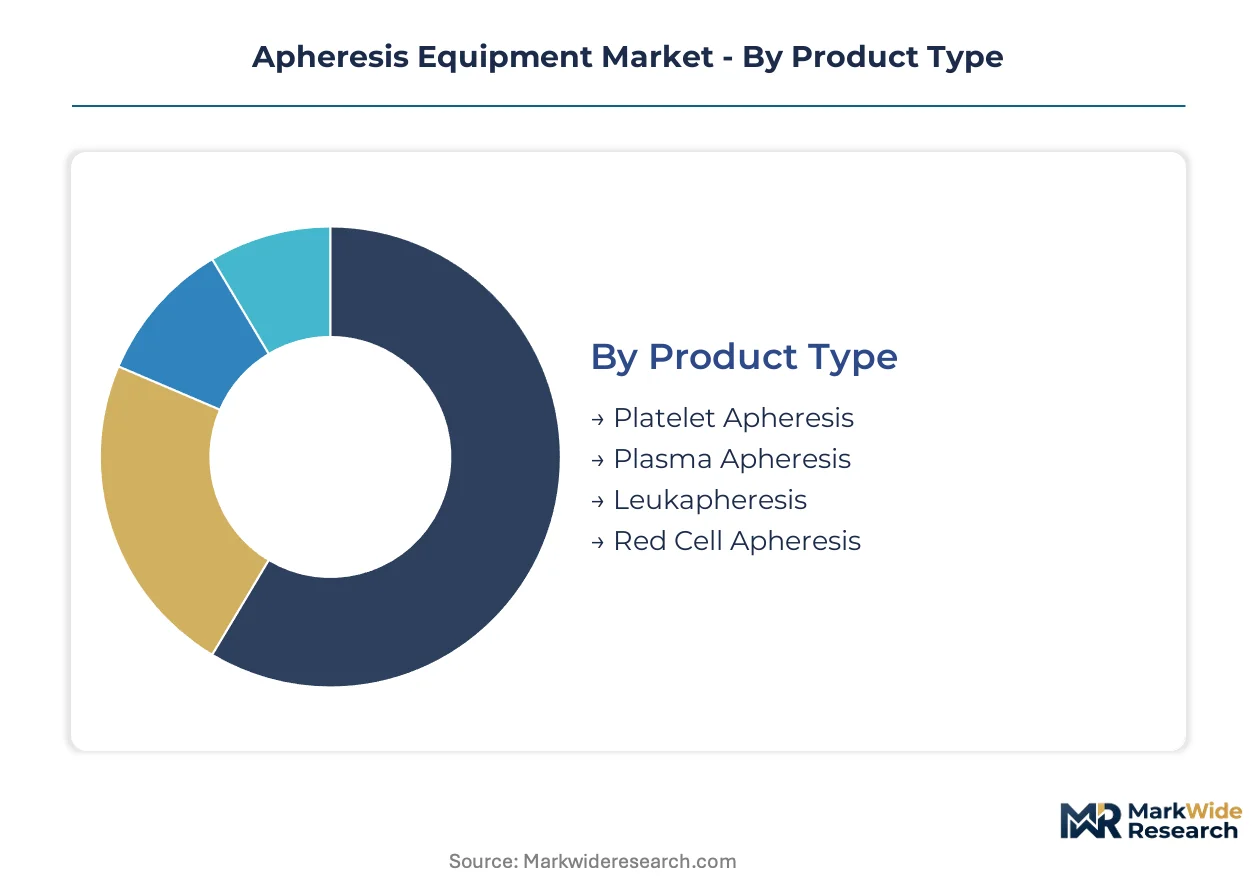
Apheresis equipment segmentation reveals how regulatory pathways and clinical use cases fragment procurement strategies across healthcare systems. Each dimension—product type, technology, end user, and application—carries distinct FDA 510(k) or EU MDR validation burdens that shape vendor positioning and hospital budgeting cycles.
Product Type:
FDA 510(k) clearance timelines vary substantially across product categories, with platelet and plasma systems facing streamlined predicate device pathways while leukapheresis platforms encounter extended clinical evidence requirements for cellular therapy applications.
- Platelet Apheresis:Automated systems isolate platelets from whole blood using continuous flow centrifugation at 50–70 mL per minute flow rates. Blood centers in the United States and Germany concentrate procurement here for transfusion-dependent oncology and trauma protocols.
- Plasma Apheresis:Centrifugal separation extracts plasma for fractionation into immunoglobulins and albumin. Rising therapeutic plasma exchange volumes for autoimmune disorders in Japan and the United States are expanding hospital-installed bases.
- Leukapheresis:Harvests mononuclear cells for CAR-T manufacturing under EMA GMP standards. Extended validation timelines apply for commercial cell therapy feedstock production.
- Red Cell Apheresis:Automated double red cell collection optimizes donor yield for transfusion services. Slower adoption reflects narrower clinical indications compared to platelet and plasma platforms.
Platelet Apheresis sits at the top of the volume ranking, with Leukapheresis climbing the fastest.
Technology:
Capital expenditure tiers separate these platforms, with continuous flow systems commanding premium pricing for high-throughput hospital programs while membrane separation attracts niche therapeutic applications requiring molecular selectivity.
- Continuous Flow:Dominates clinical throughput through uninterrupted blood processing. Academic medical centers in Switzerland and the Netherlands deploy these platforms for stem cell harvest efficiency.
- Intermittent Flow:Processes blood in discrete batches with lower capital costs. Blood banks with moderate collection volumes favor this approach for operational flexibility.
- Centrifugation:Established density-gradient separation technology with broad predicate device availability for FDA submissions.
- Membrane Separation:Selective plasma filtration where protein specificity determines therapeutic efficacy. Pilot programs for rare disease protocols are expanding the addressable market.
Continuous Flow generates the largest installed base, though Membrane Separation is gaining share fastest in selective filtration niches.
End User:
Procurement authority concentration differs sharply across these settings—hospital systems centralize capital decisions while blood banks negotiate multi-vendor service contracts for distributed collection networks.
- Hospitals:Therapeutic apheresis programs for autoimmune and neurological disorders drive equipment placement. Integrated delivery networks in the United States are unbundling capital procurement from disposable supply agreements.
- Blood Banks:Donor collection infrastructure depends on automated platforms for component optimization. Long-term partnerships with device manufacturers shape competitive positioning in Germany and Japan.
- Research Institutes:Preclinical and translational studies require flexible systems for protocol development. Lower volume requirements favor intermittent flow technology.
- Dialysis Centers:Cross-selling opportunities from existing vascular access infrastructure. Fresenius leverages its dialysis-installed base to expand therapeutic apheresis penetration.
Hospitals command the largest capital allocation, with Blood Banks showing the steepest expansion trajectory in automated collection capacity.
Application:
Margin structures diverge significantly—donor apheresis operates on thin per-procedure economics while cellular therapy applications command premium pricing for GMP-compliant equipment validation.
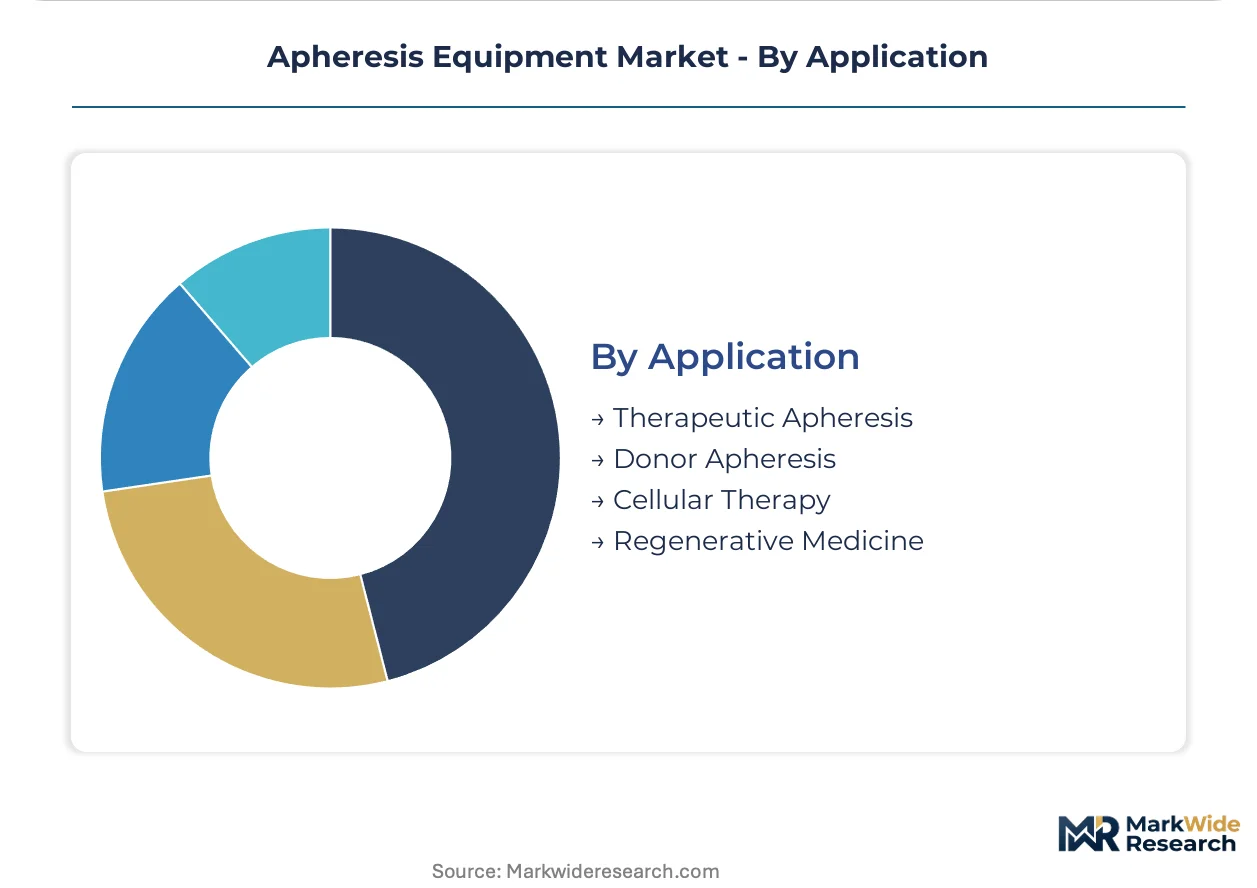
- Therapeutic Apheresis:Removes pathogenic antibodies or lipids from patient circulation. Rising autoimmune disease prevalence in aging populations expands hospital program capacity in the United States and Germany.
- Donor Apheresis:Harvests blood components for transfusion supply. Volume-dependent economics favor high-throughput continuous flow platforms at regional blood centers.
- Cellular Therapy:Leukapheresis collections for CAR-T and stem cell therapies. EMA GMP standards now explicitly cover equipment validation, extending compliance obligations to device manufacturers.
- Regenerative Medicine:Emerging applications in tissue engineering and cell therapy manufacturing. Contract development organizations seek qualified equipment for starting material collection.
Donor Apheresis holds the highest procedure volume, with Cellular Therapy expanding most quickly on CAR-T manufacturing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor concentrates North American CAR-T manufacturing infrastructure, pulling leukapheresis equipment demand into academic medical centers and contract development organizations.
United States
Therapeutic plasma exchange volumes for autoimmune disorders are expanding hospital apheresis programs in Cleveland Clinic and Mayo Clinic networks. FDA 510(k) clearance pathways for automated collection systems are tightening software validation requirements. Blood centers in the American Red Cross network are negotiating multi-vendor service contracts to reduce single-source disposable dependency.
Germany
Aging demographics are driving chronic disease apheresis protocols across university hospitals in Berlin and Munich. EU MDR harmonization is streamlining CE marking pathways for apheresis disposables, reducing regional market access friction. The Fraunhofer Institute clusters near Stuttgart are piloting membrane separation systems for rare disease therapeutic applications.
Japan
Metropolitan Tokyo and Osaka medical centers are deploying high-throughput continuous flow platforms for stem cell harvest efficiency. PMDA device approval timelines for algorithm-driven separation systems are compressing product update cycles. The Kobe biomedical innovation cluster is integrating apheresis equipment into regenerative medicine cell therapy manufacturing pipelines.
Switzerland
Academic medical centers in Zurich and Basel are piloting selective plasma filtration where protein specificity determines therapeutic efficacy. Swissmedic validation requirements for cellular therapy starting materials are extending compliance obligations to leukapheresis equipment manufacturers. The Lake Geneva biotech corridor is consolidating supplier relationships to reduce audit complexity for contract manufacturers.
India
Emerging blood banking infrastructure and rising thalassemia treatment demand are creating first-mover positioning for automated collection platforms in Mumbai and Delhi-NCR. CDSCO pathway acceleration is reducing device registration timelines for multinational manufacturers. The Hyderabad medical device cluster is attracting regional distribution partnerships for therapeutic apheresis platforms.
Apheresis Equipment Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance capabilities and installed base service density. The vendor base organizes into three tiers: diversified medical technology conglomerates with cross-selling infrastructure, blood management specialists with long-term center partnerships, and emerging players targeting cellular therapy validation niches. Consolidation pressure is mounting through M&A activity among disposable kit manufacturers and strategic partnerships between device makers and contract development organizations.
Within the diversified medical technology tier, Fresenius SE & Co. KGaA and B. Braun SE exemplify European-based conglomerates leveraging existing dialysis and infusion therapy infrastructure. Haemonetics Corporation and Terumo BCT, Inc. occupy positions as blood management specialists with deep North American and Japanese market penetration respectively. These five entities represent the competitive anchors around which procurement relationships and service contract negotiations revolve.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| Fresenius SE & Co. KGaA |
| Terumo BCT, Inc. |
| Asahi Kasei Medical Co., Ltd. |
| B. Braun SE |
| Cerus Corporation |
| NxStage Medical, Inc. |
| Miltenyi Biotec |
| NIKKISO Medical Europe GmbH |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap disposable kit manufacturers in Germany and Japan anchor supply discipline through long-term blood center partnerships, translating captive customer relationships into stable pricing corridors that resist commodity erosion. This ownership structure concentrates negotiation leverage with incumbent device platforms, forcing hospital systems toward multi-vendor service contracts to escape single-source dependency.
Pricing Analysis
Input-cost pass-through from medical-grade plastics and sterile filtration membranes runs through disposable kit pricing, with manufacturers indexing contract renewals to polymer commodity benchmarks. Pricing stratifies across GMP-validated premium tiers for cellular therapy applications, FDA-cleared standard platforms for hospital therapeutic programs, and economy intermittent-flow systems for moderate-volume blood banks. Cost compression in the economy tier intensifies because Indian and Chinese manufacturers are expanding regional distribution partnerships. Blood banks exhibit highest price sensitivity due to volume-dependent per-procedure economics, while CAR-T contract manufacturers accept premium pricing for EMA GMP-compliant validation packages.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Chicago, and Singapore orchestrate hub-and-spoke patterns for sterile disposable kits, with 48-hour replenishment commitments to hospital systems and blood centers. Component manufacturing concentrates in Germany, Japan, and the United States for precision centrifugation hardware, while Mexico and Malaysia host final assembly for cost-sensitive intermittent-flow platforms. Raw material dependencies center on medical-grade polycarbonates, silicone tubing, and gamma-stable packaging films. Single-source vulnerability persists for membrane filtration substrates sourced from specialized chemical processors in Switzerland and the Netherlands. Distribution runs through exclusive distributor networks in emerging markets and direct vendor-managed inventory at major academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Apheresis Equipment Market functions as a geographic-arbitrage play where EMA GMP validation burdens in Europe create cost and timeline premiums that Indian CDSCO-registered manufacturers can undercut by 30-40% on comparable hardware specifications.
For Market Incumbents: Acquire disposable kit manufacturing capacity to secure supply chain control against emerging Asian competitors. Haemonetics and Terumo BCT should backward integrate into membrane substrate production to reduce Swiss and Dutch supplier dependency. Fresenius must defend its dialysis cross-selling infrastructure through exclusive therapeutic apheresis service contracts with integrated delivery networks in the American Midwest. For New Entrants and Emerging Players: AI-enabled flow rate optimization algorithms offer a technology-first wedge into the continuous flow centrifugation segment dominated by legacy platforms. White-space targets include leukapheresis-to-cell-therapy pipeline equipment for Indian CDMOs and membrane separation systems for rare disease protocols in Dutch academic centers. A regulatory-first go-to-market angle—pre-validating software for FDA 510(k) predicate pathways—accelerates hospital procurement cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap disposable kit specialists with ISO 13485 certification gaps that strategic buyers can remedy through quality system integration. Long-term viability over the next decade hinges on cellular therapy feedstock positioning as CAR-T manufacturing scales beyond academic medical centers into commercial CDMO infrastructure. The signal to watch is CDSCO pathway acceleration timelines—compression there indicates first-mover capture of Indian thalassemia and blood banking automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Validation Investment | Accelerates clearance timelines for algorithm-driven separation protocols in Cleveland Clinic and Mayo Clinic networks. |
| EMA GMP Equipment Qualification Program | Extends compliance obligations to leukapheresis manufacturers supplying Swiss and German CAR-T contract manufacturers. |
| Multi-Vendor Service Contract Negotiation | Unbundles capital procurement from disposable supply agreements at American Red Cross blood centers. |
| Membrane Separation Technology Licensing | Pilots selective plasma filtration for rare disease protocols at Fraunhofer Institute clusters near Stuttgart. |
| CDSCO Registration Pathway Acceleration | Reduces device registration timelines for multinational manufacturers targeting Mumbai and Delhi-NCR blood banking infrastructure. |
Methodological Framework
Direct dialogue with apheresis program directors at Cleveland Clinic and Mayo Clinic networks, biomedical engineers at German university hospitals in Berlin and Munich, and procurement managers at the American Red Cross grounded qualitative assessment. Secondary validation drew from FDA 510(k) clearance databases, EMA GMP inspection records for cellular therapy starting materials, and hospital procurement contracts filed with US GPOs. Bottom-up triangulation across installed base counts and top-down reconciliation against therapeutic plasma exchange procedure volumes ensured cross-verified market sizing.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, technology platform, end-user setting, and application category. The analytical framework incorporated continuous flow versus membrane separation adoption curves, hospital versus blood bank capital expenditure cycles, and donor apheresis versus cellular therapy margin structures. CAGRs derived from procedure volume growth in autoimmune disease protocols, stem cell harvest efficiency improvements, and CAR-T manufacturing capacity expansion trajectories.
The model holds under stable regulatory validation timelines; deviation in FDA software clearance stringency or EMA GMP equipment audit frequency would shift revenue recognition patterns. Forecasts reflect assumptions about technician training pipeline expansion and polymer raw material supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Home Medical Equipment Market