
 Minor Surgical Lights Market | 2026-2036
Minor Surgical Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Minor Surgical Lights Market Foresight
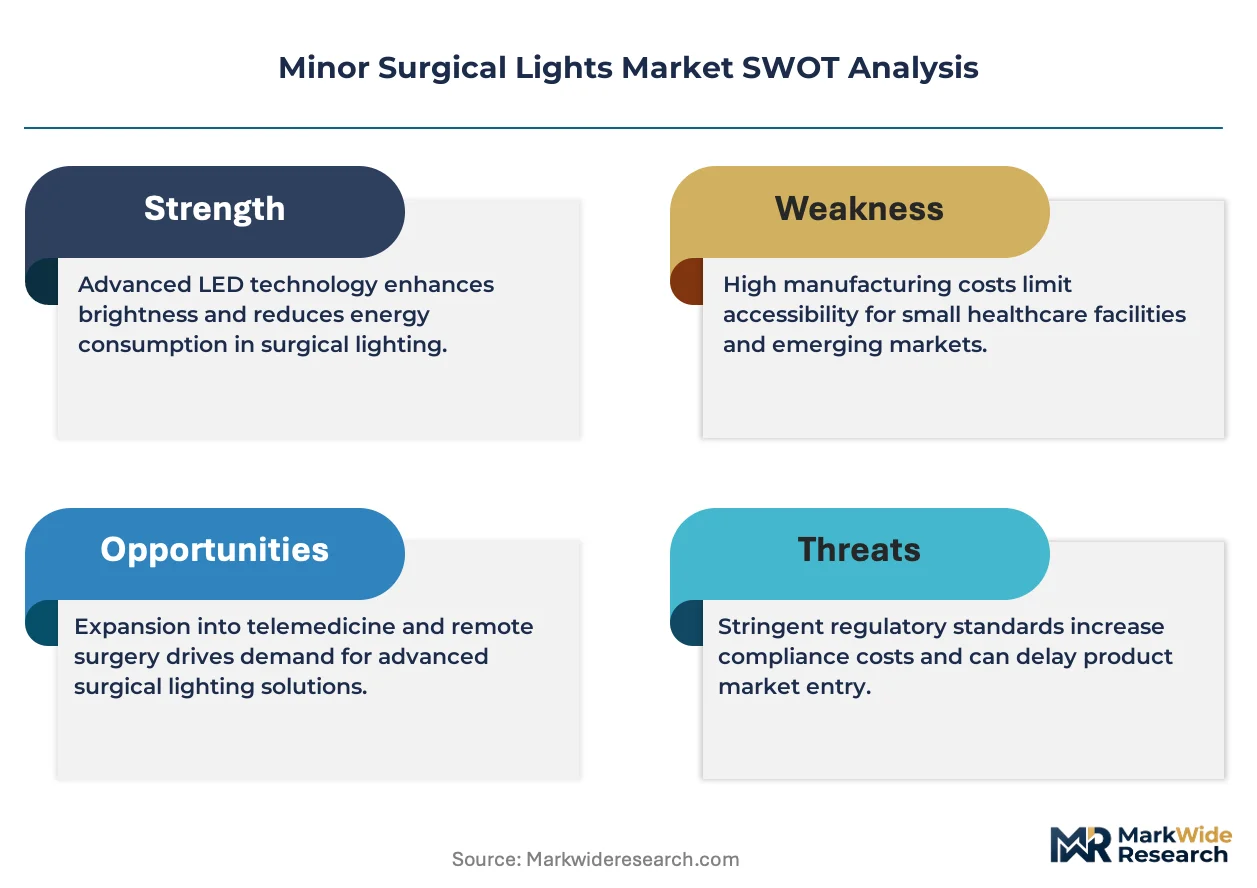
EU Medical Device Regulation is realigning the cost-of-entry calculus for minor surgical light manufacturers seeking CE-marked access. Skytron leverages its vertical integration in LED optical engines to sustain margin structures under tighter conformity assessment. Stryker anchors its competitive position through channel control across North American outpatient surgical centers. S.I.M.E.O.N. Medical GmbH & Co. KG specializes in ceiling-mounted configurations that dominate European hospital retrofit programs.
Minor surgical lights are precision illumination instruments engineered to deliver color temperatures between 3,500K and 5,000K with color rendering indices exceeding 90, designed for localized surgical fields in procedures not requiring full operating room infrastructure. LED product type now leads installed base transitions as halogen and xenon segments enter mature replacement-only phases; dermatology and orthopedics applications concentrate demand due to high procedure frequency in outpatient settings. Ceiling-mounted installation type captures the majority of hospital procurement value, while portable configurations serve the fastest-growing clinic and ambulatory center segments where space flexibility governs capital decisions.
FDA 510(k) clearance pathways and EU MDR conformity assessment shape product development timelines and market access sequencing for manufacturers. IEC 60601-1 medical electrical safety standards and ISO 13485 quality management requirements further discipline design controls and post-market surveillance obligations. Stakeholders must monitor how regulatory divergence between FDA and notified body interpretations of surgical lighting risk classification affects registration strategies and geographic launch prioritization.
Market Dynamics
LED optical engine maturation is compressing replacement cycles across outpatient surgical infrastructure as color rendering performance thresholds harden under EU MDR technical documentation requirements. Hospital capital committees now weight ten-year total cost of ownership against upfront procurement spend.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volume concentration in standalone facilities drives fixture procurement for procedure rooms lacking full OR infrastructure. Germany's specialist clinic networks anchor European demand density.
- EU MDR conformity alignment:Tighter notified body scrutiny of surgical lighting risk classification accelerates documentation investment among established manufacturers. CE-marked access becomes a competitive filter.
- Halogen-to-LED transition:Thermal management limitations of legacy illumination sources force replacement decisions as energy efficiency mandates tighten operational budgets.
Market Restraints
- Optical component supply concentration:Precision LED die and secondary optics production clusters in East Asian manufacturing regions expose procurement to logistics volatility.
- EU MDR transition costs:Conformity assessment fee inflation and extended technical documentation timelines compress margin structures for mid-tier product portfolios.
- Ceiling infrastructure rigidity:Hardwired electrical and mechanical mounting specifications in existing hospital construction limit portable configuration penetration.
Strategic Opportunities
- Battery-integrated portable units:Cordless illumination systems address space-constrained clinic environments where permanent installation is structurally prohibitive.
- Indian outpatient infrastructure buildout:Central government health scheme expansion into tier-2 and tier-3 cities creates procurement windows for mid-range LED configurations.
- IEC 60601-1-2 electromagnetic compatibility harmonization:Converged international standards reduce variant proliferation costs for manufacturers serving multiple regulatory domains.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise spanning optical physics, thermal management, and medical electrical safety standards concentrates in established manufacturing clusters.
- Legacy fixture integration complexity:Suspension arm and control interface incompatibility with installed hospital infrastructure extends sales cycles and elevates field service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minor Surgical Lights Market |
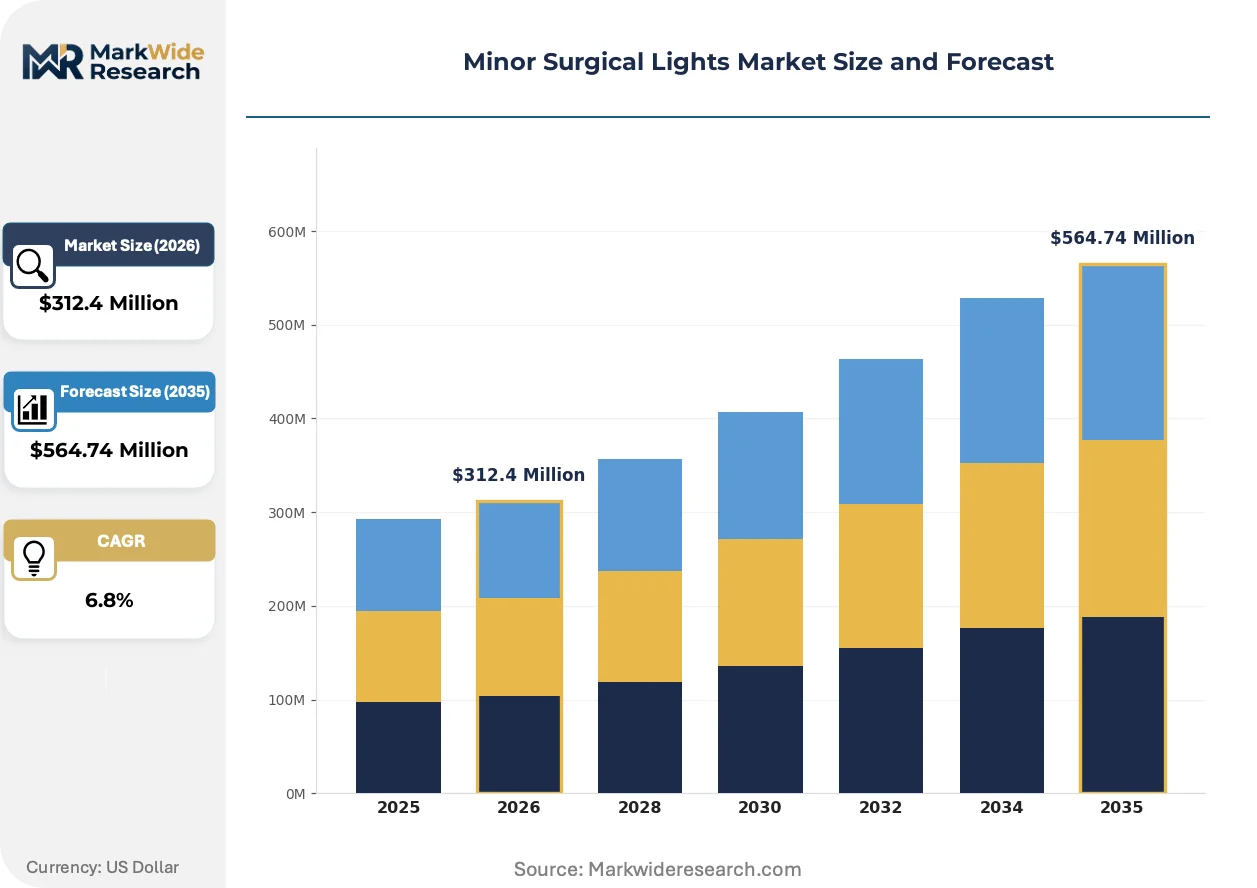
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Fluorescent Application: Orthopedics, Dermatology, Gynecology, Urology End User: Hospitals, Outpatient Surgical Centers, Clinics, Medical Institutions Installation Type: Ceiling Mounted, Wall Mounted, Portable, Floor Standing |
| Companies Covered | Skytron, A-dec Inc., STERIS, KLS Martin Group, S.I.M.E.O.N. Medical GmbH & Co. KG, Stryker, Koninklijke Philips, Baxter, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minor Surgical Lights Market Shifts & Advancements
Illumination control architectures are migrating toward software-defined intensity and color temperature modulation. This shift reconfigures supplier value capture toward embedded systems competency and away from pure optical component manufacturing.
Adaptive ambient compensation technology is expanding into minor surgical light product lines. Ceiling-mounted configurations in German hospital retrofit programs adopt sensor-driven output adjustment to maintain field consistency against variable room lighting. The capability is compressing specification differentiation between premium and standard product tiers.
EU MDR Annex I general safety and performance requirements are forcing design control documentation depth that favors manufacturers with established quality management systems. Notified body capacity constraints in Germany and the Netherlands extend conformity assessment timelines. Smaller manufacturers are responding through authorized representative partnerships and technical file outsourcing.
Hospital procurement committees are consolidating vendor relationships to reduce service contract fragmentation. Multi-year maintenance agreements bundled with initial capital expenditure now displace transactional spot purchasing in North American health system procurement. This concentration is most visible in integrated delivery networks spanning multiple ambulatory surgical centers.
Minor Surgical Lights Market Segmentation
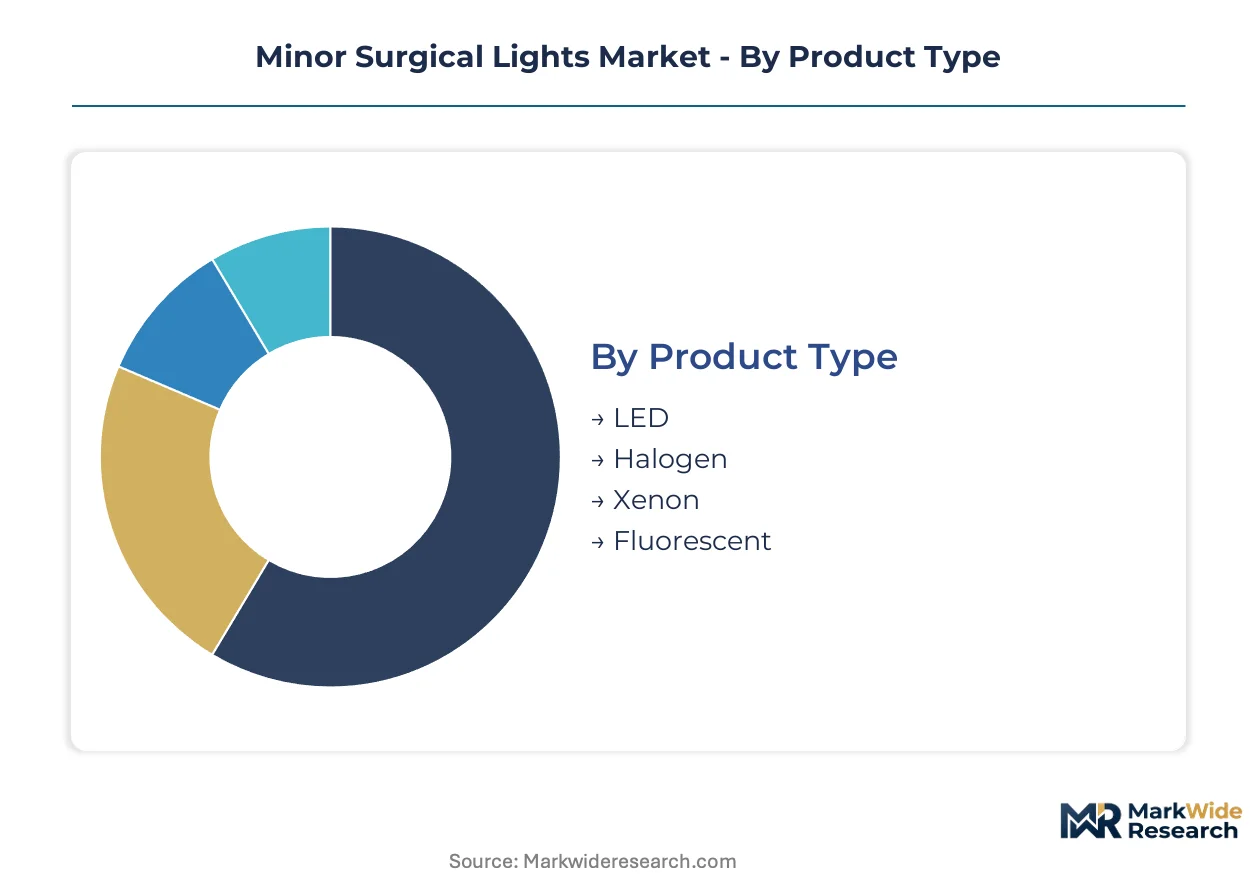
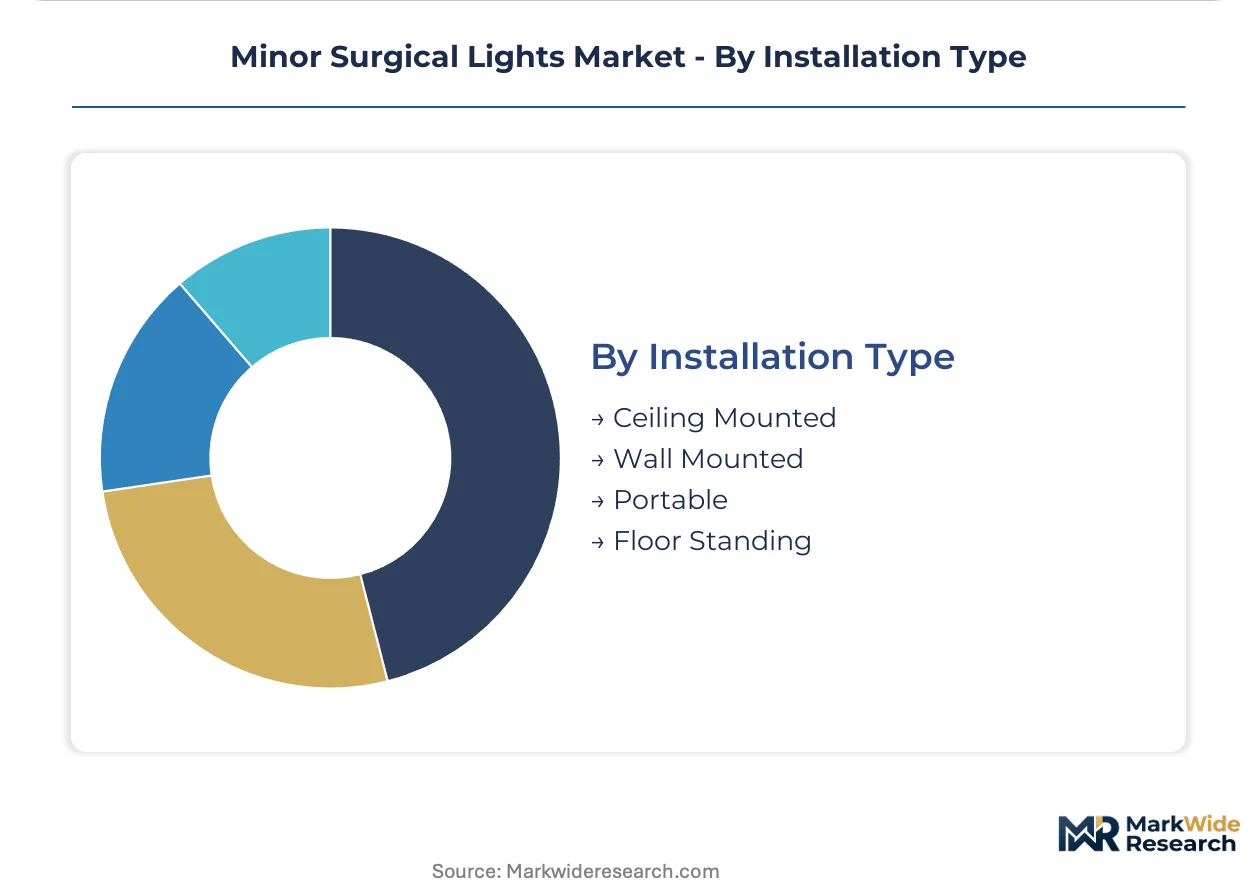
Segmentation in minor surgical lights reveals how procurement priorities diverge between capital-intensive hospital infrastructure and flexible outpatient environments. Understanding these splits illuminates where specification standards tighten versus where cost and adaptability dominate purchasing decisions.
Product Type:
LED configurations command premium positioning through superior thermal performance and regulatory compliance alignment, while legacy technologies persist in cost-constrained replacement cycles.
- LED:Solid-state illumination delivering 3,500K-5,000K color temperature with CRI above 90. Demand concentrates in German hospital modernization programs where EU MDR technical documentation requirements favor established LED optical engine suppliers with quality management infrastructure.
- Halogen:Tungsten-filament technology constrained by heat generation and energy inefficiency. Replacement demand persists in Eastern European clinics where procurement budgets lag Western European efficiency mandates.
- Xenon:High-intensity arc discharge systems with excellent color rendering. Niche applications in academic medical centers with legacy suspension arm infrastructure limit volume expansion.
- Fluorescent:Linear tube configurations with limited maneuverability. Minimal new procurement; residual demand restricted to non-surgical examination rooms in rural Indian health facilities.
Mature deployment sits with halogen and xenon systems in legacy hospital infrastructure. Newer deployment is concentrated in LED configurations across ambulatory surgical centers and German specialist clinic networks.
Application:
Procedure frequency and reimbursement structures shape illumination specification intensity across surgical specialties.
- Orthopedics:High-volume joint and fracture procedures requiring deep field penetration. Outpatient surgical centers in the United States drive fixture procurement for minor arthroscopic and soft tissue interventions.
- Dermatology:Surface-level procedures with precision color rendering requirements. Mohs surgery clinics prioritize LED configurations with adjustable color temperature for tissue margin assessment.
- Gynecology:Pelvic examination and minor procedural suites. Hospital-based women's health centers in France specify ceiling-mounted configurations with integrated video capture compatibility.
- Urology:Cystoscopy and minor endoscopic interventions. Ambulatory centers favor portable units for flexible procedure room utilization.
High-specification deployment sits with dermatology and orthopedics. Volume expansion is climbing fastest in urology as outpatient migration accelerates.
End User:
Capital availability and infrastructure permanence create distinct procurement patterns across care delivery settings.
- Hospitals:Integrated health systems with multi-year capital planning cycles. German university hospitals anchor European demand for ceiling-mounted surgical light retrofits with adaptive ambient compensation.
- Outpatient Surgical Centers:Standalone facilities optimized for procedure throughput. United States ASC networks bundle multi-site procurement to consolidate vendor relationships and service contracts.
- Clinics:Smaller-scale settings with space constraints. Battery-integrated portable configurations address structural limitations in leased medical office buildings.
- Medical Institutions:Training and research facilities with specialized requirements. Academic centers in Switzerland prioritize video integration and documentation capabilities.
Established procurement volume sits with hospital systems. Steepest expansion trajectory is gaining share fastest in outpatient surgical centers as procedure migration accelerates.
Installation Type:
Physical mounting constraints determine capital expenditure structure and operational flexibility trade-offs.
- Ceiling Mounted:Permanent suspension arm systems with integrated power and control infrastructure. German hospital retrofit programs dominate European procurement value for this configuration.
- Wall Mounted:Space-efficient alternatives for procedure rooms with ceiling obstruction. Gaining traction in older European hospital buildings with structural limitations.
- Portable:Mobile units with casters or battery power. Fastest-growing segment in United States ambulatory surgical centers where room reconfiguration flexibility governs capital decisions.
- Floor Standing:Telescoping pole-mounted fixtures for temporary deployment. Limited to emergency response and military field applications with minimal commercial volume.
Permanent infrastructure investment sits with ceiling-mounted systems. Flexible deployment is expanding most quickly in portable configurations serving space-constrained clinic environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for medical device manufacturing in Penang, Malaysia and Shenzhen, China concentrate optical component sourcing for surgical lighting supply chains. These zones attract LED die and secondary optics producers through tax holidays and duty exemptions. Procurement demand patterns diverge sharply between mature hospital retrofit markets and rapidly expanding outpatient infrastructure.
United States
Ambulatory surgical center networks in Texas and Florida drive fixture procurement for minor procedure rooms. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting outpatient migration. Dallas-Fort Worth ASC clusters anchor multi-site procurement consolidation.
Germany
Hospital modernization programs in Bavaria and North Rhine-Westphalia sustain ceiling-mounted surgical light replacement cycles. EU MDR conformity assessment through German notified bodies tightens documentation requirements for CE-marked access. Berlin-Brandenburg specialist clinic networks concentrate demand density.
China
Central government health scheme expansion into tier-2 cities creates procurement windows for mid-range LED configurations. NMPA medical device registration reforms accelerate market access for domestic manufacturers. Yangtze River Delta optical component clusters supply precision LED die production.
India
Ayushman Bharat infrastructure buildout drives demand for portable surgical lighting in tier-3 cities. CDSCO medical device rules impose quality management requirements on imported fixtures. Maharashtra medical device parks in Pune and Mumbai attract contract manufacturers.
Japan
Aging hospital infrastructure in Kansai region triggers retrofit demand for energy-efficient LED systems. METI energy efficiency mandates accelerate halogen replacement decisions. Osaka-based medical equipment distributors consolidate procurement relationships with domestic clinics.
Minor Surgical Lights Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers. The vendor base structures around three archetypes: diversified medical technology conglomerates with lighting divisions, dedicated surgical illumination specialists, and optical component suppliers backward-integrating into finished fixtures. Consolidation pressures intensify as hospital procurement committees reduce vendor fragmentation. Strategic moves center on M&A for regulatory capability acquisition and geographic expansion into outpatient-dense markets.
Among German surgical lighting specialists, S.I.M.E.O.N. Medical GmbH & Co. KG occupies a position exemplifying ceiling-mounted configuration expertise. Skytron and Stryker represent North American diversified conglomerates with channel control across ambulatory surgical center networks. These three anchors illustrate how regulatory compliance infrastructure and distribution scale separate competitive tiers.
| Leading Market Players |
|---|
| Skytron |
| A-dec Inc. |
| STERIS |
| KLS Martin Group |
| S.I.M.E.O.N. Medical GmbH & Co. KG |
| Stryker |
| Koninklijke Philips |
| Baxter |
| Getinge |
| Others |
Supply & Pricing Matrix
LED die spot prices on the Yangtze River Delta commodity index cascade through three pricing tiers as East Asian optical component concentration limits buyer leverage. Procurement committees in German university hospitals absorb premium positioning for CE-marked configurations, while Indian tier-3 clinics face extended lead times on standard-tier fixtures.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate emergency procurement from scheduled replacement cycles in hospital capital planning. Pricing stratifies across premium, standard, and economy tiers based on EU MDR certification grade and bundled multi-year service contracts. Cost compression in the mid-tier segment is intensifying because notified body capacity constraints extend conformity assessment timelines. Ambulatory surgical centers in the United States exhibit the highest price sensitivity due to fragmented ownership structures, while integrated German hospital systems leverage volume consolidation for standard-tier discounts.
Supply Chain Analysis
Refurbishment flows from German hospital retrofit programs feed secondary markets in Eastern Europe, compressing residual value for original manufacturers. Precision LED die production concentrates in China, South Korea, and Taiwan, with secondary optics clustering in Penang and Shenzhen special economic zones. Raw material dependencies include gallium nitride substrates, aluminum heat sinks, and medical-grade silicone gaskets. Single-source vulnerability in precision optical lens grinding exposes procurement to logistics volatility. Distribution runs through specialized medical equipment distributors with exclusive territorial agreements in North America and direct hospital contracts in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity in Germany and the Netherlands operates at saturation, propping pricing power for manufacturers with established technical documentation infrastructure. This supply-constrained dynamic favors incumbents with quality management systems already aligned to EU MDR Annex I requirements.
For Market Incumbents: Extend service contract bundling into multi-year maintenance agreements that lock out competitor replacement cycles. Deepen backward integration into LED optical engine production to defend margin structures against East Asian component price volatility. Prioritize CE marking pathway acceleration through pre-submission meetings with German notified bodies before capacity constraints lengthen further. For New Entrants and Emerging Players: Battery-integrated portable configurations offer a technology-first wedge into United States ambulatory surgical center networks where space constraints exclude ceiling-mounted competitors. Target clinic segments in Indian tier-2 cities where Ayushman Bharat infrastructure buildout creates procurement windows for mid-range LED systems. Pursue authorized representative partnerships with established EU MDR technical file consultants to bypass direct notified body engagement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European specialists with dormant CE marking applications awaiting notified body review in Germany. Long-term viability hinges on regulatory compliance infrastructure rather than pure optical engineering capability. Watch for inflection signals in notified body capacity expansion announcements from German and Dutch accreditation authorities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation depth separates compliant manufacturers from market access denial. |
| Hospital System Partnership | Multi-site procurement consolidation in Texas and Florida ASC networks reduces vendor fragmentation. |
| Software Companion Development | Adaptive ambient compensation algorithms differentiate ceiling-mounted configurations in German retrofits. |
| Backward Integration into LED Engines | In-house optical component production insulates margin structures from Yangtze River Delta price volatility. |
| Reimbursement Strategy | Outpatient procedure coding alignment in CMS Medicare data drives fixture specification intensity. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation guidance, and hospital procurement contract registries, complemented by interviews with biomedical engineering directors, ambulatory surgical center purchasing managers, GPO contracts specialists, and optical component procurement leads at Tier 1 manufacturers. Secondary validation drew from SEC filings of diversified medical technology conglomerates, customs records of LED die imports, and CMS Medicare outpatient procedure volume data. Bottom-up installation base modeling and top-down capital expenditure triangulation anchored market sizing.
Unit shipment and revenue projections across the analysis window reflect procedure volume migration patterns, replacement cycle compression, and regulatory transition timelines. Segmentation dimensions modeled include product type, installation configuration, application specialty, end-user setting, and regional regulatory cluster. CAGRs were derived from weighted average of historical replacement rates and forward-looking capital committee survey data. Forecast inputs incorporated EU MDR conformity assessment queue lengths and NMPA registration reform implementation pace.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwan Strait shipping lanes, abrupt FDA reclassification of surgical lighting risk categories, and pandemic-related hospital capital expenditure freezes. Forecasts reflect assumptions of stable notified body capacity and gradual halogen-to-LED transition curves. Practitioners should monitor German BfArM capacity announcements and Indian CDSCO rule harmonization progress for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Animal Operating Table Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Operating Light Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Global Steam Autoclaves Market