
 Global Mobile Operating Tables Market | 2026-2036
Global Mobile Operating Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Operating Tables Market Intelligence
Germany's precision engineering corridor is reshaping competitive dynamics in mobile operating table manufacturing. Stryker leverages integrated surgical suite ecosystems to sustain premium positioning across tertiary hospital networks. Getinge anchors European supply chains through specialized infection control-compatible table designs. Mizuho OSI competes in the Asia-Pacific theater with robotics-integrated table platforms for neurosurgical applications.
A mobile operating table constitutes a motorized, height-adjustable surgical platform engineered from stainless steel and radiolucent composites, typically supporting patient loads exceeding 225 kg while permitting C-arm fluoroscopy access without repositioning. Electric product types command structural margin pools due to programmable positioning memory and remote-control integration, whereas hybrid configurations blend hydraulic reliability with electronic precision for cost-sensitive installations. Surgical procedures represent the dominant application dimension, though ambulatory surgery centers are driving incremental demand for compact, battery-powered units with rapid turnover capability.
FDA 510(k) clearance pathways and the EU MDR conformity assessment framework govern market access, with both regulators intensifying scrutiny of electromagnetic compatibility and patient safety interlocks in powered surgical furniture. ISO 13485 quality management certification functions as a baseline procurement filter for hospital systems across OECD markets. Stakeholders must monitor how battery-powered technology segments evolve under evolving energy storage safety standards and whether antimicrobial coating claims face post-market clinical validation requirements.
Market Dynamics
Hybrid operating room proliferation is compressing replacement cycles for mobile operating tables as hospitals demand platforms compatible with intraoperative imaging and robotic surgical systems. The shift from general-purpose tables to procedure-specific configurations is redrawing procurement specifications across tertiary care networks.
Growth Catalysts
- EU MDR compliance mandates:The Medical Device Regulation's heightened electromagnetic compatibility requirements are accelerating hospital replacement of legacy hydraulic tables with certified electric platforms that integrate patient safety interlocks.
- Battery-powered mobility:Lithium iron phosphate energy storage systems are enabling cordless table operation during emergency transfers and power-outage scenarios, expanding deployment in ambulatory surgery centers lacking fixed infrastructure.
- Germany:Precision engineering clusters around Tuttlingen and Stuttgart are concentrating specialized component supply for radiolucent carbon fiber tabletops, reducing lead times for C-arm-compatible configurations.
Market Restraints
- Stainless steel price volatility:Nickel alloy input costs for table frames and bases fluctuate with commodity markets, compressing margins on mid-tier electric models where pricing power is constrained.
- Single-source dependency:High-torque linear actuator supply concentrates among German and Japanese specialist manufacturers, creating vulnerability for table OEMs lacking backward integration into motion control systems.
- ISO 13485 certification timelines:Quality management system audits for powered surgical furniture extend 12-18 months, delaying market entry for new entrants and product line extensions.
Strategic Opportunities
- India:Hospital infrastructure expansion under the Ayushman Bharat scheme is creating first-time demand for cost-optimized electric tables in tier-2 and tier-3 cities where surgical capacity is scaling rapidly.
- Antimicrobial coating convergence:Integration of copper-alloy surfaces with existing stainless steel architectures offers differentiation against healthcare-associated infection transmission without full platform redesign.
- Direct hospital contracting:Bypassing traditional medical device distributors through GPO-negotiated enterprise agreements is capturing margin previously allocated to regional sales intermediaries.
Industry Challenges
- Mechatronics engineering scarcity:Table manufacturers compete for talent capable of integrating servo motors, load sensors, and control software within Class II medical device frameworks.
- Legacy OR integration:Retrofitting programmable tables into fixed-column surgical suites requires structural floor reinforcement and electrical capacity upgrades that extend installation timelines.
- Post-market surveillance obligations:EU MDR mandates for clinical follow-up of powered patient support equipment impose ongoing data collection costs that favor established players with regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Operating Tables Market |
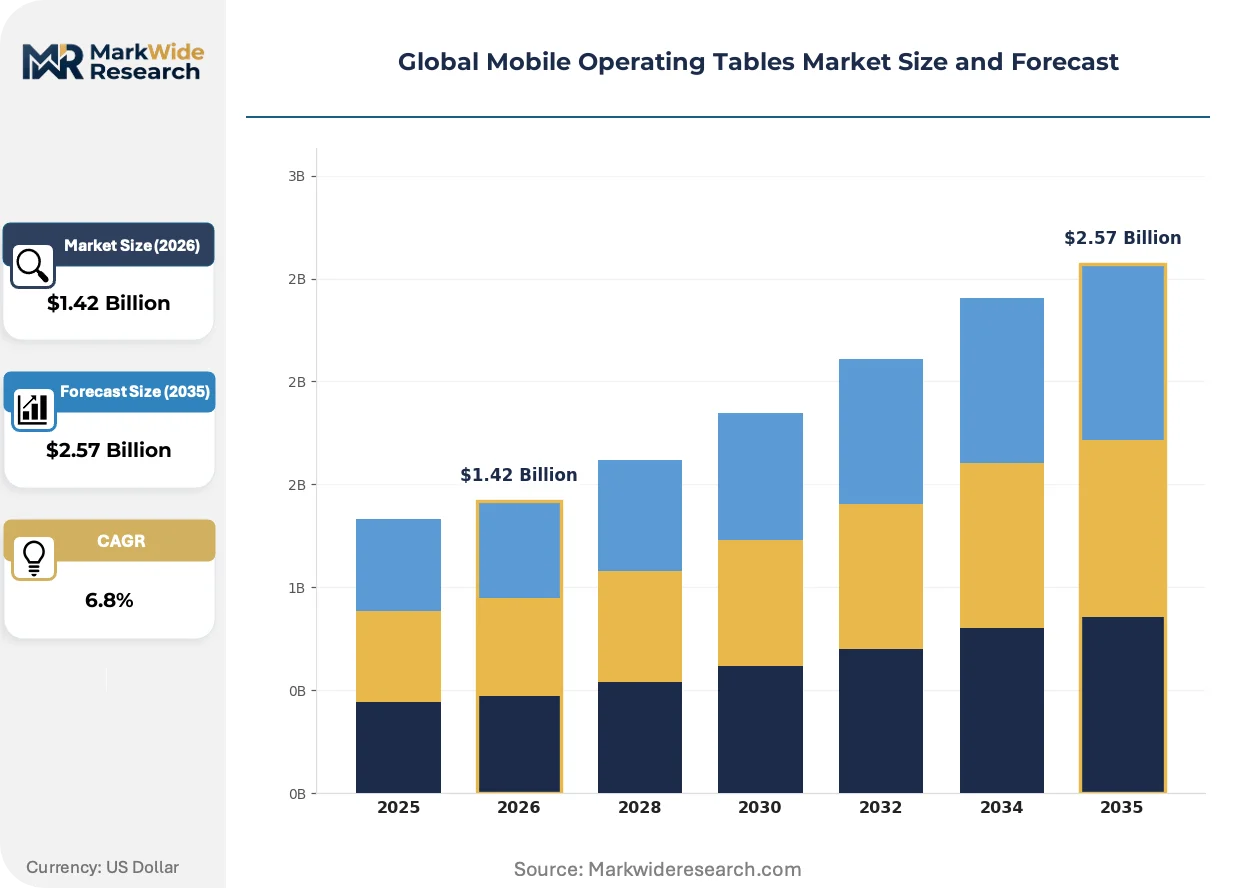
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Manual, Hybrid Application: Surgical Procedures, Emergency Care, Diagnostic Imaging, Outpatient Services, Ambulatory Surgery End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Clinics, Trauma Centers, Specialized Care Facilities Technology: Wireless Control, Adjustable Height, Tilt Functionality, Battery Powered, Anti-microbial Coating |
| Companies Covered | Stryker, Getinge, STERIS, Mizuho OSI, Skytron, Baxter, TRUMPF Medizin Systeme, Alvo Medical, Merivaara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Operating Tables Market Strategic Shifts & Innovations
Digital integration and material science advances are converging to transform mobile operating tables from passive platforms into active surgical workflow components. The next generation of products embeds sensing, connectivity, and adaptive positioning capabilities.
Radiolucent carbon fiber composite tabletops is hybridizing fluoroscopy access with structural load-bearing capacity previously achievable only with aluminum alloys. Tertiary hospital systems in the United States and Germany are specifying these configurations for spinal and orthopedic suites where intraoperative imaging is standard. The technology is hybridizing table design architectures, forcing manufacturers to maintain dual material supply chains and specialized molding capabilities.
The EU Medical Device Regulation's Unique Device Identification requirements are mandating serialized traceability for all powered surgical equipment entering European markets. Manufacturers must now embed permanent marking systems and maintain post-market surveillance databases accessible to notified bodies. Electric table platforms with integrated software logging capabilities are capturing preference as hospitals seek streamlined compliance documentation.
Consolidated procurement through integrated delivery networks is displacing decentralized purchasing authority previously held by individual surgeons and department heads. IDNs in the United States are standardizing on single-vendor surgical platform ecosystems to capture volume discounts and simplify service contracting. This concentration is most visible in multi-hospital systems across Texas and Florida where capital equipment committees now mandate interoperability with existing room control infrastructure.
Global Mobile Operating Tables Market Segmentation
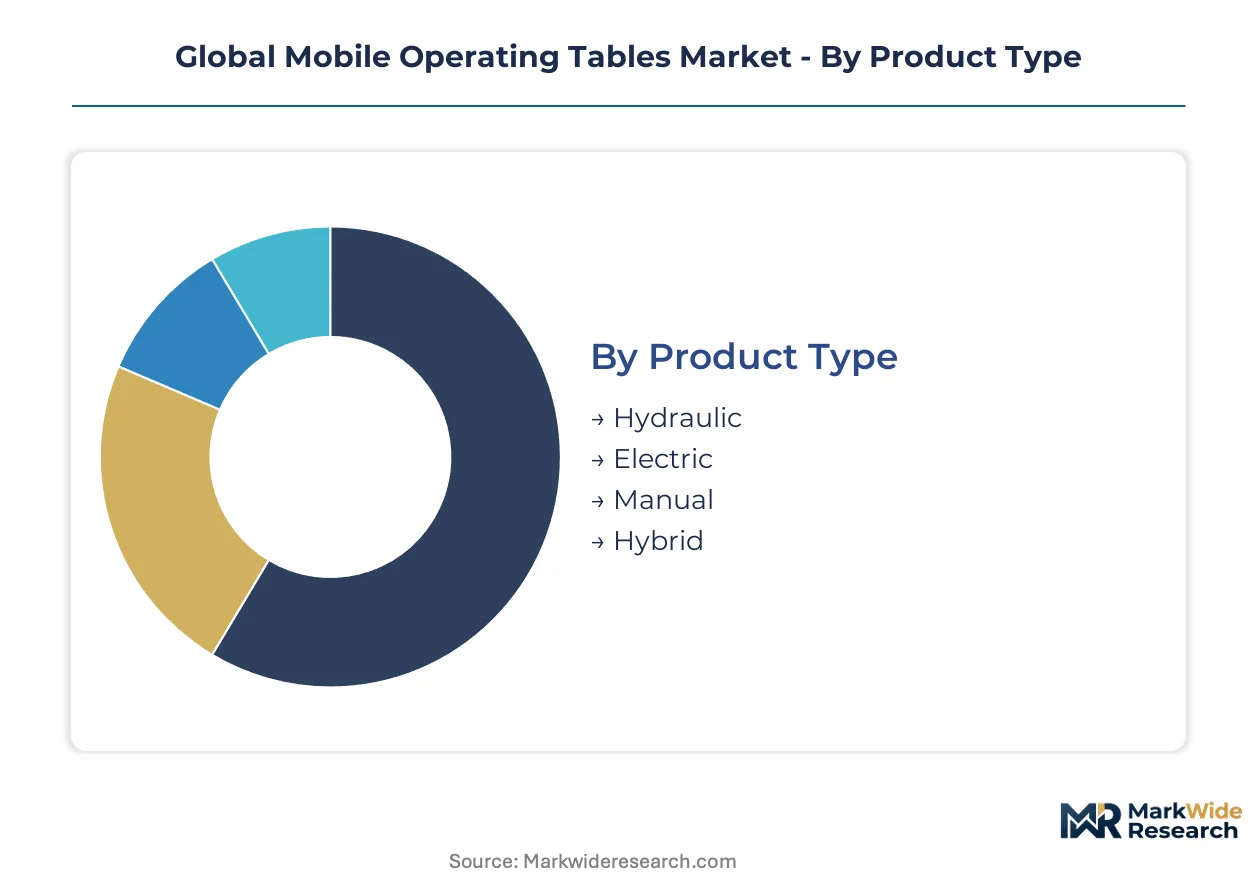
Mobile operating table segmentation reflects divergent procurement priorities across acute care networks, ambulatory facilities, and hybrid surgical environments. Product architecture, clinical application, and power modality each create distinct margin pools and compliance obligations for manufacturers navigating FDA and EU MDR pathways.
Product Type:
Mature hydraulic platforms coexist with emerging electric configurations as hospitals balance capital constraints against interoperability requirements for robotic surgical systems.
- Electric:Programmable positioning memory and remote-control integration define this segment. German hospital systems specify electric platforms for hybrid operating rooms requiring C-arm fluoroscopy compatibility and seamless integration with da Vinci surgical systems.
- Hybrid:Blending hydraulic reliability with electronic precision, these configurations target cost-sensitive installations. Demand concentrates in India's tier-2 cities where Ayushman Bharat infrastructure expansion prioritizes functional versatility over premium automation.
- Hydraulic:Legacy installations dominate secondary care facilities in Brazil and Mexico where maintenance simplicity outweighs positioning sophistication.
- Manual:Crank-operated platforms persist in resource-constrained settings across sub-Saharan Africa and rural Southeast Asia.
Electric configurations retain volume leadership in OECD markets; hybrid designs hold the steepest expansion curve across emerging economies.
Application:
Volume distribution tracks surgical specialization intensity, with procedure-specific table configurations displacing general-purpose platforms in tertiary networks.
- Surgical Procedures:General, orthopedic, and cardiac interventions drive specification complexity. United States integrated delivery networks demand weight capacities exceeding 225 kg with radiolucent tabletops for intraoperative imaging.
- Ambulatory Surgery:Compact footprints and rapid turnover capability define procurement criteria. Germany's same-day surgery expansion under DRG reimbursement reforms accelerates deployment of battery-powered units.
- Emergency Care:Trauma resuscitation bays require immediate C-arm access without patient repositioning.
- Diagnostic Imaging:MRI-compatible and CT-compatible variants serve interventional radiology suites in Japanese university hospitals.
- Outpatient Services:Minor procedure rooms in United Kingdom primary care networks prioritize cost minimization over technical sophistication.
Surgical Procedures commands installed base dominance; Ambulatory Surgery gains share fastest as same-day discharge protocols proliferate.
End User:
Procurement authority concentration varies sharply by facility type, with consolidated purchasing through integrated delivery networks reshaping vendor relationships.
- Hospitals:Tertiary and community facilities represent the anchor demand segment. Texas and Florida multi-hospital systems standardize on single-vendor surgical platform ecosystems to capture volume discounts.
- Ambulatory Surgical Centers:Freestanding facilities drive demand for compact, battery-powered configurations. California and New York ASC networks prioritize rapid room turnover over imaging compatibility.
- Trauma Centers:Level I facilities in Chicago and Phoenix specify motorized tables with immediate radiolucent access.
- Diagnostic Clinics:Imaging-focused installations in South Korea emphasize C-arm geometry optimization.
- Specialized Care Facilities:Bariatric surgery centers in Australia require reinforced load-bearing architectures.
Hospitals retain procurement volume leadership; Ambulatory Surgical Centers exhibit the most aggressive expansion trajectory.
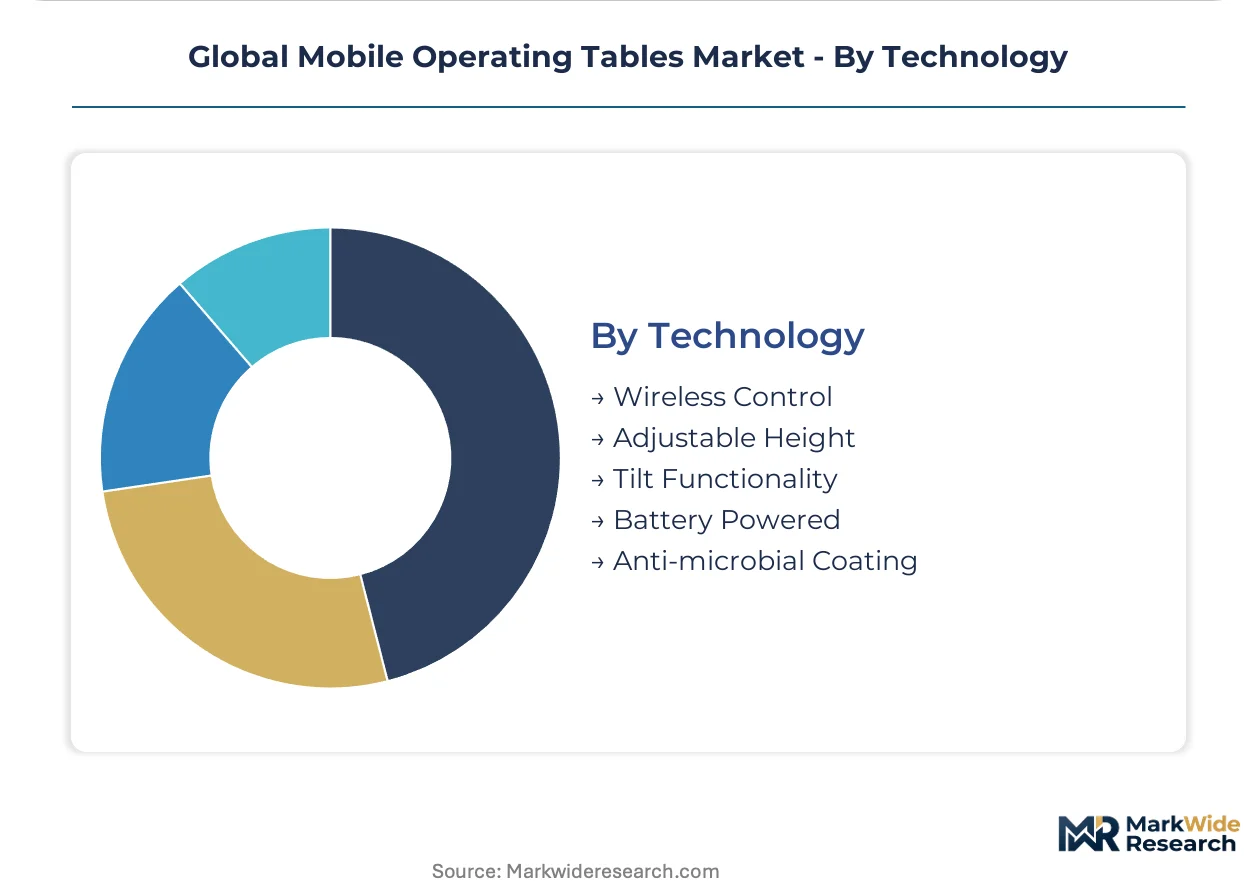
Technology:
Feature integration intensity separates premium configurations from commodity alternatives, with software-enabled capabilities capturing disproportionate margin.
- Adjustable Height:Electromechanical lift systems enabling Trendelenburg and reverse-Trendelenburg positioning constitute baseline functionality. French university hospitals specify minimum 75 cm vertical travel ranges.
- Battery Powered:Lithium iron phosphate energy storage eliminates cord dependency during emergency transfers. Swedish hospital networks deploy these for operating room flexibility and power resilience.
- Wireless Control:Bluetooth-enabled handsets and foot pedals reduce cable clutter in sterile fields.
- Tilt Functionality:Lateral tilt and longitudinal tilt specifications vary by surgical specialty.
- Anti-microbial Coating:Copper-alloy surface integration addresses healthcare-associated infection protocols under EU MDR post-market surveillance obligations.
Adjustable Height remains universal specification; Battery Powered features climb the fastest as cordless operation becomes standard in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters around Tuttlingen and Stuttgart supply critical linear actuators and radiolucent carbon fiber components to table manufacturers worldwide. This upstream concentration shapes procurement timelines and technical specifications across hospital systems in multiple continents.
United States
Integrated delivery networks in Texas and Florida drive standardization toward single-vendor surgical platform ecosystems. FDA 510(k) clearance pathways govern market entry for powered surgical furniture with intensifying scrutiny of electromagnetic compatibility. Chicago and Phoenix Level I trauma centers specify motorized tables with immediate C-arm radiolucent access for emergency interventions.
Germany
DRG reimbursement reforms accelerate same-day surgery expansion, fueling demand for battery-powered compact units in ambulatory settings. EU MDR conformity assessment frameworks mandate serialized traceability and post-market surveillance databases for all powered patient support equipment. The Tuttlingen medical technology cluster anchors specialized supply chains for high-torque electromechanical lift systems.
India
Ayushman Bharat hospital infrastructure expansion creates first-time procurement demand for cost-optimized electric tables across tier-2 and tier-3 cities. The Central Drugs Standard Control Organization regulates medical device imports and local manufacturing compliance for powered surgical equipment. Surgical capacity scaling in Karnataka and Tamil Nadu concentrates demand for hybrid hydraulic-electric configurations balancing functionality against capital constraints.
Japan
University hospital networks in Tokyo and Osaka specify robotics-integrated table platforms for neurosurgical and spinal applications. The Ministry of Health, Labour and Welfare through PMDA oversees pharmaceutical and medical device safety including powered surgical furniture. The Nagoya industrial corridor hosts precision component manufacturers supplying load sensor and servo motor subsystems to regional table OEMs.
Australia
Bariatric surgery centers in Sydney and Melbourne require reinforced load-bearing architectures exceeding standard 225 kg specifications. The Therapeutic Goods Administration administers medical device conformity assessment including electromagnetic compatibility validation for electric platforms. Victorian hospital procurement frameworks prioritize antimicrobial surface integration under healthcare-associated infection prevention protocols.
Global Mobile Operating Tables Market Key Industry Players
Integrated surgical suite providers and specialized medical furniture manufacturers split the market between ecosystem bundling and component specialization strategies. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with hospital-wide contracting power, precision engineering specialists with captive component supply, and regional fabricators serving cost-sensitive procurement channels. Competitive dynamics revolve around M&A activity consolidating service networks and strategic partnerships securing exclusive distribution through group purchasing organizations.
Among diversified medical technology conglomerates, Stryker and Getinge occupy positions anchoring premium-tier procurement through integrated surgical suite ecosystems. TRUMPF Medizin Systeme exemplifies the precision engineering specialist archetype with concentrated manufacturing in German industrial clusters. Mizuho OSI represents the robotics-integration specialist segment competing on procedure-specific platform configurations.
| Leading Market Players |
|---|
| Stryker |
| Getinge |
| STERIS |
| Mizuho OSI |
| Skytron |
| Baxter |
| TRUMPF Medizin Systeme |
| Alvo Medical |
| Merivaara |
| Others |
Cost & Logistics Intelligence
Tuttlingen's precision engineering corridor concentrates specialized manufacturing capacity for high-torque linear actuators and radiolucent carbon fiber tabletops, granting incumbent OEMs pricing power over mid-tier competitors lacking captive component supply. This upstream concentration compresses margins for electric table assemblers while premium-tier integrated suite providers extract value through hospital-wide contracting leverage.
Pricing Analysis
EU MDR dictates the pricing tier structure across European procurement channels, with certified electric platforms commanding premium positioning over legacy hydraulic alternatives. Three-tier pricing structure across premium, standard, and economy levels separates integrated surgical suite bundles from standalone table sales and basic manual configurations. Cost compression in mid-tier electric models is intensifying because nickel alloy input volatility erodes fixed-price contract viability. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraint; tertiary hospital networks demonstrate lowest sensitivity where interoperability with robotic surgical systems dominates specification.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk assessment for electromechanical subsystems sourcing. Component manufacturing draws from Germany, Japan, and China for linear actuators, load sensors, and servo motor assemblies. Raw material dependencies center on nickel-alloy stainless steel for structural frames, lithium iron phosphate cells for battery modules, and carbon fiber prepreg for radiolucent tabletops. Single-source vulnerability concentrates in high-torque actuator supply among Tuttlingen and Nagoya specialists. Distribution runs through group purchasing organizations and integrated delivery networks consolidating procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed surgical infrastructure presents a substitution threat as ceiling-mounted boom systems and integrated room architectures displace mobile platforms in new hybrid operating room construction. Incumbents must navigate this structural shift while defending installed base replacement cycles.
For Market Incumbents: Pre-empt fixed infrastructure substitution by embedding tables within comprehensive surgical suite ecosystems that lock in hospital-wide service contracts. Secure captive supply of electromechanical actuators through backward integration into Tuttlingen manufacturing clusters or exclusive supplier partnerships. Accelerate battery-powered platform development to capture ambulatory surgery center expansion before cost-optimized entrants establish footholds. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 cities where Ayushman Bharat infrastructure expansion creates first-time procurement demand without entrenched incumbent relationships. Target hybrid hydraulic-electric configurations balancing functionality against capital constraints for cost-sensitive hospital systems. Pursue direct hospital contracting models bypassing traditional distributor networks to capture margin allocated to regional sales intermediaries. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement authority concentration through integrated delivery networks favors scaled service infrastructure over fragmented vendor bases. Acquisition targets should exhibit specialized component manufacturing capabilities in electromechanical systems or established GPO contracting relationships. Monitor battery-powered technology segment share as inflection indicator for ambulatory surgery center penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Serialized traceability compliance unlocks European hospital procurement channels under tightened conformity assessment. |
| Hospital System Partnership | Enterprise agreements with Texas and Florida IDNs capture volume commitment through single-vendor standardization. |
| Backward Integration into Actuators | In-house production of high-torque lift systems mitigates single-source dependency on German and Japanese suppliers. |
| Battery Platform Development | Lithium iron phosphate integration addresses ambulatory surgery center demand for cordless operation and power resilience. |
| Software Companion Development | Integrated control logging streamlines EU MDR post-market surveillance obligations for powered patient support equipment. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and surgical suite planners and refined through secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and SEC filings of listed medical device manufacturers. Bottom-up demand modeling across product type, application, end user, and technology segments was triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning electric-hybrid-hydraulic-manual product architectures, surgical-ambulatory-emergency-diagnostic applications, and battery-powered-wireless-antimicrobial technology features. CAGRs were derived from installed base replacement cycle analysis and capacity expansion trajectories in German precision engineering clusters, incorporating nickel alloy price volatility assumptions and EU MDR compliance cost pass-through estimates.
Sensitivities concentrate around nickel commodity price swings, EU MDR audit timeline extensions, and fixed surgical infrastructure substitution rates in new hospital construction. Forecasts reflect assumptions on replacement cycle compression and ambulatory surgery center penetration without guaranteed realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Manufacturing on Demand for Medical Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Medical Automation Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Europe Medical Carts Market