
 Germany Hair Transplant Market | 2026-2036
Germany Hair Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Hair Transplant Market Insights
Post-procedure maintenance and subscription-based aftercare is consolidating as a distinct revenue layer in Germany's hair transplant industry. Novo Hair Clinic Berlin leverages its integrated follow-up protocols to sustain recurring patient engagement. KÖ-Hair Clinic Düsseldorf anchors premium positioning through specialized scalp health programs. Hattingen Hair Düsseldorf differentiates via technology leadership in robotic-assisted monitoring systems.
Germany hair transplant services encompass surgical follicular relocation procedures performed under local anesthesia, typically extracting grafts from occipital donor zones using punches between 0.7mm and 1.0mm diameter for implantation into recipient sites. The primary commercial purpose addresses androgenetic alopecia restoration while minimizing visible scarring. FUE dominates procedure volume due to shorter recovery windows, though robotic hair transplant captures margin expansion as capital-intensive automation reduces technician variability. Platelet-rich plasma therapy within the technology segment attracts out-of-pocket spend from patients seeking adjunctive growth stimulation.
German clinic licensing falls under state medical chambers (Ärztekammern) alongside federal oversight from the Federal Institute for Drugs and Medical Devices (BfArM) and EU MDR compliance requirements for surgical devices. These frameworks elevate facility standards and restrict market access for unaccredited operators. Stakeholders must monitor how BfArM guidance on robotic surgical systems evolves, as classification shifts could reshape capital deployment timelines for automated transplant platforms.
Market Dynamics
EU Medical Device Regulation (MDR) compliance requirements are compressing the German hair transplant clinic base, forcing smaller operators toward consolidation while elevating facility standards and capital barriers across the sector.
Growth Catalysts
- Young male professionals aged 26-35:This demographic cohort exhibits rising willingness to pay out-of-pocket for aesthetic restoration procedures, expanding addressable demand beyond traditional age brackets.
- FUE technique maturation:Shorter recovery windows and minimized visible scarring have elevated patient conversion rates from consultation to procedure.
- Platelet-rich plasma therapy:Adjunctive growth stimulation protocols attract incremental spend per patient while extending clinic engagement timelines.
Market Restraints
- Robotic surgical system capital intensity:Automated transplant platforms require substantial upfront investment, constraining deployment timelines for mid-tier operators.
- Federal Institute for Drugs and Medical Devices (BfArM) classification uncertainty:Evolving guidance on robotic systems creates compliance timeline risk for capital deployment decisions.
- Technician variability compression limits:Automation reduces but does not eliminate human skill dependency in graft handling and placement precision.
Strategic Opportunities
- Subscription-based aftercare models:Recurring revenue protocols for post-procedure maintenance consolidate patient lifetime value beyond single procedures.
- Berlin-Düsseldorf corridor expansion:Specialized clinic clustering near university hospitals and medical tourism infrastructure enables referral network density.
- Scalp health program integration:Preventive and therapeutic non-surgical services capture patients earlier in hair loss progression.
Industry Challenges
- Ärztekammern accreditation timelines:State medical chamber licensing procedures create operational delays for new facility openings.
- Robotic-assisted monitoring integration:Legacy clinic workflows require substantial reconfiguration to capture technology-enabled efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Hair Transplant Market |
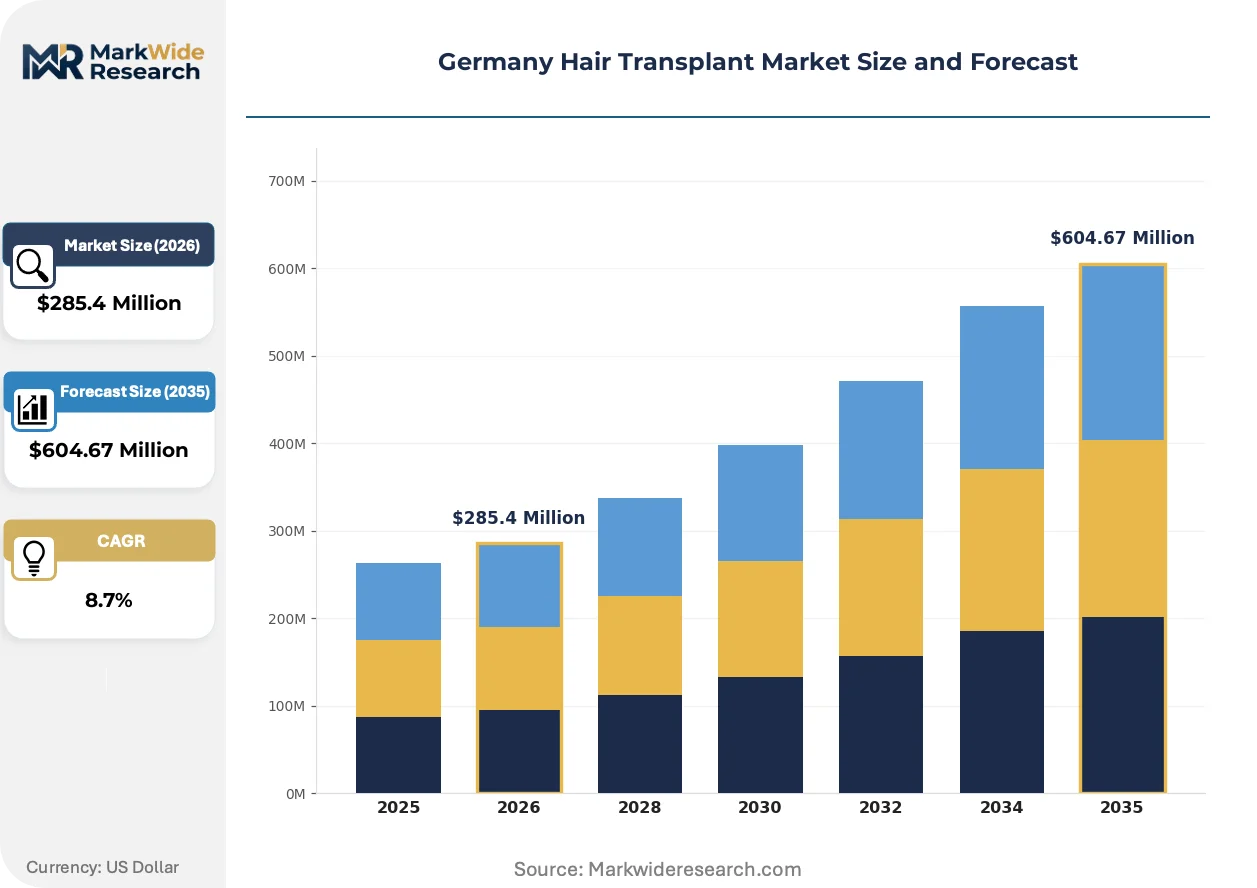
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: FUE, FUT, DHI, Robotic Hair Transplant Technology: Micrografting, Laser Therapy, Platelet-Rich Plasma, Stem Cell Therapy End User: Clinics, Hospitals, Independent Surgeons, Aesthetic Centers Age Group: 18-25, 26-35, 36-45, 46+ |
| Companies Covered | AQ Clinics Frankfurt, Novo Hair Clinic Berlin, Novohair Clinic Berlin, Otberg Medical Berlin, Munich Hairtransplant Munich, Trichomed Clinic Berlin, Hattingen Hair Düsseldorf, My Perfect Hair Clinic Berlin, KÖ-Hair Clinic Düsseldorf, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Hair Transplant Market Trends and Innovations
Automation and regulatory compression are restructuring how German hair transplant clinics compete, with technology deployment and compliance architecture becoming primary differentiation vectors rather than marketing or pricing alone.
Robotic-assisted follicular unit extraction is decentralizing procedure volume from high-volume metropolitan centers toward mid-tier clinics that can now match graft placement consistency. Young male professionals aged 26-35 drive adoption velocity as this demographic prioritizes outcome predictability over clinic brand heritage. The technology is decentralizing competitive advantage away from surgeon reputation toward capital-access and protocol standardization.
German Medical Devices Act (MPG) alignment with EU MDR elevates surgical device traceability and post-market surveillance obligations. Clinic operators must now maintain enhanced documentation for implantable devices and automated systems. Berlin and Düsseldorf facilities face the steepest compliance adaptation curves given their higher procedure volumes and device variety.
After-sales service unbundling reshapes patient relationship economics as clinics separate procedure fees from maintenance subscriptions. Specialized scalp health programs replace bundled follow-up care with tiered engagement options. This pattern concentrates in Düsseldorf where premium positioning supports service stratification.
Germany Hair Transplant Market Segmentation
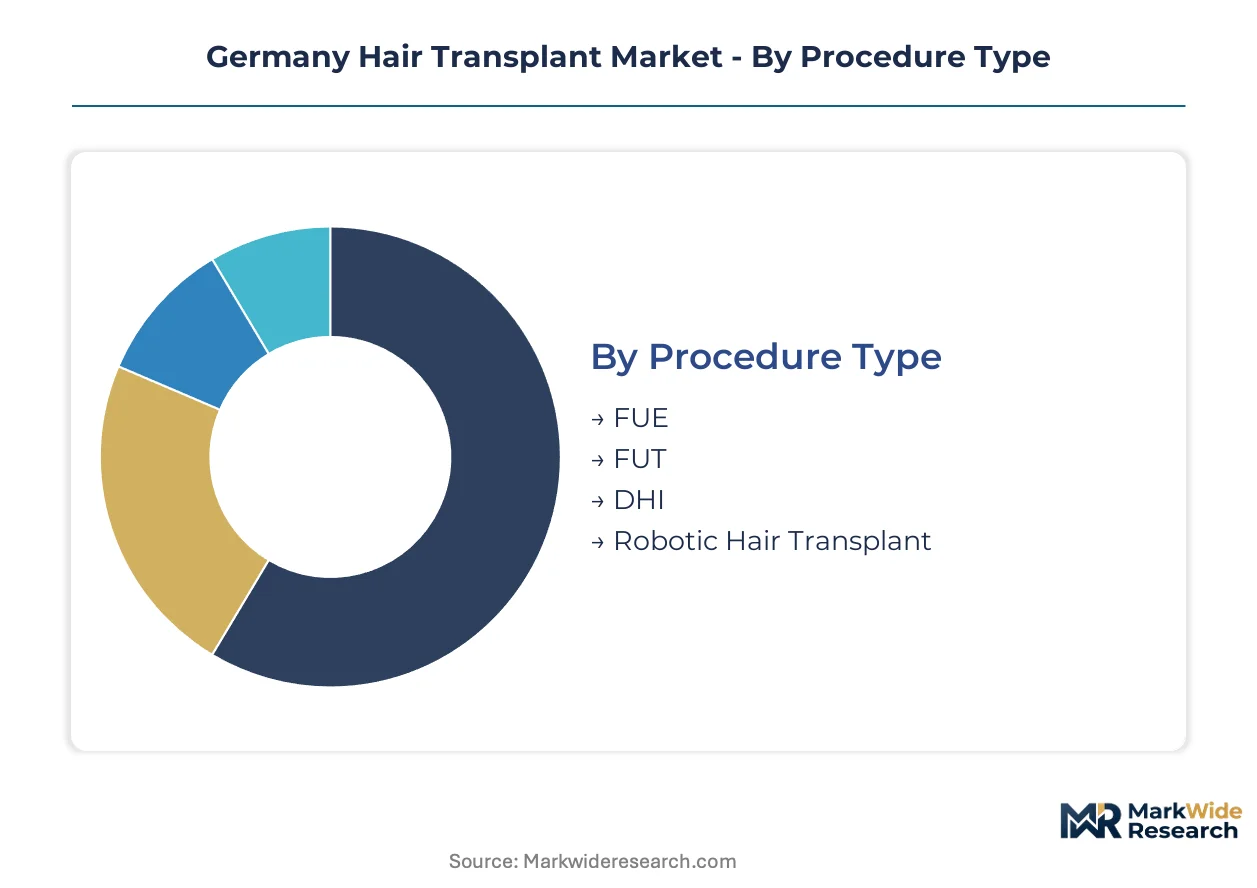
Procedure mix and technology deployment patterns in Germany's hair transplant sector reveal how capital intensity and regulatory compliance reshape competitive positioning across distinct patient and provider categories.
Procedure Type:
Supply concentration in metropolitan clinic clusters favors capital-light techniques for volume scaling while reserving automated systems for premium positioning.
- FUE:Follicular unit extraction removes individual grafts using 0.7mm to 1.0mm diameter punches from occipital donor zones, enabling discrete scarring and faster recovery. Berlin clinics deploy this technique for 26-35 year-old professionals seeking minimal downtime between procedures and return to work.
- Robotic Hair Transplant:Automated follicular unit extraction systems utilize stereoscopic vision and precision robotics to standardize graft harvesting and placement. Düsseldorf facilities absorb the capital intensity to attract patients prioritizing outcome predictability over surgeon reputation heritage.
- FUT:Follicular unit transplantation harvests donor tissue strips for microscopic dissection into grafts, suited for patients requiring maximum graft counts in single sessions.
- DHI:Direct hair implantation employs specialized Choi implanter pens to place grafts without recipient site pre-incision, reducing scalp trauma and healing intervals.
Today's leader: FUE. Tomorrow's challenger: Robotic Hair Transplant.
Technology:
Adjunctive therapy integration separates bundled procedure pricing from recurring revenue protocols across German clinic networks.
- Platelet-Rich Plasma:Autologous blood concentrate injections stimulate follicular growth through growth factor release. Düsseldorf premium clinics package PRP into subscription aftercare models for sustained patient engagement beyond initial surgery.
- Micrografting:Precision follicular unit placement techniques achieve natural hairline density and directional flow. Berlin university-adjacent clinics leverage micrografting expertise to anchor referral networks from dermatology departments.
- Laser Therapy:Low-level laser devices deliver photobiomodulation to dormant follicles as non-surgical maintenance intervention.
- Stem Cell Therapy:Experimental protocols utilizing adipose-derived or follicular stem cells remain investigational under BfArM oversight with restricted commercial deployment.
Adjunctive revenue concentrates in Platelet-Rich Plasma. Regulatory pathway uncertainty constrains Stem Cell Therapy expansion timelines.
End User:
Facility type determines compliance architecture complexity and capital access for technology acquisition under EU MDR and MPG frameworks.
- Clinics:Specialized hair restoration facilities concentrate procedure volume in Berlin and Düsseldorf corridor locations near university hospitals and medical tourism infrastructure.
- Hospitals:Academic medical centers integrate transplant services within dermatology or plastic surgery departments, leveraging Ärztekammern accreditation for complex reconstruction cases.
- Independent Surgeons:Solo practitioners face escalating EU MDR compliance costs and device traceability obligations that compress operational viability.
- Aesthetic Centers:Multi-service cosmetic facilities add hair transplant procedures to service portfolios, competing on convenience rather than surgical specialization depth.
Consolidation pressure targets Independent Surgeons. Aesthetic Centers capture price-sensitive volume without surgical depth investment.
Age Group:
Demographic segmentation maps directly to payment willingness and intervention timing across hair loss progression stages.
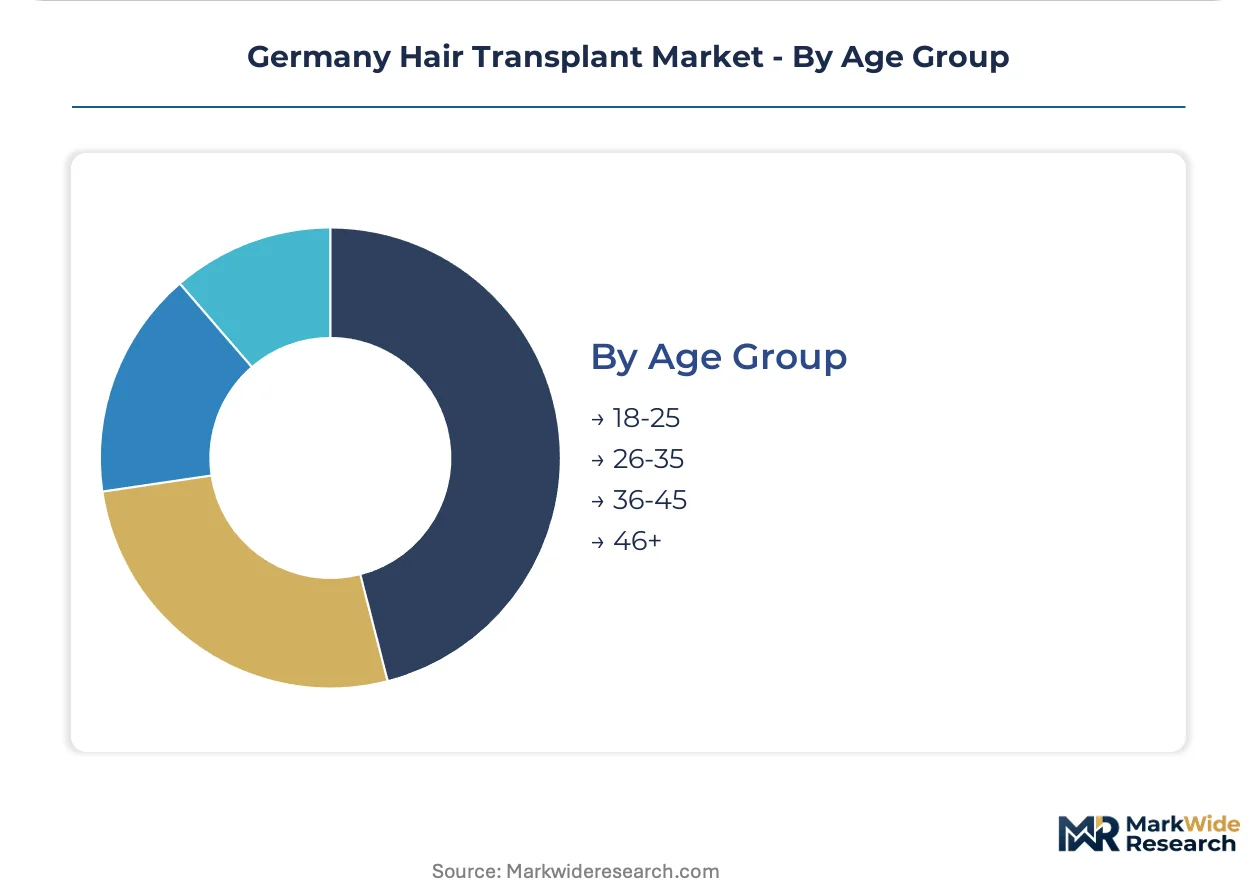
- 26-35:Young male professionals exhibit highest out-of-pocket payment propensity for aesthetic restoration, expanding addressable demand beyond traditional patient profiles. This cohort drives FUE adoption velocity and robotic system acceptance.
- 36-45:Mid-career patients present established androgenetic alopecia patterns requiring comprehensive graft counts and combination therapy protocols.
- 18-25:Early intervention seekers pursue preventive measures and conservative graft placement with long-term maintenance planning.
- 46+:Late-stage candidates prioritize scalp coverage maximization over hairline refinement, often combining transplant with medical therapy.
Revenue growth concentrates in 26-35 segment. 46+ maintains procedure volume stability through restorative necessity rather than discretionary choice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher per-procedure pricing than neighboring markets, while Turkey attracts volume-driven medical tourism with lower-cost alternatives. This divergence shapes how German clinics compete on quality assurance rather than price.
Bavaria
Munich Hairtransplant anchors surgical volume in this southern state, where affluent patient demographics sustain premium FUE pricing. The Bavarian State Ministry of Health enforces Ärztekammern licensing standards that exceed federal baselines. Munich's concentration of private dermatology practices generates referral density for specialized restoration services.
North Rhine-Westphalia
Düsseldorf hosts Hattingen Hair and KÖ-Hair Clinic, clustering robotic system deployment near medical tourism infrastructure. The state's economic ministry promotes healthcare service exports through trade fair presence at MEDICA. The Rhine-Ruhr metropolitan corridor concentrates Germany's highest transplant procedure density outside Berlin.
Berlin-Brandenburg
Novo Hair Clinic Berlin and Trichomed Clinic Berlin compete for young professional patients aged 26-35 seeking minimal-downtime procedures. The Berlin Senate Department for Health monitors EU MDR implementation timelines for surgical device compliance. University hospital adjacencies in Charlottenburg and Mitte enable academic referral networks.
Hesse
Frankfurt's AQ Clinics captures financial sector professionals with discretionary aesthetic spending capacity. The Hessian Ministry of Social Affairs coordinates with BfArM on robotic surgical system classification guidance. The Frankfurt-Rhine-Main economic region supports outpatient surgical facility expansion through commercial real estate availability.
Hamburg
Northern Germany's commercial hub sustains mid-tier clinic operations serving patients from Schleswig-Holstein and Lower Saxony. The Hamburg Authority for Health and Consumer Protection inspects facility compliance with MPG sterilization protocols. The city's port infrastructure supports medical device import logistics for automated transplant platforms.
Germany Hair Transplant Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with metropolitan clinic networks consolidating position while independent surgeons face compliance-driven attrition. The German market exhibits tiered concentration: Düsseldorf and Berlin anchor premium robotic-assisted services, secondary cities host FUE volume operations, and rural areas show clinic scarcity. Three archetypes dominate—university-affiliated academic centers, technology-forward robotic adopters, and subscription-aftercare integrators. Consolidation pressure and M&A activity target independent practitioners unable to absorb EU MDR compliance costs, while geographic expansion concentrates new facility openings in the Berlin-Düsseldorf corridor.
Among Berlin-based operators, Novo Hair Clinic Berlin and Trichomed Clinic Berlin exemplify the metropolitan network archetype, occupying positions near university hospital infrastructure that sustains referral density. Hattingen Hair Düsseldorf and KÖ-Hair Clinic Düsseldorf represent the technology-forward tier, anchoring robotic system deployment in Germany's medical tourism gateway city. These named entities illustrate how capital access and regulatory compliance architecture determine competitive viability more than historical surgeon reputation.
| Leading Market Players |
|---|
| AQ Clinics Frankfurt |
| Novo Hair Clinic Berlin |
| Novohair Clinic Berlin |
| Otberg Medical Berlin |
| Munich Hairtransplant Munich |
| Trichomed Clinic Berlin |
| Hattingen Hair Düsseldorf |
| My Perfect Hair Clinic Berlin |
| KÖ-Hair Clinic Düsseldorf |
| Others |
Pricing and Supply Chain Analysis
Horizontal consolidation among Düsseldorf and Berlin clinic networks anchors supply concentration and pricing power, as multi-facility operators capture economies of scale in robotic system deployment and EU MDR compliance architecture that smaller independents cannot replicate.
Pricing Analysis
Capacity additions in Berlin are reshaping price floors for FUE procedures as Novo Hair Clinic Berlin and Trichomed Clinic Berlin expand metropolitan footprint. Three-tier pricing structure across premium robotic-assisted, standard FUE, and economy FUT levels separates patients by outcome predictability demands and aftercare bundling intensity. Pricing pressure stems from Turkey's medical tourism inflows, which compress margins on price-sensitive volume. Young professionals aged 26-35 exhibit lowest price sensitivity, prioritizing minimal downtime and technology assurance over absolute cost.
Supply Chain Analysis
Robotic surgical system supply rests on South Korean and US precision automation producers, with stereoscopic vision components drawing from Japanese optical manufacturers. Punch tools and extraction devices source from German surgical instrument specialists certified under EU MDR traceability protocols. Single-source vulnerability concentrates in robotic arm servo motors, where replacement timelines extend procedure scheduling windows. Distribution runs through manufacturer-direct sales to accredited clinic networks, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's hair transplant sector functions as a regulatory compounder where EU MDR compliance milestones accelerate clinic consolidation and elevate capital barriers for new entrants.
For Market Incumbents: Cement market position through backward integration into robotic system maintenance capabilities and captive aftercare subscription platforms. Consolidation pressure from Ärztekammern accreditation timelines favors acquiring independent surgeons facing compliance cost absorption limits. Priority lever rests on locking Berlin-Düsseldorf corridor real estate near university hospital referral networks before competitor facility saturation. For New Entrants and Emerging Players: Enter via white-space targeting in Hamburg and Frankfurt, where mid-tier FUE volume gaps exist between established Berlin-Düsseldorf dominance and rural clinic scarcity. The 18-25 preventive intervention segment offers lowest competitive density, with scalp health program anchoring as the viable go-to-market angle before surgical service expansion. For Investors and Strategic Acquirers: Roll-up economics work for technology-forward clinic networks because EU MDR compliance costs disproportionately burden solo practitioners and create forced sellers. Long-term viability centers on platforms with robotic system deployment and subscription aftercare infrastructure already operational. Signal to watch: BfArM classification guidance shifts on automated surgical platforms, which would accelerate capital deployment timelines for compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic System Deployment | Automated follicular extraction standardizes graft quality and reduces technician variability for outcome-predictable positioning. |
| Subscription Aftercare Integration | Recurring revenue protocols extend patient lifetime value beyond single procedures and reduce acquisition cost dependency. |
| EU MDR Compliance Certification | Enhanced device traceability and post-market surveillance obligations elevate facility standards and compress unaccredited competitors. |
| University Hospital Partnership | Academic referral networks in Charlottenburg and Mitte anchor premium patient flow and dermatology department collaboration. |
| Scalp Health Program Launch | Preventive non-surgical services capture patients earlier in hair loss progression and build surgical pipeline conversion. |
Research Methodology
Bottom-up procedure volume modeling reconciled against top-down clinic capacity tracking forms the analytical core, combining primary interviews with clinic operators, biomedical engineers, GPO contracts managers, and BfArM regulatory specialists against secondary validation from EU MDR filing databases, Ärztekammern accreditation registries, and hospital procurement contract disclosures.
Historical trendline analysis of FUE and robotic procedure adoption patterns calibrated segmentation dimensions across technique type, technology deployment, facility category, and age cohort demand profiles. CAGRs derive from installed base expansion rates for automated systems and patient consultation-to-procedure conversion tracking. Forecast inputs incorporate BfArM regulatory pathway timelines and medical tourism flow elasticity to Turkish competitors.
Inputs from clinic operator interviews and EU MDR filing databases were available through the study window; gaps in real-time robotic system utilization rates introduce uncertainty bands around capacity expansion assumptions. Forecasts reflect modeled assumptions on regulatory compliance cost absorption and patient demographic shift velocity. Material deviation in BfArM classification guidance or Turkey-EU medical tourism policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Australia Laser Hair Removal Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market