
 New-Born Screening Equipment Market | 2026-2036
New-Born Screening Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
New-Born Screening Equipment Market Outlook
Hospital procurement of integrated screening platforms is hardening as health systems consolidate newborn testing into centralized laboratory workflows. PerkinElmer Inc leverages its long-standing installed base in tandem mass spectrometry to sustain recurring reagent revenue streams. Thermo Fisher Scientific anchors its position through in-house production of PCR and next-generation sequencing chemistries that feed directly into screening protocols. Bio-Rad Laboratories competes by specializing in dried blood spot automation and quality control systems that laboratories depend on for reproducible results.
New-born screening equipment encompasses analytical instruments, assay kits, and data management systems designed to detect metabolic, genetic, and congenital disorders from blood spots, hearing tests, and pulse oximetry within the first days of life. These systems typically process 3.2 mm dried blood spot punches through automated punchers coupled to tandem mass spectrometers operating at 0.1 Da mass accuracy, with throughput demands of 500–2,000 samples daily in high-volume reference laboratories. Spectrometry-based metabolic panels still occupy the largest revenue share given their entrenched role in phenylketonuria and fatty acid oxidation disorder detection, though next-generation sequencing is displacing single-analyte workflows as multiplex gene panels drop in cost. Hearing test equipment represents a mature segment with stable replacement cycles, while pulse oximetry for critical congenital heart defects shows faster expansion tied to point-of-care adoption in delivery rooms.
FDA oversight of in vitro diagnostic devices and CLIA laboratory certification requirements shape product development timelines and commercial access in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked screening assays entering European markets. WHO newborn screening guidelines influence procurement priorities in middle-income health systems seeking external validation for program expansion. Stakeholders must monitor how regulatory divergence between FDA and EMA post-market surveillance requirements affects instrument validation costs and geographic launch sequencing.
Market Dynamics
Hospital consolidation of newborn testing into centralized laboratory workflows is hardening procurement patterns around integrated multiplex platforms, compressing vendor margins while locking in long-term reagent contracts.
Growth Catalysts
- Panel Expansion Mandates:The FDA's expansion of the Recommended Uniform Screening Panel drives mandatory adoption of expanded metabolic and genetic testing protocols across US birthing facilities.
- China's National Health Commission:Population-wide screening mandates in tier-one cities are scaling procurement of tandem mass spectrometry systems for phenylketonuria detection.
- Next-Generation Sequencing:Multiplex gene panels are dropping in cost-per-test, enabling replacement of single-analyte workflows with comprehensive genomic screening platforms.
Market Restraints
- Reagent Cost Volatility:Specialized chemistries for tandem mass spectrometry and PCR assays concentrate pricing power with a limited supplier base in Western Europe.
- EMA Post-Market Surveillance:Stricter clinical evidence standards under the EU In Vitro Diagnostic Regulation extend validation timelines and raise instrument certification costs.
- Technical Throughput Ceilings:Dried blood spot automation systems face physical limits on daily sample processing that constrain laboratory expansion without parallel unit deployment.
Strategic Opportunities
- Point-of-Care Pulse Oximetry:Critical congenital heart defect screening in delivery rooms represents underpenetrated deployment of portable diagnostic devices outside centralized labs.
- Data Management Convergence:Integration of laboratory information systems with electronic health records creates white space for platform vendors offering end-to-end workflow solutions.
- WHO Guideline Adoption:Middle-income health systems in Southeast Asia and Latin America are using WHO newborn screening guidelines to justify program expansion funding.
Industry Challenges
- CLIA Personnel Requirements:High-complexity laboratory certification demands specialized technologist training that outpaces workforce pipeline capacity in rural US markets.
- Legacy System Interoperability:Integration of new sequencing platforms with existing tandem mass spectrometry infrastructure requires custom middleware development and extended validation periods.
- Cross-Border Regulatory Divergence:Divergent FDA and EMA validation requirements force vendors to maintain parallel quality management systems, duplicating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New-Born Screening Equipment Market |
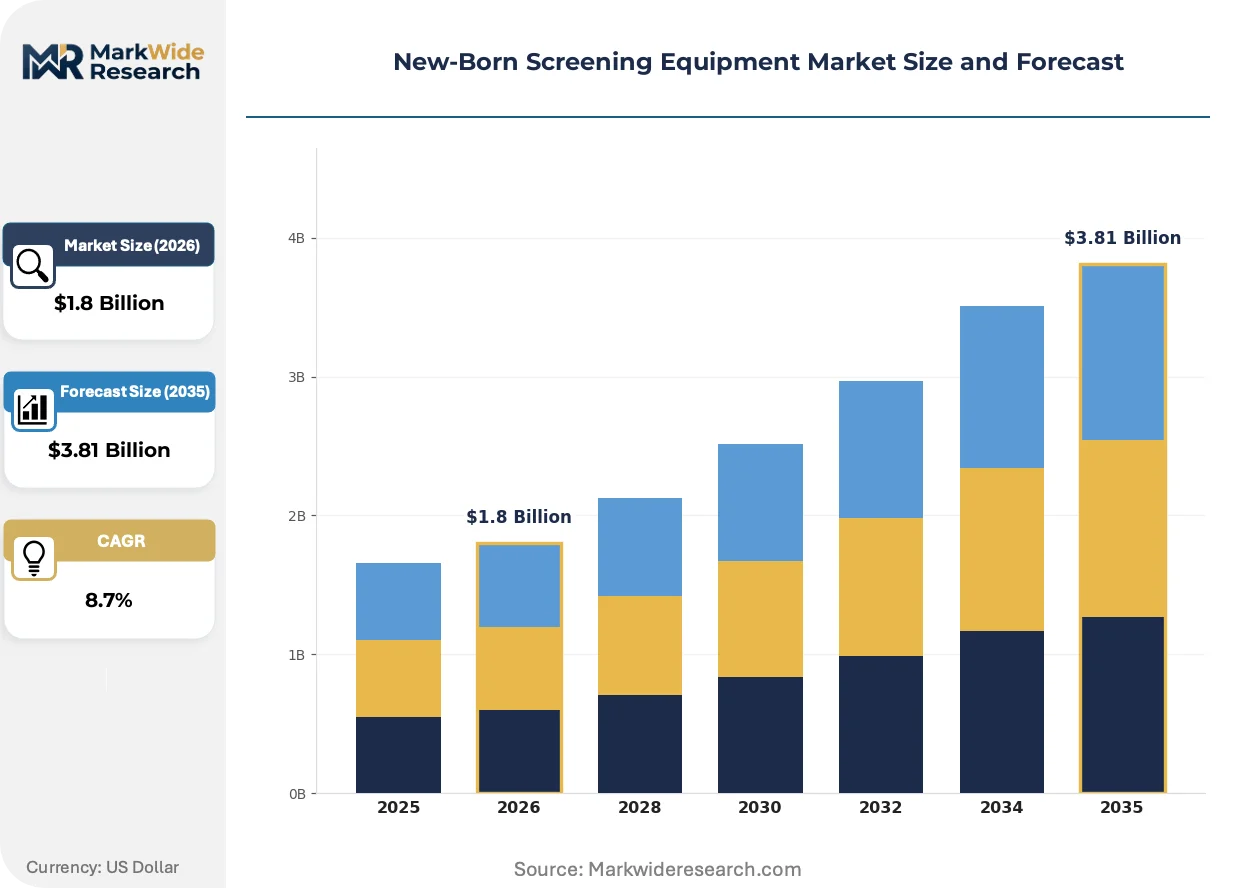
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Spot Test, Genetic Test, Hearing Test, Pulse Oximetry End User: Hospitals, Clinics, Laboratories, Pediatrician Offices Technology: Spectrometry, Immunoassay, PCR, Next-Generation Sequencing Application: Metabolic Disorders, Congenital Disorders, Hearing Impairment, Critical Congenital Heart Defects |
| Companies Covered | Bio-Rad Laboratories, PerkinElmer Inc, Agilent Technologies, Waters Corporation, Natus Medical, Thermo Fisher Scientific, AB SCIEX, Masimo, Trivitron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New-Born Screening Equipment Market Strategic Shifts
Next-generation sequencing platforms are actively compressing the cost structure of genetic disorder detection while hearing test equipment enters stable replacement cycles. Three forces are reshaping competitive positioning.
Multiplex gene panels are overtaking single-analyte tandem mass spectrometry workflows for fatty acid oxidation disorder detection. High-volume reference laboratories in the United States and Germany are adopting these platforms at accelerated replacement cycles. This shift is compressing reagent revenue per test while expanding total addressable panel breadth.
The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked screening assays entering European markets. Manufacturers must now generate prospective performance data rather than relying on literature-based submissions. Pediatric reference laboratories in France and Germany are extending procurement timelines to accommodate vendor re-certification efforts.
Health system consolidation is compressing vendor sales cycles into centralized procurement frameworks that bundle instruments, reagents, and service contracts. Group purchasing organizations are displacing direct hospital negotiations in the United States. This pattern is most visible in integrated delivery networks across Texas and California, where newborn screening contracts now span multiple birthing facilities under single vendor relationships.
New-Born Screening Equipment Market Segmentation
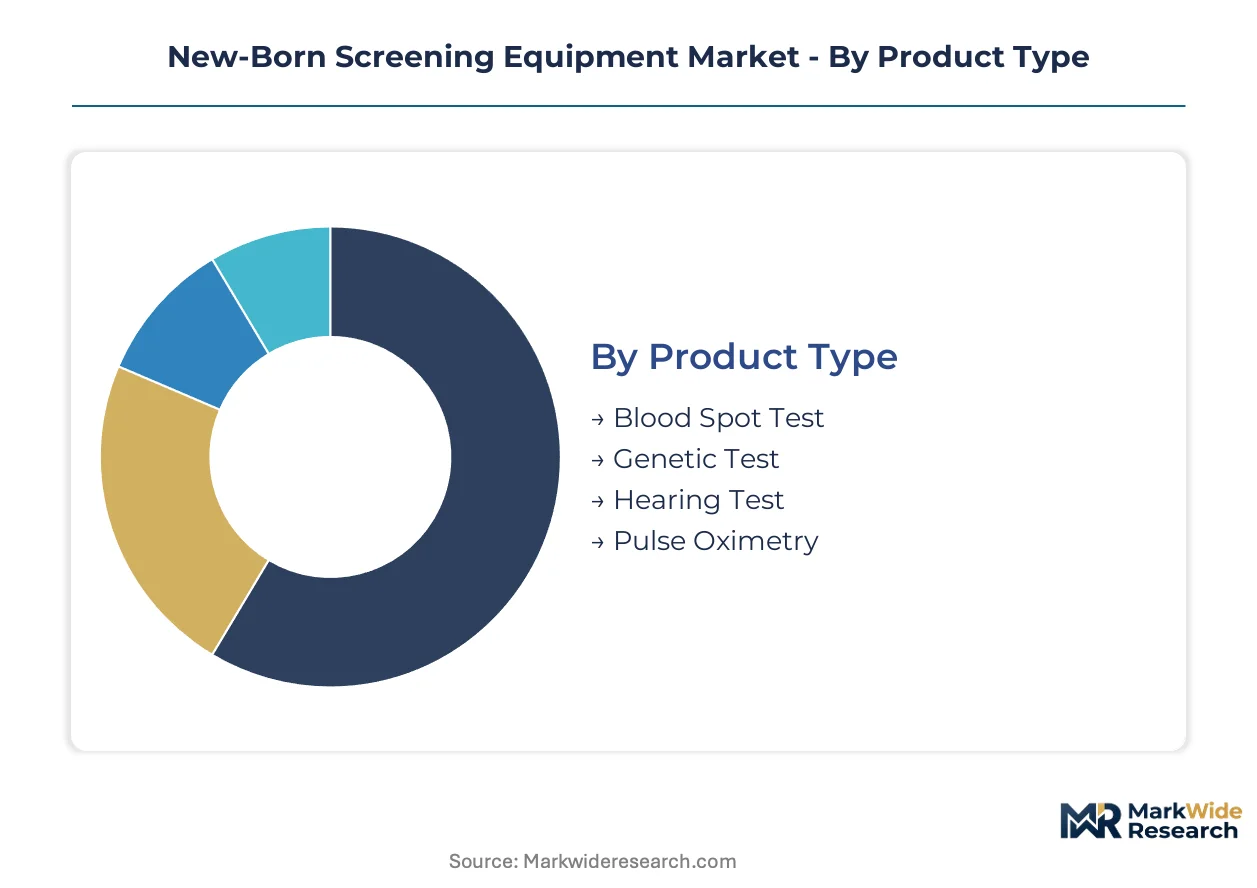
New-born screening equipment segments diverge sharply by clinical workflow integration and regulatory validation burden. Procurement patterns cluster around platforms that consolidate multiple test modalities into centralized laboratory infrastructure.
Product Type:
Hospital laboratory directors prioritize platforms by throughput capacity and reagent contract flexibility when selecting screening modalities.
- Blood Spot Test:Dried blood spot cards punched at 3.2 mm diameter feed tandem mass spectrometry systems detecting phenylketonuria and fatty acid oxidation disorders. Demand concentrates in high-volume reference laboratories across Germany and the United States where state mandates require universal metabolic screening within 48 hours of birth.
- Genetic Test:Multiplex gene panels analyze DNA extracted from blood spots for cystic fibrosis and spinal muscular atrophy variants. Laboratories in China are scaling procurement as the National Health Commission expands mandatory genetic screening protocols in tier-one cities.
- Hearing Test:Automated auditory brainstem response and otoacoustic emission equipment screens for congenital hearing loss. Replacement cycles dominate purchasing in mature markets.
- Pulse Oximetry:Portable sensors measure oxygen saturation for critical congenital heart defect detection. Point-of-care deployment in delivery rooms drives fastest expansion outside centralized laboratory workflows.
Volume sits with blood spot testing; growth tilts toward genetic test platforms.
End User:
Facility scale and CLIA certification status determine instrument complexity thresholds and service contract structures.
- Hospitals:Birthing facilities with level III neonatal intensive care units process 500–2,000 samples daily through integrated platforms. Consolidated procurement across integrated delivery networks in Texas and California bundles instruments with multi-year reagent supply agreements.
- Laboratories:State public health laboratories and commercial reference labs operate high-complexity workflows requiring specialized technologist training. Workforce pipeline constraints in rural US markets limit expansion.
- Clinics:Outpatient facilities perform preliminary hearing screening and pulse oximetry before referral. Equipment specifications emphasize portability over throughput.
- Pediatrician Offices:Private practices conduct follow-up confirmatory testing for abnormal screening results. Lower sample volumes favor compact, semi-automated systems.
Procurement volume clusters with hospitals; pediatrician offices expand most quickly as decentralized follow-up networks mature.
Technology:
Platform selection hinges on panel breadth requirements versus per-test cost constraints across metabolic and genetic screening protocols.
- Spectrometry:Tandem mass spectrometry operating at 0.1 Da mass accuracy remains the analytical backbone for metabolic disorder detection. Entrenched installed bases generate recurring reagent revenue streams.
- Next-Generation Sequencing:Multiplex gene panels displace single-analyte workflows as cost-per-test declines. High-volume laboratories in the United States and Germany accelerate replacement cycles.
- PCR:Polymerase chain reaction chemistries detect specific genetic variants with rapid turnaround. In-house production capabilities anchor vendor positioning.
- Immunoassay:Enzyme-linked immunosorbent assays screen for thyroid-stimulating hormone and other endocrine markers. Mature technology with stable replacement demand.
Revenue concentrates in spectrometry; steepest expansion trajectory belongs to next-generation sequencing.
Application:
Mandatory screening panel composition varies by national health authority guidelines, directly shaping equipment procurement specifications.
- Metabolic Disorders:Phenylketonuria, fatty acid oxidation disorders, and amino acidopathies require tandem mass spectrometry analysis of blood spot metabolite profiles. WHO guideline adoption in middle-income health systems drives program expansion funding.
- Critical Congenital Heart Defects:Pulse oximetry screening in delivery rooms detects hypoplastic left heart syndrome and other structural anomalies before discharge. Underpenetrated deployment outside centralized laboratories creates white space for portable device vendors.
- Congenital Disorders:Expanded panels incorporate cystic fibrosis, sickle cell disease, and severe combined immunodeficiency testing. Panel breadth varies by state and national mandate.
- Hearing Impairment:Universal newborn hearing screening programs operate in over 40 countries with stable equipment replacement cycles. Technology maturity limits pricing flexibility.
Metabolic disorder screening commands installed base volume; critical congenital heart defect detection climbs fastest as point-of-care adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in Germany and the United States, while procurement demand scales fastest in China and tier-one Asian cities. Consumption patterns diverge between mature screening programs in Western Europe and rapidly expanding mandates in middle-income health systems.
United States
State-level expansion of the Recommended Uniform Screening Panel drives tandem mass spectrometry procurement across birthing facilities. FDA oversight of in vitro diagnostic devices and CLIA laboratory certification requirements shape vendor market access timelines. Texas and California integrated delivery networks consolidate newborn screening contracts across multiple facilities under centralized procurement frameworks.
Germany
Pediatric reference laboratories in Bavaria and North Rhine-Westphalia operate high-throughput metabolic screening workflows requiring 0.1 Da mass accuracy instrumentation. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked assays, extending vendor re-certification periods. Berlin-Brandenburg health authorities coordinate national quality control protocols for dried blood spot automation systems.
China
The National Health Commission mandates population-wide phenylketonuria screening in tier-one cities, scaling procurement of tandem mass spectrometry platforms. NMPA regulatory pathways for in vitro diagnostic devices accelerate approval timelines for domestic manufacturers. Shanghai and Beijing municipal health bureaus pilot expanded genetic screening panels for spinal muscular atrophy detection.
Japan
METI industrial policy supports domestic production of analytical instrumentation for newborn screening applications. PMDA regulatory harmonization with international standards facilitates importation of multiplex testing platforms from Western vendors. The Kanto region around Tokyo hosts concentrated demand from university-affiliated pediatric hospitals operating centralized laboratory workflows.
India
State governments in Maharashtra and Karnataka pilot universal newborn hearing screening programs using automated auditory brainstem response equipment. CDSCO medical device regulations govern importation of pulse oximetry systems for critical congenital heart defect detection. Mumbai and Bangalore pediatric hospital networks expand metabolic screening capacity through public-private partnership models.
New-Born Screening Equipment Market Competitive Environment
Top-tier vendors anchor the spectrometry and sequencing instrumentation tier, while mid-scale specialists concentrate in dried blood spot automation and point-of-care diagnostics. The vendor base stratifies across three archetypes: integrated life science conglomerates with in-house chemistry production, precision instrument manufacturers with entrenched installed bases, and emerging specialists in portable screening devices. Consolidation pressures favor vendors offering bundled instrument-reagent-service contracts. Geographic expansion and technology licensing represent the dominant competitive vectors as health systems centralize procurement.
Among diversified life science conglomerates, Thermo Fisher Scientific and PerkinElmer Inc exemplify the integrated platform archetype through captive supply of analytical chemistries and data management systems. Bio-Rad Laboratories occupies a position within the quality control and automation specialist tier, representing vendors that laboratories depend upon for reproducible dried blood spot processing. These three companies illustrate the competitive structure: scale-driven conglomerates with vertical chemistry integration versus focused specialists with entrenched workflow dependencies.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| PerkinElmer Inc |
| Agilent Technologies |
| Waters Corporation |
| Natus Medical |
| Thermo Fisher Scientific |
| AB SCIEX |
| Masimo |
| Trivitron Healthcare |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees in integrated delivery networks concentrate purchasing power around bundled instrument-reagent-service contracts, anchoring the market's dominant contract-based long-term offtake pricing model. This buyer concentration compresses vendor margins while locking in multi-year reagent supply agreements that span 500–2,000 sample daily throughput requirements.
Pricing Analysis
Margin tightening in high-volume reference laboratories reflects group purchasing organization consolidation across Texas and California birthing facilities. Three-tier pricing structure across premium, standard, and economy levels differentiates systems by throughput capacity and CLIA certification tier, with pediatrician offices showing highest price sensitivity due to lower sample volumes. Cost-down pressure on mid-tier platforms accelerates because next-generation sequencing platforms displace single-analyte workflows at compressed per-test economics.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China maintain hub-and-spoke patterns for analytical instrumentation and specialized chemistries. Manufacturing of tandem mass spectrometry components and PCR assay chemistries draws from concentrated supplier bases in Western Europe, with dried blood spot card production anchored in North American paper processing facilities. Single-source vulnerability in specialized reagent supply creates exposure to regulatory restriction under EU In Vitro Diagnostic Regulation re-certification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in active technology transition as next-generation sequencing platforms displace entrenched tandem mass spectrometry workflows for metabolic and genetic disorder detection. This displacement compresses legacy revenue streams while expanding total addressable panel breadth.
For Market Incumbents: Anticipate accelerated replacement cycles in high-volume reference laboratories by deepening captive supply of sequencing chemistries and data management systems. Defend installed base positions through extended service contracts that bundle legacy spectrometry maintenance with next-generation platform migration pathways, addressing the threat of multiplex gene panel cost compression. For New Entrants and Emerging Players: FDA expansion of the Recommended Uniform Screening Panel in the United States opens a window for point-of-care pulse oximetry deployment in delivery rooms outside centralized laboratory workflows. Target underpenetrated critical congenital heart defect screening in rural US markets and tier-two Chinese cities, leveraging portable device specifications that emphasize ease-of-use over throughput capacity. For Investors and Strategic Acquirers: The window for entry favors quality control and automation specialists with entrenched dried blood spot processing dependencies. Long-term viability rests on acquiring vendors with validated middleware for legacy system interoperability, with the signal to monitor being WHO guideline adoption rates across Southeast Asian and Latin American health systems.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU In Vitro Diagnostic Regulation compliance enables access to German and French pediatric reference laboratories. |
| Hospital System Partnership | Integrated delivery networks in Texas and California consolidate procurement across multiple birthing facilities under single vendor relationships. |
| Software Companion Development | Laboratory information system integration with electronic health records creates workflow lock-in for platform vendors. |
| Reimbursement Strategy | State-level mandate expansion for expanded metabolic panels secures predictable revenue streams through Medicaid and private payer coverage. |
| Backward Integration into Chemistries | In-house production of PCR and sequencing reagents reduces supplier concentration risk and protects margin structure. |
Study Parameters
FDA filings, EMA submissions, and CMS Medicare data formed the secondary backbone for regulatory pathway validation, supplemented by hospital procurement databases and GPO contracts. Primary interviews with laboratory directors, biomedical engineers, and GPO contracts managers triangulated against secondary sources, with bottom-up instrument installation counts and top-down health system expenditure analysis cross-validating market sizing.
Bottom-up modeling of installed base replacement cycles and reagent consumption patterns anchored volume projections across the analysis window, while top-down health authority budget allocation data validated expenditure trajectories. Segmentation dimensions included technology platform, end-user facility type, and application panel breadth, with CAGRs derived from instrument shipment trends and reagent pricing elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for next-generation sequencing platform cost reduction would alter the outlook for spectrometry retention rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Medical Automation Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Medical Equipment Calibration Services Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Cath Lab Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
North America Nuclear Medicine Equipment Market