
 Europe Hospital Furniture Market | 2026-2036
Europe Hospital Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hospital Furniture Market Foresight
Maintenance contracts and software-defined bed positioning is hardening into a core revenue layer rather than an afterthought. Wissner Bosserhoff leverages its German manufacturing base to anchor premium service agreements across Central European hospital networks. Lojer Group specializes in Nordic rehabilitation equipment, while Haelvoet competes through modular cabinetry systems designed for rapid ward reconfiguration.
Europe hospital furniture encompasses beds, stretchers, seating, and storage systems engineered to IEC 60601 electrical safety standards and EN 60601-2-52 dimensional protocols for patient support surfaces. These products serve clinical workflows, infection control, and caregiver ergonomics in acute and post-acute settings. Hospital beds retain the largest installed base, though stretchers generate higher replacement velocity in emergency departments. Private clinics increasingly specify metal-frame construction with antimicrobial powder coating, while long-term care facilities drive upholstery demand for pressure-relief surfaces.
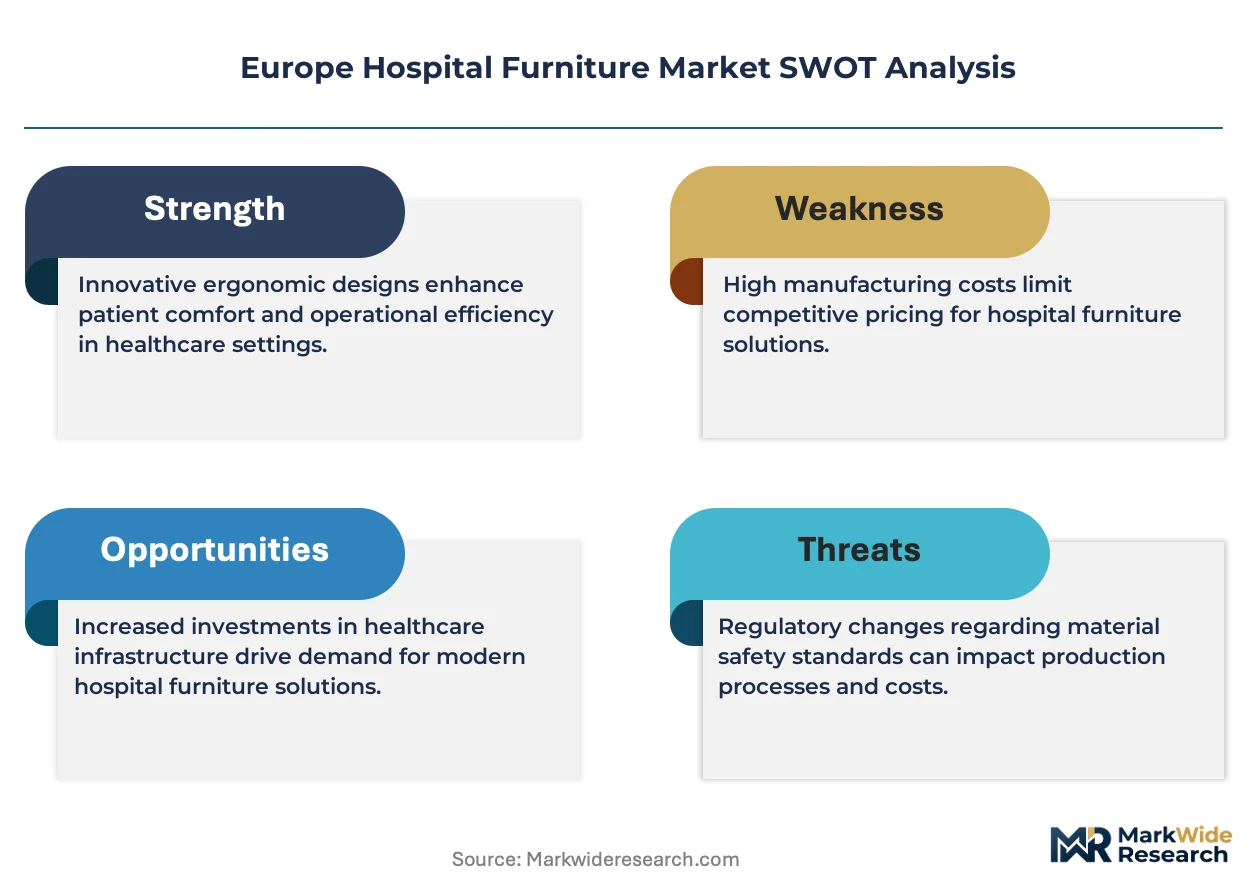
EMA device vigilance requirements and EU MDR technical documentation obligations are extending product development cycles and raising barriers for non-certified suppliers. REACH restrictions on flame retardants and the F-Gas Regulation on cooling components in specialized mattresses are forcing material substitutions across the supply base. Stakeholders must weigh certification investment against the contracting window for public hospital tenders.
Market Dynamics
EU MDR compliance timelines and IEC 60601-2-52 dimensional mandates are compressing product development cycles while elevating certification costs for powered patient support surfaces across European acute care networks.
Growth Catalysts
- France acute care renovation programs:Hospital infrastructure modernization is accelerating replacement cycles for motorized beds and pressure-relief surfaces in tertiary centers.
- EU Medical Device Regulation:MDR safety certification requirements are filtering out non-compliant suppliers and consolidating procurement toward certified manufacturers.
- Motorized bed technology:Long-term care facilities in Germany are expanding procurement of powered positioning systems to reduce caregiver injury rates.
Market Restraints
- REACH flame retardant restrictions:ECHA limitations on halogenated compounds are forcing costly upholstery material reformulations without proven alternatives.
- F-Gas Regulation compliance:Cooling component restrictions for specialized therapeutic mattresses are narrowing supplier options and extending qualification periods.
- Steel and aluminum input volatility:Metal frame construction costs fluctuate with energy-intensive European smelter output constraints.
Strategic Opportunities
- Software-defined bed positioning:Firmware-enabled patient surface control creates recurring service revenue streams beyond hardware sales.
- Modular cabinetry systems:Rapid ward reconfiguration capabilities address Netherlands and Belgium hospital flexibility mandates for surge capacity planning.
- Antimicrobial powder coating:Private clinic specifications for metal-frame construction with infection-resistant finishes open premium pricing tiers.
Industry Challenges
- EMA device vigilance documentation:Extended technical file preparation timelines delay product launches by 12-18 months for powered furniture categories.
- Legacy electrical infrastructure integration:Older hospital buildings require costly retrofitting to support IEC 60601-compliant powered bed installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hospital Furniture Market |
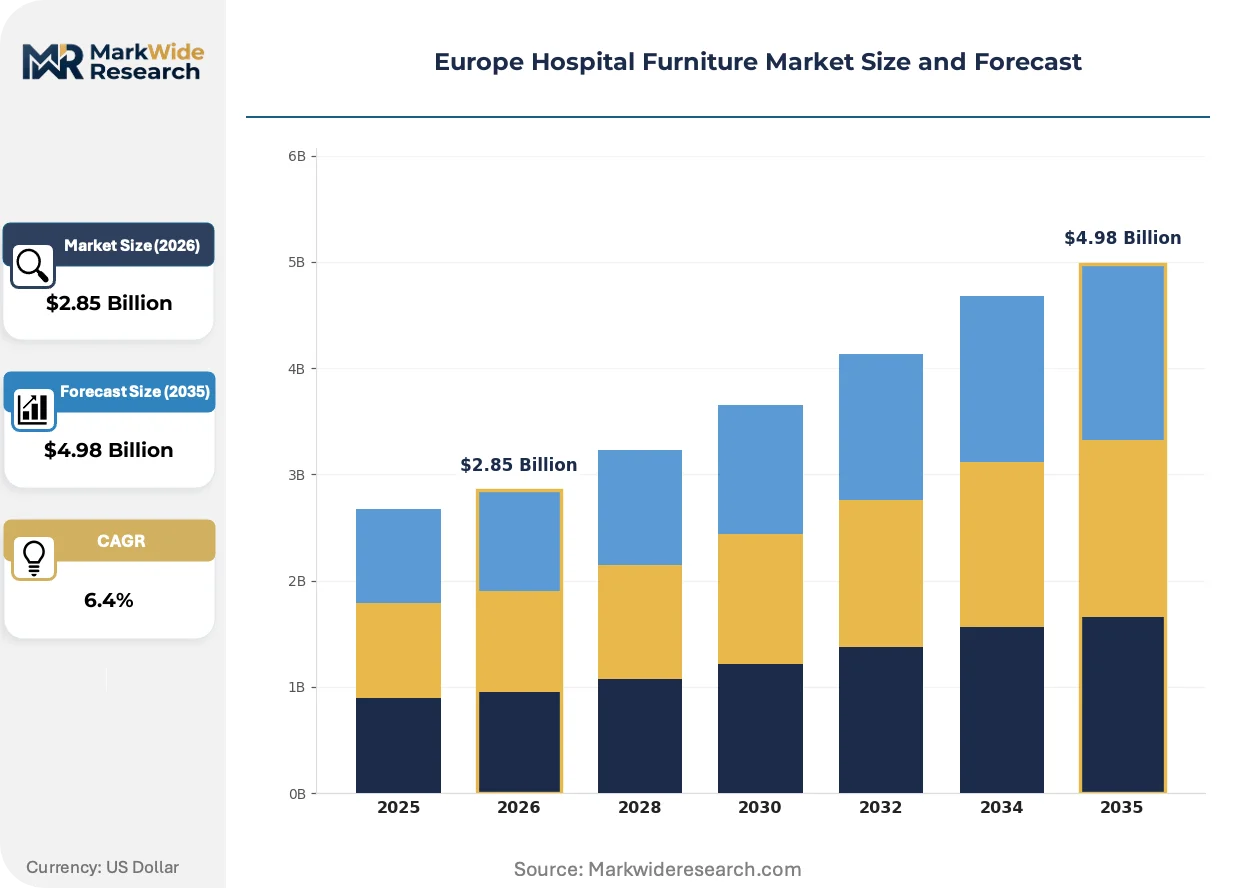
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hospital Beds, Stretchers, Recliners, Cabinets End User: Public Hospitals, Private Clinics, Rehabilitation Centers, Long-term Care Facilities Material: Metal, Wood, Plastic, Upholstery Service Type: Installation, Maintenance, Consulting, Customization |
| Companies Covered | Hospital Forniture SRL, Spacestor Healthcare, Haelvoet, JTC Furniture Group, Ocura Healthcare Furniture, Medical Innovation Solutions, Wissner Bosserhoff, Lojer Group, HT Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hospital Furniture Market Shifts & Advancements
Digital connectivity and material science advances are redefining how patient support surfaces integrate with clinical workflows and infection control protocols across European healthcare networks.
Wireless sensor networks embedded in hospital beds are modularizing how patient monitoring data flows to nurse stations and electronic health records. Nordic rehabilitation centers are piloting these systems for fall-risk prediction and pressure ulcer prevention. The technology is modularizing vendor relationships by separating hardware procurement from software subscription layers.
REACH restrictions on persistent organic pollutants are compelling upholstery manufacturers toward bio-based flame retardant formulations. ECHA evaluation timelines for alternative chemistries are creating interim supply bottlenecks for pressure-relief mattress cores. German and French hospital groups are responding by consolidating purchasing power to secure qualified material streams ahead of reformulation deadlines.
Maintenance contracts are unbundling from capital equipment sales as distinct revenue lines with separate margin profiles. Central European hospital networks now negotiate multi-year service agreements covering firmware updates, calibration, and predictive parts replacement. This shift is most pronounced in Switzerland and Austria, where private clinic chains prioritize uptime guarantees over lowest-bidder procurement.
Europe Hospital Furniture Market Segmentation
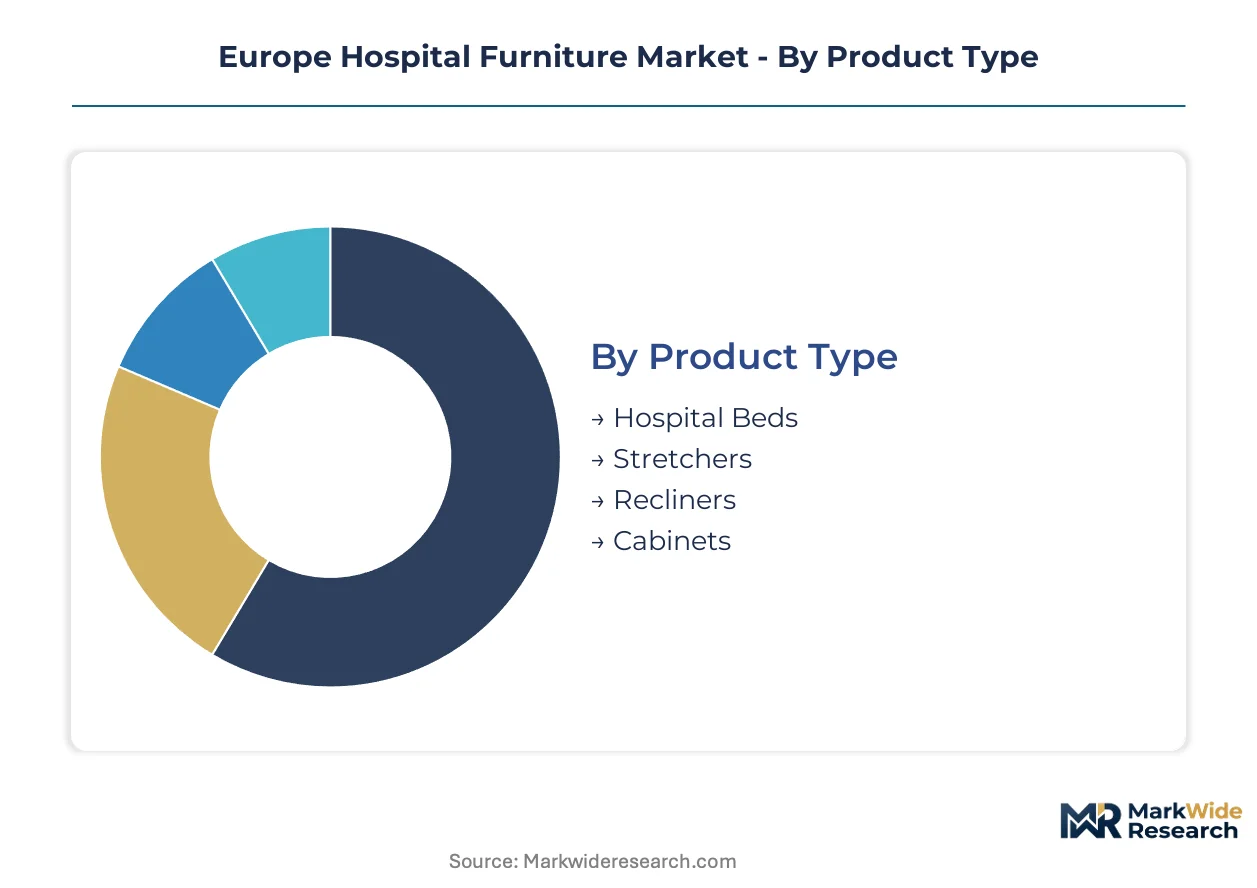
Hospital furniture procurement across Europe fragments across clinical workflow requirements, regulatory compliance tiers, and facility infrastructure constraints. Each segmentation dimension carries distinct margin profiles and certification burdens that reshape vendor positioning.
Product Type:
Customization intensity spans from standardized stretchers to fully configurable motorized beds with embedded sensor networks.
- Hospital Beds:Motorized positioning systems with IEC 60601-2-52 compliant patient support surfaces dominate capital expenditure in German and French acute care networks. Demand concentrates in tertiary centers renovating aging ward infrastructure under national hospital modernization programs.
- Stretchers:Emergency department workflow equipment with hydraulic height adjustment and radiolucent decking generates replacement velocity above other categories. French public hospitals are accelerating procurement to meet surge capacity mandates.
- Recliners:Dialysis and infusion therapy seating with pressure-relief cushioning serves outpatient expansion in Netherlands private clinic chains.
- Cabinets:Modular storage systems with antimicrobial powder coating enable rapid ward reconfiguration for Belgium and Netherlands surge planning protocols.
Leading the category by volume: Hospital Beds. Expanding most quickly: Stretchers.
End User:
Procurement sophistication varies from centralized tender processes to direct manufacturer relationships.
- Public Hospitals:EU MDR compliance documentation and extended technical file preparation dominate sourcing criteria. German hospital groups are consolidating purchasing power to secure qualified material streams ahead of REACH reformulation deadlines.
- Private Clinics:Metal-frame construction with infection-resistant finishes commands premium pricing tiers in Swiss and Austrian chains prioritizing uptime guarantees.
- Rehabilitation Centers:Nordic facilities pilot wireless sensor networks for fall-risk prediction and pressure ulcer prevention.
- Long-term Care Facilities:German procurement of powered positioning systems is accelerating to reduce caregiver injury rates and meet occupational safety mandates.
Dominating procurement value: Public Hospitals. Steepest expansion trajectory: Long-term Care Facilities.
Material:
REACH restrictions are forcing substitution timelines that fragment supplier qualification across the supply base.
- Metal:Steel and aluminum frame construction with antimicrobial powder coating serves private clinic specifications. ECHA limitations on halogenated compounds are forcing costly upholstery material reformulations without proven alternatives.
- Wood:Modular cabinetry systems in Nordic rehabilitation centers emphasize natural material aesthetics for patient environment design.
- Plastic:High-density polymer components for non-structural elements face F-Gas Regulation compliance constraints on cooling-integrated therapeutic mattresses.
- Upholstery:Pressure-relief mattress cores are experiencing interim supply bottlenecks as ECHA evaluates bio-based flame retardant formulations.
Highest volume consumption: Metal. Narrowing fastest: Upholstery.
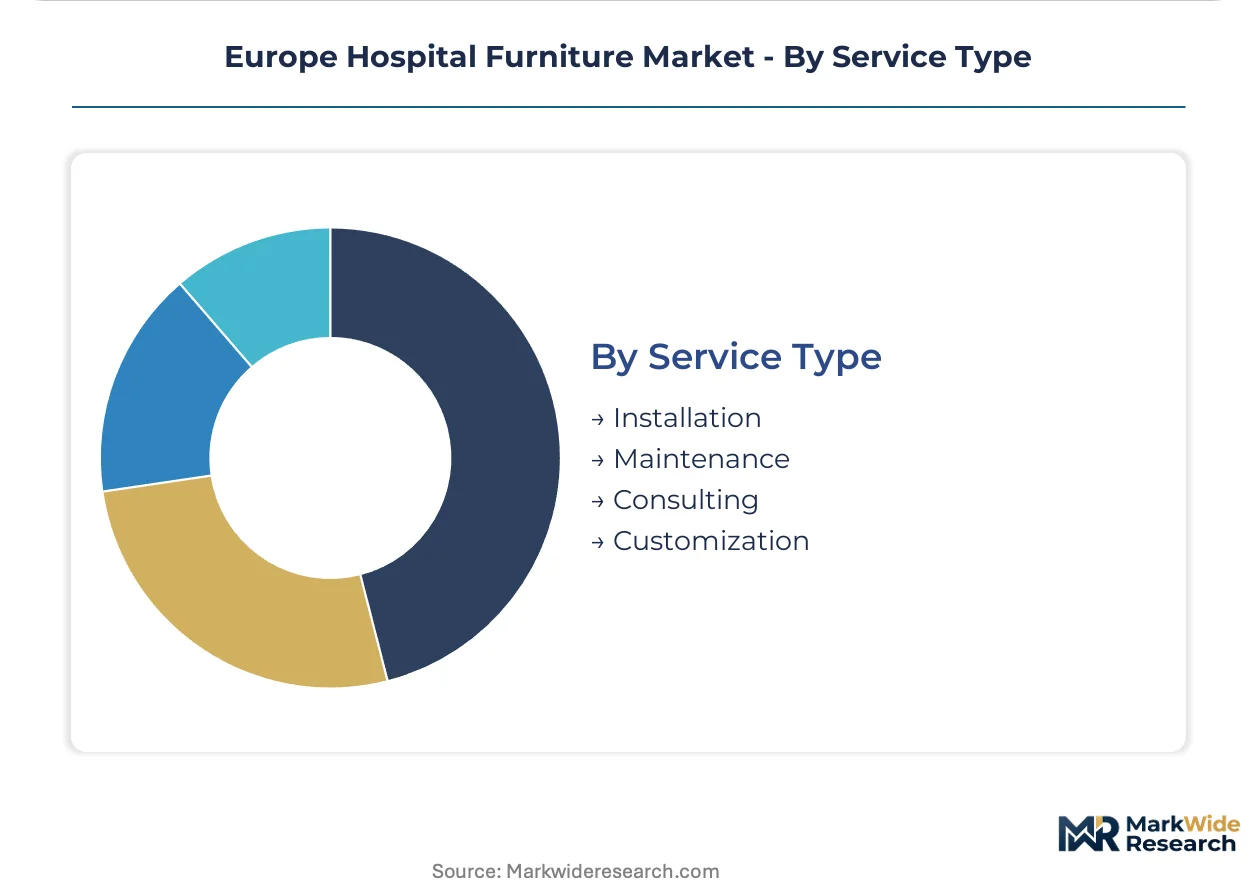
Service Type:
Revenue unbundling from hardware sales is creating distinct margin profiles across Central European hospital networks.
- Installation:IEC 60601-compliant electrical infrastructure retrofitting for older hospital buildings extends project timelines and service contract scope.
- Maintenance:Multi-year agreements covering firmware updates and predictive parts replacement now dominate Swiss and Austrian private clinic negotiations.
- Consulting:Ward workflow optimization and infection control protocol alignment supports Netherlands and Belgium flexibility mandates.
- Customization:Software-defined bed positioning with firmware-enabled patient surface control creates recurring subscription revenue beyond capital equipment sales.
Largest revenue pool: Maintenance. Gaining share fastest: Customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany anchors European production capacity for powered patient support surfaces, while France and the Netherlands drive consumption through acute care renovation and surge capacity mandates. This production-consumption divide shapes procurement patterns across Central and Western European hospital networks.
Germany
Long-term care facilities in North Rhine-Westphalia and Bavaria are expanding procurement of motorized beds to meet occupational safety mandates for caregiver injury reduction. EU MDR compliance timelines are compressing product development cycles for powered furniture manufacturers based in Baden-Württemberg. The Stuttgart industrial cluster hosts several IEC 60601-certified producers supplying Central European hospital networks with firmware-enabled positioning systems.
France
Acute care renovation programs in Île-de-France and Provence-Alpes-Côte d'Azur are accelerating replacement cycles for motorized beds and pressure-relief surfaces. ANSM device vigilance requirements are extending technical documentation preparation timelines for hospital furniture suppliers. Lyon-based manufacturers are consolidating purchasing power to secure qualified upholstery material streams ahead of REACH reformulation deadlines.
Netherlands
Private clinic chains in the Randstad region specify metal-frame construction with antimicrobial powder coating for infection control protocols. ECHA limitations on halogenated flame retardants are forcing costly material reformulations for Dutch upholstery suppliers. Eindhoven-area fabricators specialize in modular cabinetry systems designed for rapid ward reconfiguration under national surge capacity planning mandates.
Switzerland
Swissmedic certification requirements are filtering procurement toward manufacturers with established EU MDR technical documentation. Private clinic chains in Zurich and Geneva prioritize multi-year maintenance agreements covering firmware updates and predictive parts replacement over lowest-bidder procurement. Basel-area hospital networks are piloting wireless sensor networks embedded in patient support surfaces for fall-risk prediction.
Belgium
Public hospitals in Flanders and Wallonia face legacy electrical infrastructure constraints when installing IEC 60601-compliant powered beds. REACH restrictions on persistent organic pollutants are compelling Belgian upholstery manufacturers toward bio-based flame retardant formulations. Brussels-based hospital groups are consolidating tender processes to secure qualified material streams ahead of ECHA evaluation timelines for alternative chemistries.
Europe Hospital Furniture Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European hospital furniture market, creating a tiered structure where integrated manufacturers anchor premium service agreements while specialized fabricators compete on rapid customization. The vendor base fragments across three strategic archetypes: full-system providers bundling hardware with software subscriptions, component specialists focusing on pressure-relief surfaces or modular storage, and regional fabricators serving national tender processes. Dominant competitive moves include backward integration into qualified material streams to secure REACH-compliant upholstery supplies, and geographic expansion through multi-year maintenance contracts that harden recurring revenue beyond capital equipment sales.
Within the full-system provider tier, Wissner Bosserhoff and Lojer Group exemplify capital-intensive positioning anchored by manufacturing presence in Germany and Finland respectively. Haelvoet occupies a position within the component specialist archetype, with its naming convention suggesting Belgian origins and modular cabinetry focus. These three entities represent the competitive spectrum from integrated hardware-software platforms to rapid-reconfiguration storage systems, each sitting within distinct margin profiles tied to certification depth and service contract penetration.
| Leading Market Players |
|---|
| Hospital Forniture SRL |
| Spacestor Healthcare |
| Haelvoet |
| JTC Furniture Group |
| Ocura Healthcare Furniture |
| Medical Innovation Solutions |
| Wissner Bosserhoff |
| Lojer Group |
| HT Group |
| Others |
Supply & Pricing Matrix
Steel and aluminum frame materials flow from German and Austrian smelters through tiered pricing structures that separate IEC 60601-certified powered beds from standard manual configurations, with REACH-compliant upholstery commanding premium positioning against reformulation-constrained supply.
Pricing Analysis
Cost-down pressure on public hospital procurement accelerates because ECHA flame retardant restrictions compress qualified upholstery supply. Three-tier pricing structure across premium firmware-enabled beds, standard motorized configurations, and economy manual frames differentiates by certification depth and service bundling. Private clinic chains in Switzerland exhibit lowest price sensitivity, prioritizing uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Direct-to-hospital-group channels handle large-scale tender demand from German and French acute care networks. Manufacturing concentrates in Germany, Finland, and Belgium, drawing from steel mills in North Rhine-Westphalia, polymer component fabricators in the Netherlands, and Italian textile suppliers for pressure-relief surfaces. Single-source vulnerability in REACH-compliant upholstery creates qualification bottlenecks extending procurement timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR certification capacity constraints prop pricing power for qualified manufacturers, as technical documentation backlogs limit new supplier entry.
For Market Incumbents: Deepen backward integration into qualified upholstery streams to secure REACH-compliant material ahead of ECHA evaluation deadlines. Expand firmware-enabled service contract penetration in Swiss and Austrian private clinic chains to lock in recurring revenue against emerging modular competitors. For New Entrants and Emerging Players: Long-term care facilities in German federal states present the most penetrable buyer archetype, with occupational safety mandates accelerating powered bed procurement beyond incumbent service capacity. Enter through maintenance-first contracting models that bypass capital tender barriers. For Investors and Strategic Acquirers: Consolidation of hospital group purchasing power in France and Germany is the leading indicator that scale advantages are concentrating among certified manufacturers. Target mid-tier firmware developers with established IEC 60601 technical files. Watch ECHA alternative chemistry approvals as the signal for upholstery supply normalization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Investment | CE marking pathways filter procurement toward compliant manufacturers in German hospital networks. |
| Software-Defined Bed Positioning Development | Firmware subscriptions create recurring revenue streams beyond hardware capital sales cycles. |
| REACH-Compliant Upholstery Backward Integration | Captive supply of qualified materials secures production continuity against ECHA restriction timelines. |
| Multi-Year Maintenance Contract Expansion | Service agreements harden customer retention in Swiss and Austrian private clinic chains. |
| Modular Cabinetry Rapid Reconfiguration Systems | Netherlands and Belgium surge capacity mandates drive specification for flexible ward infrastructure. |
Research Methodology
Hospital procurement databases, ECHA regulatory filings, and GPO contract records formed the secondary backbone, supplemented by primary interviews with hospital biomedical engineers, long-term care facility procurement directors, and medical device regulatory consultants. Bottom-up shipment analysis triangulated against top-down healthcare capital expenditure tracking across the analysis window.
Historical trendline analysis of motorized bed installations and stretcher replacement cycles informed the projection framework. Segmentation modeling spanned product type, end-user facility category, material compliance tier, and service bundling intensity. CAGRs derived from weighted average of equipment procurement trajectories and service revenue unbundling patterns, incorporating EU MDR implementation timelines and REACH reformulation deadlines as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA alternative chemistry approval delays and steel input cost volatility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Medicine Cabinets Market
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Medical Walker Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Medical Commodes Market