
 Orthopedic Operating Tables Market | 2026-2036
Orthopedic Operating Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Operating Tables Market Analysis
Capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is redrawing competitive boundaries in orthopedic table supply. Stryker Corporation leverages in-house imaging integration and surgical workflow software to sustain premium positioning across hospital networks. Getinge AB anchors European demand through direct service infrastructure and MDR-compliant validation documentation. Mizuho OSI specializes in spine-specific table configurations that dominate neuro-orthopedic hybrid procedures in Japanese and North American academic centers.
Orthopedic operating tables are height-adjustable surgical platforms engineered with carbon-fiber tabletop sections, radiolucent extensions, and multi-axis articulation to enable fluoroscopic imaging during fracture fixation, arthroplasty, and spinal instrumentation. Electric tables with motorized Trendelenburg, lateral tilt, and longitudinal slide functions have displaced manual crank systems in tertiary hospitals where surgical throughput and nurse ergonomics drive capital decisions. Imaging-compatible technology segments command margin premiums as C-arm integration becomes standard in trauma and joint replacement workflows, while hybrid tables combining general surgery and orthopedic functionality are penetrating surgical centers seeking equipment utilization flexibility. Wireless control adoption lags due to cybersecurity validation burdens and IT integration costs.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for table manufacturers. ISO 13485 quality management systems and IEC 60601-1 electrical safety standards form baseline compliance thresholds that determine Original Equipment Manufacturer eligibility in contracted procurement channels. Stakeholders must monitor evolving cybersecurity guidance from FDA and Notified Body interpretation of MDR Annex I general safety and performance requirements for networked surgical devices.
Market Dynamics
Imaging compatibility requirements are compressing replacement cycles for manual orthopedic tables as hospitals integrate C-arm fluoroscopy into trauma and joint replacement workflows, forcing capital allocation toward radiolucent carbon-fiber platforms with motorized articulation.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding ASCs in the United States are acquiring imaging-compatible tables to perform outpatient arthroplasty and spine procedures previously confined to inpatient settings.
- EU MDR conformity validation:Stricter technical documentation requirements for Class IIa surgical devices are accelerating obsolescence of legacy table designs lacking validated electromagnetic compatibility testing.
- Carbon-fiber tabletop substitution:Radiolucent composite materials are displacing traditional metal sections to enable uninterrupted intraoperative imaging during fracture fixation and spinal instrumentation.
Market Restraints
- Stainless steel input volatility:Surgical-grade 316L stainless steel price fluctuations from European and Asian mills compress margin predictability for table frame manufacturers.
- Electronics supply concentration:Servo motor controllers and linear actuator systems source predominantly from German and Japanese component suppliers, creating single-source vulnerability.
- Cybersecurity validation burden:FDA guidance on networked medical device security adds 12-18 month premarket timelines for wireless-enabled table control systems.
Strategic Opportunities
- Indian hospital infrastructure buildout:Greenfield tertiary facilities under the country's PLI scheme for medical devices present first-mover positioning for imaging-integrated table suppliers.
- Orthopedic-robotic convergence:Tables with registered kinematic interfaces for navigation systems and robotic arms are opening premium positioning in computer-assisted surgery suites.
- Refurbishment channel formalization:Certified pre-owned programs with OEM-backed service contracts are penetrating price-sensitive municipal hospital procurement in Southern Europe.
Industry Challenges
- Biomedical technician specialization gap:Servicing motorized tables with integrated imaging interfaces requires cross-trained personnel scarce in secondary hospital markets.
- Legacy OR integration complexity:Retrofitting electric tables into aging surgical suites with inadequate power infrastructure and ceiling suspension systems drives installation cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Operating Tables Market |
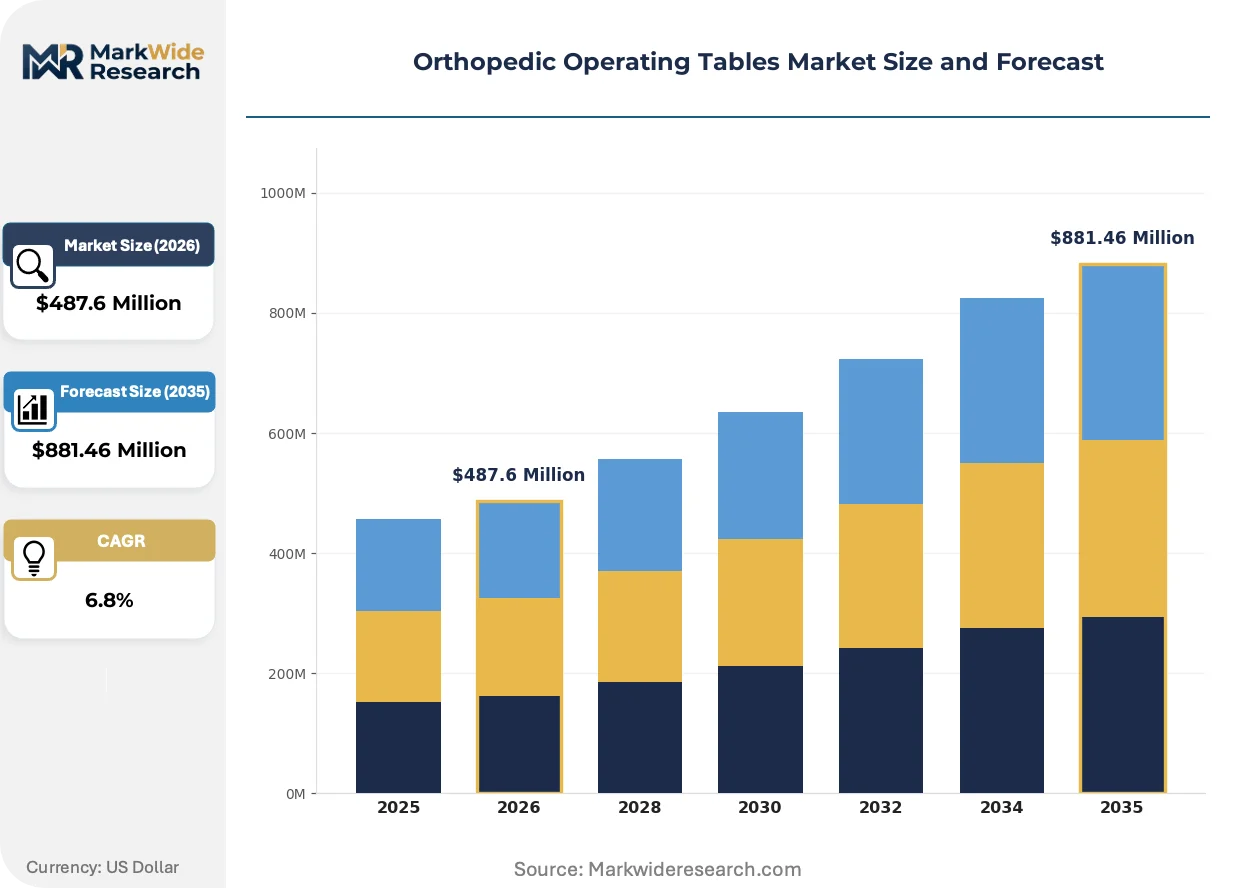
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Tables, Electric Tables, Hydraulic Tables, Hybrid Tables End User: Hospitals, Surgical Centers, Outpatient Facilities, Specialty Clinics Technology: Adjustable Height, Imaging-Compatible, Integrated Navigation, Wireless Control Application: Trauma Surgery, Joint Replacement, Spine Surgery, Sports Medicine |
| Companies Covered | Stryker Corporation, Steris Plc, Getinge AB, Mizuho OSI, Skytron LLC, Hill-Rom Holdings, Inc., Trumpf Medical, Maquet Holding B.V. & Co. KG, SCHAERER MEDICAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Operating Tables Market Emerging Trajectories
Orthopedic table engineering is converging with surgical navigation and robotic positioning systems, compressing the boundary between passive patient support and active procedural enablement.
Carbon-fiber radiolucent tabletops with integrated rail systems for traction and limb positioning are bifurcating the mid-market tier. Academic medical centers in Germany and Japan are specifying these platforms for hybrid trauma-spine procedures, while community hospitals delay upgrades pending capital cycle renewal. The technology is bifurcating procurement patterns between imaging-intensive sites and general surgery-focused facilities.
EU MDR Annex I general safety and performance requirements for electromagnetic compatibility are extending validation protocols for motorized tables with networked control interfaces. Manufacturers must demonstrate immunity to surgical equipment emissions and resilience against wireless interference. Japanese academic centers are prioritizing MDR-compliant documentation in supplier qualification to ensure exportable validation packages for multi-site health systems.
Leasing structures with bundled preventive maintenance are displacing outright purchase for tables in independent surgical centers. Financial intermediaries in the United States are offering usage-based arrangements where per-procedure fees cover equipment, service, and technology refresh. This model concentrates in California and Texas ASC markets where capital constraint meets high orthopedic procedure volume.
Orthopedic Operating Tables Market Segmentation
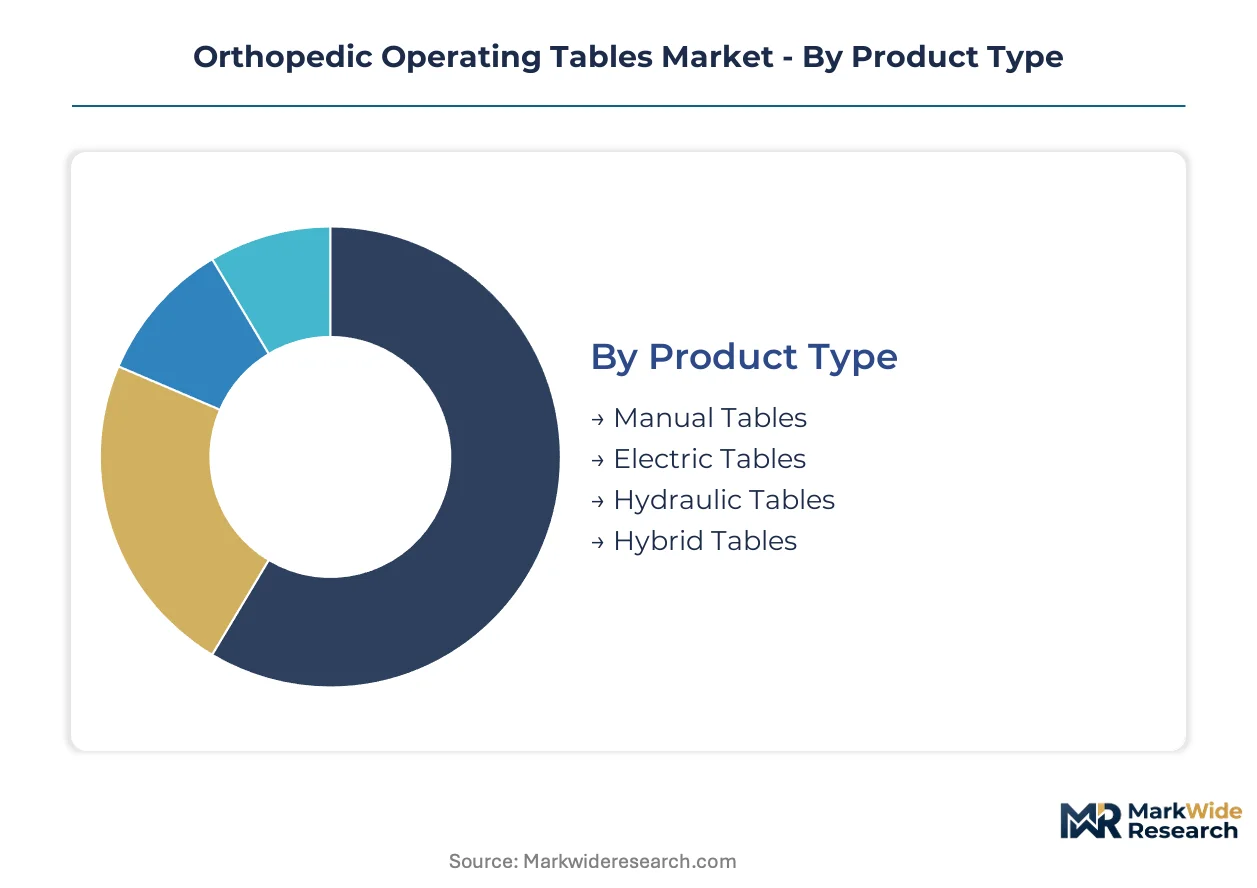
Orthopedic operating table procurement patterns diverge sharply across facility types and surgical workflows. Technology integration requirements and capital intensity thresholds create distinct substitution dynamics between manual, motorized, and hybrid platforms.
Product Type:
Electric tables face the most acute substitution pressure as imaging-compatible carbon-fiber platforms displace legacy motorized designs lacking radiolucent tabletops and C-arm integration.
- Manual Tables:Hand-crank height adjustment and mechanical tilt mechanisms persist in cost-constrained secondary hospitals and rural facilities. Demand concentrates in India and Southeast Asia where capital budgets prioritize basic functionality over imaging compatibility.
- Electric Tables:Motorized Trendelenburg, lateral tilt, and longitudinal slide functions dominate tertiary hospital procurement in the United States, Germany, and Japan. Nurse ergonomics and surgical throughput requirements drive replacement of manual systems.
- Hydraulic Tables:Fluid-powered positioning systems occupy mid-tier positioning in Eastern European and Latin American markets where electric infrastructure reliability varies. Lower maintenance requirements appeal to facilities with limited biomedical engineering staff.
- Hybrid Tables:Configurable platforms combining general surgery and orthopedic functionality penetrate ambulatory surgical centers seeking equipment utilization flexibility. Carbon-fiber radiolucent sections enable trauma and spine procedures in multi-specialty settings.
Electric tables anchor the volume base while hybrid tables gain share at the steepest rate.
End User:
Capital allocation discipline varies dramatically across facility types, with surgical centers pursuing imaging-compatible platforms on compressed procurement cycles compared to hospital networks.
- Hospitals:Tertiary academic medical centers specify premium motorized tables with integrated navigation interfaces and robotic arm compatibility. German and Japanese university hospitals drive demand for MDR-validated systems with electromagnetic immunity documentation.
- Surgical Centers:Freestanding ASCs in Texas and California acquire imaging-compatible electric tables for outpatient arthroplasty and spine procedures. Leasing structures with bundled maintenance displace outright purchase.
- Outpatient Facilities:Limited-service clinics prioritize manual and hydraulic tables for minor orthopedic interventions. Price sensitivity dominates procurement decisions.
- Specialty Clinics:Sports medicine and hand surgery centers specify compact tables with limb positioning attachments. Space constraints and procedure-specific workflows shape selection criteria.
Hospitals command the installed base while surgical centers demonstrate the most aggressive upgrade velocity.
Technology:
Wireless control adoption lags due to cybersecurity validation burdens, creating a gap between available connectivity and regulatory clearance timelines.
- Adjustable Height:Vertical travel range of 600-1100mm accommodates surgeon ergonomics across standing and seated procedures. Baseline capability present across all motorized platforms.
- Imaging-Compatible:Carbon-fiber tabletops with radiolucent extensions enable uninterrupted C-arm fluoroscopy during fracture fixation and spinal instrumentation. Premium pricing reflects material costs and electromagnetic compatibility testing.
- Integrated Navigation:Registered kinematic interfaces for surgical navigation systems and robotic arms command positioning in computer-assisted surgery suites. Japanese academic centers specify these platforms for hybrid neuro-orthopedic procedures.
- Wireless Control:Networked tablet and pendant interfaces face 12-18 month FDA premarket timeline extensions due to cybersecurity guidance. IT integration costs and hospital network security protocols constrain deployment.
Imaging-compatible technology captures the margin premium while integrated navigation climbs fastest in academic center procurement.
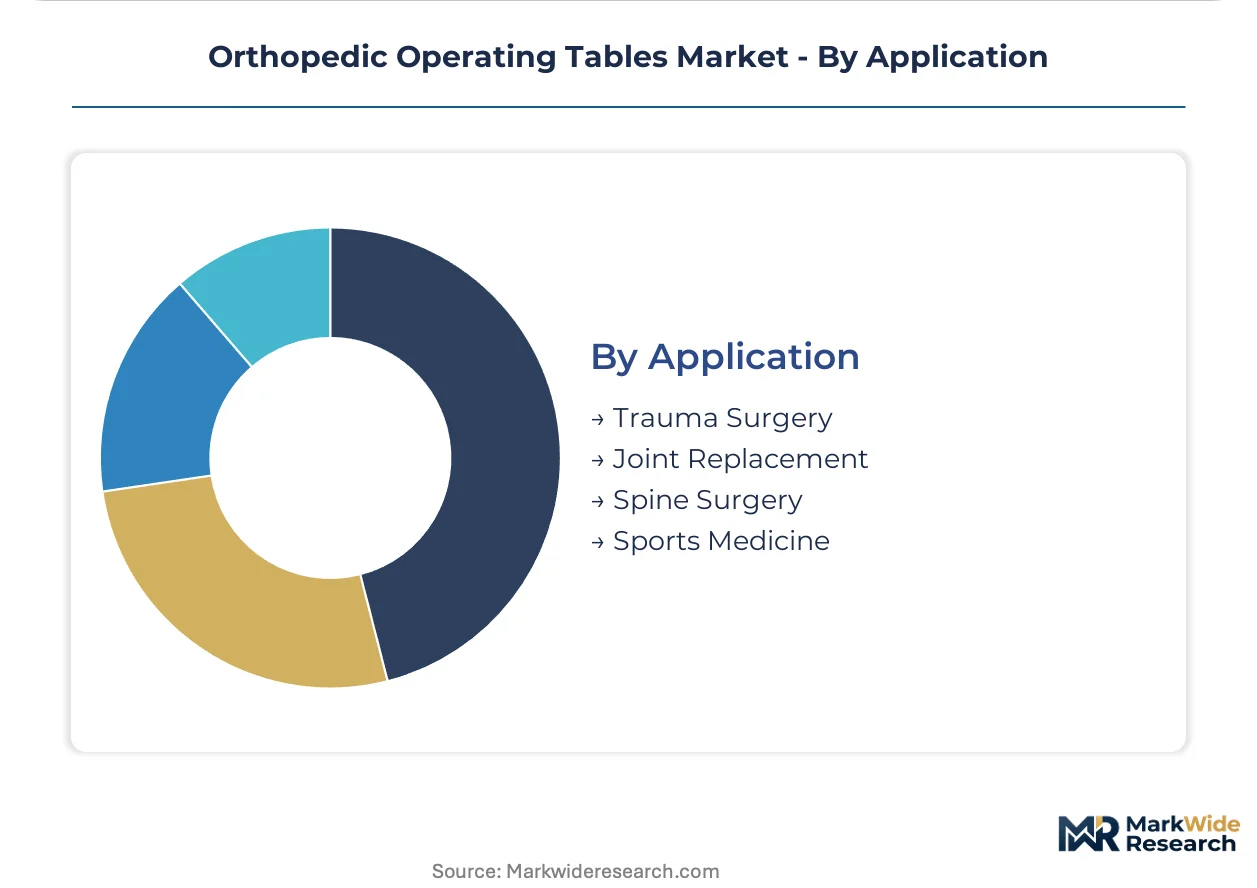
Application:
Procedure complexity and imaging intensity determine table specification requirements, with spine and trauma surgery demanding the most advanced articulation capabilities.
- Trauma Surgery:Rapid patient positioning and radiolucent tabletop sections enable intraoperative imaging during fracture fixation. Carbon-fiber extensions support traction and limb manipulation.
- Joint Replacement:Motorized lateral tilt and Trendelenburg positioning facilitate exposure for hip and knee arthroplasty. ASC volume growth drives demand for efficient turnover platforms.
- Spine Surgery:Multi-axis articulation with neurophysiological monitoring integration dominates neuro-orthopedic hybrid procedures. Mizuho OSI configurations lead Japanese and North American academic center specifications.
- Sports Medicine:Arthroscopy-focused tables with limb positioning attachments and irrigation management features serve high-volume knee and shoulder procedures.
Joint replacement procedures generate the highest table utilization hours while spine surgery commands the most specialized platform specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for carbon-fiber tabletops and precision servo systems concentrates trade flows toward manufacturing clusters in Germany, Japan, and the United States. Equipment exporters from these markets dominate procurement channels in secondary hospitals across India, Brazil, and Southeast Asia.
United States
FDA 510(k) clearance pathways shape validation timelines for motorized tables with networked control interfaces. Ambulatory surgical centers in Texas and California drive leasing adoption for imaging-compatible platforms. The Greater Boston cluster anchors academic medical center procurement for spine-specific table configurations with navigation system integration.
Germany
EU MDR conformity requirements extend technical documentation obligations for Class IIa surgical devices. TÜV and DEKRA Notified Body interpretations of electromagnetic compatibility standards filter market access for motorized platforms. The Baden-Württemberg industrial corridor concentrates precision actuator manufacturing for European table OEMs.
Japan
PMDA premarket certification aligns with MDR documentation standards for exportable validation packages. METI industrial policy supports domestic production of radiolucent carbon-fiber composite materials. The Chubu region around Nagoya hosts specialized suppliers for neuro-orthopedic hybrid procedure tables.
India
PLI scheme incentives for medical device manufacturing attract greenfield table assembly investments. CDSCO import licensing requirements favor local production for cost-sensitive municipal hospital procurement. Maharashtra and Karnataka tertiary facilities concentrate demand for imaging-compatible electric platforms under infrastructure buildout programs.
China
NMPA Class II medical device registration mandates clinical validation for motorized surgical tables with C-arm integration. MIIT industrial standards for medical equipment quality accelerate substitution of manual systems in tier-2 city hospitals. The Yangtze River Delta manufacturing base supplies domestic OEMs with linear actuator and control system components.
Orthopedic Operating Tables Market Vendor Landscape
Concentration sits with integrated manufacturers controlling in-house imaging integration and electromagnetic compatibility validation capabilities. The vendor base splits between premium-tier suppliers with direct service infrastructure and assembly-dependent competitors sourcing carbon-fiber tabletops and servo systems from concentrated component markets. Two strategic archetypes dominate: vertically integrated surgical equipment conglomerates with software workflow integration, and specialized table manufacturers with procedure-specific kinematic expertise. Competitive moves center on MDR documentation bundling for multi-site health systems and leasing structure formalization for ASC markets.
Among North American and European surgical equipment conglomerates, Stryker Corporation and Getinge AB occupy positions reflecting integrated manufacturing depth. Stryker exemplifies the imaging-software convergence archetype through in-house C-arm compatibility and surgical workflow platforms. Getinge anchors European demand fulfillment through direct service infrastructure and MDR-compliant validation documentation. Mizuho OSI represents the procedure-specialist archetype, with its corporate name indicating Japanese origin and spine-orthopedic hybrid focus. These three companies illustrate the competitive spectrum from diversified surgical equipment portfolios to targeted neuro-orthopedic platform engineering.
| Leading Market Players |
|---|
| Stryker Corporation |
| Steris Plc |
| Getinge AB |
| Mizuho OSI |
| Skytron LLC |
| Hill-Rom Holdings, Inc. |
| Trumpf Medical |
| Maquet Holding B.V. & Co. KG |
| SCHAERER MEDICAL |
| Others |
Supply Flow & Price Mechanics
Carbon-fiber tabletop manufacturing scale in Germany and Japan anchors supply-side concentration while establishing price floors for imaging-compatible platforms. These production clusters leverage precision composite fabrication and electromagnetic compatibility testing infrastructure that smaller assembly operations cannot replicate, compressing margin flexibility for mid-tier competitors sourcing from third-party component markets.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers based on FDA 510(k) clearance status and bundled service contracts. Certification tier and after-sales service bundling drive price differentiation, with MDR-validated systems commanding sustained premiums. Cost compression in the standard tier intensifies as Asian assembly competitors enter with basic motorized platforms. Ambulatory surgical centers demonstrate highest price sensitivity, while German and Japanese academic medical centers prioritize electromagnetic immunity documentation over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision servo motor and linear actuator production, while China supplies domestic OEMs with control system components. Surgical-grade 316L stainless steel for table frames draws from European and Asian mills, with radiolucent carbon-fiber composites tethered to specialized German and Japanese suppliers. Single-source vulnerability concentrates in German and Japanese precision electronics. Distribution runs through direct OEM service infrastructure for premium-tier systems and third-party medical equipment distributors for cost-sensitive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic operating table demand is accelerating through ambulatory surgical center expansion and EU MDR regulatory inflection, creating asymmetric opportunities across incumbent defense, entrant positioning, and acquisition targeting strategies.
For Market Incumbents: Shield premium positioning by deepening backward integration into carbon-fiber composite fabrication and electromagnetic compatibility validation infrastructure. Consolidate channel control through direct service contracts that lock hospital networks into MDR-compliant documentation ecosystems. Priority lever rests on software workflow integration that embeds tables into broader surgical platform architectures, raising switching costs against emerging assembly competitors.
For New Entrants and Emerging Players: Anchor in Indian tertiary hospital infrastructure buildout under CDSCO and PLI scheme incentives, where greenfield procurement lacks incumbent service relationships. Target municipal hospital segments in Southern Europe with certified pre-owned programs and OEM-backed refurbishment channels. Go-to-market angle emphasizes imaging-compatible electric platforms at standard-tier price points, exploiting the gap between basic hydraulic tables and premium integrated navigation systems.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among table manufacturers with leasing structures and bundled preventive maintenance contracts in United States ASC markets. Long-term viability favors acquisition targets with validated MDR technical documentation and established direct service infrastructure. Signal to watch is FDA cybersecurity guidance finalization, which will compress premarket timelines for wireless-enabled platforms and reshape competitive positioning for networked control systems.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | EU MDR Annex I compliance accelerates market access for Class IIa surgical devices across German and Japanese health systems. |
| Leasing Structure Formalization | Usage-based arrangements with bundled maintenance penetrate Texas and California ASC markets facing capital constraints. |
| Imaging-Integration Partnership | C-arm compatibility and surgical navigation interfaces embed tables into fluoroscopy-dependent trauma and spine workflows. |
| Cybersecurity Validation Pathway | FDA premarket timeline navigation for wireless control systems differentiates compliant suppliers from lagging competitors. |
| Refurbishment Channel Certification | OEM-backed pre-owned programs unlock municipal hospital procurement in Southern Europe and Southeast Asia. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, ambulatory surgical center administrators, orthopedic surgeons, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR Notified Body technical documentation, hospital procurement records, and ISO 13485 quality management system audits. Bottom-up installation base estimates triangulated against top-down capital equipment spending projections across the analysis window.
Across the modeling period, volume and value outputs segmented by product type, end-user facility tier, technology integration level, and application intensity. CAGRs derived from procedure volume trajectories, replacement cycle compression rates, and capital allocation elasticity to imaging compatibility requirements. Industry-specific forecast inputs incorporated C-arm fluoroscopy adoption curves and EU MDR transition timelines for Class IIa surgical device re-registration.
Decision-makers should treat outputs as directional under sustained ambulatory surgical center expansion and EU MDR enforcement assumptions; material deviation in stainless steel input costs or FDA cybersecurity guidance timing would warrant model refresh. Recalibration cycles align with material shifts in procedure site migration, regulatory clearance velocity, and carbon-fiber composite supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Centrifuge Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Dial Thermometers Market