
 North America Anesthesia Drugs Market | 2026-2036
North America Anesthesia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Anesthesia Drugs Market Analytics
Market Context
Hospital purchasing consortiums and specialty pharmacy networks is reshaping how anesthesia drugs reach end users across North America. Pfizer Inc leverages its manufacturing scale to supply intravenous anesthetic formulations to integrated delivery networks. Baxter International anchors the inhalation anesthetic segment through its captive production of volatile agents. Fresenius SE & Co KGaA competes in the hospital channel with bundled anesthesia and critical care portfolios.
Technical and Segment Structure
Anesthesia drugs are pharmacological agents that induce reversible loss of sensation or consciousness, formulated as injectable solutions, inhaled gases, or topical preparations with precise potency specifications measured in minimum alveolar concentration or mg per kg dosing curves. General anesthetics dominate value pools due to their essential role in major surgical procedures, while intravenous delivery mode commands procurement priority in ambulatory settings where rapid induction and recovery protocols govern selection. Sedatives represent the fastest-expanding category as outpatient procedural volume rises and conscious sedation protocols broaden across gastroenterology and interventional cardiology suites.
Regulatory Environment
FDA bioequivalence standards for generic injectable anesthetics shape product development timelines and ANDA approval economics for manufacturers serving the United States market. Health Canada's Therapeutic Products Directorate maintains parallel but distinct review pathways that Canadian suppliers must navigate for market authorization. Stakeholders must monitor how FDA quality metrics guidance and Health Canada ICH Q12 implementation on post-approval management will alter lifecycle strategies for established anesthesia portfolios.
Market Dynamics
Hospital purchasing consortiums and specialty pharmacy networks are consolidating procurement power across the United States and Canada, compressing price points for generic injectable anesthetics while elevating quality audit requirements for suppliers.
Growth Catalysts
- FDA ANDA Pathway Streamlining:The FDA's updated guidance on abbreviated new drug applications for generic injectable anesthetics reduces approval timelines, accelerating market entry for cost-competitive alternatives.
- Ambulatory Surgical Center Expansion:Freestanding ASCs across Texas, California, and Florida are building dedicated anesthesia service lines to capture shifting surgical volume from inpatient settings.
- Conscious Sedation Protocol Broadening:Gastroenterology and interventional cardiology suites are adopting expanded sedation frameworks, creating new demand nodes for short-acting intravenous agents.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for propofol and midazolam concentrates in a limited number of overseas facilities, exposing formulators to single-source vulnerability.
- Health Canada Parallel Review Burden:Canadian suppliers must navigate distinct Therapeutic Products Directorate pathways that extend authorization timelines relative to FDA processes.
- Inhalation Anesthetic Environmental Substitution:Desflurane faces displacement pressure from sevoflurane and intravenous alternatives due to greenhouse gas intensity concerns in hospital sustainability mandates.
Strategic Opportunities
- Canadian Provincial Contract Consolidation:Ontario and Quebec health authorities are centralizing anesthesia drug tenders, creating volume aggregation opportunities for suppliers with Health Canada approvals.
- Preoperative Assessment Clinic Integration:Bundled anesthesia and critical care portfolios can extend into perioperative medicine workflows, capturing value upstream of the operating room.
- US 340B Program Participation:Eligible entities including disproportionate share hospitals can access discounted pricing mechanisms that improve margin capture on high-volume generic anesthetics.
Industry Challenges
- Certified Registered Nurse Anesthetist Shortage:CRNA staffing gaps in rural and community hospital markets constrain service line expansion regardless of drug availability.
- Legacy EHR Integration Complexity:Anesthesia information management systems require costly interoperability upgrades to support real-time drug diversion monitoring and automated dispensing reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Anesthesia Drugs Market |
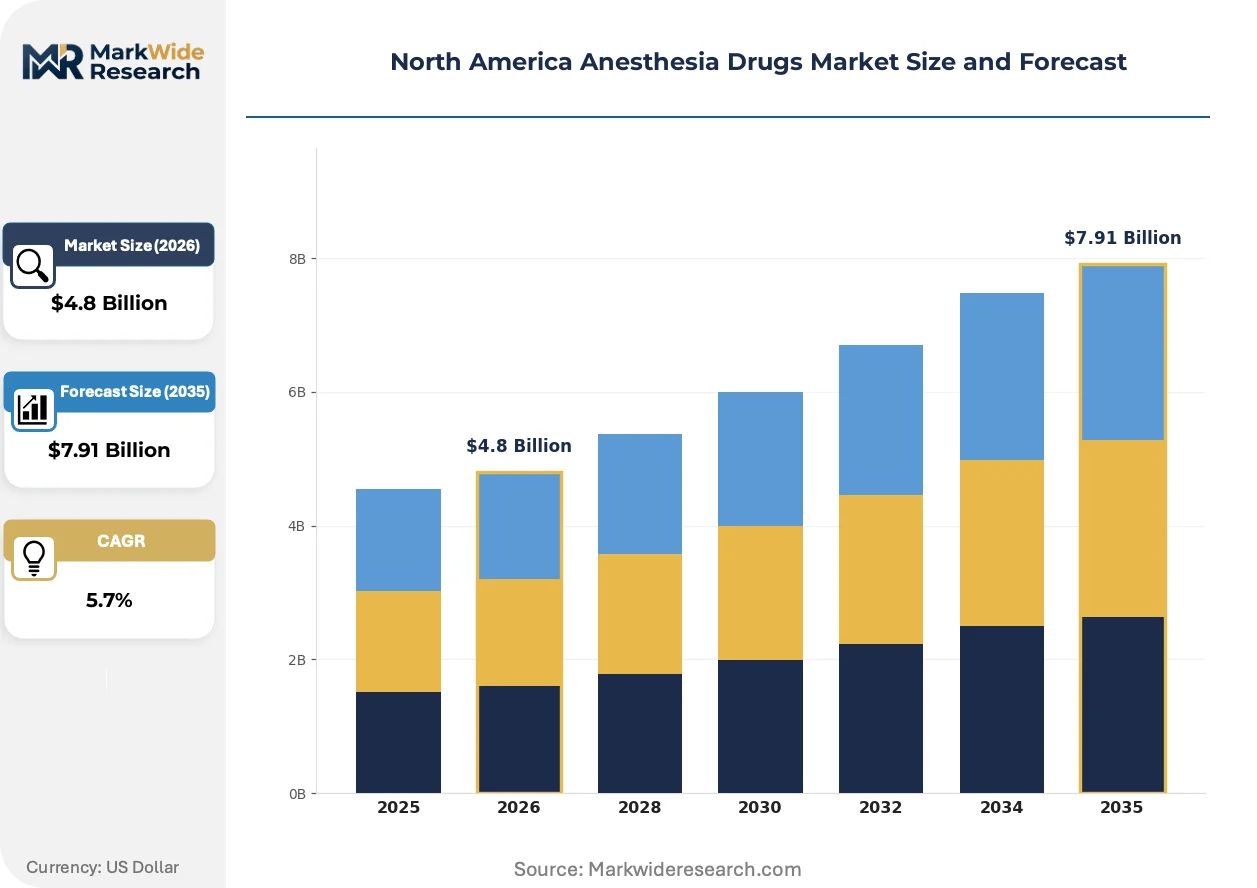
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Anesthetics, Local Anesthetics, Regional Anesthetics, Sedatives Delivery Mode: Inhalation, Intravenous, Topical, Oral End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Pharmacies Formulation: Injectables, Gases, Solutions, Tablets |
| Companies Covered | F Hoffmann-La Roche Ltd, Pfizer Inc, Baxter International, Eisai Co Ltd, B Braun SE, Fresenius SE & Co KGaA, Novartis AG, Avet Pharmaceuticals Inc, AbbVie Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Anesthesia Drugs Market Evolving Landscape
Digital anesthesia delivery systems and pharmacokinetic modeling software are converging with traditional drug formulation, creating closed-loop control architectures that personalize dosing in real time.
Target-controlled infusion platforms are hybridizing pharmacokinetic modeling with automated pump control, enabling anesthesiologists to specify desired effect-site concentrations rather than manual rate titration. Academic medical centers in Boston and Houston are piloting these systems for total intravenous anesthesia protocols. This technology is compressing variability in emergence times and reducing drug consumption per case.
FDA quality metrics guidance implementation is reshaping manufacturing inspection priorities for sterile injectable facilities, elevating process analytical technology adoption as a compliance differentiator. Facilities with mature continuous manufacturing data packages receive expedited review consideration. Generic anesthetic manufacturers serving the US market are responding by investing in real-time release testing capabilities.
Hospital buying groups are consolidating anesthesia drug contracts across integrated delivery networks, displacing fragmented purchasing through local pharmacy committees. Texas-California corridor health systems are leading this aggregation, leveraging perioperative volume scale to extract price concessions and dedicated supply security commitments from formulary winners.
North America Anesthesia Drugs Market Segmentation
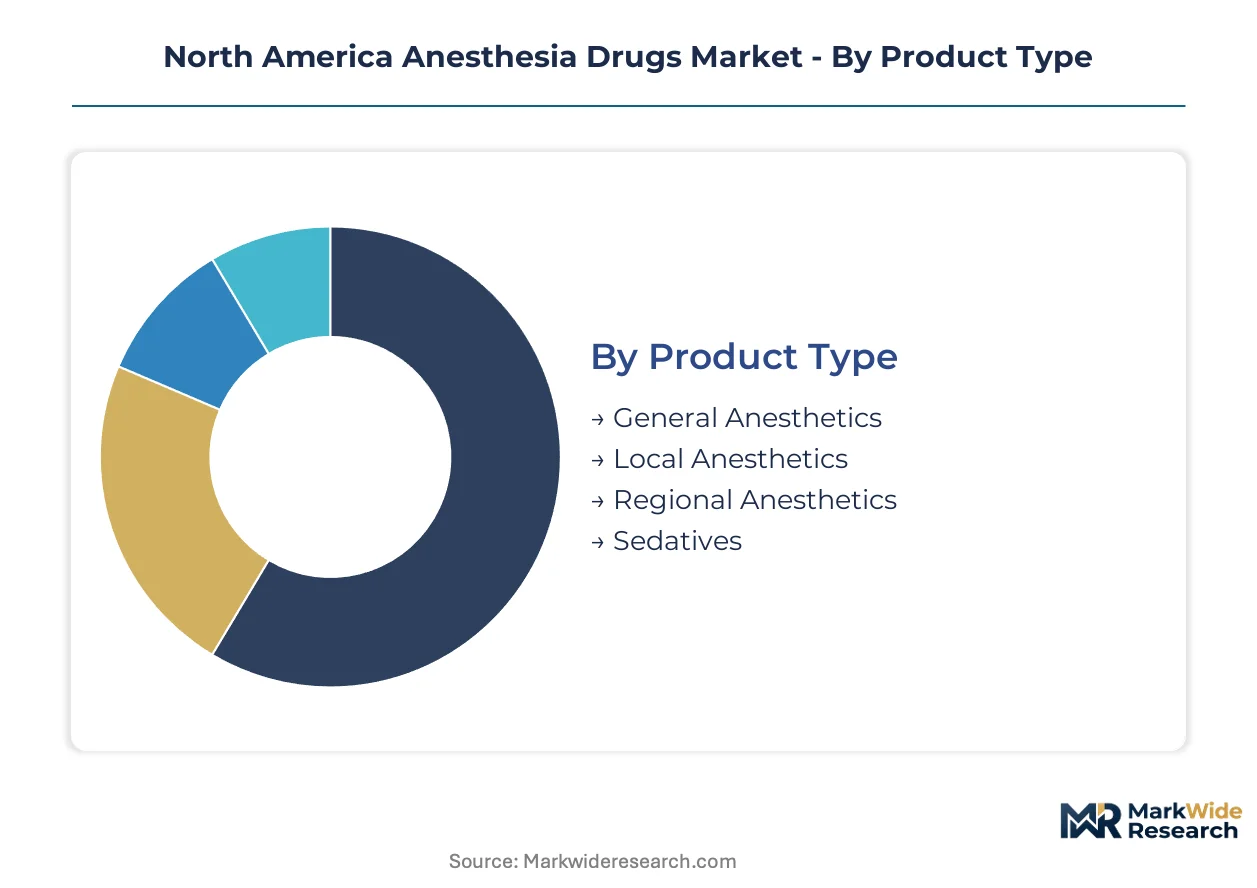
Segmentation in the North America Anesthesia Drugs Market reveals how clinical workflow requirements, regulatory pathways, and procurement economics split demand across distinct technical and channel categories. Understanding these divisions exposes where pricing power concentrates and where generic substitution accelerates.
Product Type:
Mature injectable formulations anchor procurement volumes while emerging sedation protocols reshape growth trajectories across the United States and Canada.
- General Anesthetics:These agents induce reversible unconsciousness through intravenous or inhalation routes, formulated as propofol emulsions or volatile halogenated ethers. Hospital systems in the Texas-California corridor drive procurement scale for major surgical procedures, with integrated delivery networks negotiating multi-year supply security agreements.
- Sedatives:Short-acting benzodiazepines and alpha-2 agonists enable conscious sedation protocols in outpatient settings. Ambulatory surgical centers across Florida and Arizona are expanding service lines around these agents as colonoscopy and cardiac catheterization volumes shift from inpatient facilities.
- Local Anesthetics:Amide and ester-class compounds block nerve conduction in defined anatomical regions.
- Regional Anesthetics:Epidural and spinal formulations target neuraxial anesthesia for obstetric and orthopedic procedures.
General anesthetics handle the majority of throughput; sedatives are the fastest mover on share.
Delivery Mode:
Cost tier differentiation separates capital-intensive inhalation infrastructure from flexible intravenous platforms that dominate ambulatory economics.
- Intravenous:Injectable formulations enable rapid induction and titratable depth of anesthesia through peripheral or central venous access. ASCs in Texas and California prioritize these modalities for same-day discharge protocols, compressing recovery timelines and facility utilization.
- Inhalation:Volatile agents delivered through calibrated vaporizers require scavenging systems and environmental monitoring. Hospital sustainability mandates in Ontario and Quebec are displacing desflurane in favor of sevoflurane and intravenous alternatives due to greenhouse gas intensity metrics.
- Topical:Surface-applied formulations target mucosal anesthesia for minor procedures.
- Oral:Preoperative anxiolytics and pediatric sedation agents bypass parenteral administration requirements.
Intravenous delivery commands the largest installed base; topical applications are climbing the fastest as office-based procedures expand.
End User:
Customer type fragmentation concentrates purchasing power among consolidated hospital networks while specialty pharmacies capture niche infusion protocols.
- Hospitals:Academic medical centers and community hospitals maintain captive anesthesia departments with 24/7 coverage requirements. The Texas-California corridor health systems leverage perioperative volume scale to extract formulary commitments and dedicated inventory buffers from suppliers.
- Ambulatory Surgical Centers:Freestanding facilities optimize throughput through rapid-turnover anesthesia protocols. Medicare reimbursement shifts and patient preference for same-day discharge are accelerating ASC construction across Florida, Arizona, and the Carolinas.
- Clinics:Office-based settings administer local and topical agents for dermatologic and minor surgical procedures.
- Specialty Pharmacies:Compounding and infusion-focused distributors serve home-based chronic pain management and palliative sedation protocols.
Hospitals retain the dominant share of procurement volume; ambulatory surgical centers are expanding most quickly as surgical migration accelerates.
Formulation:
Supply concentration dynamics favor sterile injectable manufacturing scale while gas production requires captive fill-finish and distribution infrastructure.
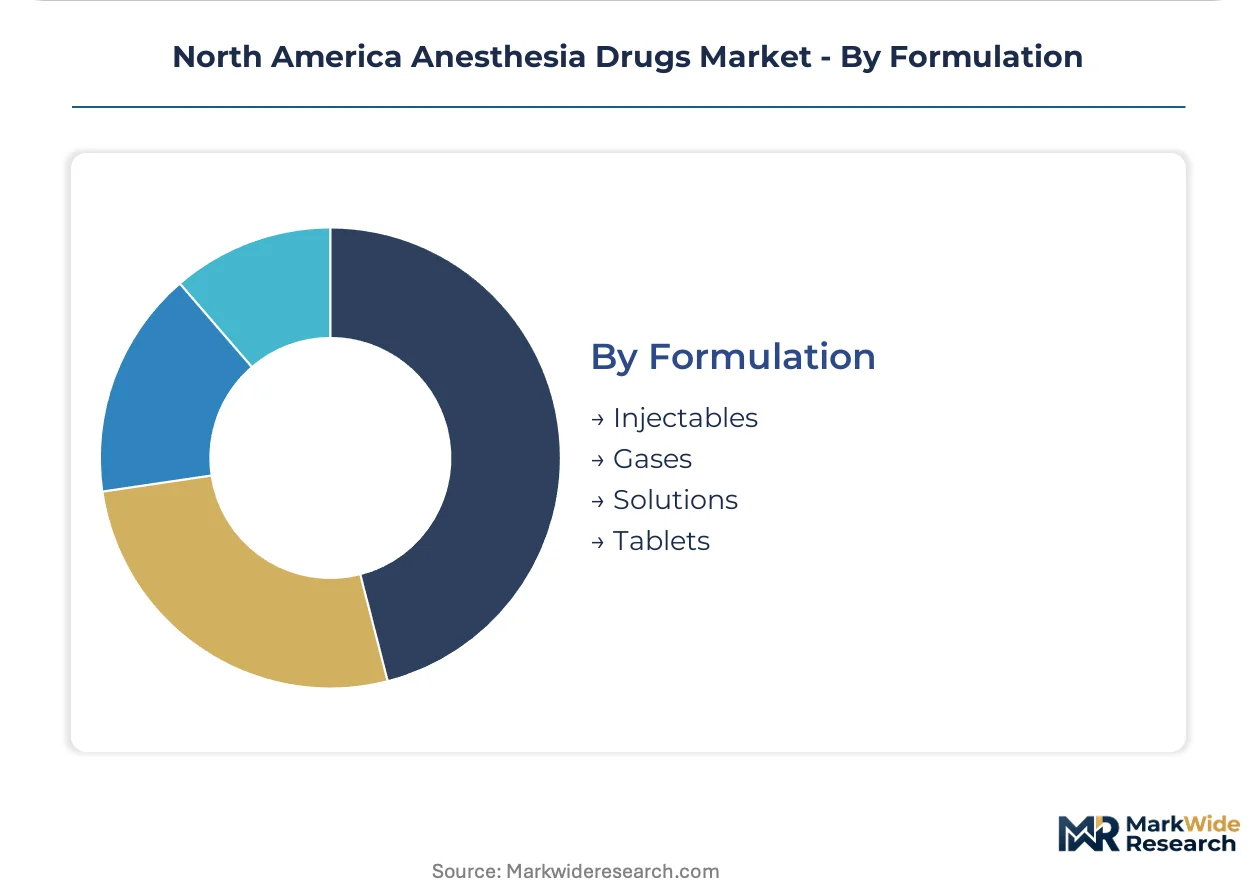
- Injectables:Sterile solutions and emulsions dominate perioperative anesthesia through precise dosing control. FDA quality metrics guidance elevates process analytical technology adoption as a compliance differentiator for facilities serving the United States market.
- Gases:Volatile anesthetics require specialized manufacturing, packaging, and cold-chain logistics. Health Canada's Therapeutic Products Directorate maintains distinct review pathways that extend authorization timelines relative to FDA processes for Canadian market entry.
- Solutions:Topical and irrigation formulations serve localized anesthesia and surgical site preparation.
- Tablets:Oral solid dosage forms target premedication and pediatric compliance.
Injectables handle the majority of throughput; gases face the steepest environmental substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 35 corridor from Texas to Minnesota anchors pharmaceutical distribution infrastructure for anesthesia drugs across the continent, with cold-chain logistics networks radiating from Dallas-Fort Worth and Chicago O'Hare hubs enabling just-in-time delivery to surgical facilities.
United States
Hospital purchasing consortiums in the Texas-California corridor leverage perioperative volume scale to negotiate multi-year supply security agreements. FDA quality metrics guidance elevates process analytical technology adoption as a compliance differentiator for sterile injectable facilities. Academic medical centers in Houston and Boston pilot target-controlled infusion platforms for total intravenous anesthesia protocols.
Canada
Health Canada's Therapeutic Products Directorate maintains distinct review pathways that extend authorization timelines relative to FDA processes. Provincial health authorities in Ontario and Quebec centralize anesthesia drug tenders, creating volume aggregation opportunities for approved suppliers. Hospital sustainability mandates in Toronto and Vancouver displace desflurane in favor of sevoflurane and intravenous alternatives.
Mexico
COFEPRIS regulatory convergence with FDA standards accelerates market entry for generic injectable manufacturers. Manufacturing clusters in Mexico State and Jalisco supply active pharmaceutical ingredients to North American formulators. Cross-border logistics infrastructure through Laredo-Nuevo Laredo enables rapid replenishment of critical anesthesia inventories.
North America Anesthesia Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in active pharmaceutical ingredient and sterile manufacturing niches. The vendor base organizes around three archetypes: diversified pharmaceutical conglomerates with captive anesthesia portfolios, mid-cap generic injectable specialists, and regional compounding pharmacies serving niche infusion protocols. Consolidation pressures favor scale-driven players with integrated distribution networks. Strategic partnerships between drug formulators and delivery device manufacturers reshape competitive positioning.
Within the diversified pharmaceutical tier, Pfizer Inc and Baxter International anchor competitive dynamics through manufacturing scale and integrated delivery network relationships. Fresenius SE & Co KGaA occupies a distinct position bundling anesthesia and critical care portfolios for hospital channel penetration. These three entities exemplify how captive production capabilities and formulary depth create defensive moats against generic substitution pressures.
| Leading Market Players |
|---|
| F Hoffmann-La Roche Ltd |
| Pfizer Inc |
| Baxter International |
| Eisai Co Ltd |
| B Braun SE |
| Fresenius SE & Co KGaA |
| Novartis AG |
| Avet Pharmaceuticals Inc |
| AbbVie Inc |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient manufacturing for propofol and midazolam concentrates in India and China funnels pricing power to downstream formulators with FDA-approved sterile injectable facilities. Hospital purchasing consortiums extract volume concessions while generic manufacturers absorb margin compression from consolidated procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs anesthesia drug procurement. Price differentiation centers on FDA bioequivalence certification tier and volume scale commitments from integrated delivery networks. Cost compression in the generic injectable tier is intensifying because abbreviated new drug application approvals accelerate competitor entry. Ambulatory surgical centers exhibit the highest price sensitivity due to fixed reimbursement rates, while academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
Export-control scrutiny on pharmaceutical manufacturing equipment constrains capacity expansion for sterile injectable facilities serving North America. API production draws from India, China, and Italy, with propofol emulsion raw materials resting on soybean oil and egg lecithin supply chains. Single-source vulnerability in halogenated ether precursors creates exposure to geopolitical disruption. Distribution runs through cold-chain logistics networks radiating from Dallas-Fort Worth and Chicago O'Hare to surgical facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against intravenous alternatives displacing inhalation anesthetics under hospital sustainability mandates.
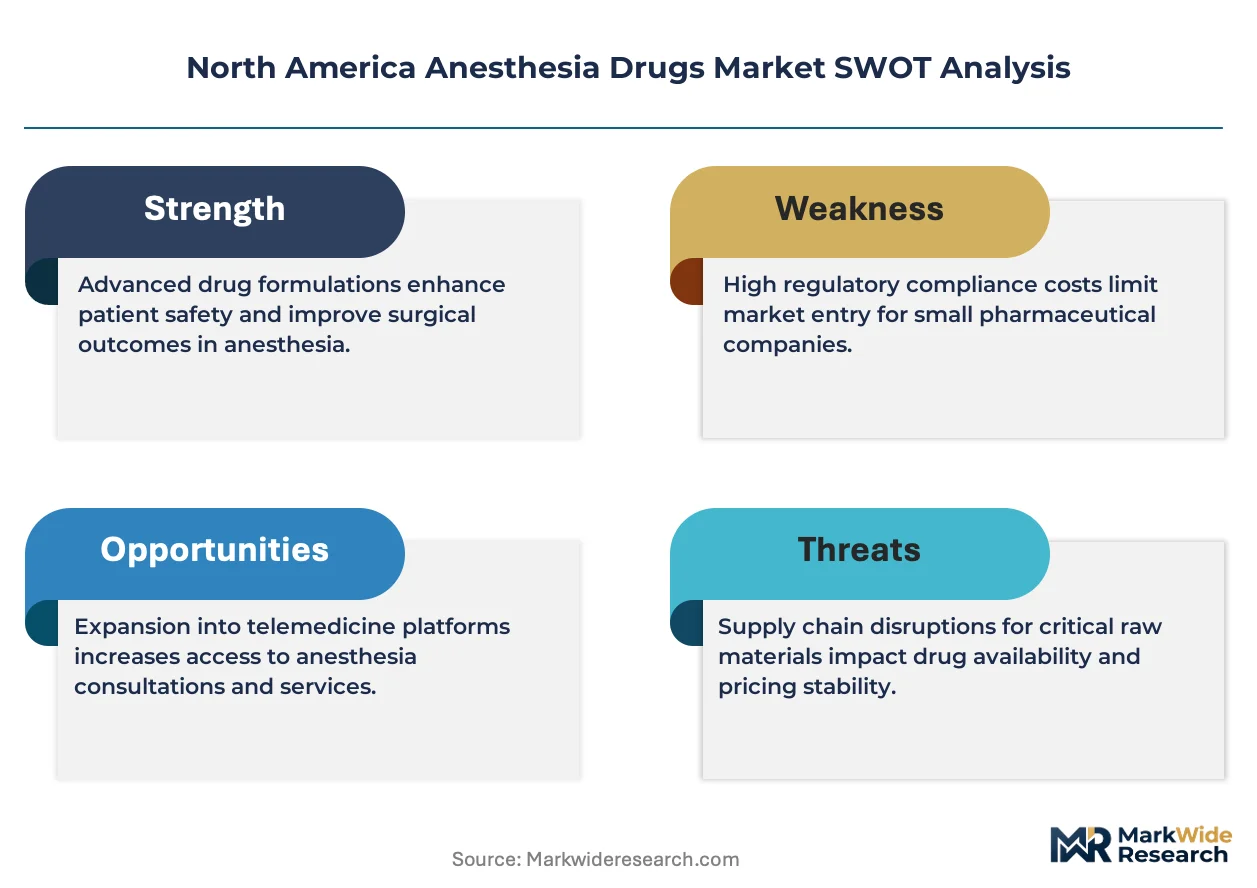
For Market Incumbents: Harden formulary position through backward integration into API manufacturing for propofol and midazolam. Secure multi-year supply security agreements with Texas-California corridor health systems before provincial tender consolidation in Ontario and Quebec accelerates. FDA quality metrics guidance elevates process analytical technology investment as a compliance differentiator against mid-cap generic specialists. For New Entrants and Emerging Players: Freestanding ambulatory surgical centers in Florida and Arizona represent the most penetrable entry point for short-acting sedation portfolios. Conscious sedation protocols in gastroenterology suites offer a second white-space channel with lower capital barriers than hospital formulary displacement. A compounding pharmacy partnership model bypasses direct manufacturing scale requirements while building clinical credibility. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap generic injectable specialists with Health Canada parallel approvals and real-time release testing capabilities. The five-to-ten year viability window favors suppliers with dual FDA-Health Canada regulatory packages over single-market players. Watch for Health Canada ICH Q12 implementation timelines as an inflection signal for post-approval management cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Investment | FDA quality metrics guidance rewards facilities with mature continuous manufacturing data packages through expedited review consideration. |
| Health Canada Parallel Approval Pathway | Ontario and Quebec provincial tender consolidation creates volume aggregation opportunities for dual-approved suppliers. |
| Target-Controlled Infusion Platform Partnership | Academic medical centers in Houston and Boston pilot pharmacokinetic modeling software for total intravenous anesthesia protocols. |
| 340B Program Participation Expansion | Eligible disproportionate share hospitals access discounted pricing mechanisms improving margin capture on high-volume generic anesthetics. |
| Preoperative Assessment Clinic Integration | Bundled anesthesia and critical care portfolios extend into perioperative medicine workflows capturing value upstream of the operating room. |
Research Methodology
Initial hypotheses were tested against primary input from anesthesiology department heads, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads at generic injectable manufacturers and refined through secondary validation. FDA filings, Health Canada Therapeutic Products Directorate submissions, hospital procurement databases, and GPO contract repositories anchored quantitative estimates. Bottom-up facility-level capacity assessments and top-down therapeutic category spend analysis provided triangulation checks.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include product type, delivery mode, end-user channel, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories, reimbursement rate assumptions, and generic substitution elasticity curves. Propofol emulsion manufacturing capacity and CRNA staffing ratios served as industry-specific forecast inputs.
Practitioners should monitor FDA ANDA approval velocity and Health Canada ICH Q12 implementation timelines for early signals of competitive intensity shifts. Forecasts reflect assumptions around perioperative volume migration to ambulatory settings and inhalation anesthetic environmental substitution rates. Material shifts in API export-control regimes or hospital sustainability mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Budesonide Market