
 Portable Cancer Screen Devices Market | 2026-2036
Portable Cancer Screen Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Cancer Screen Devices Market Analytics
Portable diagnostic manufacturing is consolidating in South Korea and Taiwan as semiconductor foundries dedicate cleanroom capacity to biosensor wafer production. Niramai leverages thermal imaging AI to sustain leadership in non-contact breast screening across Indian outpatient networks. Forward Science anchors North American distribution through dental and oral cavity detection platforms. Zilico competes in cervical cancer applications with electrical impedance spectroscopy systems that occupy a distinct regulatory pathway from optical competitors.
Portable cancer screen devices are compact, battery-powered diagnostic systems that detect malignant tissue through miniaturized sensors, typically operating at wavelengths from visible to near-infrared with power draws below 50 watts for field deployment. Their primary purpose is enabling point-of-care oncology screening outside centralized hospital radiology departments, reducing patient travel burdens and accelerating triage decisions. Blood test products lead volume shipments due to lower capital requirements and compatibility with existing phlebotomy infrastructure, while liquid biopsy technology captures the fastest expansion as circulating tumor DNA assays migrate from reference laboratories to handheld formats. Home care end users represent an emerging margin pool where subscription-based monitoring models offset lower per-unit pricing.
FDA 510(k) clearances and CE marking under the EU MDR shape product development roadmaps, with FDA breakthrough device designations accelerating access for AI-enhanced imaging platforms. India's CDSCO medical device rules and BIS electrical safety standards determine import eligibility and local manufacturing incentives for multinational suppliers. Stakeholders must monitor how WHO prequalification criteria for cancer diagnostics influence procurement decisions in low and middle-income health systems.
Market Dynamics
Semiconductor foundries in South Korea and Taiwan are dedicating cleanroom capacity to biosensor wafer production, compressing sensor costs and redrawing competitive boundaries for portable diagnostic manufacturers.
Growth Catalysts
- FDA Breakthrough Device Designations:Accelerated review pathways for AI-enhanced imaging platforms reduce time-to-market for novel screening modalities in the US oncology sector.
- India CDSCO Clearance Pathways:Streamlined product registration timelines for thermal imaging units drive adoption across Maharashtra, Karnataka, and Tamil Nadu hospital networks.
- Liquid Biopsy Miniaturization:Circulating tumor DNA assays migrating from reference laboratories to handheld formats expand addressable screening populations beyond centralized facilities.
Market Restraints
- Cleanroom Capacity Constraints:Dedicated foundry allocation for biosensor wafers concentrates supply risk in two East Asian manufacturing clusters.
- EU MDR Compliance Burden:Enhanced clinical evidence requirements for CE marking extend certification timelines and inflate regulatory spend for optical imaging platforms.
- Electrical Safety Certification:India's BIS standards for battery-powered devices create additional testing layers before import eligibility.
Strategic Opportunities
- Home Care Subscription Models:Recurring revenue structures for continuous monitoring offset per-unit pricing pressure among direct-to-consumer channels.
- WHO Prequalification Criteria:Alignment with procurement standards for low and middle-income health systems unlocks institutional purchasing in Sub-Saharan Africa and Southeast Asia.
- Thermal-AI Convergence:Integration of non-contact temperature mapping with machine learning classification creates differentiation in outpatient breast screening workflows.
Industry Challenges
- Multidisciplinary Talent Scarcity:Convergence of semiconductor fabrication, clinical oncology, and regulatory affairs expertise strains hiring pipelines for product development teams.
- Legacy Radiology Integration:Point-of-care devices must interface with hospital PACS and EMR systems that lack standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Cancer Screen Devices Market |
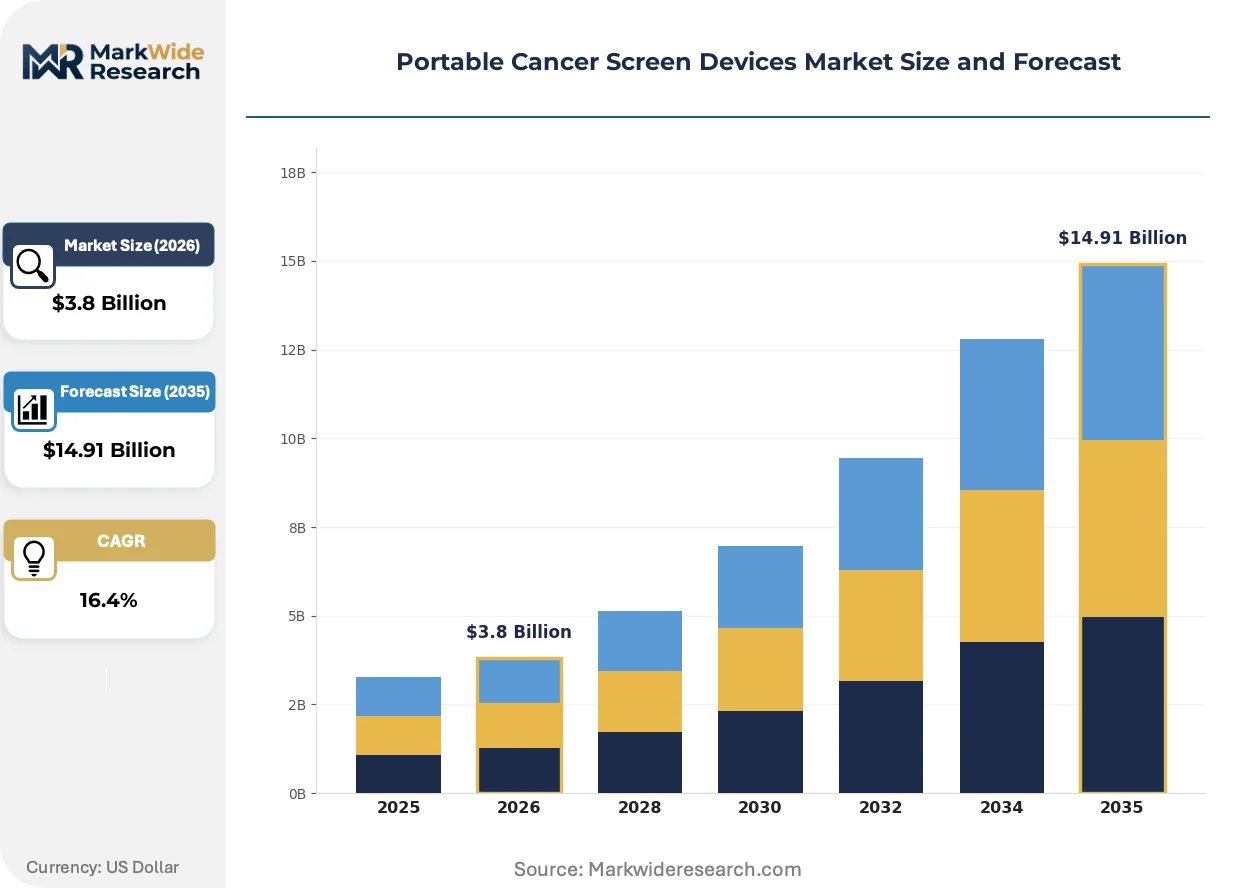
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, MRI, CT Scan, Blood Test Technology: Imaging, Biopsy, Liquid Biopsy, Spectroscopy End User: Hospitals, Clinics, Home Care, Diagnostic Centers Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesalers |
| Companies Covered | Niramai, Forward Science, LED Apteryx, Breastlight, Zilico, Braster, Bremed, TruScreen, AdDent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Cancer Screen Devices Market Evolving Landscape
Portable cancer screening is undergoing platform-level transformation as sensor miniaturization, regulatory acceleration mechanisms, and decentralized care models simultaneously reshape product roadmaps and go-to-market architectures.
Near-infrared spectroscopy is rewriting tissue characterization economics by enabling real-time malignancy assessment without biopsy referral. Community health centers in rural India are piloting these devices for oral cavity screening, compressing the diagnostic pathway from weeks to minutes. The technology is forcing recalibration of specialist referral rates and reimbursement structures across primary care networks.
CE marking under the EU MDR is elevating clinical evidence thresholds for optical cancer diagnostics, favoring sponsors with robust prospective trial portfolios. Manufacturers are responding by front-loading pivotal studies and establishing European notified body relationships earlier in development cycles. Electrical impedance spectroscopy platforms face distinct scrutiny compared to thermal imaging competitors due to novel mechanism-of-action classification.
Hospital procurement committees are unbundling device acquisition from service contracts, separating capital expenditure from preventive maintenance and software update obligations. This disintermediation pressures original equipment manufacturers to demonstrate standalone device reliability or build captive service capabilities. The pattern is most pronounced in Indian metropolitan hospital networks negotiating multi-unit thermal imaging deployments.
Portable Cancer Screen Devices Market Segmentation
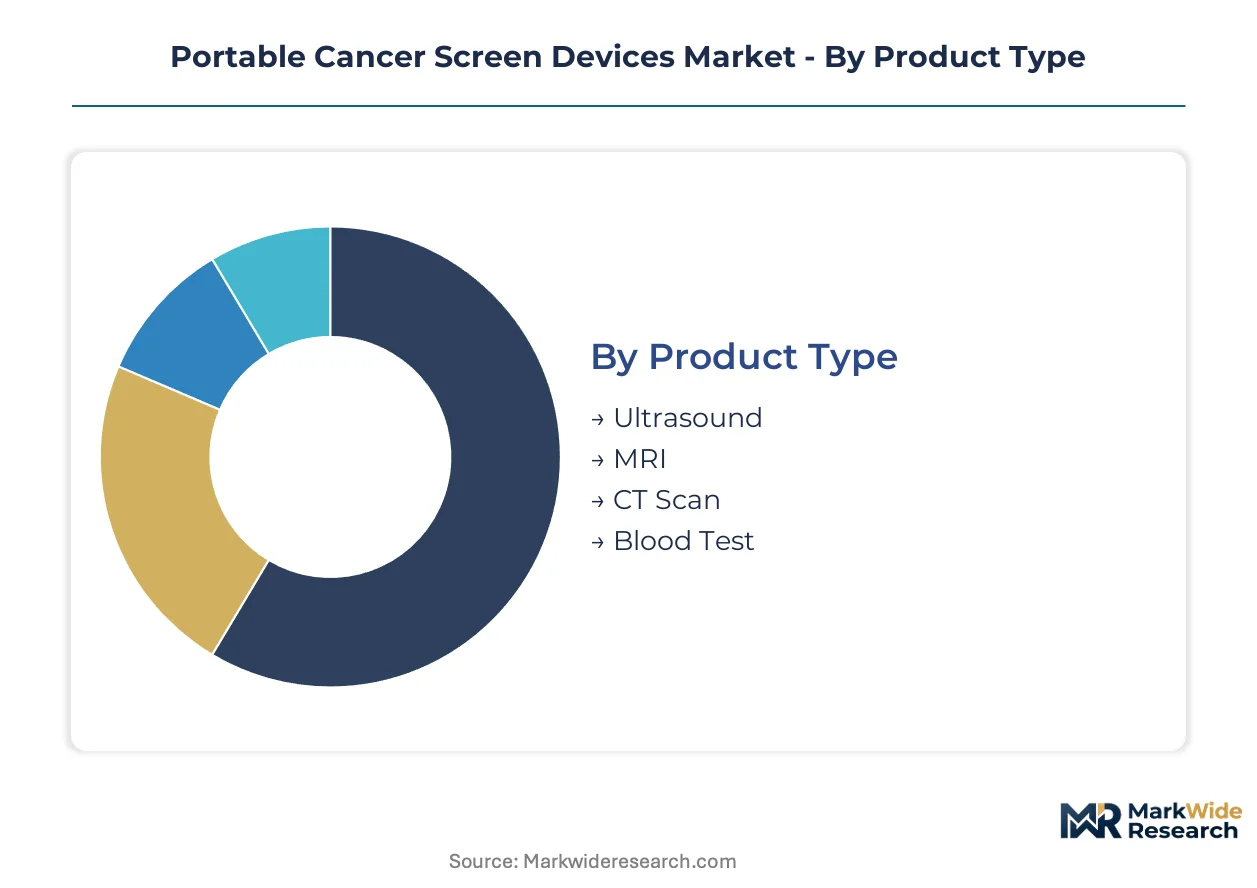
Portable cancer screening devices fragment across four structural dimensions that determine procurement workflows, regulatory pathways, and margin profiles. Product type and technology choices anchor capital expenditure decisions, while end-user setting and distribution channel shape service intensity and pricing architecture.
Product Type:
Standalone imaging modalities dominate hospital radiology departments, while embedded sensor formats penetrate point-of-care and home settings through integration with mobile platforms.
- Blood Test:Capillary or venous sample analysis using miniaturized assay cartridges compatible with existing phlebotomy infrastructure. Demand concentrates in diagnostic centers across Maharashtra and Karnataka where CDSCO-cleared devices accelerate patient throughput without radiologist involvement.
- Ultrasound:Handheld transducer arrays operating at 5-15 MHz with battery-powered consoles for soft tissue characterization. Tamil Nadu oncology clinics deploy these for thyroid and breast screening triage, compressing specialist referral timelines from weeks to same-day decisions.
- CT Scan:Cone-beam miniaturized systems with reduced radiation profiles for lung nodule detection.
- MRI:Low-field portable magnets for extremity and superficial tissue assessment.
Blood test leads volumes today; ultrasound is gaining share fastest.
Technology:
Cost tiers separate capital-intensive imaging platforms from disposable-consumable assay formats, with hybrid approaches emerging at mid-price points.
- Liquid Biopsy:Circulating tumor DNA and circulating tumor cell capture from peripheral blood samples using microfluidic chips. Home care subscription models in Indian metropolitan networks offset lower per-unit pricing through recurring revenue structures.
- Imaging:Optical coherence tomography, photoacoustic, and thermal infrared systems for non-invasive tissue visualization. Maharashtra hospital networks prioritize thermal-AI convergence for outpatient breast screening workflows.
- Biopsy:Image-guided core needle and fine-needle aspiration devices for confirmatory tissue sampling.
- Spectroscopy:Near-infrared and Raman scattering systems for real-time molecular characterization.
Imaging leads volumes today; liquid biopsy is expanding most quickly.
End User:
Application intensity varies from high-acuity oncology decision-making to preventive screening workflows, determining device specification and service bundling requirements.
- Hospitals:Multi-modality deployment within radiology and oncology departments requiring PACS integration and FDA 510(k) or CE marking under EU MDR. Karnataka tertiary centers drive thermal imaging adoption through CDSCO-accelerated procurement pathways.
- Home Care:Direct-to-consumer devices with cloud-connected monitoring platforms and subscription-based software updates. Tamil Nadu pilot programs test oral cavity screening near-infrared spectroscopy for rural community health worker deployment.
- Clinics:Outpatient-focused systems emphasizing throughput and operator-independent diagnostic output.
- Diagnostic Centers:High-volume reference laboratory settings with centralized quality control.
Hospitals lead volumes today; home care is climbing the fastest.
Distribution Channel:
Customer type determines whether procurement flows through institutional contracting, retail accessibility, or intermediary inventory management.
- Direct Sales:Manufacturer field teams negotiating multi-unit thermal imaging deployments with Maharashtra, Karnataka, and Tamil Nadu hospital networks. Procurement committees unbundle device acquisition from service contracts, separating capital expenditure from preventive maintenance obligations.
- Medical Distributors:Regional inventory and technical service capabilities for clinics and diagnostic centers requiring local installation support.
- Online Retail:Direct-to-consumer channels for home care devices with subscription onboarding.
- Wholesalers:Bulk procurement intermediaries serving institutional buyers with standardized specifications.
Direct sales leads volumes today; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing manufacturing footprints as portable diagnostic producers relocate to jurisdictions offering streamlined device clearance pathways and concentrated semiconductor infrastructure. Cost-of-compliance gaps between major markets are accelerating facility migration decisions.
United States
FDA breakthrough device designations compress review timelines for AI-enhanced imaging platforms, drawing venture funding into California and Massachusetts development clusters. The 510(k) pathway remains the dominant regulatory on-ramp for optical cancer diagnostics. Boston-area medical device incubators host multiple liquid biopsy miniaturization programs targeting home care deployment.
India
Maharashtra, Karnataka, and Tamil Nadu hospital networks drive thermal imaging adoption through CDSCO-accelerated procurement timelines. The country's medical device rules and BIS electrical safety standards determine import eligibility for multinational suppliers. Bangalore-based manufacturing partnerships are emerging for biosensor assembly to satisfy domestic content requirements.
Germany
CE marking under EU MDR elevates clinical evidence thresholds, favoring sponsors with robust prospective trial portfolios. Bavarian precision optics clusters supply near-infrared spectroscopy components to portable device integrators. Munich medical technology parks host regulatory affairs specialists navigating notified body relationships for optical imaging platforms.
South Korea
Semiconductor foundries in Gyeonggi Province dedicate cleanroom capacity to biosensor wafer production, compressing sensor costs for portable diagnostic manufacturers. MFDS device approval pathways support rapid market entry for miniaturized assay formats. Seoul-based OEMs are vertically integrating into MEMS fabrication to secure supply continuity.
Japan
PMDA consultation programs de-risk development for handheld cancer detection devices targeting aging rural populations. Nagoya-area manufacturing clusters produce miniaturized optical components for point-of-care deployment. METI funding initiatives support liquid biopsy platform development for home-based monitoring applications.
Portable Cancer Screen Devices Market Competitive Landscape
South Korean and Taiwanese producers anchor the component supply tier; US and European specialists hold the regulatory clearance and clinical validation tier. The vendor structure concentrates around semiconductor fabrication capabilities and notified body relationships rather than end-brand recognition. Three archetypes dominate: foundry-integrated component suppliers, regulatory-navigating platform developers, and AI-software layer specialists. Competitive moves center on foundry capacity reservations and European notified body pre-submission strategies.
Within the thermal-AI convergence archetype, Niramai occupies a position exemplifying non-contact breast screening platform development. Forward Science and Zilico sit within distinct regulatory pathway categories—oral cavity detection and electrical impedance spectroscopy respectively—demonstrating how mechanism-of-action classification shapes competitive positioning. These three anchors illustrate the market's segmentation across optical, impedance, and multi-modal detection methodologies.
| Leading Market Players |
|---|
| Niramai |
| Forward Science |
| LED Apteryx |
| Breastlight |
| Zilico |
| Braster |
| Bremed |
| TruScreen |
| AdDent |
| Others |
Value Network & Pricing Analysis
Performance-grade divergence between FDA breakthrough-designated AI imaging platforms and unregulated wellness devices manifests in pricing spreads exceeding tenfold, with premium tiers commanding bundled service contracts while commodity units compete on unit economics alone. This bifurcation concentrates margin capture among CDSCO-cleared suppliers in Indian metropolitan networks and FDA-authorized developers in US oncology clusters, leaving undifferentiated hardware manufacturers exposed to foundry pricing power and distributor margin compression.
Pricing Analysis
Distributor margin layers absorb 25-40 points between South Korean foundry gate pricing and Indian hospital network procurement committees, compressing platform developer returns. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced thermal imaging with predictive analytics subscriptions from basic optical devices without connectivity. Pricing pressure stems from semiconductor foundry capacity reservation fees rising as biosensor wafer demand outpaces cleanroom expansion. Home care direct-to-consumer channels exhibit highest price sensitivity, while tertiary oncology centers in Maharashtra and Karnataka prioritize clinical validation over unit cost.
Supply Chain Analysis
Specialized cleanroom technician scarcity in Gyeonggi Province and Hsinchu Science Park constrains biosensor wafer throughput expansion despite capital equipment availability. Manufacturing gravity centers on South Korea, Taiwan, and emerging Indian assembly partnerships for domestic content compliance. Critical input dependencies include silicon photonics substrates, microfluidic cartridge polymers, and AI inference chips. Single-source vulnerability concentrates in two East Asian foundry clusters exposed to regional logistics disruption. Distribution runs through medical device distributors with regional technical service capabilities, bypassing generalist wholesalers for installation-intensive imaging platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in portable cancer screening rest on semiconductor cost curves flattening as foundry capacity dedicates to biosensor production, while premium-tier demand concentrates in CDSCO-accelerated Indian procurement and FDA breakthrough-designated US deployments.
For Market Incumbents: Anchor defensive positioning through captive foundry capacity reservations in Gyeonggi Province or Hsinchu, securing wafer supply continuity against emerging entrant allocation competition. Deepen regulatory moats by front-loading European notified body relationships for EU MDR CE marking, extending certification timelines that strain optical imaging competitors without robust prospective trial portfolios. Prioritize PACS and EMR integration standardization to lock in hospital radiology department switching costs. For New Entrants and Emerging Players: Begin with thermal-AI convergence for outpatient breast screening in Indian diagnostic centers, where CDSCO clearance pathways compress registration timelines relative to FDA 510(k) review. Target rural community health worker deployment in Tamil Nadu pilot programs testing near-infrared spectroscopy oral cavity screening, exploiting underpenetrated primary care networks. Pursue subscription-based home care monitoring models with cloud-connected platforms, offsetting per-unit pricing pressure through recurring revenue structures. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory clearance portfolios compound faster than standalone R&D economics can replicate, favoring acquisition of CDSCO-cleared thermal imaging platforms or FDA breakthrough-designated liquid biopsy miniaturization programs. Long-term viability across the analysis window hinges on WHO prequalification alignment for institutional purchasing in Sub-Saharan Africa and Southeast Asia. Monitor MFDS approval velocity in South Korea as inflection indicator for foundry-integrated OEM competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Accelerated Registration | Compresses product entry timelines for thermal imaging units in Maharashtra hospital networks. |
| FDA Breakthrough Device Designation | Reduces review duration for AI-enhanced imaging platforms targeting US oncology clinics. |
| Foundry Capacity Reservation | Secures biosensor wafer allocation against cleanroom constraints in Gyeonggi Province. |
| European Notified Body Pre-Submission | Front-loads clinical evidence requirements for EU MDR CE marking on optical diagnostics. |
| WHO Prequalification Alignment | Unlocks institutional procurement in Sub-Saharan Africa and Southeast Asia health systems. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers at tertiary oncology centers, CDSCO regulatory consultants, and GPO contracts specialists grounded qualitative findings in operational realities across Maharashtra, Karnataka, and Tamil Nadu. Secondary validation drew from FDA 510(k) clearance databases, CDSCO medical device registration records, EU MDR notified body guidance documents, and WHO prequalification criteria for cancer diagnostics. Bottom-up device shipment estimates triangulated against top-down addressable screening population models.
Segment-level revenue trajectories across the projection horizon reflect product type, technology modality, end-user setting, and distribution channel dimensions, with liquid biopsy miniaturization and thermal-AI convergence tracked as distinct growth vectors. CAGRs derived from fitted adoption curves incorporating regulatory clearance velocity, reimbursement pathway maturity, and foundry capacity expansion schedules. Forecast inputs included semiconductor cost compression rates and CDSCO registration timeline distributions.
Several conditions sit outside the modeled scope, including unforeseen EU MDR clinical evidence requirement amendments, geopolitical disruption to Taiwan Strait logistics corridors, and WHO prequalification criteria revisions for low-income health system procurement. Forecasts reflect documented assumptions regarding foundry capacity allocation continuity and regulatory pathway stability. Material deviation in FDA breakthrough designation velocity or CDSCO clearance backlog accumulation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market