
 Latin America Breast Biopsy Needle Market | 2026-2036
Latin America Breast Biopsy Needle Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Breast Biopsy Needle Market Foresight
Modular biopsy system bundling is consolidating purchasing decisions across Latin American hospital procurement offices. Hologic leverages integrated imaging-needle platforms to anchor premium positioning in Brazilian diagnostic centers. Becton, Dickinson and Company sustains broad distribution reach through direct sales channels spanning Mexico and Colombia. Cook Medical specializes in vacuum-assisted configurations that occupy the fastest-growing procedural segment in Argentine oncology clinics.
A breast biopsy needle is a hollow, stainless steel or nitinol instrument, typically 8-20 gauge in diameter, designed to extract tissue cores or cellular samples from suspicious breast lesions under image guidance for histopathological analysis. Vacuum-assisted technology leads procedural volume due to larger specimen yields and reduced sampling error, while ultrasound-guided deployment dominates technology selection because of lower capital requirements and wider clinic accessibility compared to MRI-guided alternatives.
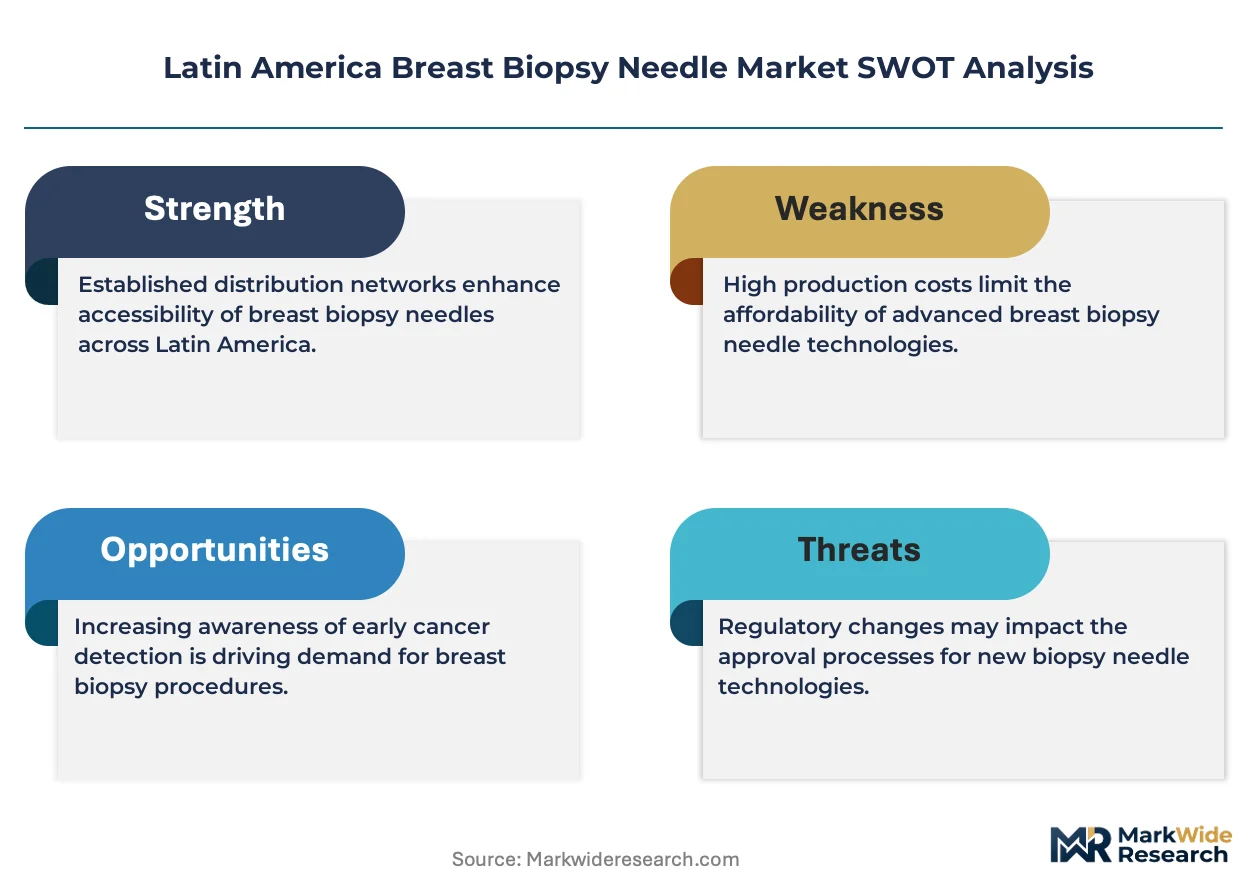
ANVISA governs medical device registration and post-market surveillance in Brazil, while Mexico's COFEPRIS enforces equivalent conformity assessment pathways; both regulators extend approval timelines for non-harmonized standards, creating barriers for unestablished suppliers. Argentina's national administration of medicines, food and medical technology (ANMAT) maintains parallel import licensing requirements that fragment cross-border distribution efficiency. Stakeholders must monitor pending regulatory convergence discussions across Mercosur to anticipate simplified market entry protocols.
Market Dynamics
ANVISA's sterility and biocompatibility standards are compressing product registration timelines, forcing suppliers to front-load compliance investment before Brazilian market entry while metropolitan hospital networks consolidate procurement around integrated imaging-needle platforms.
Growth Catalysts
- Vacuum-Assisted Biopsy (VAB) Protocols:Argentine oncology clinics are expanding VAB procedures due to larger specimen yields and reduced sampling error, driving replacement demand for legacy core needle systems.
- ANVISA Harmonization Discussions:Pending Mercosur regulatory convergence talks are creating anticipatory inventory builds among distributors preparing for simplified cross-border entry protocols.
- Brazilian Screening Expansion:Municipal breast cancer screening programs in São Paulo and Rio de Janeiro metropolitan networks are procuring ultrasound-guided needle systems at volume scale.
Market Restraints
- Nitinol Raw Material Concentration:Superelastic alloy supply chains concentrate among a limited set of Asian specialty metallurgy suppliers, exposing Brazilian manufacturers to input cost volatility and extended lead times.
- COFEPRIS Non-Harmonized Pathways:Mexico's regulator extends approval timelines for devices lacking ISO 13485 certification equivalence, creating friction for first-time entrants without established local technical files.
- MRI-Guided System Substitution:Capital-intensive MRI-guided biopsy platforms face displacement pressure from lower-cost ultrasound alternatives, constraining premium segment expansion outside tertiary academic centers.
Strategic Opportunities
- Colombian Diagnostic Network Buildout:Bogotá and Medellín private hospital chains are establishing dedicated breast imaging centers with bundled needle-procurement contracts open to new suppliers.
- Disposable Single-Use Convergence:Cross-category infection control protocols are accelerating integration between disposable needle systems and automated specimen handling workflows.
- ANMAT Import Licensing Reform:Argentina's pending streamlining of parallel import requirements would reduce cross-border distribution fragmentation for established Mercosur suppliers.
Industry Challenges
- Interventional Radiology Training Bottlenecks:Brazilian and Mexican teaching hospitals report insufficient fellowship slots for image-guided biopsy specialization, constraining procedural volume expansion.
- Legacy PACS Integration Complexity:New needle-tracking software encounters compatibility friction with entrenched picture archiving systems in Colombian and Chilean public hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Breast Biopsy Needle Market |
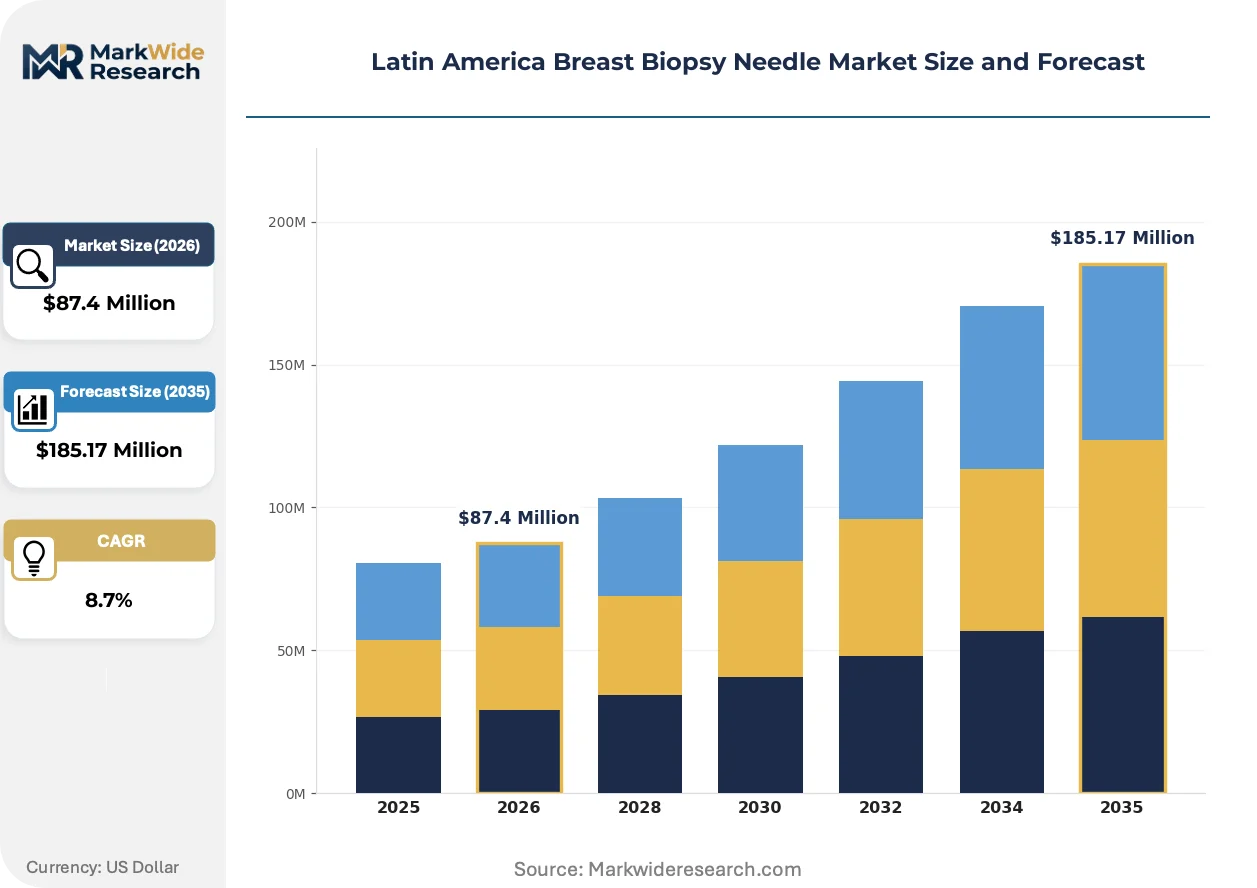
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Needle, Vacuum-Assisted, Fine Needle, Stereotactic End User: Hospitals, Diagnostic Centers, Oncology Clinics, Research Institutions Technology: Ultrasound-Guided, MRI-Guided, X-Ray Guided, Palpation Distribution Channel: Direct Sales, Retail, E-Commerce, Distributors |
| Companies Covered | Hologic, Becton, Dickinson and Company, Medtronic, Boston Scientific Corporation, Cook Medical, Leica Biosystems, Argon Medical Devices, Fujifilm Medical Systems, C.R. Bard, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Breast Biopsy Needle Market Shifts & Advancements
Device miniaturization and real-time imaging fusion are compressing the gap between diagnostic accuracy and procedural accessibility across Latin American outpatient settings.
Ultrasound-guided vacuum-assisted biopsy is overtaking stereotactic core needle methods in Brazilian diagnostic centers. The technology eliminates dedicated mammography suite requirements. Community oncology clinics in São Paulo's peripheral zones are adopting portable ultrasound-VAB configurations at accelerating pace. This shift is overtaking the traditional hospital-centric deployment model and compressing capital barriers for mid-tier facilities.
COFEPRIS is tightening post-market surveillance obligations for Class III invasive devices through expanded adverse event reporting mandates. Mexican distributors must now maintain localized complaint handling infrastructure. Breast biopsy needle importers face heightened documentation burdens for batch traceability. The policy is forcing supply chain restructuring toward authorized representative models with dedicated regulatory affairs capacity.
Hospital procurement offices across Latin America are unbundling service contracts from capital equipment purchases. Brazilian metropolitan networks now negotiate needle supply agreements separately from imaging platform leases. This pattern is displacing the historical bundled-procurement norm where device manufacturers captured recurring consumable revenue through exclusive compatibility clauses. The behavioral shift is most visible in Rio de Janeiro's state hospital consortium, where competitive tendering for needles now occurs on 12-month cycles independent of imaging vendor relationships.
Latin America Breast Biopsy Needle Market Segmentation
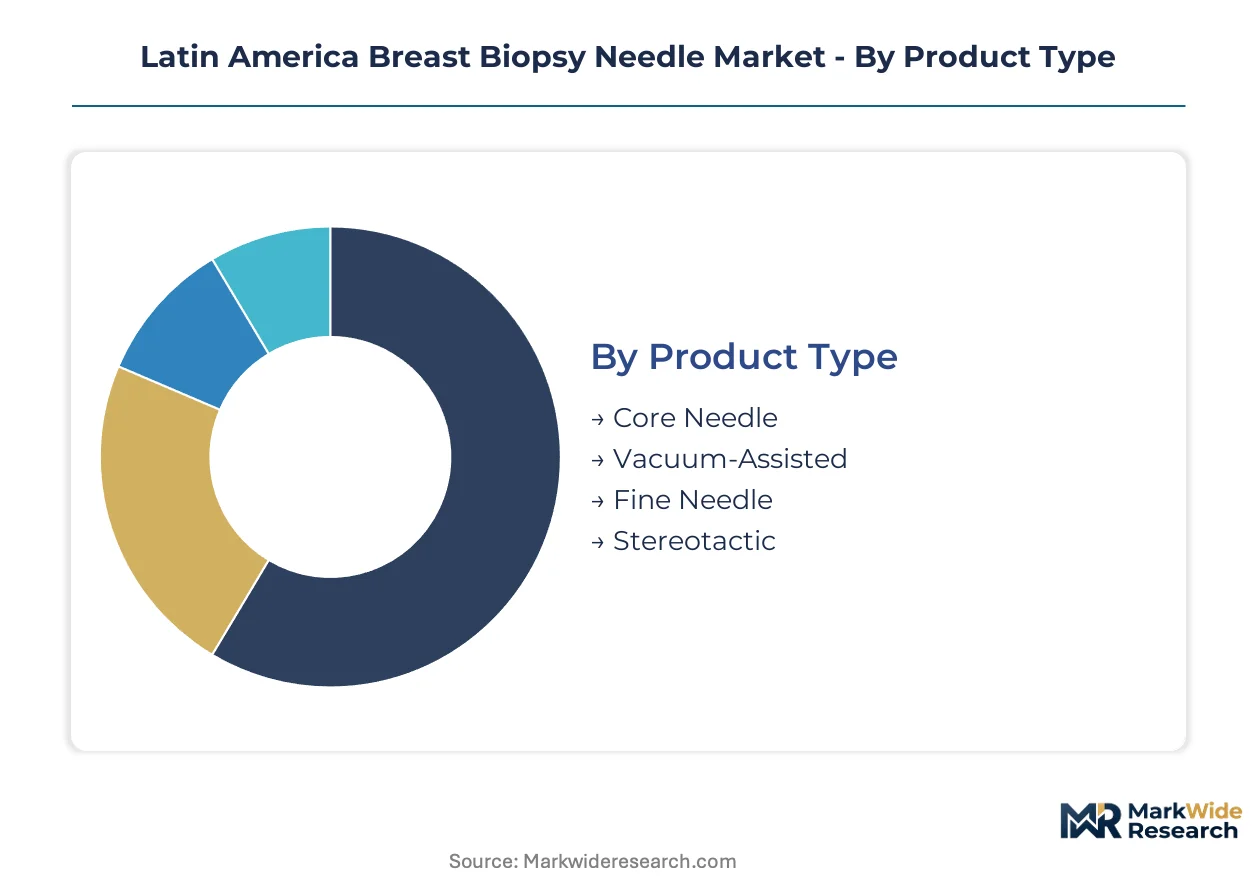
Segmentation in the Latin America breast biopsy needle market reveals how procurement priorities diverge across clinical settings and imaging modalities. Brazilian metropolitan networks and Argentine oncology clinics drive distinct demand patterns that reshape supplier positioning.
Product Type:
Volume concentrates in established core needle systems while premium capture shifts toward vacuum-assisted platforms with superior specimen yields.
- Core Needle:Hollow 14-18 gauge stainless steel instruments extract tissue cores through manual spring-loaded mechanisms. São Paulo municipal hospital networks procure these systems at scale for screening program saturation, though reimbursement compression limits margin expansion.
- Vacuum-Assisted:Continuous suction mechanisms enable larger contiguous tissue samples through single insertion points. Argentine oncology clinics in Buenos Aires and Córdoba are displacing legacy core systems here, drawn by reduced sampling error rates and downstream pathology cost savings.
- Fine Needle:20-25 gauge aspirational devices for cytological sampling in resource-constrained settings.
- Stereotactic:Mammography-guided directional configurations for non-palpable calcification targeting.
Today's leader: Core Needle. Tomorrow's challenger: Vacuum-Assisted.
End User:
Procurement authority is fragmenting as diagnostic centers gain independent purchasing autonomy previously concentrated in hospital networks.
- Hospitals:Tertiary academic medical centers in Rio de Janeiro and Mexico City anchor capital-intensive platform deployment. These institutions negotiate bundled imaging-needle contracts through centralized supply chains, though unbundling pressures are accelerating.
- Diagnostic Centers:Dedicated breast imaging facilities in Bogotá and Medellín private chains are establishing standalone procurement offices. Competitive tendering cycles now run independent of imaging vendor relationships, opening supplier entry points.
- Oncology Clinics:Specialized cancer treatment facilities across Brazil's southeast region.
- Research Institutions:Academic pathology laboratories conducting specimen banking and biomarker studies.
Hospital purchasing still dominates transaction volume, but diagnostic centers are climbing the fastest.
Technology:
Capital requirements and infrastructure availability create sharp divergence between accessible ultrasound and constrained MRI-guided alternatives.
- Ultrasound-Guided:Real-time imaging with portable probe configurations eliminates dedicated suite requirements. Community oncology clinics in São Paulo's peripheral zones are adopting portable ultrasound-VAB systems at accelerating pace, compressing deployment barriers for mid-tier facilities.
- MRI-Guided:Magnetic resonance-compatible needle systems enable targeting of mammographically occult lesions. Deployment concentrates in tertiary academic centers with dedicated interventional MRI suites; capital intensity and scheduling constraints limit expansion outside Brazil's southeast and Mexico City.
- X-Ray Guided:Stereotactic mammography-based targeting for calcification clusters.
- Palpation:Manual localization without image guidance for superficial palpable masses.
Ultrasound-Guided commands installed base. MRI-Guided seeks niche premium positioning.
Distribution Channel:
Channel strategy must navigate regulatory compliance burdens that favor established local infrastructure over direct market entry.
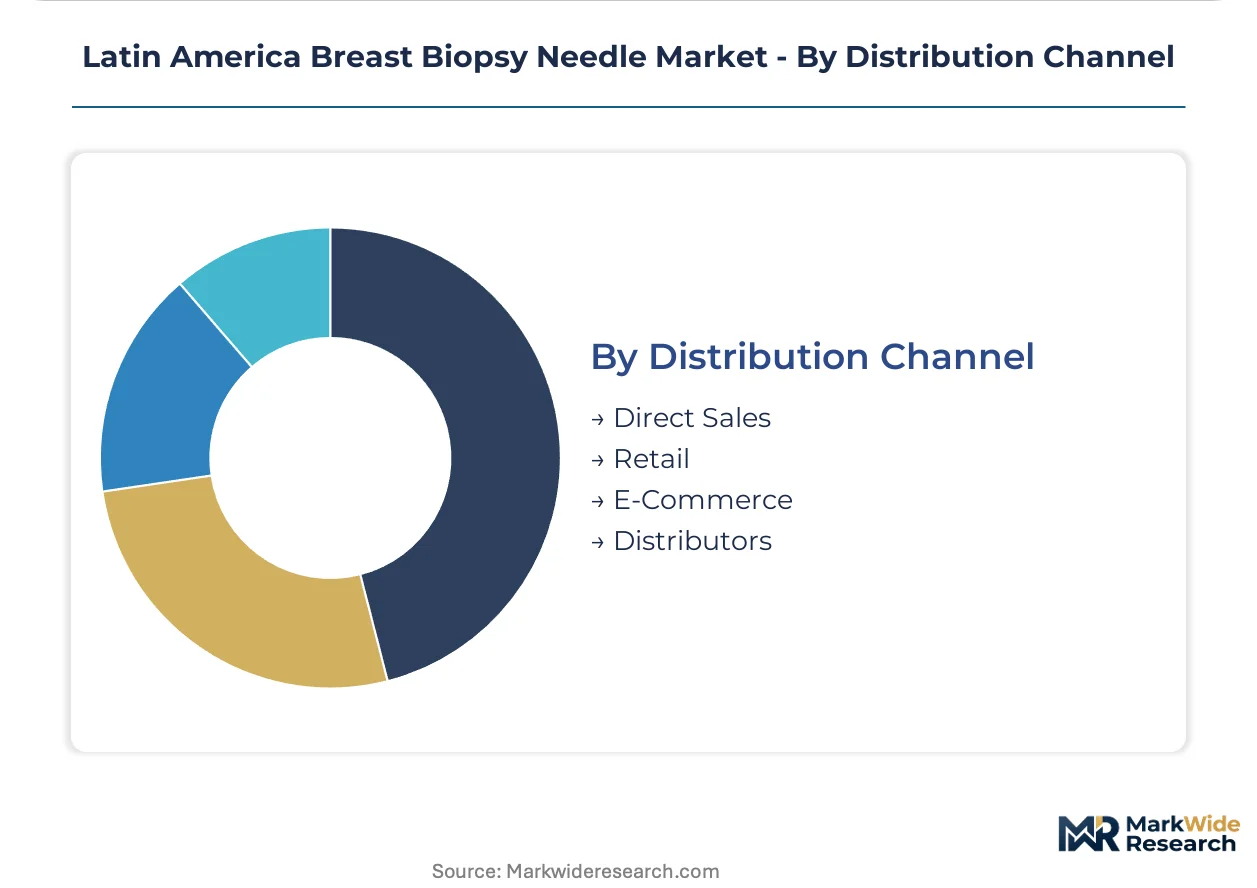
- Direct Sales:Manufacturer-controlled field organizations serving high-volume Brazilian hospital networks. Hologic and Becton, Dickinson and Company maintain dedicated sales engineering teams for integrated platform placement, capturing recurring consumable commitments through technical support relationships.
- Distributors:Authorized representative models with dedicated regulatory affairs capacity. COFEPRIS post-market surveillance mandates and ANVISA sterility documentation requirements force supply chain restructuring toward localized complaint handling infrastructure.
- Retail:Medical supply storefronts serving small clinic and outpatient settings.
- E-Commerce:Digital procurement platforms with limited penetration in regulated device categories.
Direct Sales retains premium accounts. Distributors enable regulatory-compliant market coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Breast biopsy needle manufacturing in Latin America traces its commercial roots to multinational medtech expansion into Brazil during the 1990s, when diagnostic imaging infrastructure first scaled across São Paulo's hospital networks. Today procurement patterns diverge sharply across national regulatory environments and metropolitan healthcare investment cycles.
Brazil
São Paulo and Rio de Janeiro metropolitan hospital networks anchor regional consumption volume through municipal breast cancer screening programs. ANVISA enforces sterility and biocompatibility standards that compress product registration timelines, forcing suppliers to front-load compliance investment. Community oncology clinics in São Paulo's peripheral zones are adopting portable ultrasound-guided systems at accelerating pace.
Mexico
Mexico City tertiary academic centers concentrate capital-intensive platform deployment while private diagnostic chains expand through the Bajío Region. COFEPRIS extends approval timelines for devices lacking ISO 13485 certification equivalence, creating friction for first-time entrants. Northern Border States are witnessing distributor restructuring toward authorized representative models with dedicated regulatory affairs capacity.
Argentina
Buenos Aires and Córdoba oncology clinics are displacing legacy core needle systems with vacuum-assisted configurations. ANMAT maintains parallel import licensing requirements that fragment cross-border distribution efficiency. Pending streamlining of import requirements would reduce distribution fragmentation for established Mercosur suppliers.
Colombia
Bogotá and Medellín private hospital chains are establishing dedicated breast imaging centers with bundled needle-procurement contracts. New needle-tracking software encounters compatibility friction with entrenched picture archiving systems in public hospital networks. Competitive tendering cycles now run independent of imaging vendor relationships.
Chile
Santiago's concentrated private healthcare sector drives premium segment demand for integrated imaging-needle platforms. Public hospital networks in regional centers face capital constraints that favor lower-cost ultrasound alternatives. Interventional radiology training bottlenecks at teaching hospitals constrain procedural volume expansion outside the capital.
Latin America Breast Biopsy Needle Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with bundled imaging-needle platforms commanding pricing power against standalone needle suppliers. The vendor base stratifies into three tiers: multinational medtech conglomerates with direct sales infrastructure, regional specialists in vacuum-assisted configurations, and distributor-dependent importers serving price-sensitive segments. Consolidation pressure is accelerating as hospital procurement offices unbundle service contracts from capital equipment purchases, while regulatory compliance burdens favor players with localized complaint handling infrastructure.
Among the multinational tier, Hologic and Becton, Dickinson and Company exemplify premium positioning through integrated platform strategies, with the former anchoring diagnostic center relationships in Brazil and the latter sustaining broad distribution reach across Mexico and Colombia. Cook Medical occupies a specialist position within the vacuum-assisted segment, representing the archetype of procedure-specific technology focus that Argentine oncology clinics increasingly favor.
| Leading Market Players |
|---|
| Hologic |
| Becton, Dickinson and Company |
| Medtronic |
| Boston Scientific Corporation |
| Cook Medical |
| Leica Biosystems |
| Argon Medical Devices |
| Fujifilm Medical Systems |
| C.R. Bard |
| Others |
Supply & Pricing Matrix
Captive manufacturing of nitinol needle components in São Paulo industrial zones anchors both supply security and premium pricing power for Brazilian producers serving ANVISA-regulated hospital networks. This integration choice insulates against Asian alloy price volatility while compressing landed costs for vacuum-assisted biopsy systems displacing legacy core needle imports.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated imaging-needle platforms from standalone vacuum-assisted devices and basic core needle systems. Price differentiation rests on ANVISA certification grade and after-sales technical support bundling. Cost compression in the economy tier is intensifying because Argentine oncology clinics are consolidating procurement volume around mid-tier vacuum-assisted configurations. Municipal hospital networks in Brazil exhibit highest price sensitivity, while tertiary academic centers in Mexico City show lowest sensitivity due to capital budget autonomy.
Supply Chain Analysis
Specialized interventional radiology technician training programs in São Paulo, Mexico City, and Buenos Aires constrain manufacturing scale-up for precision needle assembly operations. Nitinol superelastic alloy feeds from Chinese and Japanese specialty metallurgy suppliers, while stainless steel cannula stock sources from domestic Brazilian mills. Single-source vulnerability concentrates in nitinol shape-setting equipment, where German and Japanese machine tool builders dominate installed base. Distribution runs through authorized representative models with localized regulatory affairs capacity serving COFEPRIS and ANVISA compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Latin American breast biopsy needle supply is justified by accelerating unbundling of needle procurement from imaging platform leases, which shifts purchasing authority toward specialized suppliers with standalone value propositions.
For Market Incumbents: Extend technical support relationships into standalone service contracts that survive imaging platform replacement cycles. Consolidate backward integration into nitinol wire forming to defend against Asian alloy price volatility. ANVISA sterility documentation requirements favor incumbents with established local quality infrastructure over distributor-dependent challengers. For New Entrants and Emerging Players: Begin with portable ultrasound-guided vacuum-assisted configurations targeting São Paulo's peripheral zone community oncology clinics. These facilities lack capital for dedicated mammography suites and represent the most penetrable procedural segment. A go-to-market angle emphasizing reduced pathology laboratory costs through larger specimen yields opens procurement conversations outside traditional hospital supply chains. For Investors and Strategic Acquirers: Roll-up economics work for regional vacuum-assisted biopsy specialists because ANMAT import licensing fragmentation prevents efficient cross-border distribution for sub-scale players. The long-term viability window favors acquisition targets with established Mercosur regulatory files and direct sales presence in at least two of Brazil, Mexico, and Argentina. Watch ANVISA-COFEPRIS harmonization progress as the inflection signal for simplified multi-country scaling.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Pre-Submission Consultation | Front-loaded sterility documentation accelerates Brazilian market entry timelines for vacuum-assisted platforms. |
| Colombian Diagnostic Center Partnership | Bogotá private hospital chains seek bundled needle-procurement contracts independent of imaging vendors. |
| Nitinol Alloy Supply Agreement | Long-term offtake with Japanese metallurgy suppliers hedges against input cost volatility in Brazilian manufacturing. |
| Portable Ultrasound-VAB Configuration Launch | Eliminates dedicated mammography suite requirements for São Paulo peripheral zone community clinics. |
| COFEPRIS Authorized Representative Establishment | Localized complaint handling infrastructure satisfies tightened post-market surveillance obligations for Class III devices. |
Research Methodology
Multiple input streams — procurement database analysis, regulatory filing review, and clinician workflow observation — were reconciled to construct segment-level demand estimates. Primary interviews with hospital purchasing committee members, interventional radiologists, biomedical engineers, and GPO contracts managers were validated against secondary sources including ANVISA registration databases, COFEPRIS medical device alerts, and hospital procurement tender records. Bottom-up installation base counts and top-down healthcare expenditure allocations were cross-referenced to anchor volume projections.
Historical procedure volume trajectories were cross-referenced against panel input from distribution channel partners to calibrate adoption curve assumptions across the projection horizon. Segmentation modeling incorporated product type, end user category, guidance technology, and national regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to base-year estimates, with vacuum-assisted biopsy procedural shift rates and ultrasound-guided deployment penetration serving as key forecast inputs.
Several conditions sit outside the modeled scope, including pending Mercosur regulatory convergence implementation timing and nitinol alloy commodity price shocks beyond historical volatility bands. Forecasts reflect documented assumptions about screening program expansion continuity and interventional radiology fellowship slot growth. Material deviation in ANVISA-COFEPRIS harmonization progress or Brazilian municipal health budget allocations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Carotid Artery Stents Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Medical Device Cros Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Cough Assist Devices Market