
 Europe Single-Use Medical Device Reprocessing Market | 2026-2036
Europe Single-Use Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Single-Use Medical Device Reprocessing Market Foresight
Equipment leasing and pay-per-cycle service contracts are tilting competitive dynamics toward capital-light entrants. Stryker Sustainability Solutions leverages its installed base of reprocessing equipment to sustain recurring revenue streams. Vanguard AG competes through specialized catheter reprocessing capabilities that anchor its position in German hospital networks.
Single-use medical device reprocessing encompasses the cleaning, functional testing, sterilization, and repackaging of devices originally labeled for single patient use, employing validated cycles that meet sterility assurance levels of 10^-6. The practice reduces per-procedure costs for hospitals while requiring compliance with material compatibility thresholds for polymers and adhesives. Endoscope reprocessing leads volume given the high unit cost of flexible scopes and established validation protocols, while catheter reprocessing represents the fastest-growing segment as cardiac and urological procedure volumes expand. Thermal sterilization dominates current installed capacity, though chemical reprocessing technologies are capturing margin pools in temperature-sensitive polymer applications.
The EU Medical Device Regulation and notified body frameworks in Germany, France, and the United Kingdom shape validation requirements and market access pathways for third-party reprocessors. EMA coordination with national competent authorities creates fragmented but tightening standards for clinical evidence of reprocessed device safety. Stakeholders must monitor how MDR implementation timelines and national reimbursement rulings on reprocessed device eligibility reshape competitive boundaries across European hospital procurement consortia.
Market Dynamics
Cost-containment mandates from German hospital procurement consortia are accelerating third-party reprocessor validation, compressing decision cycles for catheter and endoscope sterilization outsourcing.
Growth Catalysts
- EU Medical Device Regulation:The MDR framework mandates validated reprocessing protocols for single-use devices, creating compliant market access pathways for sterilization service providers.
- Ambulatory surgery centers:French and UK outpatient facilities are consolidating device reprocessing contracts to reduce per-procedure supply expenditures.
- Thermal sterilization capacity:Established autoclave infrastructure in German hospital networks enables rapid scaling of reprocessed catheter volumes.
Market Restraints
- Polymer material incompatibility:Temperature-sensitive adhesives in cardiac catheters limit thermal sterilization applicability, constraining reprocessing yield rates.
- Notified body capacity:EMA-coordinated validation queues create 18-24 month certification backlogs for novel reprocessing technologies.
- Single-use device substitution:Original equipment manufacturers are deploying material innovations that accelerate device degradation after initial use.
Strategic Opportunities
- Eastern European hospital networks:Polish and Romanian healthcare systems lack in-house sterilization infrastructure, creating white space for outsourced reprocessing services.
- Chemical sterilization convergence:Hydrogen peroxide vapor systems paired with RFID tracking enable reprocessing of temperature-sensitive polymer devices previously excluded from reuse programs.
- EU Green Deal procurement incentives:Sustainability-linked tender criteria in France and Germany award contract preference to reprocessed device suppliers.
Industry Challenges
- Validation microbiologist scarcity:Sterility assurance testing expertise concentrates in German and Swiss laboratory clusters, creating recruitment bottlenecks for reprocessor expansion.
- Legacy device tracking integration:Reprocessors must reconcile batch-level sterilization records with hospital ERP systems lacking standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Single-Use Medical Device Reprocessing Market |
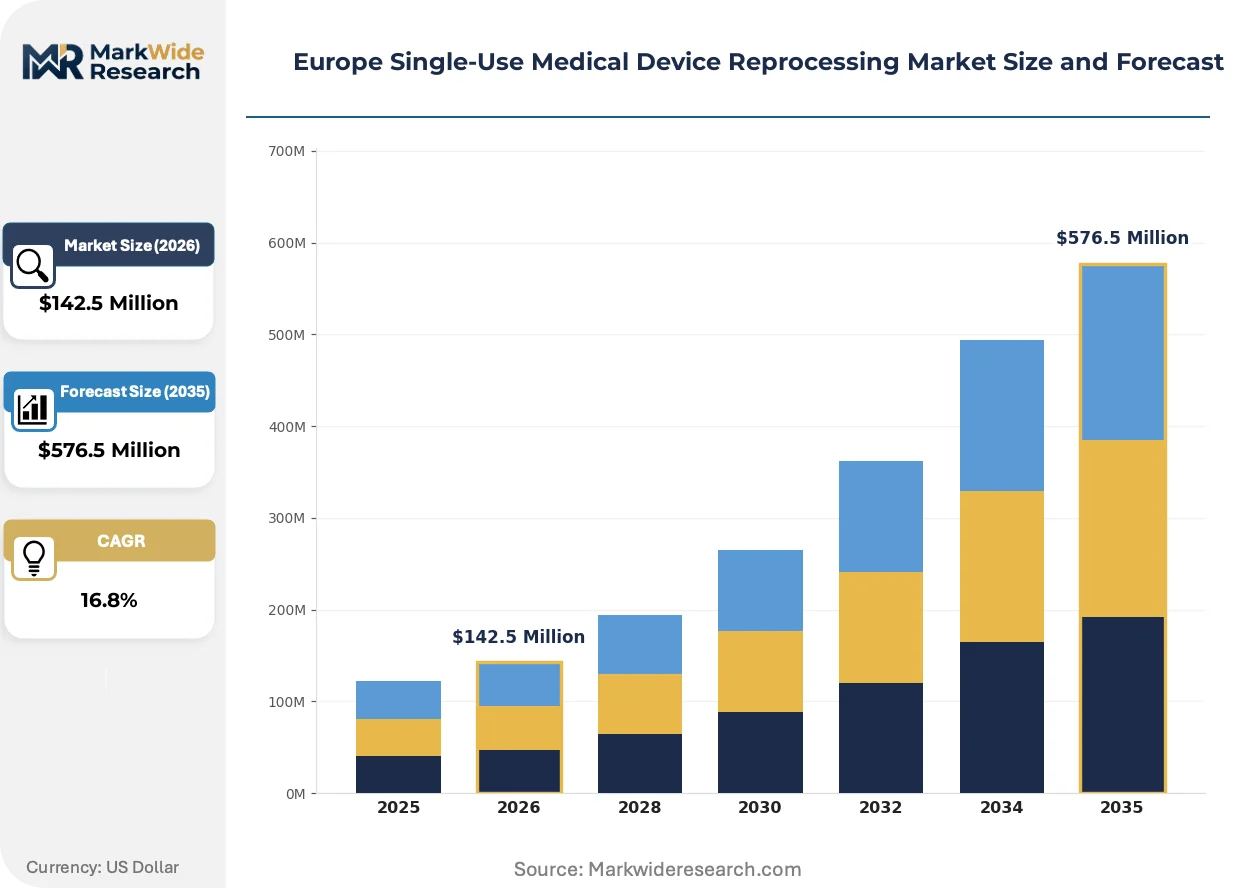
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $576.5 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscope, Surgical Instrument, Catheter, Dialyzer Application: Cardiology, Orthopedics, Urology, Gastroenterology Technology: Chemical, Thermal, Radiation, Ultrasonic End User: Hospitals, Clinics, Ambulatory Surgery Centers, Laboratories |
| Companies Covered | Stryker Sustainability Solutions, Medline Industries, Johnson & Johnson Services, Vanguard AG, NEScientific, Arjo, Sterilmed, STERIS, SureTek Medical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Single-Use Medical Device Reprocessing Market Shifts & Advancements
Digital traceability infrastructure and low-temperature sterilization chemistry are converging to expand the addressable device pool for European reprocessors beyond established endoscope categories.
Radio-frequency identification tagging is virtualizing supply chain visibility for reprocessed devices. German hospital networks are mandating RFID-enabled catheter tracking to satisfy MDR post-market surveillance requirements. This technology is virtualizing batch recall procedures, compressing traceability response times from weeks to hours across sterilization service contracts.
The EU Medical Device Regulation's Unique Device Identification mandate is restructuring competitive access for third-party reprocessors. Manufacturers must now submit clinical evidence packages for reprocessed device equivalence, elevating documentation burdens. Cardiac catheter reprocessing segments in France and the United Kingdom are absorbing these compliance costs through consortia-level validation sharing agreements.
Hospital procurement consortia are unbundling sterilization services from device supply contracts. German university hospital networks now tender reprocessing as standalone service categories, displacing bundled OEM pricing. This pattern is most visible in North Rhine-Westphalia and Bavaria, where regional purchasing alliances negotiate cycle-based pricing for catheter sterilization.
Europe Single-Use Medical Device Reprocessing Market Segmentation
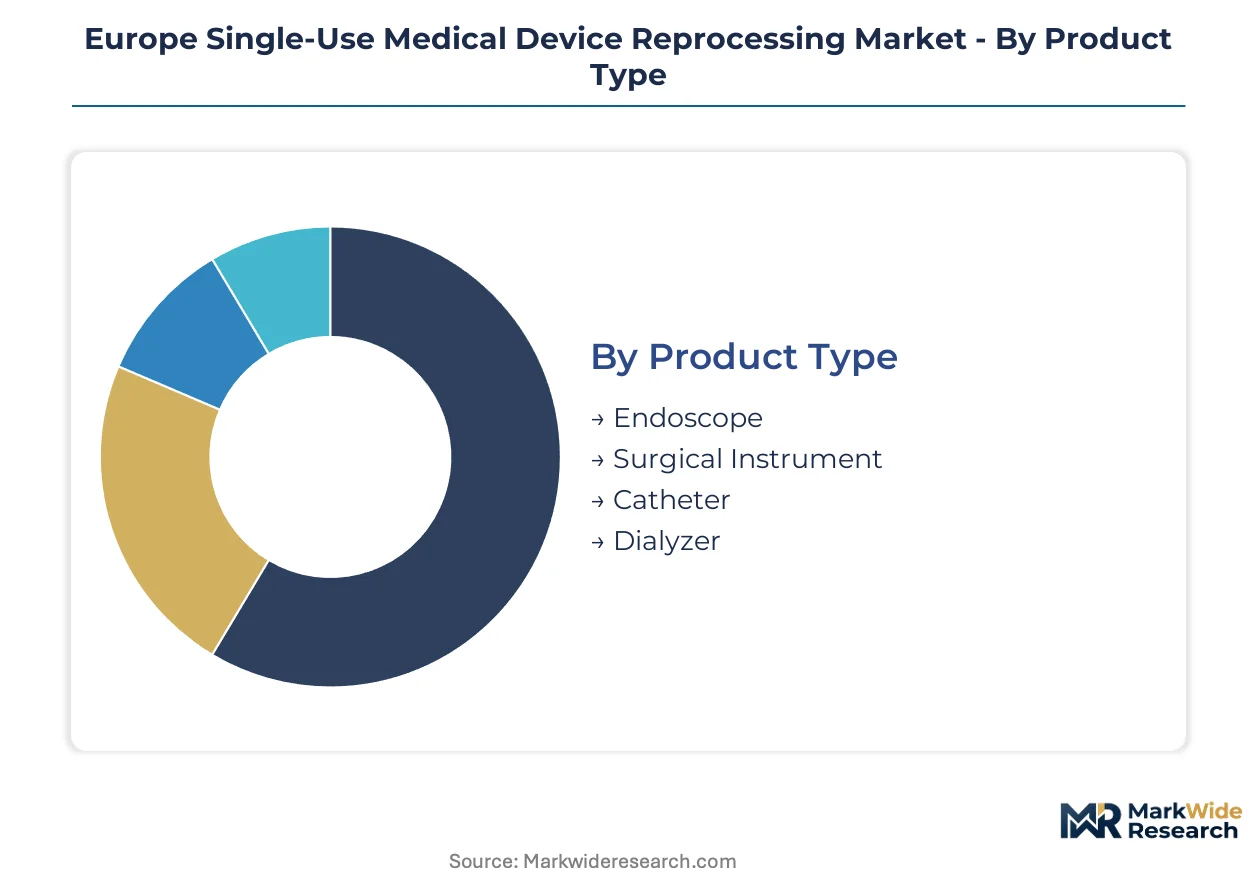
Device-specific reprocessing protocols demand differentiated service intensities across European sterilization networks. Material compatibility thresholds and validation complexity fragment procurement strategies by product category and clinical application.
Product Type:
After-sales service intensity varies sharply across device categories, with flexible endoscopes requiring dedicated technician deployment and catheter programs scaling through remote monitoring infrastructure.
- Endoscope:Flexible gastrointestinal and bronchial scopes incorporate complex luminal geometries demanding brush-based cleaning validation and pressure-leak testing. German university hospital networks in Bavaria and North Rhine-Westphalia concentrate outsourced reprocessing contracts for duodenoscopes and colonoscopes, driven by MDR-mandated post-market surveillance documentation burdens.
- Catheter:Cardiac electrophysiology and urological catheters employ thermoplastic elastomers and adhesive-bonded hubs requiring material-specific sterilization cycles. French ambulatory surgery centers in the Île-de-France region are consolidating cardiac catheter reprocessing contracts to reduce per-procedure supply expenditures amid reimbursement compression.
- Surgical Instrument:Laparoscopic graspers and trocars feature hinged mechanisms and insulation layers requiring functional testing post-sterilization. UK NHS procurement consortia favor reprocessed instrument sets for routine cholecystectomy procedures.
- Dialyzer:Hollow-fiber membrane cartridges present protein-fouling challenges and endotoxin clearance thresholds. Italian renal care networks maintain limited in-house dialyzer reprocessing due to membrane integrity verification costs.
Endoscope reprocessing holds the largest share; momentum sits with catheter sterilization services.
Application:
Clinical procedure volumes and device unit economics determine reprocessing viability across European specialty care networks.
- Cardiology:Electrophysiology mapping catheters and diagnostic angiography devices command reprocessing economics justified by per-unit acquisition costs exceeding several thousand euros. German cardiac catheterization laboratories in Berlin and Hamburg validate sterilization cycles for multipolar mapping catheters through notified body-certified third-party providers.
- Gastroenterology:Colonoscopy and EGD procedure volumes sustain dedicated endoscope reprocessing facilities. UK independent sector treatment centers outsource flexible sigmoidoscope sterilization to specialized service bureaus.
- Urology:Cystoscopy and ureteroscopy devices employ semi-rigid and flexible instrument platforms with divergent material specifications. French urology clinics in Lyon and Marseille adopt consortia-level reprocessing agreements for ureteral access sheaths.
- Orthopedics:Arthroscopic shavers and burrs present battery-component and cutting-edge integrity challenges limiting reprocessing applicability. Swiss orthopedic networks restrict reprocessing to non-powered instrument subsets.
Gastroenterology anchors current sterilization volumes; cardiology is climbing the fastest as electrophysiology procedure expansion outpaces device manufacturing capacity.
Technology:
Capital equipment depreciation schedules and cycle throughput economics shape technology adoption patterns across European sterilization infrastructure.
- Thermal:Saturated steam autoclave cycles dominate installed capacity with validated sterility assurance levels and polymer compatibility established across decades of clinical use. German hospital networks leverage existing autoclave infrastructure for catheter and instrument reprocessing with minimal incremental capital deployment.
- Chemical:Hydrogen peroxide vapor and ethylene oxide systems enable sterilization of temperature-sensitive polymers and adhesive assemblies. UK sterilization service providers invest in vaporized hydrogen peroxide capacity to address cardiac catheter material constraints excluded from thermal processing.
- Radiation:Gamma and electron beam sterilization accommodate bulk commodity devices with established dose-response validation. Limited European reprocessor adoption due to centralized irradiation facility requirements and logistics complexity.
- Ultrasonic:Cavitation-based cleaning protocols serve as pre-sterilization preparation for luminal devices and complex geometries. French endoscope reprocessing facilities integrate ultrasonic baths prior to thermal or chemical terminal sterilization.
Thermal sterilization retains dominant share; chemical modalities are gaining share fastest as polymer device portfolios expand.
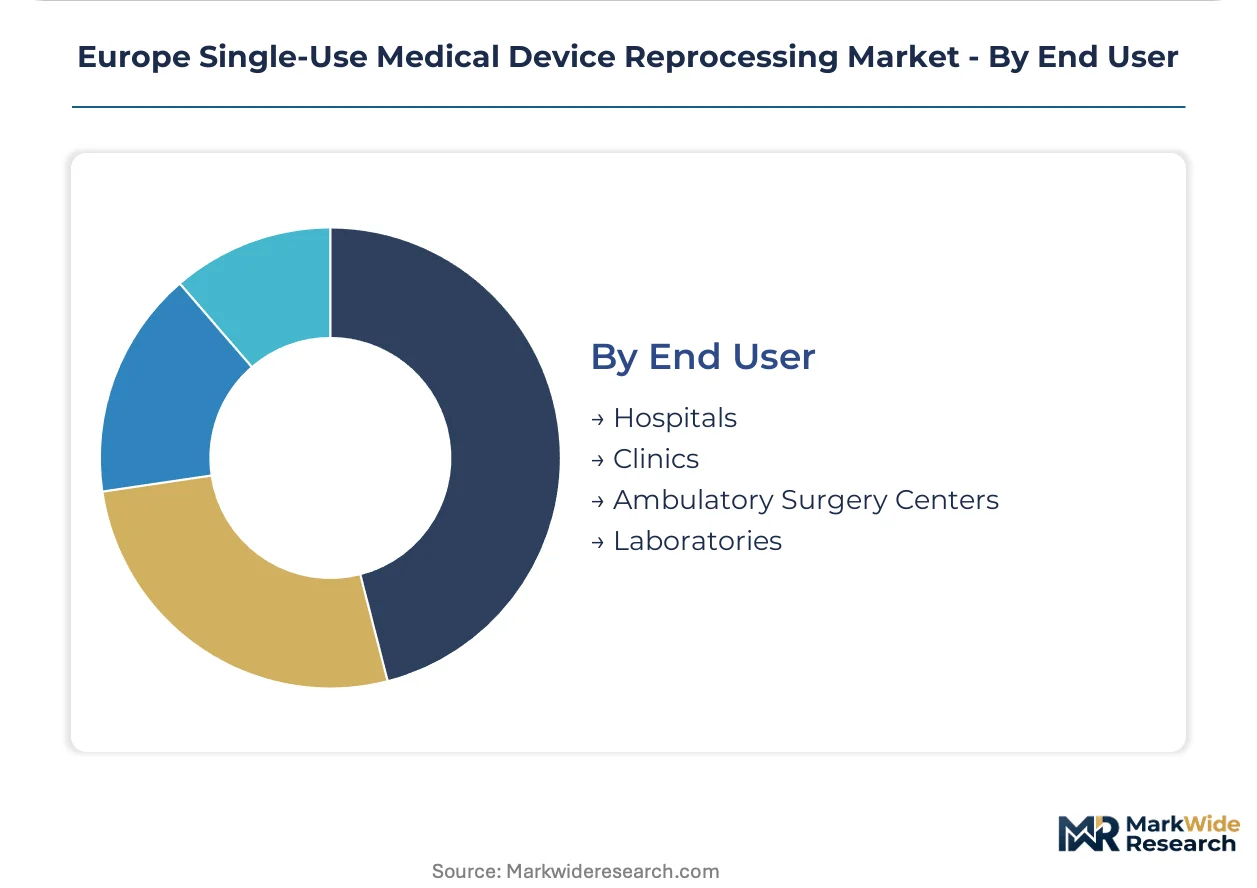
End User:
Procurement autonomy and sterilization infrastructure ownership determine outsourcing penetration across European healthcare delivery settings.
- Hospitals:German university hospital networks maintain hybrid models combining in-house endoscope reprocessing with outsourced catheter sterilization. Central sterile supply departments in France negotiate cycle-based pricing for high-volume device categories.
- Ambulatory Surgery Centers:French and UK outpatient facilities lack capital budgets for sterilization infrastructure deployment. Consolidated reprocessing contracts with regional service providers reduce per-procedure supply costs for cataract and endoscopic procedures.
- Clinics:Independent specialist practices in Spain and Italy rely on third-party sterilization bureaus for limited-volume device categories. Urology and gastroenterology clinics prioritize logistics integration over in-house processing capacity.
- Laboratories:Research and diagnostic facilities generate reprocessing demand for specialized sampling devices and cell culture instrumentation. Validation requirements diverge from clinical sterilization standards, limiting service provider overlap.
Hospitals command the largest share; ambulatory surgery centers represent the steepest expansion trajectory as outpatient procedural migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European sterilization service exports flow predominantly from German and French processing hubs toward Eastern European hospital networks lacking thermal sterilization infrastructure. Import dependency concentrates in Polish and Romanian healthcare systems sourcing catheter and endoscope reprocessing from Western European providers. The regional trade pattern reflects capital equipment ownership disparities rather than technology gaps.
Germany
Bavarian university hospital networks in Munich and Erlangen anchor catheter reprocessing volumes driven by cardiac electrophysiology procedure expansion. The EU Medical Device Regulation mandates notified body certification for third-party reprocessors, compressing validation timelines for sterilization service contracts. North Rhine-Westphalia procurement consortia in Cologne and Düsseldorf negotiate cycle-based pricing for outsourced endoscope sterilization.
France
Île-de-France ambulatory surgery centers in Paris and surrounding suburbs consolidate reprocessing contracts to reduce per-procedure supply expenditures amid reimbursement compression. The ANSM national competent authority coordinates with EMA on MDR implementation timelines for reprocessed device market authorization. Lyon and Marseille urology clinics adopt consortia-level agreements for ureteral access sheath sterilization.
United Kingdom
NHS procurement consortia favor reprocessed instrument sets for routine cholecystectomy procedures in London and Southeast England independent sector treatment centers. The MHRA post-Brexit regulatory framework maintains alignment with MDR sterilization validation requirements. UK sterilization service providers invest in vaporized hydrogen peroxide capacity to address temperature-sensitive polymer constraints.
Italy
Italian renal care networks in Lombardy and Emilia-Romagna maintain limited in-house dialyzer reprocessing due to hollow-fiber membrane integrity verification costs. Regional health authorities in Milan and Bologna tender sterilization services separately from device supply contracts. The Italian Ministry of Health defers to EMA-coordinated standards for clinical evidence of reprocessed device safety.
Poland
Polish hospital networks in Warsaw and Krakow lack capital budgets for autoclave infrastructure deployment, creating white space for outsourced reprocessing services from Western European providers. The national pharmaceutical regulator aligns device reprocessing oversight with EU MDR implementation timelines. Regional purchasing alliances negotiate logistics integration over in-house processing capacity for catheter sterilization.
Europe Single-Use Medical Device Reprocessing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The European reprocessing market structures around sterilization service providers with installed equipment bases and specialized validation laboratories. Three archetypes dominate: capital equipment owners with recurring service revenue, catheter-focused reprocessors with material-specific expertise, and diversified medical device manufacturers extending into sustainability services. Competitive moves concentrate on equipment leasing arrangements and pay-per-cycle contract structures that reduce hospital capital deployment.
Within the equipment-integrated tier, Stryker Sustainability Solutions and STERIS exemplify platform-scale positioning through installed autoclave and sterilization system deployment. Vanguard AG occupies a specialized position in German hospital networks with catheter-specific reprocessing capabilities. Medline Industries represents the diversified distributor archetype extending service revenue through sterilization outsourcing contracts. These three anchors illustrate how competitive positioning fragments between capital-heavy infrastructure ownership and specialized material validation expertise.
| Leading Market Players |
|---|
| Stryker Sustainability Solutions |
| Medline Industries |
| Johnson & Johnson Services |
| Vanguard AG |
| NEScientific |
| Arjo |
| Sterilmed |
| STERIS |
| SureTek Medical |
| Others |
Supply & Pricing Matrix
German sterilization equipment manufacturers concentrate upstream supply of autoclave systems and hydrogen peroxide vapor chambers, anchoring margin pools in downstream service contracts rather than hardware sales. This concentration enables reprocessors to extract recurring revenue through cycle-based pricing while hospital buyers face limited alternative sourcing for validated sterilization infrastructure.
Pricing Analysis
Hospital procurement consortia anchor pricing structures around pay-per-cycle service contracts with tiered volume discounts. Price differentiation hinges on MDR certification tier and geographic service density, with French and German networks commanding premium rates for notified body-validated protocols. Pricing pressure stems from Eastern European buyers negotiating logistics-integrated contracts that compress per-unit margins. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while German university hospitals prioritize compliance over cost.
Supply Chain Analysis
Extended payment terms from German equipment financiers enable reprocessors to deploy sterilization infrastructure without upfront capital burden. Supply concentrates in Germany, France, and Switzerland for thermal sterilization systems, while hydrogen peroxide vapor chemistry draws from Belgian and Dutch specialty chemical suppliers. Raw material dependencies include medical-grade stainless steel for autoclave chambers, polymer-grade hydrogen peroxide, and RFID tagging components. Single-source vulnerability runs through Swiss sterilization validation laboratory capacity. Distribution runs through regional service hubs co-located with hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European single-use medical device reprocessing market reads as a service-attach opportunity where sterilization-as-a-service contracts expand faster than capital equipment sales. Validation and tracking services now generate recurring revenue streams that outpace hardware replacement cycles.
For Market Incumbents: Entrench position by deepening captive supply of hydrogen peroxide vapor chemistry through backward integration into Belgian specialty chemical networks. Expand thermal sterilization capacity in North Rhine-Westphalia procurement corridors to preempt Eastern European entrants. The threat of OEM material innovations that accelerate device degradation demands accelerated investment in chemical sterilization R&D to preserve addressable device pools.
For New Entrants and Emerging Players: Polish hospital networks in Warsaw and Krakow offer the most penetrable geographic entry point given capital budget constraints and absence of in-house autoclave infrastructure. Target cardiac catheter reprocessing in French ambulatory surgery centers where reimbursement compression intensifies outsourcing demand. A go-to-market angle built on RFID-enabled traceability integration with hospital ERP systems differentiates against incumbent equipment-heavy positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sterilization service platforms seeking geographic roll-up opportunities in Eastern Europe. The five-to-ten year viability window favors platforms with MDR-certified validation laboratories and established notified body relationships. Acquisition targets should demonstrate consortia-level contract concentration and chemical sterilization capability expansion. Monitor EMA coordination timelines with national competent authorities as the signal for regulatory capacity inflection that will reshape competitive boundaries.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | Notified body validation unlocks German hospital procurement consortia contract access. |
| Chemical Sterilization Capacity Buildout | Hydrogen peroxide vapor systems address temperature-sensitive polymer device expansion. |
| RFID Traceability Integration | Virtualized batch recall compresses response times for MDR post-market surveillance. |
| Eastern European Geographic Expansion | Polish and Romanian hospital networks lack thermal sterilization infrastructure ownership. |
| Consortia-Level Validation Sharing | Shared compliance costs absorb MDR documentation burdens across French cardiac catheter networks. |
Research Methodology
The analysis maps thermal sterilization, chemical sterilization, and radiation-based reprocessing modalities, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and notified body certification leads. Primary interviews with sterilization service executives and regulatory affairs directors combined with secondary validation from EMA coordination documents, national competent authority filings, hospital procurement databases, and GPO contract repositories. Bottom-up device category volume estimates triangulated against top-down healthcare expenditure flows.
Forecast assumptions held EU MDR implementation timelines and national reimbursement rulings fixed while varying ambulatory surgery center outsourcing penetration rates and chemical sterilization technology adoption curves across the analysis window. Segmentation dimensions modeled include device type, sterilization technology, clinical application, and end-user setting. CAGRs derived from procedure volume growth trajectories and per-device reprocessing economics. Industry-specific inputs incorporated cardiac electrophysiology expansion rates and polymer material compatibility thresholds.
Practitioners should monitor notified body certification queue lengths and OEM material innovation announcements for early signals of supply constraint or addressable market compression. Forecasts reflect these documented assumptions; regulatory enforcement divergence from EMA-coordinated standards or breakthrough single-use device material innovations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wireless ECG Devices Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Global Smart Implants Market
Medical Devices
Medical Goggle Market
Medical Devices
Cannula Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Injection Pen Market