
 Australia Cosmetic Surgery Market | 2026-2036
Australia Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Cosmetic Surgery Market Insights
Hyaluronic acid-based fillers is restructuring product economics across injectable categories, displacing older collagen formulations with longer duration and reversible profiles. Abbvie leverages its Allergan Aesthetics portfolio to dominate the botulinum toxin segment with established brand recognition. Candela Corporation specializes in laser platform development, sustaining its position through continuous wavelength innovation for skin resurfacing applications.
Australia cosmetic surgery encompasses surgical and non-surgical procedures that modify physical appearance through tissue manipulation, laser energy delivery, or pharmacological injection, typically performed under local or general anesthesia in accredited facilities. Breast augmentation and liposuction remain the most frequently performed surgical procedures, while non-surgical options including laser treatments and injectables capture expanding share among younger demographics seeking minimal downtime. Women constitute the dominant client type, though men represent the fastest-growing segment as social stigma around male aesthetic procedures continues to diminish across metropolitan markets.
TGA regulates all medical devices and therapeutic goods used in cosmetic procedures, enforcing stringent safety standards that filter lower-quality imports from clinic supply chains. AHPRA oversees practitioner registration requirements, ensuring only qualified medical professionals perform higher-risk surgical interventions. Stakeholders must monitor evolving TGA reclassification timelines for dermal fillers, as impending regulatory shifts will reshape procurement requirements and clinic compliance investments.
Market Dynamics
TGA's impending reclassification of dermal fillers as prescription-only medicines is compressing clinic procurement timelines and forcing wholesale supply chain restructuring across accredited facilities.
Growth Catalysts
- AHPRA Registration Standards:Mandatory specialist registration for surgical practitioners elevates consumer trust and reduces adverse event rates, expanding addressable demand among risk-averse demographics.
- Minimally Invasive Modalities:Energy-based devices and injectable platforms reduce facility overhead and anesthesia requirements, enabling clinic network expansion into secondary metropolitan zones.
- Sydney-Melbourne Corridor Concentration:Affluent suburban clusters generate referral density and economies of scale for premium service positioning.
Market Restraints
- Hyaluronic Acid Import Dependency:Supply concentration among Korean and European manufacturers exposes clinics to currency volatility and shipping delays.
- TGA Compliance Cost Escalation:Reclassification mandates trigger inventory write-downs and staff retraining investments for mid-tier operators.
- Non-Surgical Substitution:High-efficacy laser and ultrasound platforms capture patients who previously considered surgical intervention, compressing surgical volume growth.
Strategic Opportunities
- Perth-Adelaide Expansion:Underserved state capitals present first-mover positioning for chains with standardized compliance protocols.
- Regulatory Tailwind:TGA's streamlined approval pathway for Class IIb devices accelerates time-to-market for novel injectable formulations.
- Telemedicine Integration:Virtual consultation channels reduce geographic friction for pre-operative assessment and post-procedure monitoring.
Industry Challenges
- Specialist Anesthetist Scarcity:Limited supply of credentialed professionals restricts surgical capacity expansion in regional markets.
- Device Validation Timelines:TGA conformity assessment periods for laser platforms extend capital deployment cycles and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Cosmetic Surgery Market |
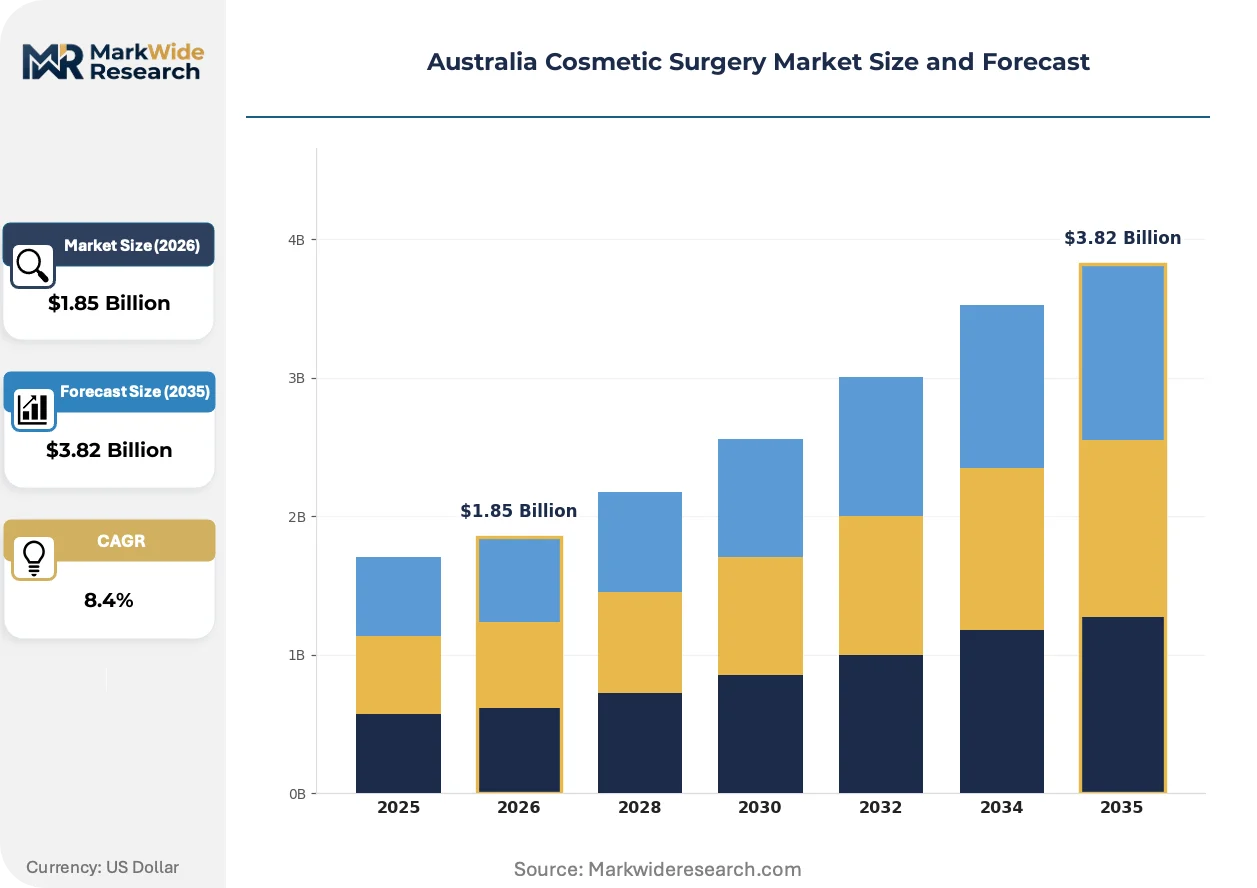
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Liposuction, Rhinoplasty, Facelifts Client Type: Women, Men, Teens, Transgender Individuals Technology: Laser Treatments, Injectables, Implants, Non-Surgical Options End Use: Clinics, Hospitals, Private Practices, Cosmetic Centers |
| Companies Covered | Abbvie, Cutera, Candela Corporation, Alma Lasers, Lumenis, Stryker Corporation, Zimmer Biomet Holdings, Bausch Health Companies, Merz Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Cosmetic Surgery Market Trends and Innovations
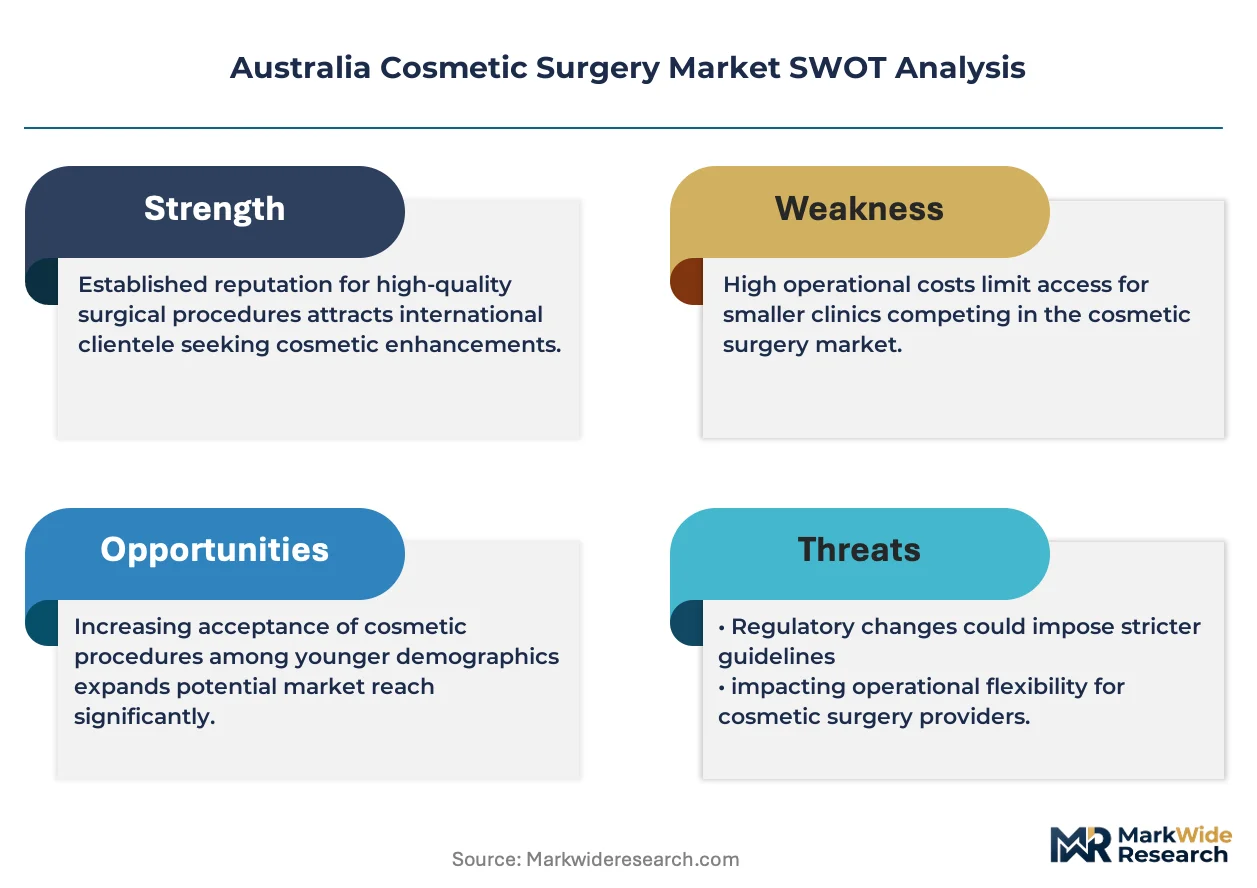
Technology convergence and regulatory recalibration are redistributing competitive advantage across surgical and non-surgical service lines, compressing legacy differentiation strategies.
Radiofrequency microneedling is decentralizing treatment delivery from hospital-grade facilities to accredited day clinics. Younger demographics in Brisbane and Melbourne are adopting combination protocols at accelerating rates. This modality is decentralizing capital requirements and enabling independent practitioner entrepreneurship outside traditional corporate structures.
TGA's 2024 device reclassification framework tightens evidence standards for energy-based platforms entering the Australian market. Manufacturers must now submit clinical data from local cohorts, extending registration timelines. Higher-risk laser categories face the steepest compliance burden, favoring established suppliers with dedicated regulatory affairs capacity.
Subscription-based maintenance programs are replacing discrete transaction models for injectable regimens. Premium Sydney clinics now bundle annual toxin and filler schedules with priority booking privileges. This shift is most pronounced among professional women aged 35-50 seeking predictable aesthetic expenditure profiles.
Australia Cosmetic Surgery Market Segmentation
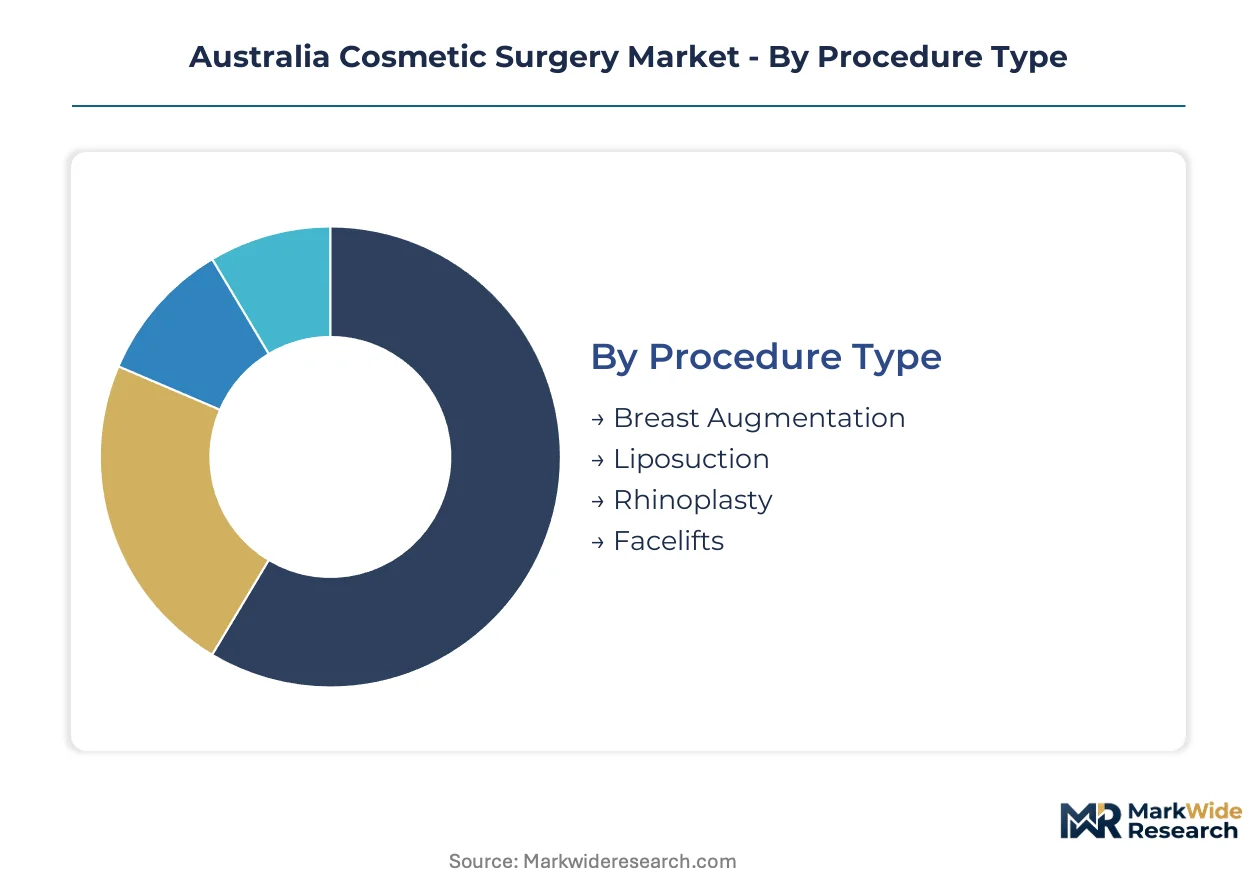
Segmentation reveals how TGA compliance burdens and facility accreditation requirements concentrate differently across procedure categories and client demographics. Understanding these divides enables targeted resource allocation for regulatory navigation and capacity planning.
Procedure Type:
Breast augmentation and liposuction carry Class III device obligations under TGA frameworks, while rhinoplasty and facelifts face AHPRA specialist registration mandates that filter practitioner supply.
- Breast Augmentation:Silicone and saline implants require TGA inclusion in the Australian Register of Therapeutic Goods before clinical use. Demand clusters in Sydney's eastern suburbs and Melbourne's inner southeast, where affluent patients prioritize dual-plane submuscular placement techniques.
- Liposuction:Tumescent and ultrasound-assisted modalities demand day-procedure licensing under state health regulations. Victorian and New South Wales facilities report highest utilization rates among post-partum women seeking body contouring with minimal downtime.
- Rhinoplasty:Open and closed surgical approaches require general anesthesia protocols and hospital-grade backup capacity.
- Facelifts:SMAS and deep-plane techniques command premium pricing tiers tied to specialist plastic surgeon availability.
Breast augmentation sits at the top of the volume ranking, with liposuction climbing the fastest among patients seeking non-implant alternatives.
Client Type:
Cost tiers stratify sharply across demographic segments, with professional women funding premium procedures through discretionary income while male and teen segments price-compare more aggressively.
- Women:Middle-aged professionals aged 35-50 drive injectable maintenance schedules and surgical rejuvenation demand. This cohort accepts bundled annual payment plans and prioritizes practitioner reputation over clinic proximity.
- Men:Gynecomastia correction and rhinoplasty lead male procedure selection, with fastest expansion occurring in Brisbane and Perth metropolitan zones. Social normalization accelerates consultation rates among professionals in finance and technology sectors.
- Teens:Otoplasty and rhinoplasty dominate, constrained by parental consent requirements and psychological assessment protocols.
- Transgender Individuals:Facial feminization and chest masculinization procedures require multidisciplinary care coordination.
Women dominate absolute procedure counts, with men gaining share fastest as stigma erosion accelerates metropolitan consultation rates.
Technology:
Application focus determines capital intensity and regulatory pathway length, with implantable devices facing TGA's longest approval timelines and energy-based platforms benefiting from streamlined Class IIb entry.
- Laser Treatments:Ablative and non-ablative resurfacing platforms require TGA conformity assessment with local clinical evidence. Fractional CO2 systems command highest utilization in Sydney premium clinics performing combination protocols.
- Injectables:Botulinum toxin and hyaluronic acid formulations face impending prescription-only reclassification. Melbourne clinics stockpile inventory ahead of procurement restriction deadlines.
- Implants:Silicone breast and facial implants carry mandatory adverse event reporting to TGA.
- Non-Surgical Options:Radiofrequency microneedling and ultrasound tightening enable day-clinic delivery without anesthesia.
Injectables lead technology segment volume, with non-surgical options expanding most quickly as younger demographics prioritize minimal downtime.
End Use:
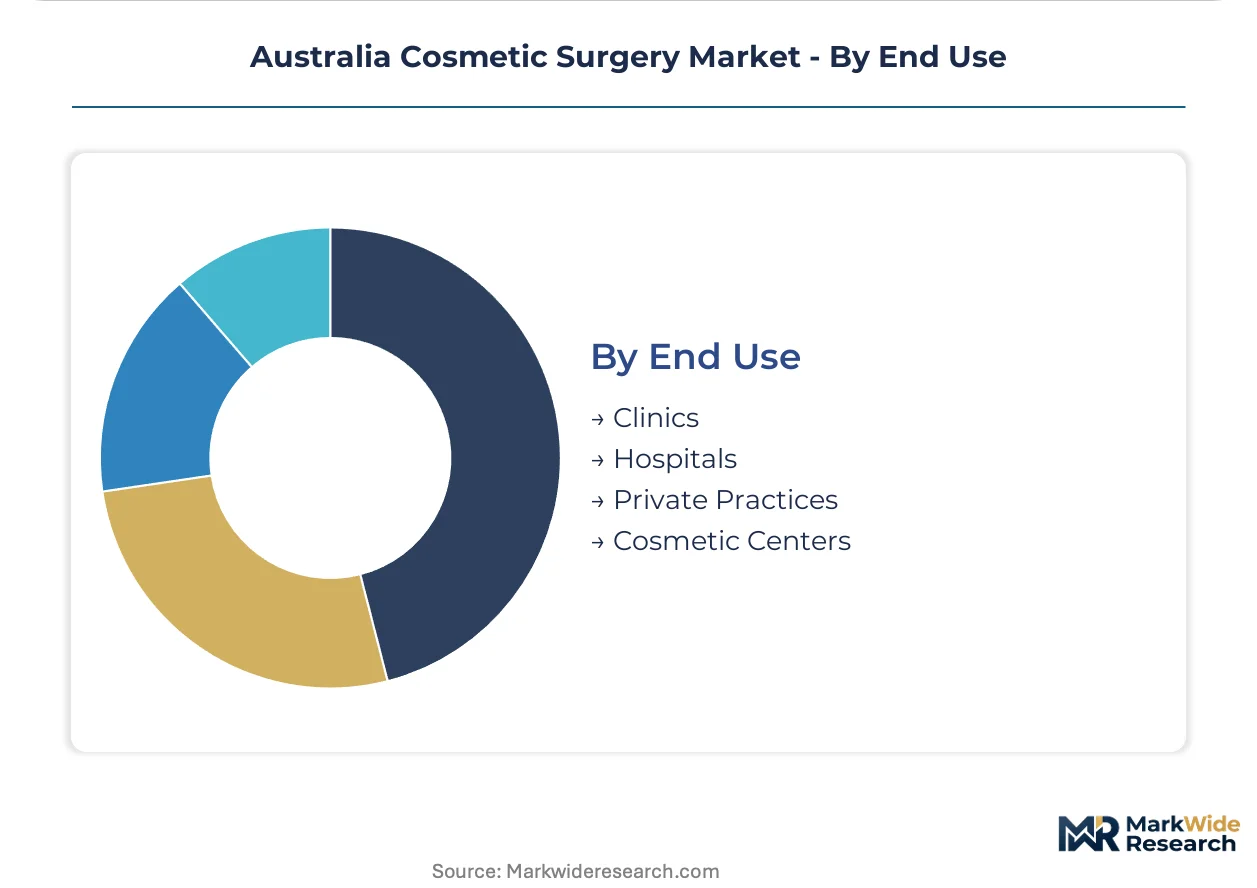
Margin structures diverge across facility types, with cosmetic centers capturing premium pricing through concierge positioning while private practices compete on accessibility and relationship continuity.
- Clinics:Accredited day-procedure units concentrate in Sydney and Melbourne suburban corridors, optimizing referral density through co-location with dermatology and plastic surgery practices.
- Hospitals:Private hospital suites handle high-complication-risk cases requiring overnight admission capacity and specialist anesthetist teams.
- Private Practices:Solo and group practitioner models dominate regional Queensland and Western Australia markets.
- Cosmetic Centers:Corporate chains standardize protocols across multi-site networks, targeting Perth and Adelaide for greenfield expansion.
Cosmetic centers lead revenue concentration, with private practices climbing fastest as independent practitioners adopt radiofrequency microneedling to reduce capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor Australian cosmetic surgery demand through concentrated premium clinic networks and affluent suburban patient bases. State-level regulatory variations and metropolitan clustering patterns create distinct operational environments across Australia's major markets. TGA's national framework applies uniformly, though enforcement intensity and specialist practitioner density vary by region.
New South Wales
Eastern Sydney suburbs generate Australia's highest per-capita cosmetic procedure rates among professional women aged 35-50. NSW Health's day-procedure licensing requirements exceed national baselines, filtering substandard operators from Bondi and Double Bay clinic corridors. North Shore and Eastern Suburbs concentrations drive national pricing benchmarks for breast augmentation and facial rejuvenation services.
Victoria
Melbourne's inner southeast corridor captures Victorian injectable volume leadership as clinics stockpile hyaluronic acid inventory ahead of TGA reclassification deadlines. AHPRA's Melbourne office processes the highest specialist plastic surgeon registration volumes nationally. South Yarra and Toorak clusters sustain premium positioning through practitioner reputation concentration.
Queensland
Brisbane's metropolitan zone records Australia's fastest male cosmetic surgery consultation growth, particularly among finance and technology professionals. Queensland Health's cosmetic procedure advertising guidelines restrict promotional claims more stringently than southern states. Gold Coast corridor clinics attract interstate medical tourism for combination laser and injectable protocols.
Western Australia
Perth's undersupplied market presents expansion opportunities for standardized clinic chains with TGA compliance protocols already established. Western Australia's specialist anesthetist scarcity restricts surgical capacity expansion beyond metropolitan boundaries. Subiaco and Cottesloe concentrations show emerging demand for non-surgical maintenance programs among mining sector executives.
South Australia
Adelaide's market remains fragmented among independent practitioners with limited corporate chain presence. South Australia's therapeutic goods enforcement prioritizes device traceability over clinical protocol variation. North Adelaide and Glenelg clinic clusters serve stable demand from public sector professionals seeking discreet service delivery.
Australia Cosmetic Surgery Market Competitive Landscape
Global majors compete with regional champions across device technology and injectable formulation segments, creating a tiered structure where scale advantages meet specialized service capabilities. The vendor base separates into pharmaceutical conglomerates with aesthetic divisions, dedicated energy-device manufacturers, and emerging platform developers. Three archetypes dominate: diversified healthcare giants leveraging cross-divisional R&D, laser technology specialists sustaining position through wavelength innovation, and mid-tier injectable houses competing on regulatory agility. Consolidation pressure intensifies as TGA compliance costs escalate and procurement scale requirements harden.
Among diversified healthcare conglomerates, Abbvie anchors the botulinum toxin segment through its Allergan Aesthetics portfolio acquisition, exemplifying pharmaceutical-scale entry into device-adjacent markets. Candela Corporation and Cutera occupy positions within the energy-based device specialist tier, with geographic naming conventions suggesting North American operational bases. Alma Lasers and Lumenis represent additional technology-focused competitors, while Stryker Corporation and Zimmer Biomet Holdings bring orthopedic-scale manufacturing discipline to implantable device categories. Merz Pharma and Bausch Health Companies complete the competitive set as mid-tier pharmaceutical operators with concentrated aesthetic therapeutic portfolios.
| Leading Market Players |
|---|
| Abbvie |
| Cutera |
| Candela Corporation |
| Alma Lasers |
| Lumenis |
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Bausch Health Companies |
| Merz Pharma |
| Others |
Pricing and Supply Chain Analysis
TGA's 2024 device reclassification framework gates qualified supply for premium-tier clinics while filtering substandard operators from pricing benchmarks. Compliance investment thresholds separate accredited Sydney-Melbourne facilities from regional competitors unable to absorb inventory write-downs and staff retraining costs.
Pricing Analysis
Input-cost pass-through from Korean and European hyaluronic acid manufacturers concentrates pricing power among established clinic chains with forward-contracting capabilities. Three-tier pricing structure across premium concierge, standard accredited, and economy-limited-service levels stratifies by practitioner registration tier and facility accreditation status. Cost compression in the mid-tier intensifies because TGA compliance mandates trigger capital redeployment away from competitive pricing. Corporate professionals in Sydney's eastern suburbs demonstrate lowest price sensitivity, while regional Queensland patients cross-shop injectable providers aggressively.
Supply Chain Analysis
Reverse-logistics flows for explanted breast implants and expired dermal filler inventory require TGA-mandated adverse event reporting and specialized medical waste handling. Supply concentrates among South Korean hyaluronic acid manufacturers, German laser platform developers, and Swiss botulinum toxin producers. Raw material dependencies include pharmaceutical-grade hyaluronic acid, medical silicone elastomers, and rare-earth laser crystal substrates. Single-source vulnerability from Korean filler manufacturers exposes clinics to currency volatility and shipping delays. Distribution runs through accredited wholesale distributors subject to TGA licensing verification before clinic delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on subscription-based maintenance programs replacing transactional injectable sales, capturing predictable revenue streams from professional women aged 35-50.
For Market Incumbents: To counter non-surgical substitution eroding surgical volumes, Abbvie and Candela Corporation should deepen backward integration into hyaluronic acid precursor supply and radiofrequency device component manufacturing. Certification investment in TGA's streamlined Class IIb pathway accelerates novel formulation time-to-market against mid-tier injectable competitors. For New Entrants and Emerging Players: Capture Perth-Adelaide corridor expansion opportunities where corporate chain presence remains limited and standardized compliance protocols confer first-mover advantage. Telemedicine-integrated consultation models present the most penetrable entry angle for virtual pre-operative assessment and post-procedure monitoring outside Sydney-Melbourne saturation. For Investors and Strategic Acquirers: Roll-up economics work for independent radiofrequency microneedling practitioners because capital-light day-clinic delivery reduces facility overhead and enables multi-site standardization. Long-term viability hinges on TGA regulatory agility rather than device innovation cycles. Monitor TGA reclassification implementation timelines as the critical inflection signal for inventory valuation and procurement restructuring across target acquisitions.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Compliance Protocol Standardization | Multi-site clinic chains leverage centralized regulatory affairs capacity to accelerate device registration across state jurisdictions. |
| Subscription-Based Maintenance Programs | Premium Sydney clinics bundle annual toxin and filler schedules with priority booking privileges for professional women. |
| Perth-Adelaide Geographic Expansion | Corporate chains deploy established TGA compliance infrastructure into undersupplied Western Australian and South Australian markets. |
| Telemedicine Integration Development | Virtual consultation channels reduce geographic friction for pre-operative assessment and post-procedure monitoring in regional Queensland. |
| Hyaluronic Acid Inventory Stockpiling | Melbourne clinics accumulate filler reserves ahead of TGA prescription-only reclassification deadlines compressing procurement timelines. |
Research Methodology
Bottom-up clinic utilization modeling reconciled against top-down device import tracking forms the analytical core of this study. Primary interviews with plastic surgeons, cosmetic clinic operators, TGA regulatory affairs specialists, and hospital procurement managers combined with secondary validation from TGA Register of Therapeutic Goods filings, AHPRA registration databases, Australian Bureau of Statistics trade data, and state health department day-procedure licensing records. Triangulation across these sources ensures procedure volume estimates align with device shipment patterns and practitioner supply constraints.
Historical trendline analysis of breast augmentation, liposuction, injectable, and laser treatment volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include procedure type, client demographic, technology platform, and end-use facility category, with particular attention to AHPRA specialist registration density and TGA device classification tier as industry-specific forecast inputs. CAGRs were derived from fitted trend extrapolation adjusted for regulatory intervention effects and demographic shift projections.
TGA reclassification timeline delays, specialist anesthetist supply constraints, and hyaluronic acid import disruption are the dominant revision risks to forecast assumptions. Practitioners should monitor TGA implementation announcements, AHPRA registration processing rates, and Korean manufacturer shipping schedules for early signals of market trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
US Gender Reassignment Surgery Market