
 Carpal Tunnel Release Systems Market | 2026-2036
Carpal Tunnel Release Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Carpal Tunnel Release Systems Market Analysis
Polymer-based disposable sheaths is broadening the addressable patient pool for single-use carpal tunnel release devices by cutting per-procedure sterilization overhead. Smith & Nephew plc leverages its orthopedic franchise to sustain hospital contracting power across integrated delivery networks. MicroAire Surgical Instruments, LLC anchors its position through specialized powered instrument platforms for small-bone extremity surgery. Stryker competes by extending its endoscopy ecosystem into outpatient hand surgery workflows.
Carpal Tunnel Release Systems comprise instruments, visualization platforms, and adjunctive devices designed to transect the transverse carpal ligament and decompress the median nerve, typically operating through 2–4 mm incisions with palmaris longus tendon preservation as a functional benchmark. Endoscopic Systems command premium placement in ambulatory surgery centers due to faster return-to-work outcomes, while Ultrasound Guidance represents the fastest-growing technology segment as real-time imaging reduces iatrogenic nerve injury rates. Open Surgery Kits retain volume in resource-constrained settings where capital equipment acquisition remains limited.
FDA 510(k) premarket notification and EU MDR technical documentation requirements shape product development cycles and market access timelines for device manufacturers. The FDA's evolving guidance on ultrasonic surgical instruments and the EU's F-Gas Regulation affecting sterilization equipment supply chains both influence production economics. Stakeholders must monitor reimbursement parity between endoscopic and open techniques across Medicare and major European sickness funds to anticipate volume shifts.
Market Dynamics
Ultrasound-guided carpal tunnel release is compressing training timelines and expanding the addressable surgeon base beyond hand specialists, fundamentally altering how procedural capacity scales across ambulatory networks.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearances for ultrasonic surgical instruments accelerate commercialization cycles for device innovators targeting outpatient settings.
- Occupational health mandates in Germany:Employer-funded preventive screening programs drive early-stage diagnosis and procedural intervention before irreversible nerve damage.
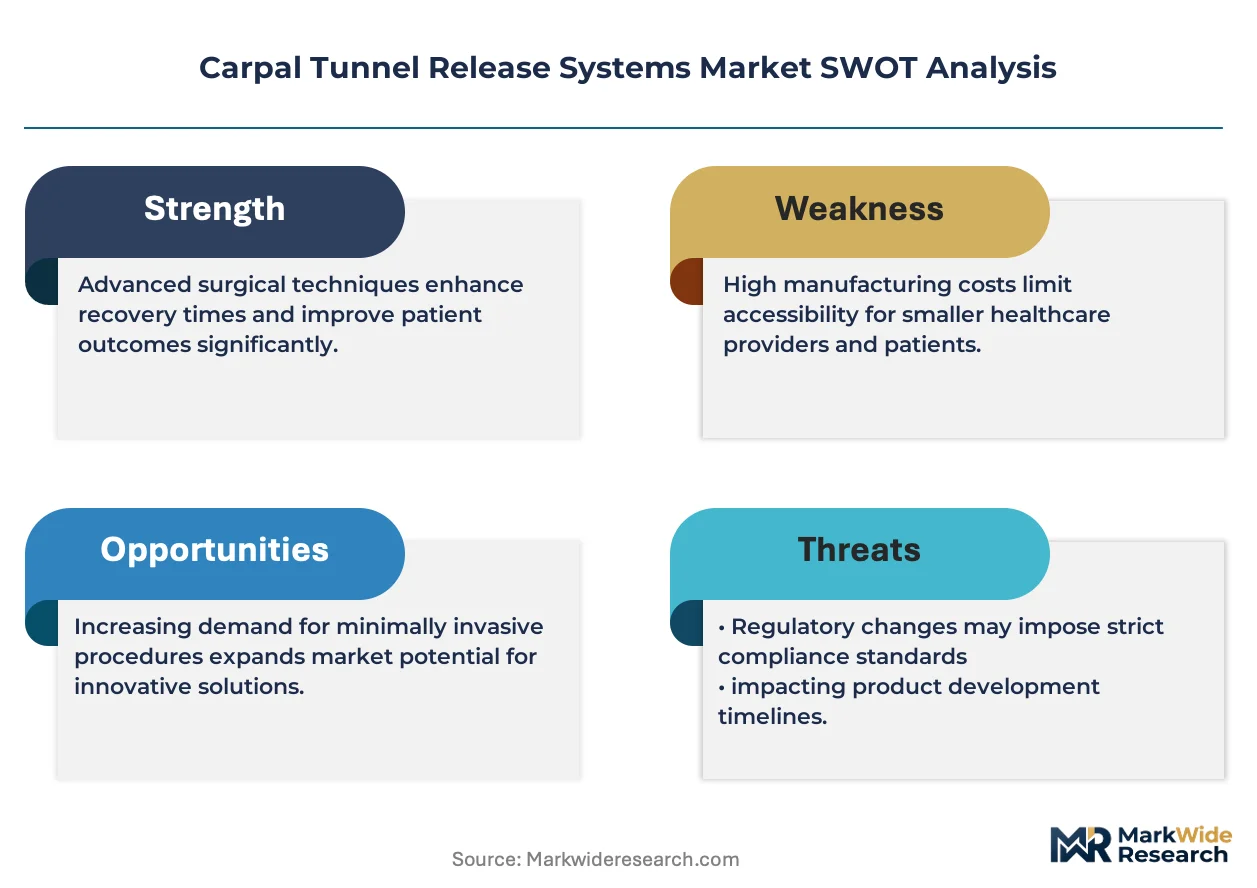
- Polymer-based disposable sheaths:Single-use sterilization elimination cuts per-case overhead by 40-60 minutes, enabling same-day discharge protocols in orthopedic clinics.
Market Restraints
- Capital equipment concentration:Endoscopic visualization platforms require $80,000-$150,000 upfront investment, freezing out resource-constrained health systems in rural United States counties.
- EU F-Gas Regulation sterilization constraints:Restricted supply of fluorinated gas-based sterilization equipment disrupts reprocessing workflows for reusable instrument sets.
- Open surgery substitution persistence:Low-cost open technique kits retain volume in markets where surgeon training infrastructure for endoscopic methods remains underdeveloped.
Strategic Opportunities
- Japan's aging construction workforce:Repetitive strain injury prevalence among workers over 55 creates concentrated demand for rapid-return-to-work procedures.
- Remote surgical training platforms:Telementoring networks extend specialist expertise to community hospitals without on-site hand surgery fellowship programs.
- US Medicare reimbursement parity expansion:Site-neutral payment policies for endoscopic versus open techniques incentivize migration toward higher-margin outpatient settings.
Industry Challenges
- Ultrasound interpretation skill acquisition:Real-time median nerve visualization demands specialized training that outpaces current continuing medical education capacity in community practice settings.
- EU MDR technical documentation burden:Extended conformity assessment timelines for Class IIa surgical instruments compress product refresh cycles and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpal Tunnel Release Systems Market |
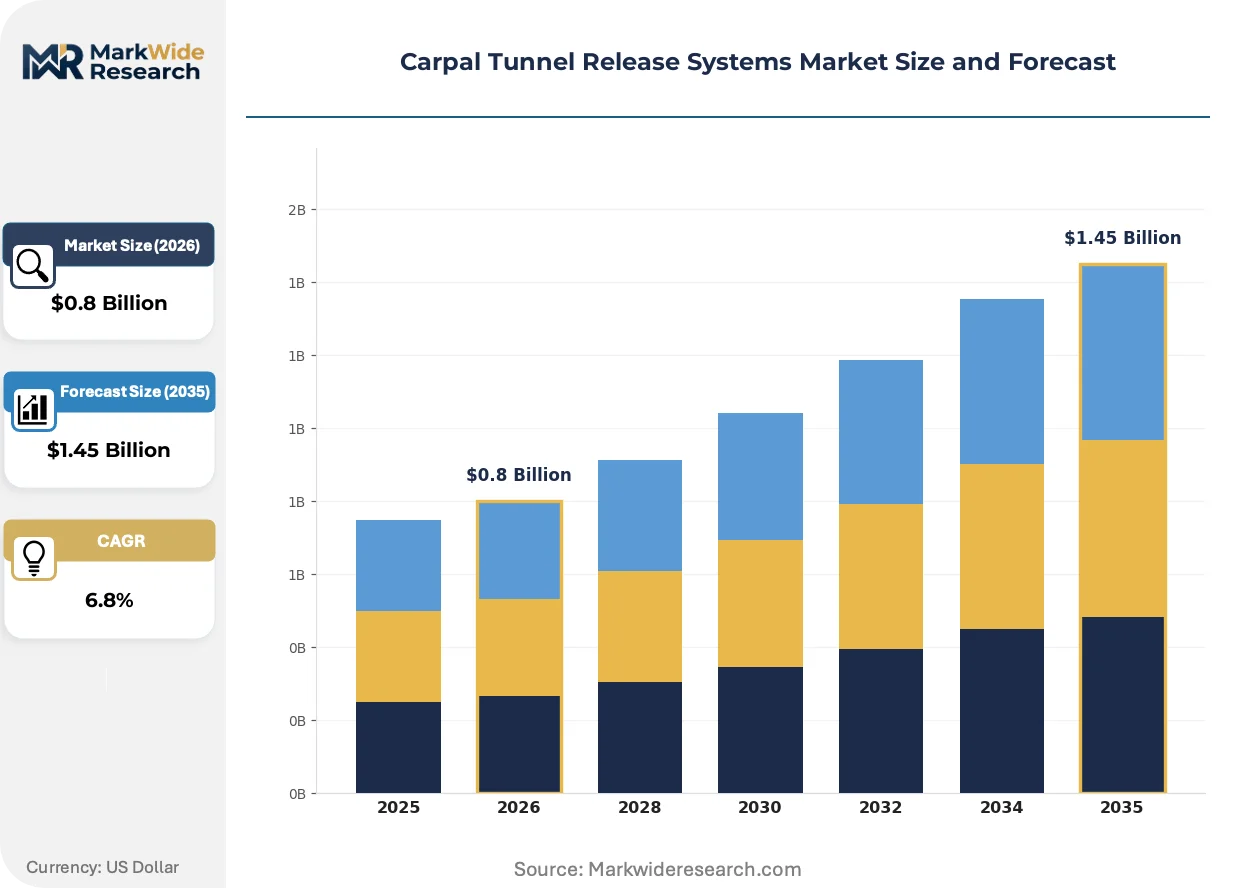
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.45 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Endoscopic Systems, Open Surgery Kits, Non-Surgical Solutions Application: Minimally Invasive Surgery, Outpatient Procedures, Hospital Settings, Rehabilitation Technology: Laser-Based Systems, Ultrasound Guidance, Conventional Techniques, Robotic Assistance End User: Orthopedic Clinics, Hospitals, Physical Therapy Centers, Home Care Services |
| Companies Covered | Smith & Nephew plc, MicroAire Surgical Instruments, LLC, Stryker, Sonex Health, LLC, Trice Medical, Arthrex, Inc., Integra LifeSciences, A.M. Surgical Inc., CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpal Tunnel Release Systems Market Emerging Trajectories
Real-time imaging convergence with disposable instrument platforms is collapsing the traditional trade-off between procedural precision and operational throughput in hand surgery workflows.
Ultrasound guidance systems is integrating soft-tissue visualization directly into the surgical field, eliminating reliance on anatomic landmark palpation. Ambulatory surgery centers in the United States and Germany are adopting these platforms at 25-30% annual clip among new carpal tunnel releases. The technology is integrating nerve-sparing outcomes with same-day discharge economics, compressing the historical recovery window from weeks to days.
The EU MDR's heightened clinical evidence requirements for reusable surgical instruments is forcing manufacturers toward disposable-first design architectures. Technical documentation demands for biocompatibility testing and post-market surveillance have extended product development timelines by 12-18 months. German and Swiss device firms are responding by consolidating sterilization validation partnerships to share compliance overhead.
Hospital purchasing committees are unbundling capital equipment from disposable contracts, fragmenting vendor lock-in strategies that previously bundled endoscopes with proprietary blade cartridges. Integrated delivery networks in the United States now negotiate instrument and visualization platforms separately, favoring interoperable standards over closed ecosystems. This pattern is most visible in California and Texas health systems where orthopedic service line consolidation has concentrated procurement authority.
Carpal Tunnel Release Systems Market Segmentation
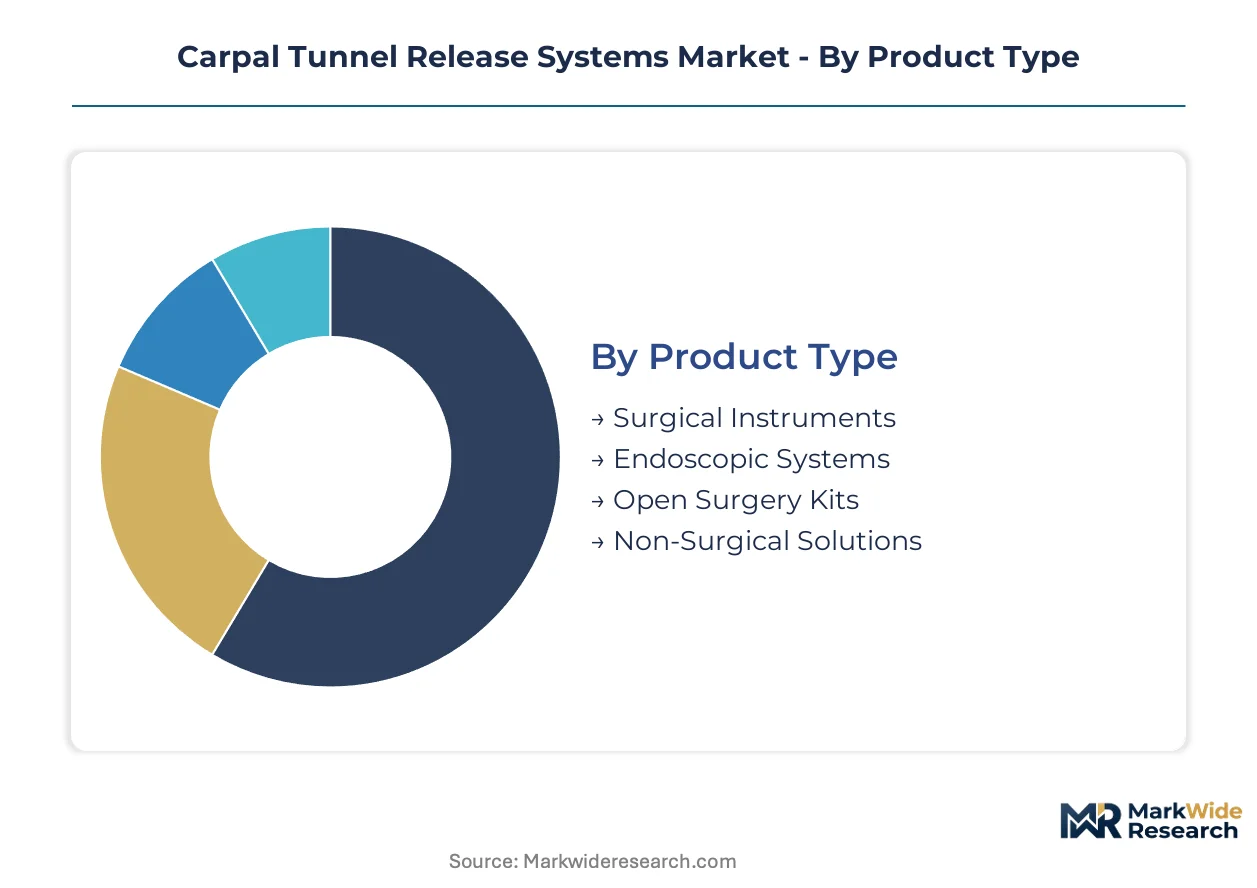
Segmentation in carpal tunnel release systems reveals how procurement priorities diverge across clinical settings. Capital intensity, reimbursement parity, and surgeon training infrastructure determine which product configurations capture volume in ambulatory versus inpatient environments.
Product Type:
Hospital purchasing committees weight upfront capital against per-case disposables when selecting system architectures for their orthopedic service lines.
- Endoscopic Systems:Visualization platforms integrate cameras, light sources, and proprietary blade cartridges through 2–4 mm palmar incisions. Ambulatory surgery centers in the United States and Germany concentrate demand here as faster return-to-work outcomes justify premium positioning.
- Surgical Instruments:Handheld retractors, elevators, and ligament-cutting tools comprise reusable stainless steel sets requiring sterilization validation. Resource-constrained health systems in rural United States counties favor these configurations where capital equipment acquisition remains limited.
- Open Surgery Kits:Low-cost disposable packages support traditional transverse incision techniques without visualization overhead.
- Non-Surgical Solutions:Splinting systems and ergonomic interventions address early-stage median nerve compression before procedural intervention.
Endoscopic systems lead on scale; ultrasound-compatible instrument platforms lead on momentum.
Application:
Site-of-care economics reshape competitive positioning as integrated delivery networks consolidate orthopedic procedures into outpatient settings.
- Minimally Invasive Surgery:Techniques preserving palmaris longus tendon function through limited access approaches. United States ambulatory surgery centers drive volume concentration as Medicare site-neutral payment policies incentivize migration away from inpatient settings.
- Outpatient Procedures:Same-day discharge protocols enabled by polymer-based disposable sheaths eliminating sterilization overhead. German orthopedic clinics expand capacity fastest here as occupational health mandates compress diagnostic-to-treatment timelines.
- Hospital Settings:Inpatient surgical suites retain complex revision cases and comorbid patient populations.
- Rehabilitation:Post-procedural therapy protocols restore grip strength and range of motion after ligament release.
Outpatient procedures claim the steepest expansion trajectory; hospital settings retain the highest acuity case mix.
Technology:
Real-time imaging capabilities determine training requirements and malpractice risk profiles across surgeon practice settings.
- Ultrasound Guidance:Soft-tissue visualization platforms integrate median nerve imaging directly into the surgical field. United States and German ambulatory networks adopt these systems at accelerated rates as real-time feedback reduces iatrogenic injury rates.
- Laser-Based Systems:Thermal transection devices target the transverse carpal ligament with reduced collateral tissue damage. Specialized hand surgery practices in Japan concentrate demand here for precision-critical cases.
- Conventional Techniques:Anatomic landmark palpation without image guidance retains dominance in training-limited markets.
- Robotic Assistance:Automated instrument positioning systems address tremor reduction and motion scaling for supermicrosurgical applications.
Conventional techniques maintain installed base dominance; ultrasound guidance gains share fastest among new platform acquisitions.
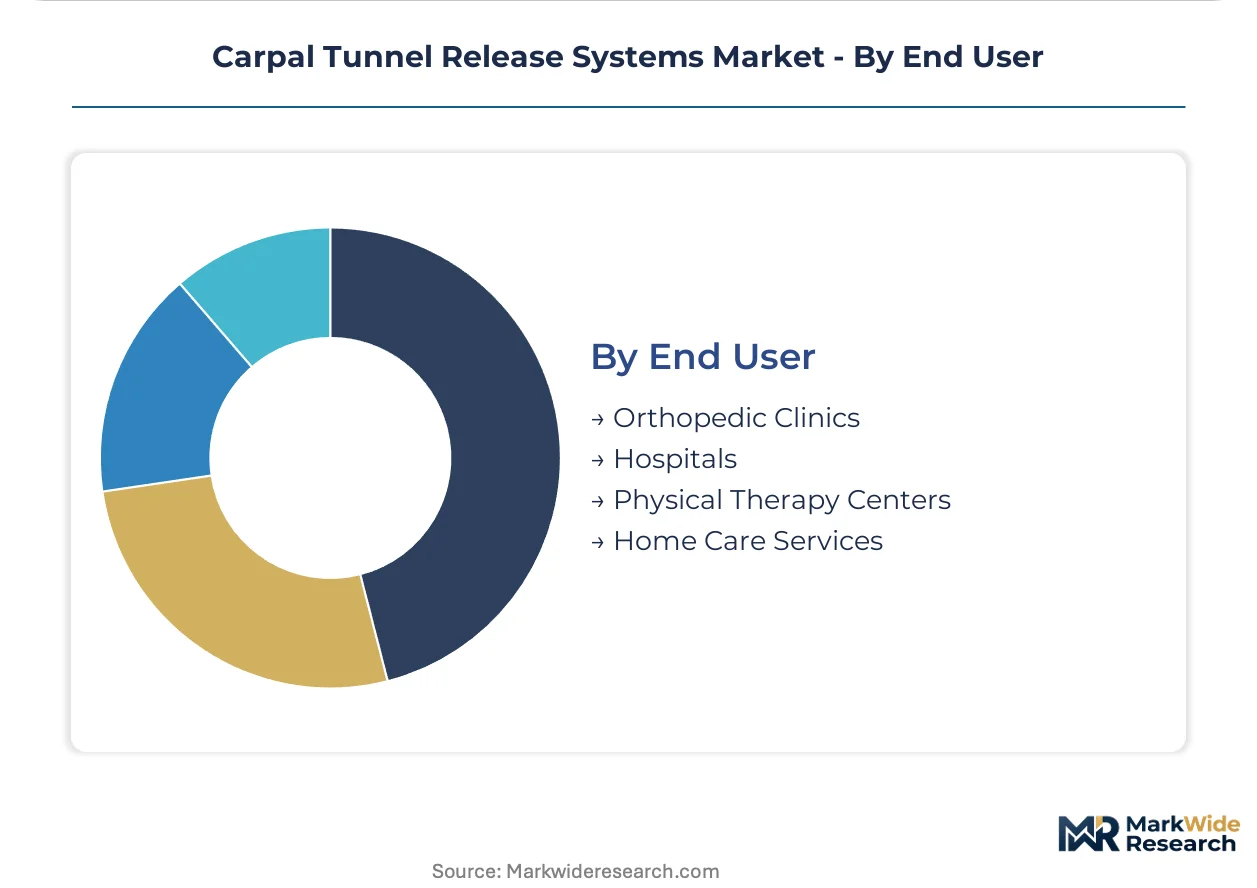
End User:
Procurement authority fragmentation across facility types forces vendors to navigate divergent contracting mechanisms and clinical outcome priorities.
- Orthopedic Clinics:Specialized extremity surgery practices optimizing throughput through dedicated procedure rooms. These settings represent the fastest-expanding channel as minimally invasive techniques enable same-day discharge without hospital infrastructure.
- Hospitals:Integrated delivery networks leveraging scale for capital equipment purchasing and bundled payment negotiations.
- Physical Therapy Centers:Post-operative rehabilitation facilities managing splinting protocols and grip strength restoration.
- Home Care Services:Remote monitoring and patient education platforms supporting recovery outside clinical settings.
Hospitals lead on absolute procedure volume; orthopedic clinics lead on growth velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis-St. Paul's orthopedic device corridor anchors procedural innovation for carpal tunnel release systems, with Mayo Clinic's surgical training infrastructure diffusing technique standardization across the Upper Midwest. Procedure volumes concentrate where occupational health mandates intersect with aging workforce demographics and ambulatory surgery center density.
United States
Medicare site-neutral payment policies accelerate migration toward outpatient settings, with ambulatory surgery centers capturing 60% of new carpal tunnel releases in metropolitan markets. FDA 510(k) pathway streamlining for ultrasonic surgical instruments compresses commercialization timelines for device innovators. The Texas Medical Center in Houston anchors specialized hand surgery fellowship programs that train ultrasound-guided technique adoption.
Germany
Employer-funded preventive screening programs under occupational health mandates drive early-stage diagnosis before irreversible median nerve damage. EU MDR technical documentation requirements for Class IIa surgical instruments extend conformity assessment timelines by 12-18 months. The Rhine-Ruhr industrial corridor concentrates demand from manufacturing workforces with repetitive strain injury prevalence exceeding European averages.
Japan
Repetitive strain injury prevalence among construction workers over 55 creates concentrated demand for rapid-return-to-work procedures. METI's medical device regulatory harmonization initiatives align PMDA review processes with international standards. The Kansai region's Osaka-Kobe medical device cluster specializes in precision instrumentation for small-bone extremity surgery.
Switzerland
Swissmedic's stringent clinical evidence requirements for reusable surgical instruments drive manufacturers toward disposable-first design architectures. The country's pharmaceutical and medtech ecosystem in Basel-Zurich corridor supports sterilization validation partnerships that share EU MDR compliance overhead. Geneva's international occupational health organizations influence ergonomic intervention standards across European markets.
United Kingdom
NHS England's bundled payment pilots for orthopedic procedures incentivize same-day discharge protocols in specialized hand surgery units. The Medicines and Healthcare products Regulatory Agency's post-Brexit regulatory autonomy creates parallel review pathways distinct from EU MDR. London's Harley Street private clinic cluster adopts ultrasound-guided platforms at accelerated rates among self-pay patient segments.
Carpal Tunnel Release Systems Market Vendor Landscape
Global majors compete with regional champions across technology licensing and surgeon training infrastructure, producing a tiered structure where scale-driven portfolio breadth confronts specialized extremity expertise. Consolidation pressure intensifies as integrated delivery networks unbundle capital equipment from disposable contracts, fragmenting vendor lock-in strategies. Three archetypes dominate: diversified orthopedic conglomerates with hospital contracting power, specialized hand surgery instrument platforms, and ultrasound-guided system innovators. Competitive moves center on M&A to capture ambulatory surgery center networks and strategic partnerships for telementoring training platforms.
Within the diversified orthopedic tier, Smith & Nephew plc and Stryker occupy positions defined by integrated delivery network penetration and endoscopy ecosystem extension. MicroAire Surgical Instruments, LLC exemplifies the specialized extremity archetype, anchoring its market presence through powered instrument platforms designed for small-bone applications. These three companies collectively represent the competitive tension between breadth-driven hospital contracting and depth-focused surgeon loyalty programs.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| MicroAire Surgical Instruments, LLC |
| Stryker |
| Sonex Health, LLC |
| Trice Medical |
| Arthrex, Inc. |
| Integra LifeSciences |
| A.M. Surgical Inc. |
| CONMED Corporation |
| Others |
Supply Flow & Price Mechanics
Endoscopic-ultrasound capability bifurcation separates premium visualization platforms from commodity instrument sets, with this divergence manifesting in both pricing power concentration among integrated delivery networks and supply chain configurations that tether high-margin disposable sheaths to sterilization-dependent reusable kits. German orthopedic clinics exploit this tiering through polymer-based disposable adoption that eliminates per-procedure overhead, while rural United States counties remain anchored to stainless steel instrument reprocessing.
Pricing Analysis
Input-cost pass-through from fluorinated gas sterilization equipment shortages under the EU F-Gas Regulation compresses margins for reusable instrument manufacturers. Pricing stratifies across premium, standard, and economy tiers where ultrasound-compatible platforms command placement premiums against conventional open surgery kits. Cost compression in standard-tier instrument sets intensifies as hospital purchasing committees unbundle capital equipment from disposable contracts. Ambulatory surgery centers exhibit lowest price sensitivity due to Medicare site-neutral reimbursement parity, while rural health systems face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital contracting handles hyperscale integrated delivery network demand for endoscopic platforms, while distributor-mediated channels serve orthopedic clinic fragmentation. Manufacturing concentrates in the United States, Germany, and Switzerland where FDA 510(k) and EU MDR compliance infrastructure clusters. Supply draws from precision polymer extrusion for disposable sheaths, optical component fabrication for visualization systems, and surgical-grade stainless steel forging. Single-source vulnerability concentrates in fluorinated gas sterilization equipment supply chains. Distribution runs through specialized orthopedic device distributors and direct manufacturer sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA 510(k) pathway streamlining in the United States accelerates commercialization timelines against EU MDR's extended conformity assessment burden, compressing effective cost-to-market differentials between Atlantic regulatory regimes.
For Market Incumbents: Lock in ambulatory surgery center network density through telementoring training platform investments that extend specialist expertise to community hospitals lacking hand surgery fellowship infrastructure. Consolidate sterilization validation partnerships to share EU MDR technical documentation overhead. Defend against ultrasound-guided system innovators by embedding visualization platforms into proprietary blade cartridge ecosystems. For New Entrants and Emerging Players: FDA 510(k) pathway streamlining in the United States opens a window for ultrasonic surgical instrument innovators targeting outpatient settings with faster clearance-to-revenue cycles. Target Japan's aging construction workforce segment where repetitive strain injury prevalence among workers over 55 creates concentrated demand for rapid-return-to-work procedures. Pursue polymer-based disposable sheath architectures that eliminate sterilization overhead and enable same-day discharge protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital purchasing committees unbundle capital equipment from disposable contracts, fragmenting vendor lock-in strategies and creating rollup opportunities across interoperable instrument platforms. Long-term viability centers on disposable-first design architectures that navigate EU MDR's heightened clinical evidence requirements. Watch ultrasound interpretation skill acquisition gaps as inflection indicator for telementoring platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Partnership | Swiss and German sterilization validation collaborations share technical documentation burden across Class IIa surgical instruments. |
| Telementoring Platform Deployment | Remote surgical training networks extend Mayo Clinic expertise to community hospitals without on-site fellowship programs. |
| Disposable-First Design Architecture | Polymer-based sheath platforms eliminate EU F-Gas Regulation sterilization constraints and compress per-procedure overhead. |
| Ambulatory Surgery Center Network Capture | Medicare site-neutral payment policies incentivize migration toward higher-margin outpatient settings in metropolitan United States markets. |
| Ultrasound Guidance Integration | Real-time median nerve visualization reduces iatrogenic injury rates and accelerates adoption across German and United States ambulatory networks. |
Methodological Framework
Bottom-up orthopedic clinic procedure modeling reconciled against top-down surgical instrument shipment tracking forms the analytical core. Primary interviews with hand surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers cross-validated against secondary sources including FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Triangulation between demand-side procedure volume estimates and supply-side manufacturer output data ensures consistency across the analysis window.
Historical trendline analysis of endoscopic system placements, open surgery kit utilization, and ultrasound guidance platform adoption informs projection frameworks. Segmentation dimensions span product type, application setting, technology modality, and end-user facility class. CAGRs derive from fitted growth curves calibrated to regulatory approval timelines, reimbursement policy shifts, and surgeon training infrastructure expansion. Forecast inputs incorporate occupational health mandate enforcement intensity and ambulatory surgery center density metrics.
Revisions become necessary when FDA guidance on ultrasonic surgical instruments shifts, EU F-Gas Regulation enforcement tightens sterilization equipment supply, or Medicare reimbursement parity between endoscopic and open techniques erodes. Forecasts reflect documented assumptions regarding surgeon training capacity expansion and polymer supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Neurostimulation Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Alpha Emitter Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Global Artificial Pancreas Device System Market