
 Global Refractive Surgery Devices Market | 2026-2036
Global Refractive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refractive Surgery Devices Market Foresight
Femtosecond laser technology is restructuring corneal flap creation economics by eliminating blade-dependent consumables and reducing complication rates. Johnson & Johnson Vision leverages its integrated cataract-refractive ecosystem to sustain recurring revenue streams across surgical consumables. Carl Zeiss Meditec anchors premium positioning through its proprietary SMILE platform, while Alcon competes across excimer and femtosecond modalities with broad portfolio coverage.
Refractive surgery devices comprise precision ophthalmic instruments designed to reshape corneal curvature and correct ametropia, typically operating at ultraviolet wavelengths with sub-micron tissue ablation precision. Laser systems command the dominant revenue share, while diagnostic devices gain traction as preoperative wavefront analysis becomes standard protocol for customized ablation profiles. Excimer laser technology remains the established workhorse for surface ablation, though femtosecond platforms represent the fastest-growing segment due to all-laser LASIK adoption and expanding presbyopia treatment applications.
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU MDR and CE marking requirements shape product standards across European markets. Japan's PMDA enforces rigorous clinical evidence thresholds for novel laser platforms, effectively filtering market access. Stakeholders must monitor evolving reimbursement classifications for advanced diagnostic-guided procedures as payor frameworks increasingly differentiate between standard and customized treatment protocols.
Market Dynamics
Femtosecond laser platforms are consolidating surgical workflows by collapsing flap creation and lenticule extraction into unified all-laser protocols, compressing capital deployment cycles for ambulatory surgical centers.
Growth Catalysts
- Presbyopia-correcting IOL integration:Cataract-refractive convergence is expanding addressable patient pools beyond myopic populations into age-related vision correction. Ophthalmology clinics in Germany and Japan report rising dual-procedure scheduling.
- EU MDR streamlined equivalence pathways:Modified 510(k)-style abridged reviews for laser platform iterations are accelerating device update cycles. Manufacturers leverage predicate device libraries to reduce regulatory lag.
- Wavefront-guided ablation standardization:Diagnostic-guided customization is displacing conventional LASIK as the default protocol in premium service tiers. Preoperative aberrometry integration is now mandatory for reimbursed procedures in several national health frameworks.
Market Restraints
- Excimer laser gas supply concentration:Argon-fluoride mixture production clusters in Eastern European industrial zones. Geopolitical friction threatens fluorine precursor availability for ultraviolet laser systems.
- PMDA clinical evidence thresholds:Japan's pharmaceutical and medical device agency mandates extended safety tracking for novel corneal reshaping modalities. Market entry timelines stretch 18-24 months beyond FDA clearance benchmarks.
- Surface ablation resurgence:Transepithelial photorefractive keratectomy eliminates flap-related complications. Cost-sensitive providers in public hospital systems are reverting to mechanical surface protocols.
Strategic Opportunities
- India's tier-2 city penetration:Refractive surgery volume in Chennai, Hyderabad, and Pune is outpacing metropolitan saturation. Domestic chains are deploying mobile diagnostic units to capture dispersed demand.
- SMILE-to-LASIK conversion protocols:Small incision lenticule extraction platforms are adapting to treat hyperopia and mixed astigmatism. Carl Zeiss Meditec's proprietary interface is expanding treatable refractive error ranges.
- Subscription service models:Device-as-a-service financing is lowering capital barriers for independent ophthalmology practices. Leasing structures bundle maintenance, software updates, and consumable replenishment.
Industry Challenges
- Femtosecond laser engineer scarcity:Ultrafast optics calibration and servo-mechanical alignment require specialized training. Academic programs in laser-tissue interaction produce insufficient technician throughput.
- Legacy excimer platform stranded asset risk:Practices holding depreciated broad-beam systems face upgrade-or-obsolescence decisions. Residual value recovery is compressing as all-laser adoption accelerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refractive Surgery Devices Market |
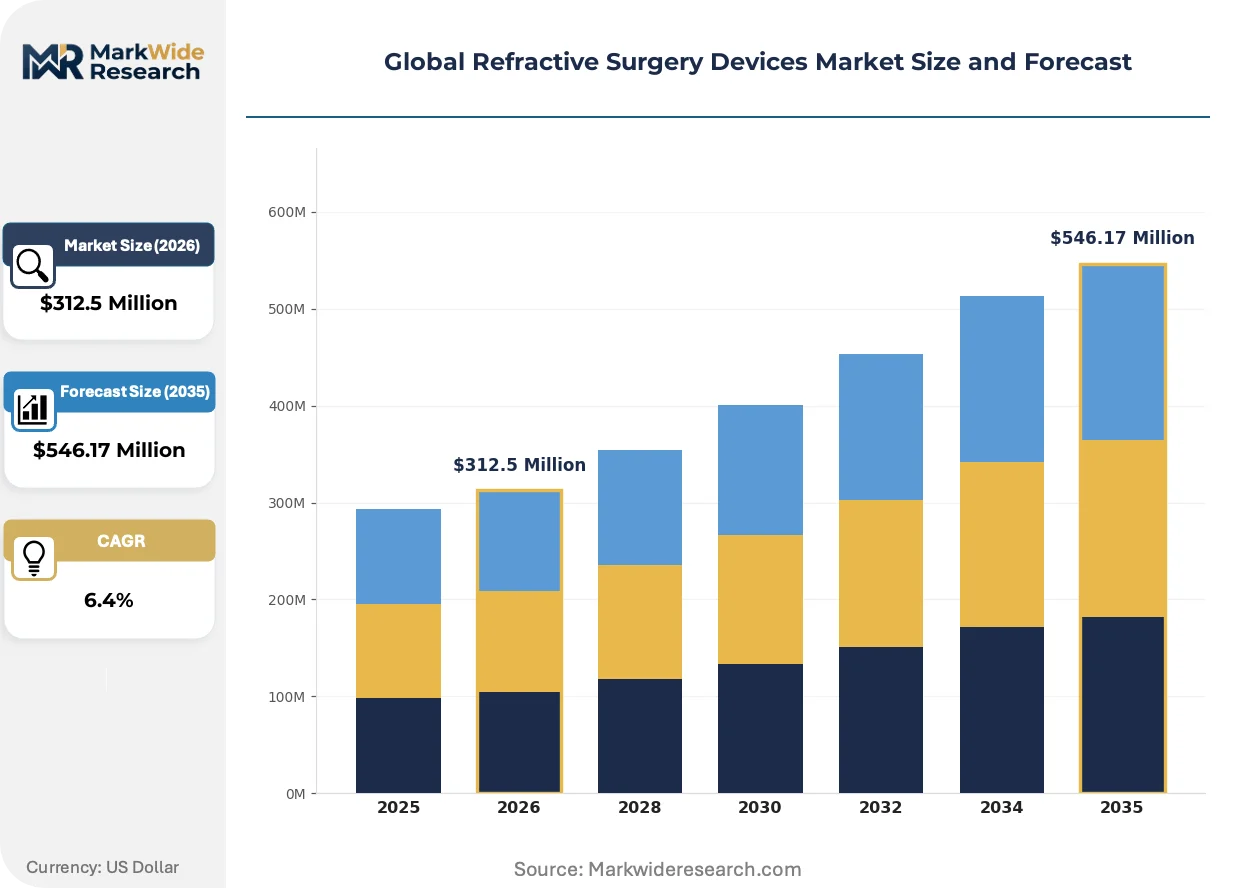
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Diagnostic Devices, Surgical Instruments, Visualization Systems Technology: Excimer Laser, Femtosecond Laser, Wavefront Technology, Corneal Topography Application: Myopia Correction, Hyperopia Correction, Astigmatism Correction, Presbyopia Treatment End User: Eye Care Centers, Ophthalmic Clinics, Ambulatory Surgical Centers, Specialty Hospitals |
| Companies Covered | Johnson & Johnson Vision, Carl Zeiss Meditec, Alcon, Bausch & Lomb, NIDEK, SCHWIND eye-tech-solutions, Ziemer Ophthalmic Systems, TOPCON, Lensar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refractive Surgery Devices Market Shifts & Advancements
Corneal diagnostic imaging and laser ablation systems are converging into closed-loop surgical ecosystems, enabling real-time tissue response monitoring and intraoperative plan modification.
Topography-guided excimer laser systems are decentralizing treatment planning authority from centralized manufacturing specifications to clinic-level customization engines. Ambulatory surgical centers in the United States are adopting surgeon-specific ablation profile libraries. This shift is compressing device vendor control over procedural outcomes while elevating physician brand equity.
Japan's PMDA revised its software-as-a-medical-device guidance in 2023, explicitly classifying AI-powered refractive outcome prediction algorithms as regulated entities. Laser platform manufacturers must now submit standalone clinical validation for embedded machine learning modules. Femtosecond system vendors with integrated nomogram optimization are restructuring regulatory submission strategies to address this bifurcation.
Patient financing platforms are displacing out-of-pocket payment as the dominant transaction mode for elective refractive procedures. Third-party medical credit providers have penetrated ophthalmology practice management systems in Germany and the United States. This behavioral shift is expanding addressable demand among middle-income demographics previously excluded by lump-sum cost barriers.
Global Refractive Surgery Devices Market Segmentation
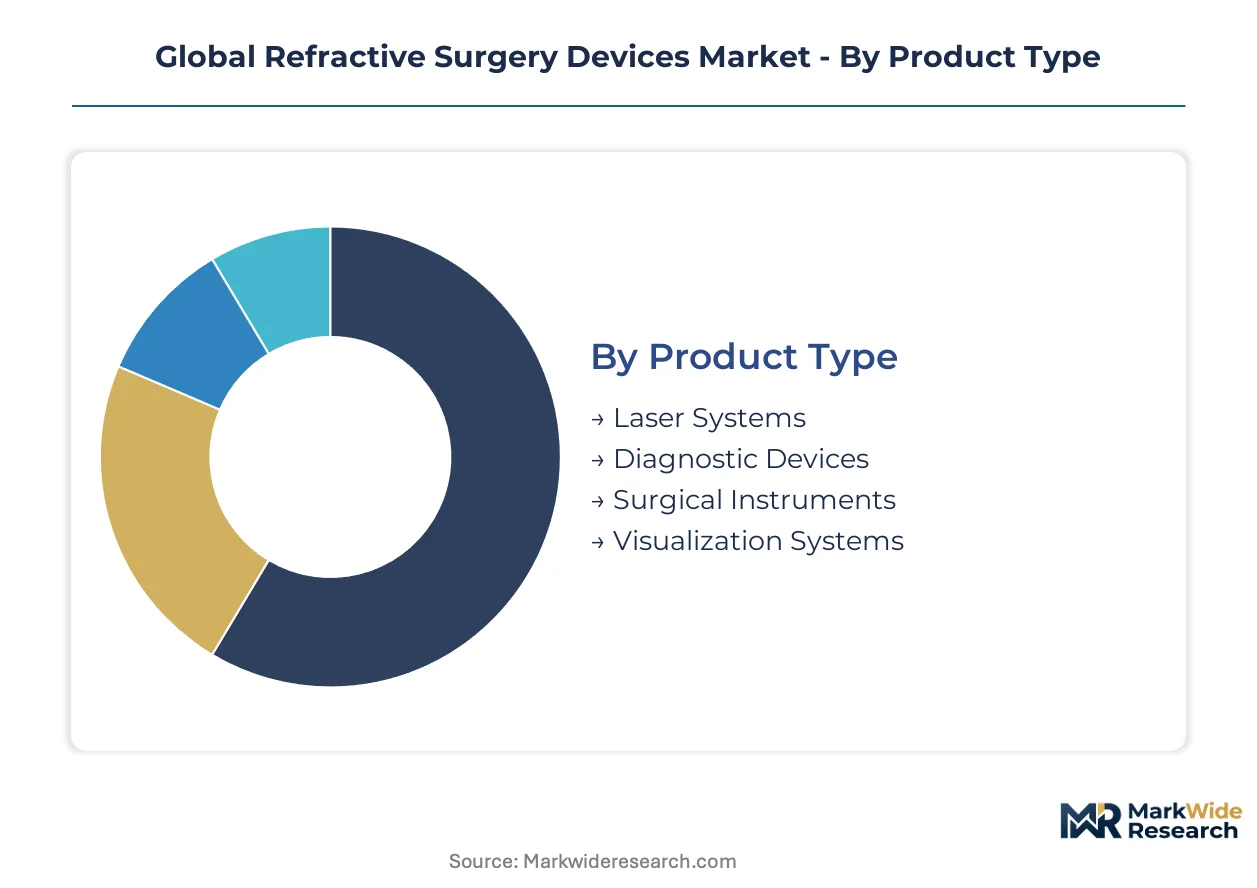
Refractive surgery device segmentation reveals how capital flows concentrate around laser platforms while diagnostic and visualization technologies capture ancillary revenue. Understanding these category boundaries clarifies where procurement decisions fragment across clinical workflows versus where integrated system purchases dominate.
Product Type:
Supply concentration in laser system manufacturing creates procurement bottlenecks for ambulatory surgical centers seeking multi-modality platforms. Component sourcing for ultraviolet optics and ultrafast pulse generators clusters among specialized photonics suppliers in Germany and Japan.
- Laser Systems:These platforms deliver ultraviolet wavelength energy for corneal tissue ablation with sub-micron precision. Demand concentrates in the United States where ambulatory surgical centers prioritize all-laser LASIK configurations to minimize flap-related complications. Capital replacement cycles accelerate as femtosecond platforms displace mechanical microkeratomes.
- Diagnostic Devices:Wavefront aberrometers and corneal tomography systems map preoperative optical aberrations. Germany's ophthalmology clinics drive adoption of combined diagnostic workstations that integrate topography and aberrometry into unified preoperative protocols. Reimbursement frameworks increasingly mandate diagnostic-guided documentation for customized procedures.
- Surgical Instruments:Microkeratomes, speculums, and suction rings support procedural execution. Japanese manufacturers supply precision-engineered mechanical components to regional device assemblers.
- Visualization Systems:Operating microscopes with integrated OCT guidance enable real-time tissue monitoring. Demand from specialty hospitals in India rises as surgical volume expands beyond metropolitan centers.
Today's leader: Laser Systems. Tomorrow's challenger: Diagnostic Devices.
Technology:
Cost tier differentiation separates premium femtosecond platforms from established excimer workhorses, with wavefront and topography technologies occupying mid-tier diagnostic positions. Procurement budgets fragment across capital-intensive laser purchases versus recurring diagnostic consumables.
- Excimer Laser:Argon-fluoride gas discharge systems generate 193nm ultraviolet pulses for photorefractive keratectomy and LASIK surface ablation. Public hospital systems in Japan retain broad-beam excimer platforms for cost-sensitive surface ablation protocols. Gas supply vulnerabilities in Eastern European industrial zones threaten operational continuity.
- Femtosecond Laser:Solid-state ultrafast oscillators create precise corneal incisions without thermal collateral damage. The United States leads platform deployment as ambulatory surgical centers convert to all-laser workflows. Presbyopia-correcting lenticule extraction expands treatable patient demographics beyond myopic populations.
- Wavefront Technology:Hartmann-Shack sensor arrays measure high-order optical aberrations for customized ablation planning. Integration into standard preoperative protocols accelerates in German reimbursement frameworks.
- Corneal Topography:Placido disk and Scheimpflug imaging systems map anterior corneal curvature and elevation. Adoption concentrates in Indian tier-2 cities where mobile diagnostic units serve dispersed patient populations.
Excimer Laser anchors current installed base. Femtosecond Laser climbs the fastest.
Application:
Volume distribution across refractive error types reflects demographic myopia prevalence while presbyopia treatment emerges as a margin expansion opportunity. Patient age profiles determine procedure selection and financing pathway eligibility.
- Myopia Correction:LASIK and SMILE procedures address spherical refractive errors in younger patient cohorts. China and South Korea report highest procedural volumes driven by juvenile myopia epidemics. Surface ablation resurgence in cost-sensitive public systems competes with premium all-laser alternatives.
- Hyperopia Correction:Excimer laser ablation steepens central corneal curvature to enhance focal power. Demand concentrates in Gulf Cooperation Council states where presbyopic hyperopes seek spectacle independence.
- Astigmatism Correction:Toric ablation profiles or arcuate incisions address cylindrical refractive components. Japanese clinics lead topography-guided customization for irregular astigmatism cases.
- Presbyopia Treatment:Corneal inlays, monovision LASIK, and presbyopia-correcting IOLs target age-related accommodation loss. German ophthalmology practices report rising dual-procedure scheduling combining cataract extraction with refractive optimization.
Myopia Correction dominates procedure volume. Presbyopia Treatment offers steepest margin expansion trajectory.
End User:
Customer type fragmentation splits procurement authority between independent ophthalmologists, hospital administrators, and corporate clinic chains with divergent capital deployment timelines. Financing structure preferences diverge sharply across these institutional categories.
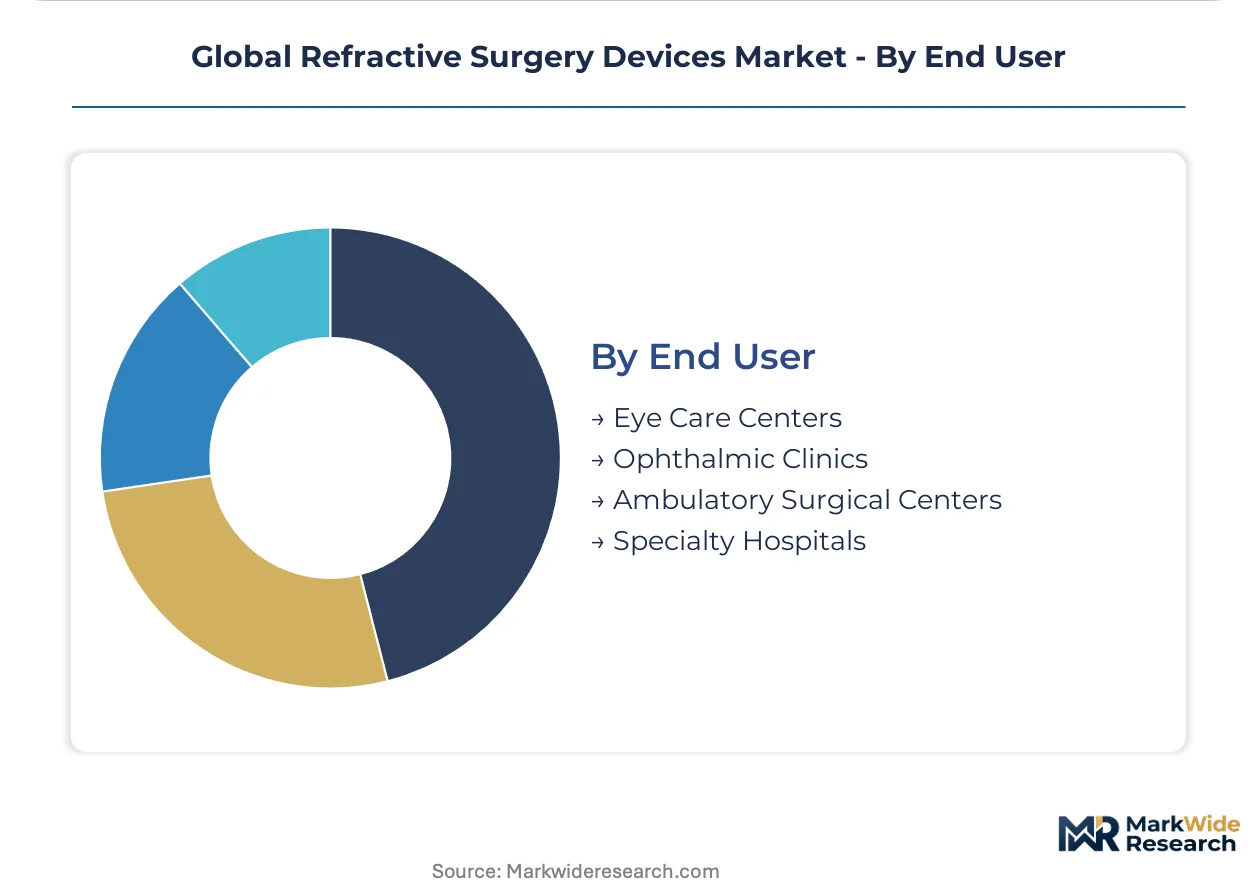
- Eye Care Centers:Comprehensive vision correction facilities combine optical retail with surgical services. Chains in India deploy standardized equipment configurations across Chennai, Hyderabad, and Pune locations. Mobile diagnostic units extend reach into underserved catchment areas.
- Ophthalmic Clinics:Physician-owned practices prioritize platform flexibility and surgeon-specific customization capabilities. The United States sees fastest adoption of subscription service models bundling device access with maintenance and software updates.
- Ambulatory Surgical Centers:Focused surgical facilities optimize throughput for elective refractive procedures. German centers lead conversion to integrated cataract-refractive workflows. Outpatient preference drives capital investment in compact, multi-function laser platforms.
- Specialty Hospitals:Academic and tertiary institutions manage complex refractive cases and trainee education. Japan's PMDA-mandated safety tracking requirements extend evaluation timelines for novel platform introductions.
Ambulatory Surgical Centers capture fastest volume growth. Ophthalmic Clinics retain pricing power through physician brand equity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision photonics corridor anchors refractive surgery device manufacturing, with Jena and Oberkochen clusters supplying ultraviolet optics and ultrafast pulse generators to global OEMs. National health frameworks in Japan and the United States drive divergent adoption curves for premium vision correction platforms.
United States
Ambulatory surgical centers in Texas and Florida drive femtosecond laser deployment as outpatient preference accelerates all-laser LASIK conversion. FDA 510(k) clearance pathways enable rapid platform iteration for predicate-established laser systems. Dallas and Miami surgical clusters report fastest subscription service model uptake among independent ophthalmology practices.
Germany
EU MDR streamlined equivalence pathways compress regulatory lag for laser platform updates originating from Baden-Württemberg engineering centers. Reimbursement frameworks mandate diagnostic-guided documentation, elevating combined topography-aberrometry workstation demand. Heidelberg and Munich clinics lead integrated cataract-refractive workflow adoption.
Japan
PMDA clinical evidence thresholds extend market entry timelines 18-24 months beyond FDA benchmarks for novel corneal reshaping modalities. Tokyo and Osaka academic centers manage complex refractive cases under extended safety tracking requirements. METI industrial policy supports domestic precision optics supply chains for excimer laser component sourcing.
India
Tier-2 city penetration in Chennai, Hyderabad, and Pune outpaces metropolitan saturation as domestic chains deploy mobile diagnostic units. CDSCO regulatory harmonization with IMDRF standards accelerates import license processing for established laser platforms. Karnataka's medical device manufacturing zones attract component assembly investments from global OEMs.
United Arab Emirates
Gulf Cooperation Council demand concentrates in Dubai and Abu Dhabi for hyperopia correction among presbyopic patient cohorts seeking spectacle independence. MOHAP medical device registration requirements emphasize post-market surveillance for imported laser platforms. Dubai Healthcare City clusters attract premium refractive surgery volume from regional medical tourism flows.
Global Refractive Surgery Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory submission capabilities and service network density. The vendor base concentrates around integrated ophthalmic conglomerates with cataract-refractive ecosystem breadth, mid-cap laser specialists with femtosecond platform focus, and precision optics suppliers with captive component manufacturing. Strategic moves center on predicate device leveraging for accelerated clearance cycles and subscription financing structures that collapse capital barriers for independent practices.
Among diversified ophthalmic conglomerates, Johnson & Johnson Vision and Alcon occupy positions spanning excimer and femtosecond modalities with broad portfolio coverage. Carl Zeiss Meditec anchors the premium specialist tier through proprietary platform architectures. These three entities exemplify divergent strategic postures: ecosystem integration versus modular flexibility versus proprietary interface control.
| Leading Market Players |
|---|
| Johnson & Johnson Vision |
| Carl Zeiss Meditec |
| Alcon |
| Bausch & Lomb |
| NIDEK |
| SCHWIND eye-tech-solutions |
| Ziemer Ophthalmic Systems |
| TOPCON |
| Lensar |
| Others |
Supply & Pricing Matrix
Ambulatory surgical centers in the United States and Germany are consolidating procurement authority around subscription-based device access, forcing manufacturers to restructure cost recovery from upfront capital sales toward recurring service bundling and compressing margin realization timelines.
Pricing Analysis
Argon-fluoride gas costs and precision optics sourcing expenses pass through directly to excimer laser platform pricing, while femtosecond systems command premium positioning through solid-state component differentiation. Three-tier pricing structure across premium, standard, and economy levels separates all-laser configurations from mechanical microkeratome bundles and refurbished legacy systems. Pricing pressure stems from surface ablation resurgence in cost-sensitive public hospital systems. Independent ophthalmology practices in India exhibit highest price sensitivity, whereas German academic medical centers prioritize diagnostic integration over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for ultraviolet optics and ultrafast pulse generators compel laser OEMs to qualify secondary suppliers in Germany and Japan alongside primary Jena and Oberkochen photonics clusters. Component manufacturing draws from German precision engineering zones, Japanese domestic optics supply chains supported by METI industrial policy, and emerging Karnataka assembly investments. Single-source vulnerability concentrates in Eastern European argon-fluoride gas precursor production. Distribution runs through authorized device distributors with field service engineering capabilities into ambulatory surgical centers and ophthalmic clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratcheting, with Japan's PMDA software-as-a-medical-device guidance revision elevating compliance investment thresholds and filtering marginal competitors from premium platform segments.
For Market Incumbents: Anticipate stranded asset risk in legacy excimer installed bases as femtosecond conversion accelerates, and preempt through trade-in programs bundling diagnostic workstation upgrades. Defensive consolidation around cataract-refractive ecosystem integration protects recurring revenue streams against modular specialist entrants. Vertical integration into captive ultraviolet optics manufacturing secures supply continuity against Eastern European gas supply friction. For New Entrants and Emerging Players: Tier-2 Indian ophthalmology chains represent the most penetrable buyer archetype, with mobile diagnostic unit deployment creating service-based entry points before capital platform placement. White-space opportunity concentrates in subscription financing structures for independent practices in Texas and Florida surgical clusters. Go-to-market positioning should emphasize device-as-a-service bundling with maintenance and software update inclusion. For Investors and Strategic Acquirers: Asymmetric upside sits with precision photonics component suppliers holding dual qualification status across German and Japanese OEM supply bases. Long-term viability favors entities with regulatory submission capabilities spanning FDA 510(k) predicate leveraging and EU MDR equivalence pathways. Watch for PMDA clearance timeline compression as signal of competitive positioning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Service Model Deployment | Device-as-a-service financing collapses capital barriers for independent ophthalmology practices in Dallas and Miami clusters. |
| Diagnostic-Guided Reimbursement Strategy | Wavefront aberrometry integration secures favorable classification within German national health framework documentation mandates. |
| SMILE Platform Range Expansion | Hyperopia and mixed astigmatism treatment protocols extend addressable patient demographics beyond myopic populations. |
| Dual-Supplier Qualification Program | Secondary sourcing for ultraviolet optics mitigates Jena cluster concentration risk and satisfies ambulatory surgical center procurement policies. |
| AI-Powered Nomogram Optimization | Embedded machine learning modules require standalone PMDA clinical validation under revised software-as-a-medical-device guidance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refractive surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR technical documentation, PMDA approval databases, and hospital procurement records. Bottom-up installed base modeling and top-down expenditure flow analysis triangulated market sizing across laser system, diagnostic device, and consumable categories.
Segment-weighting approaches distributed value estimates across product type, technology modality, application indication, and end-user institution categories, with femtosecond versus excimer platform splits receiving analytical priority. CAGRs derived from procedure volume trajectories, capital replacement cycle compression, and reimbursement framework evolution across the projection horizon. Forecast inputs incorporated wavefront-guided protocol adoption curves and presbyopia-correcting IOL integration rates.
Underlying measurement precision varies by segment; laser system shipments carry tighter precision than diagnostic device estimates due to OEM disclosure granularity. Forecasts reflect documented assumptions regarding regulatory clearance timelines and gas supply continuity. Deviation in PMDA software classification enforcement or Eastern European fluorine precursor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Surgical Smart Glasses Market